
 Massive Wood Slabs Market | 2026-2036
Massive Wood Slabs Market Size, Share, and Industry Trends Forecast 2026-2036
Massive Wood Slabs Market Outlook
Modular slab-to-tabletop bundling is rebalancing buyer choice toward configurable dimension sets rather than single-piece purchases. Timberlab leverages its prefabrication expertise to anchor urban commercial projects requiring certified mass-timber components. Big Wood Slabs competes through direct-to-maker channels that sustain margin control across custom furniture workflows. WRNS Studio differentiates by integrating massive slabs into hybrid structural systems where architectural expression meets carbon-accounting protocols.
Massive wood slabs are cross-sectional timber cuts typically exceeding three inches in thickness, often retaining natural live edges and sourced from single-trunk sections dried to 6-8% moisture content for dimensional stability in finished applications. Plain sawn slabs occupy the volume tier due to efficient yield from standard milling, while live-edge configurations command premium positioning among interior designers seeking biophilic statement pieces. Oak and walnut species dominate species selection, with walnut sustaining higher price realization through scarcity-driven positioning in luxury residential and hospitality environments.
The US EPA oversees formaldehyde emission standards under TSCA Title VI, while the EU Timber Regulation and FSC chain-of-custody certification shape import eligibility and project-specification compliance across commercial construction. These frameworks compel slab suppliers to maintain documented provenance and third-party verification, raising operational barriers for uncertified operators. Stakeholders must monitor evolving building-code equivalency determinations for exposed timber in Type IV construction, as these rulings will determine addressable square footage in multi-story developments.
Market Dynamics
Chain-of-custody mandates from the EU Timber Regulation and EPA formaldehyde standards are compressing supplier margins while rewarding certified operators with preferential access to commercial and hospitality specification channels.
Growth Catalysts
- Biophilic Interior Mandates:Corporate headquarters and luxury hospitality developers specify live-edge slabs for wellness-focused spaces, driving specification pull-through from design firms in Seattle and Portland.
- FSC Chain-of-Custody Certification:Commercial mass-timber projects require documented provenance, locking in demand for suppliers with third-party verification and excluding uncertified competitors from bidding pools.
- Reclaimed Timber Recovery:Deconstruction specialists in the Pacific Northwest are salvaging old-growth inventories from demolished industrial buildings, creating premium supply streams unavailable through conventional harvesting.
Market Restraints
- Moisture Content Control:Kiln-drying thick cross-sections to 6-8% moisture requires 18-24 month cycles, tying up working capital and limiting inventory turnover for independent mills.
- Old-Growth Access Constraints:Sustainable harvesting partnerships control limited Pacific Northwest stands, concentrating premium supply among a handful of mill relationships and creating allocation bottlenecks.
- Engineered Wood Substitution:Cross-laminated timber and glued-laminated beams offer dimensional consistency and fire-rated assemblies, capturing share in structural applications where slabs face code equivalency uncertainty.
Strategic Opportunities
- Modular Configurator Platforms:Digital tools allowing buyers to specify exact dimensions, edge profiles, and finish grades are opening direct-to-maker channels that bypass traditional distributor markups.
- Type IV Construction Code Evolution:Building-code equivalency determinations for exposed heavy timber in multi-story developments could unlock addressable square footage in mid-rise commercial and residential projects.
- Carbon Accounting Integration:Architects pursuing net-zero certifications are specifying slabs with documented embodied-carbon calculations, creating premium positioning for suppliers with lifecycle assessment capabilities.
Industry Challenges
- Specialized Drying Expertise:Fewer than a dozen North American mills possess the controlled-environment kilns and stress-relief protocols required for defect-free drying of 4-inch-plus cross-sections without checking or warping.
- Documentation System Integration:Suppliers must reconcile FSC chain-of-custody records, EPA TSCA Title VI formaldehyde testing, and project-specific carbon accounting into unified traceability platforms that general contractors can audit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massive Wood Slabs Market |
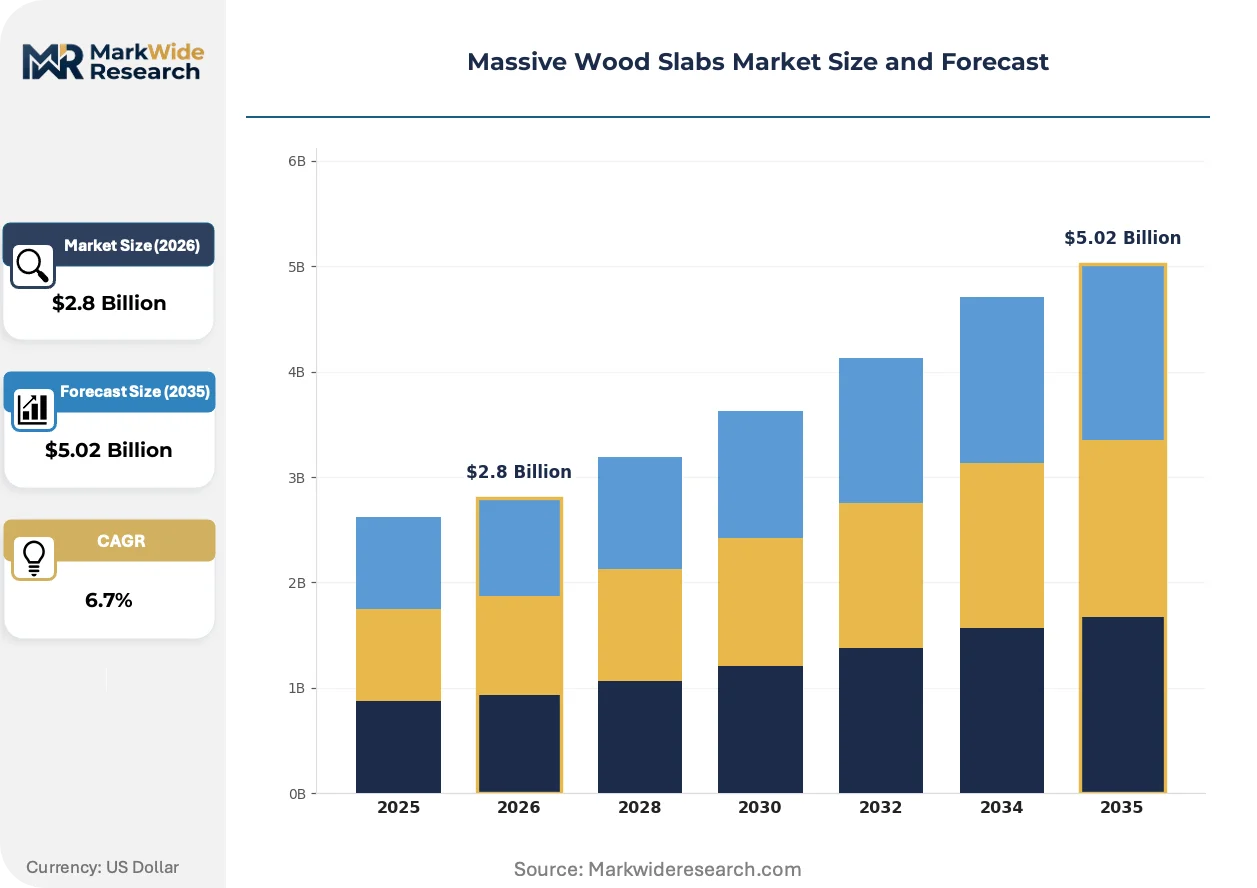
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Edge, Plain Sawn, Quarter Sawn, Slabbed Wood Species: Oak, Walnut, Maple, Cherry End User: Furniture Makers, Interior Designers, Contractors, Hobbyists Surface Treatment: Raw, Sanded, Finished, Sealed |
| Companies Covered | WRNS Studio, Timber Technologies, Timberlab, Michael Green Architecture, Swinerton Builders, Katerra, oWOW!, Big Wood Slabs, FABRIC Mass Timber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massive Wood Slabs Market Strategic Shifts
Specification workflows are digitizing rapidly. Design firms now expect interactive slab selection with real-time inventory visibility, forcing suppliers to reconfigure sales infrastructure around configurators rather than physical yard visits.
Radio-frequency identification tagging paired with blockchain ledgering is decentralizing provenance verification. High-end residential buyers and commercial specifiers now access immutable chain-of-custody records via smartphone scan, compressing due diligence timelines from weeks to minutes and shifting trust mechanisms from paper certificates to cryptographic verification.
EPA enforcement of TSCA Title VI formaldehyde emission standards is intensifying testing protocols for composite-adjacent finishes. Suppliers using catalyzed lacquers and hardwax oils must maintain third-party laboratory documentation, with California Air Resources Board equivalency determinations now serving as de facto national benchmarks for specification eligibility.
Architects and interior designers are consolidating procurement through curated maker networks rather than open-market sourcing. These invitation-only platforms pre-qualify suppliers on certification, capacity, and aesthetic consistency, concentrating volume among vetted participants and marginalizing independent mills without platform relationships, with concentration most visible in San Francisco and New York specification corridors.
Massive Wood Slabs Market Segmentation
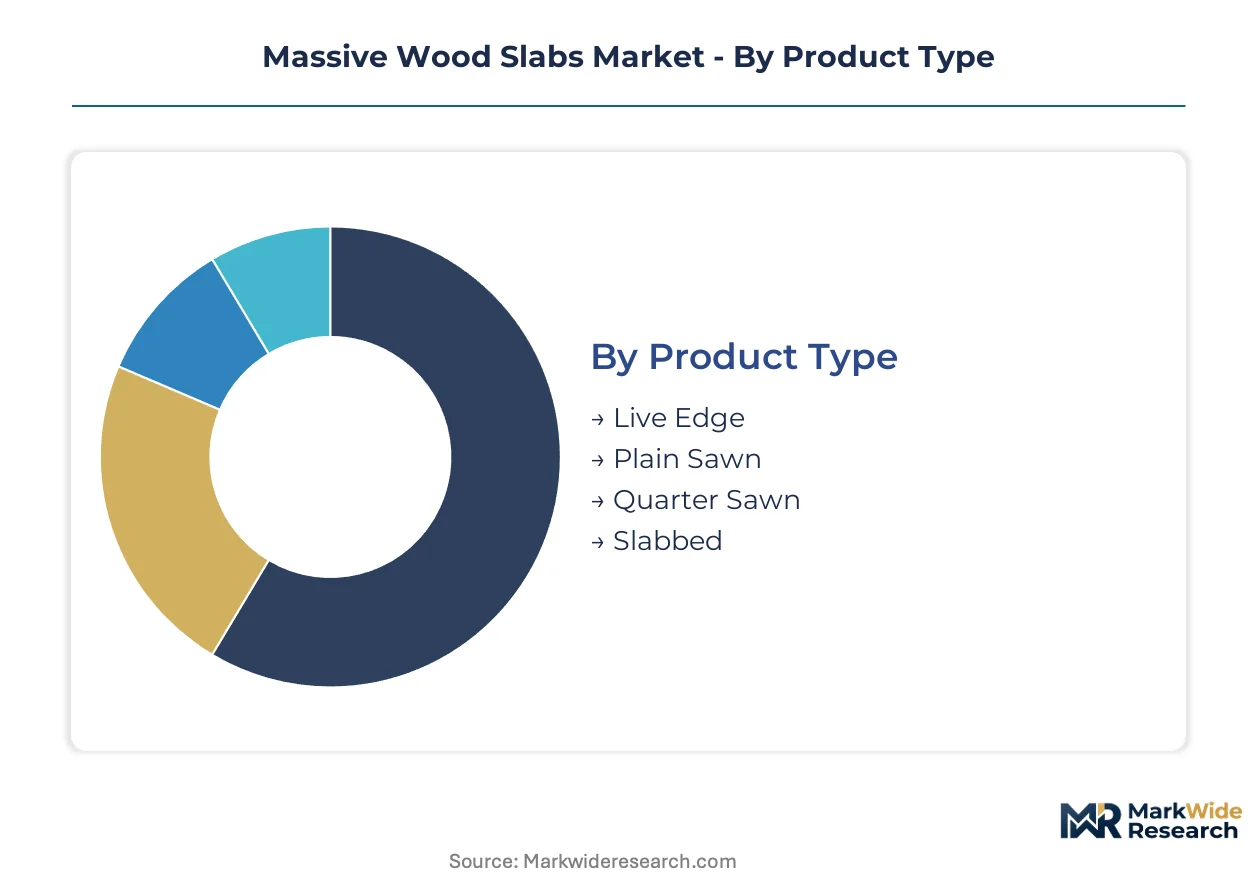
Massive wood slabs demand diverges sharply across buyer sophistication and application requirements. Segmentation reveals where capital deployment, certification burdens, and drying expertise concentrate competitive advantage.
Product Type:
Capital intensity escalates dramatically with edge-retention and drying complexity, separating commodity producers from premium-positioned mills.
- Live Edge:Retains natural bark-line contours requiring hand-stabilization and extended kiln cycles. Demand clusters among Seattle and Portland interior designers executing biophilic corporate headquarters and luxury hospitality suites where wellness mandates drive specification.
- Plain Sawn:Efficient yield from standard milling produces flat-grain surfaces with cathedral patterns. Furniture makers in North Carolina and Pennsylvania absorb volume for production dining and conference tables where cost control dominates procurement.
- Quarter Sawn:Radial cuts expose medullary rays for dimensional stability in climate-variable environments. Premium positioning targets heirloom furniture commissions.
- Slabbed:Single-trunk cross-sections exceeding four feet width require specialized bandsaw infrastructure and stress-relief protocols. Limited Pacific Northwest mill relationships control supply.
Plain Sawn absorbs the bulk of installed capacity; Live Edge is expanding most quickly.
Wood Species:
Scarcity gradients and drying behavior differentiate margin profiles across species selection.
- Walnut:Dark heartwood with chocolate tones commands scarcity-driven positioning. California and New York specification corridors sustain premium realization for statement dining tables and executive desks where aesthetic distinction justifies extended procurement timelines.
- Oak:Abundant supply and favorable drying characteristics anchor volume-tier production. White oak variants penetrate commercial mass-timber projects requiring FSC documentation.
- Maple:Hard rock maple serves high-wear applications; figured varieties target artisan markets.
- Cherry:Oxidative darkening over time creates aging narratives for residential heirloom positioning.
Oak dominates installed milling capacity; Walnut climbs the fastest on price realization metrics.
End User:
Procurement sophistication and certification requirements stratify customer economics.
- Interior Designers:Curated maker networks and platform pre-qualification concentrate specification authority. San Francisco and New York design firms consolidate procurement through invitation-only supplier pools where FSC chain-of-custody and carbon accounting documentation are mandatory entry gates.
- Furniture Makers:Direct-to-maker configurators and modular dimension sets are displacing traditional distributor relationships. Custom workflows sustain margin control through bypassed markups.
- Contractors:Commercial mass-timber projects require documented provenance and EPA TSCA Title VI compliance for specification eligibility.
- Hobbyists:Price-sensitive demand concentrates in raw and sanded surface treatments with minimal documentation requirements.
Furniture Makers represent the deepest volume concentration; Interior Designers are gaining share fastest on specification pull-through.
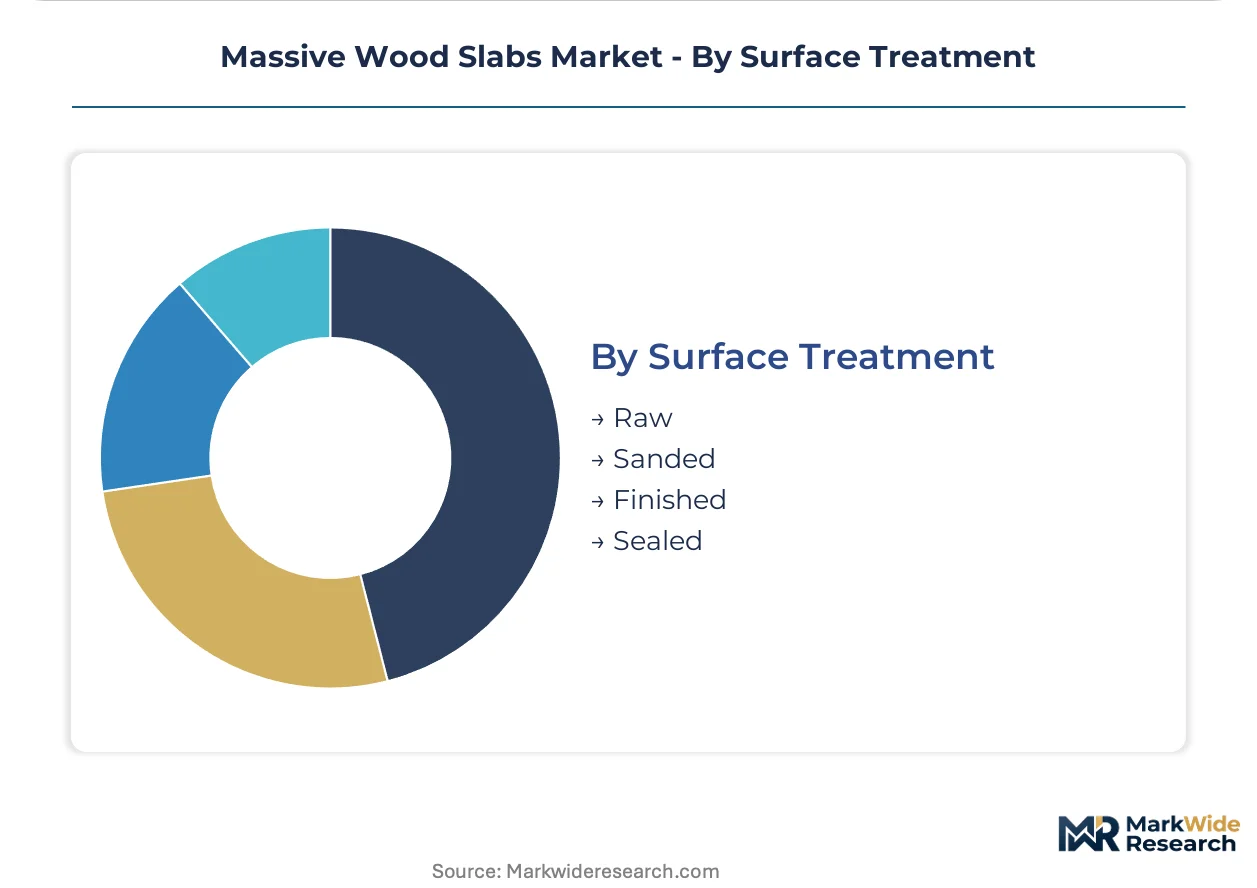
Surface Treatment:
Regulatory exposure and labor intensity determine operational positioning across finishing stages.
- Finished:Catalyzed lacquers and hardwax oils require third-party laboratory documentation under EPA TSCA Title VI and California Air Resources Board equivalency benchmarks. Commercial specifiers mandate this tier for immediate installation readiness.
- Sealed:Penetrating oil treatments balance moisture protection with field-repairability. Hospitality developers favor this tier for operational durability.
- Sanded:Progressive grit progression to 220-grit prepares surfaces for site-applied finishes. Contractors prefer this tier for schedule flexibility.
- Raw:Unprocessed surfaces transfer all finishing liability to downstream buyers. Hobbyists and budget-conscious makers dominate this segment.
Raw and Sanded together absorb the bulk of unit volume; Finished is expanding most quickly on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the Pacific Northwest while consumption disperses across coastal design corridors. The United States generates the largest share of premium old-growth and reclaimed inventory, though specification demand clusters in discrete metropolitan markets with distinct regulatory and aesthetic priorities.
United States
Seattle and Portland interior designers specify live-edge slabs for biophilic corporate headquarters and luxury hospitality suites where wellness mandates drive procurement. EPA TSCA Title VI formaldehyde standards govern finished surface treatments, compelling suppliers to maintain third-party laboratory documentation. The Pacific Northwest sustains sustainable harvesting partnerships that secure premium old-growth and reclaimed inventories for domestic mills.
Germany
Commercial mass-timber projects in Berlin and Munich require documented provenance for specification eligibility, creating demand for FSC chain-of-custody verification. The EU Timber Regulation mandates chain-of-custody documentation for all timber imports, compressing margins for uncertified operators. Bavarian fabricators specialize in quarter-sawn oak for climate-stable heirloom furniture serving Central European residential markets.
Canada
Vancouver and Toronto specification corridors drive demand for carbon-accounting integration in net-zero certified developments. Health Canada and provincial regulators align with EPA-equivalent emission standards for interior finishes, though enforcement varies by province. British Columbia mill relationships control access to limited old-growth stands, creating allocation bottlenecks for premium slabbed cross-sections exceeding four feet width.
United Kingdom
London design firms consolidate procurement through curated maker networks where FSC certification serves as mandatory entry gate. The UK Timber Regulation implements EU-equivalent chain-of-custody requirements post-Brexit, maintaining documentation burdens for imported inventory. Scottish reclaimed timber recovery operations salvage industrial-era old-growth from deconstructed buildings, creating premium supply streams unavailable through conventional harvesting.
Japan
Tokyo and Osaka hospitality developers specify massive slabs for biophilic interiors in luxury ryokan renovations and boutique hotels. METI building codes govern exposed timber in commercial construction, with evolving equivalency determinations for Type IV heavy timber assemblies. Japanese fabricators emphasize traditional drying expertise for thick cross-sections, preserving specialized kiln protocols that minimize checking and warping defects.
Massive Wood Slabs Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and drying capabilities. The vendor base stratifies between mass-timber integrators serving commercial construction and artisan mills targeting custom furniture workflows. Three archetypes dominate: prefabrication specialists with urban project anchoring, direct-to-maker channel operators sustaining margin control, and design-forward studios integrating slabs into hybrid structural systems. Competitive moves concentrate on strategic partnerships with Pacific Northwest mill relationships and modular configurator platform development.
Within the prefabrication archetype, Timberlab occupies a position exemplifying certified mass-timber component supply for urban commercial projects. Among direct-to-maker channel operators, Big Wood Slabs represents margin-preserving distribution bypassing traditional markups. On the design-integration vector, WRNS Studio anchors architectural expression where massive slabs meet carbon-accounting protocols. These three entities collectively illustrate how certification depth, channel strategy, and aesthetic positioning differentiate competitive standing.
| Leading Market Players |
|---|
| WRNS Studio |
| Timber Technologies |
| Timberlab |
| Michael Green Architecture |
| Swinerton Builders |
| Katerra |
| oWOW! |
| Big Wood Slabs |
| FABRIC Mass Timber |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FSC-verified and uncertified inventory creates divergent margin architectures, with premium tiers capturing specification premiums in commercial mass-timber projects while commodity tiers compete on yield efficiency in furniture production. This tier divergence manifests in supply chain configurations where documented provenance commands mill-direct relationships with Pacific Northwest harvesting partnerships, while undocumented flows channel through distributor networks with compressed transparency.
Pricing Analysis
Margin tightening in plain-sawn commodity tiers reflects yield competition from North Carolina and Pennsylvania furniture producers, while live-edge premiums sustain scarcity positioning through limited old-growth allocation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, drying expertise, and edge-retention complexity. Pricing pressure intensifies in raw and sanded surface treatments as hobbyist buyers consolidate through direct-to-maker configurators. Furniture makers exhibit highest price sensitivity due to distributor bypass strategies, while interior designers in San Francisco and New York specification corridors absorb premium realization for documented carbon-accounting integration.
Supply Chain Analysis
Dual-sourcing requirements from commercial mass-timber specifiers mandate Pacific Northwest mill qualification alongside secondary North American suppliers, compressing single-source dependency risk. Geographic supply concentration centers on the United States, Canada, and Germany, with British Columbia and Bavarian fabricators anchoring premium quarter-sawn and slabbed cross-section capacity. Raw material dependencies rest on old-growth stand access, specialized bandsaw infrastructure, and controlled-environment kiln technology. Single-source vulnerability concentrates in Pacific Northwest sustainable harvesting partnerships controlling limited inventory. Distribution runs through curated maker networks and direct-to-maker configurators displacing traditional lumber yard intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chain-of-custody documentation burdens and extended drying capital requirements are forcing consolidation among independent mills without certification infrastructure or Pacific Northwest mill relationships.
For Market Incumbents: Lock in exclusive sustainable harvesting partnerships with Pacific Northwest old-growth suppliers before allocation bottlenecks intensify, and deepen backward integration into controlled-environment kiln infrastructure to capture drying expertise scarcity. Engineered wood substitution in structural applications and CLT code equivalency advances threaten slab specification share, making FSC chain-of-custody certification investment the critical defensive lever for commercial project eligibility. For New Entrants and Emerging Players: Begin with modular configurator platform development targeting furniture maker direct channels, where distributor bypass sustains margin control and documentation requirements remain minimal. White-space concentration sits in carbon-accounting integration services for architects pursuing net-zero certifications, with hospitality developers in Tokyo and Vancouver representing the most penetrable specification corridor. A go-to-market angle anchored in blockchain-ledgered provenance verification addresses due-diligence compression demand from high-end residential buyers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists possessing captive Pacific Northwest mill relationships and FSC certification depth, given Type IV construction code evolution unlocking mid-rise commercial addressable square footage. Long-term viability over a decade horizon favors acquisition targets with stress-relief drying protocols and unified traceability platforms reconciling EPA TSCA Title VI, FSC chain-of-custody, and project-specific carbon accounting. The signal to watch is building-code equivalency determinations for exposed heavy timber in multi-story developments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kiln Infrastructure | Captures specialized drying expertise scarcity concentrated among fewer than a dozen North American mills. |
| Blockchain-Ledgered Provenance Verification | Compresses due-diligence timelines from weeks to minutes for FSC chain-of-custody documentation. |
| Modular Configurator Platform Launch | Opens direct-to-maker channels that bypass traditional distributor markups in furniture workflows. |
| Carbon-Accounting Integration Service | Addresses architect demand for documented embodied-carbon calculations in net-zero certifications. |
| Sustainable Harvesting Partnership Expansion | Secures premium old-growth and reclaimed inventory allocation ahead of Pacific Northwest supply bottlenecks. |
Study Parameters
Multi-period observation of kiln-capacity utilization, FSC certification penetration, and specification workflow digitization anchored the trend analysis, supplemented by interviews with sawmill operations directors, interior design firm procurement leads, commercial mass-timber project developers, furniture maker owners, and deconstruction salvage specialists. Secondary validation drew from EPA TSCA Title VI enforcement disclosures, EU Timber Regulation implementation reports, FSC chain-of-custody database extracts, and building-code equivalency determination filings. Bottom-up demand modeling across end-user segments triangulated against top-down supply-side capacity assessments.
Segment-weighting approaches distributed value and volume projections across product type, wood species, end-user sophistication, and surface treatment tier, with additional dimensional layering by regional specification corridor and certification compliance level. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking specification pipeline visibility. Industry-specific forecast inputs incorporated kiln-drying cycle duration constraints and evolving Type IV construction code adoption timelines.
Underlying measurement precision varies by segment; live-edge and quarter-sawn categories carry tighter precision than plain-sawn commodity tiers due to concentrated supplier bases and documented transaction flows. Forecasts reflect assumptions around chain-of-custody documentation adoption rates and commercial mass-timber project growth trajectories. Deviation in EPA TSCA Title VI enforcement intensity or EU Timber Regulation import screening protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Home Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
UAE Luxury Furniture Market
Furniture
Portering Chair Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Metal Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
Chair Hardware Market
Furniture
Poland Home Furniture Market
Furniture
Kids Furniture Market
Furniture
Russia Home Furniture Market
Furniture
US Sustainable Furniture Market