
 Canada Secondary Wood Products Market | 2026-2036
Canada Secondary Wood Products Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Secondary Wood Products Market Intelligence
Ontario's cross-laminated timber capacity build-out is rewriting procurement patterns for secondary wood products across Eastern Canada. Weyerhaeuser Company leverages its Pacific Northwest fiber position to supply Canadian manufacturers with consistent veneer feedstock. West Fraser Timber anchors British Columbia's engineered wood panel output through integrated softwood operations. Canfor competes aggressively on laminated strand lumber, extending its reach into Quebec's commercial construction corridor.
Canada secondary wood products encompass engineered and remanufactured items derived from primary lumber processing, including panels with specific density ratings between 500-800 kg/m³ and precision-milled components for structural and aesthetic applications. These products serve residential framing, commercial interiors, and industrial packaging through standardized dimensional stability and moisture-resistant bonding protocols. Flooring and millwork command durable margin pools, as custom architectural specifications resist commoditization pressures. Construction applications lead volume throughput, while furniture manufacturing differentiates on species-grade sourcing from certified Canadian forests.
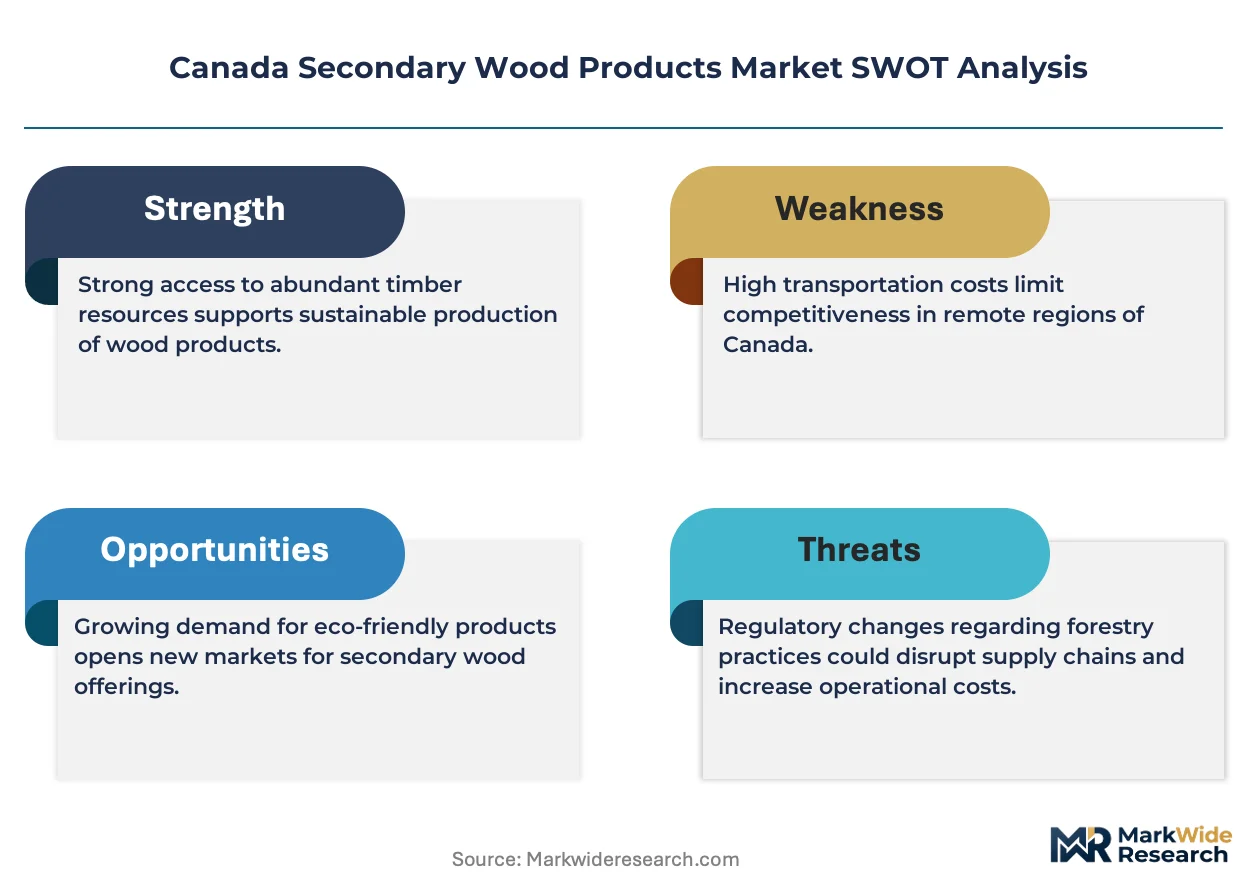
Health Canada and the Canadian Standards Association govern formaldehyde emission thresholds under composite wood product regulations, directly shaping which panel formulations gain market access. The Canadian Wood Council and provincial building codes in Ontario and British Columbia determine structural acceptance criteria for engineered products in mid-rise and tall wood buildings. Stakeholders must monitor evolving code harmonization between provinces and federal procurement preferences for low-carbon structural materials.
Market Dynamics
Mass timber code expansion in Ontario and British Columbia is compressing traditional steel and concrete specification cycles, forcing secondary wood product manufacturers to retool for engineered panel certification at unprecedented speed.
Growth Catalysts
- Toronto high-rise residential towers:Developers are specifying cross-laminated timber floor plates as standard, creating pull-through demand for compatible secondary structural components.
- Health Canada PMRA formaldehyde emission protocols:Tightening thresholds are filtering out non-compliant imports, clearing shelf space for domestic panel producers meeting CSA certification.
- Quebec commercial construction corridor:Laminated strand lumber is penetrating office and institutional builds as architects specify exposed structural wood aesthetics.
Market Restraints
- Softwood veneer feedstock volatility:Pacific Northwest fiber supply disruptions transmit directly to Canadian engineered panel margins through Weyerhaeuser's pricing power.
- Interprovincial code harmonization friction:Ontario and British Columbia maintain divergent structural acceptance criteria for mid-rise timber, fragmenting product certification requirements.
- Steel-frame substitution in seismic zones:Vancouver's earthquake engineering standards still favor reinforced concrete cores, capping mass timber penetration in critical load-bearing applications.
Strategic Opportunities
- Atlantic Canada underpenetration:Nova Scotia and New Brunswick lack mass timber manufacturing infrastructure, creating first-mover advantage for panel producers establishing regional distribution.
- Federal procurement preferences for low-carbon structural materials:Ottawa's green building mandates for government facilities are tilting specification toward certified wood products with verified carbon accounting.
- Digital fabrication convergence:CNC milling paired with BIM modeling is enabling custom architectural millwork at production-scale economics, opening premium interior specification.
Industry Challenges
- Mass timber engineering talent scarcity:Canadian universities produce fewer structural timber specialists than code expansion requires, extending project timelines and consulting costs.
- CSA certification backlog:New panel formulations face extended testing queues at accredited labs, delaying product launches by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Secondary Wood Products Market |
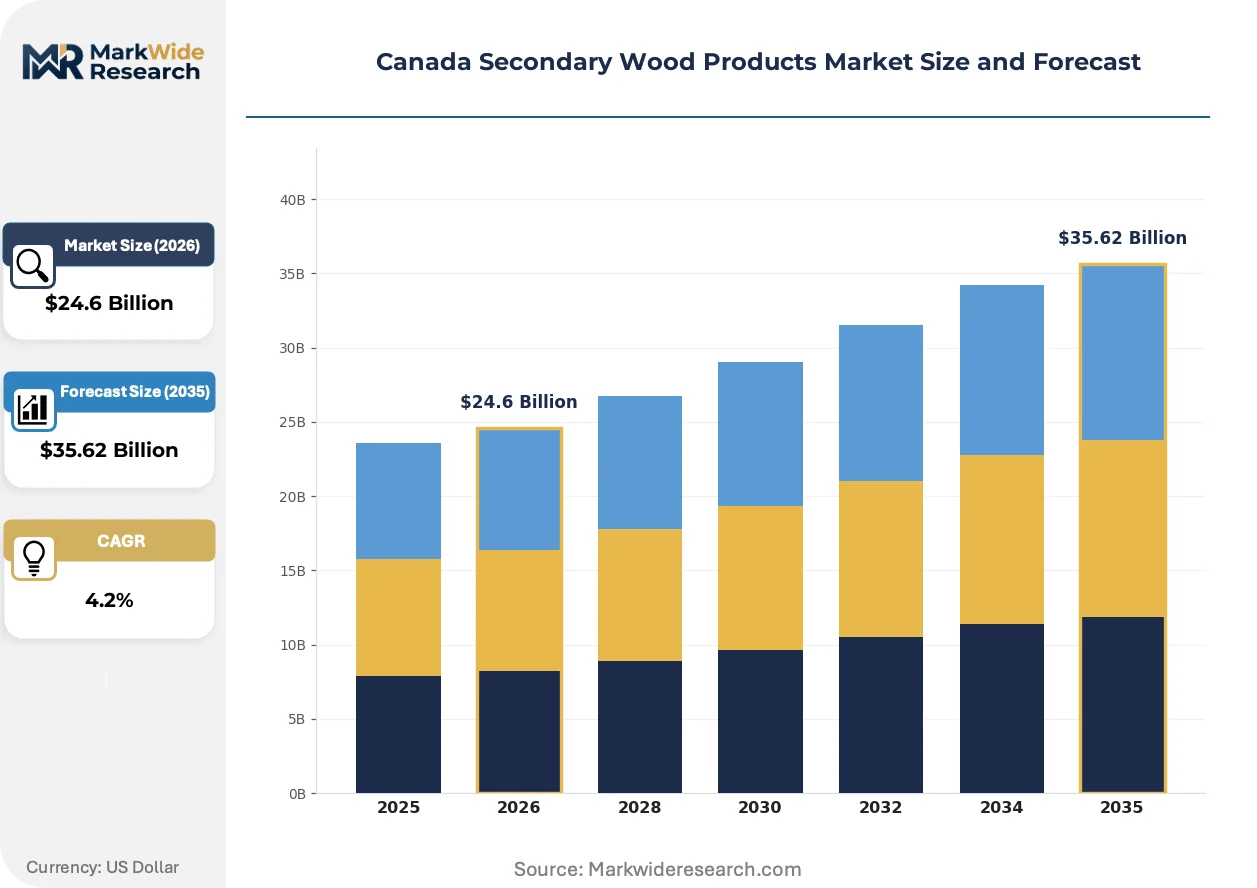
| Market Size in 2026 | $24.6 Billion |
| Market Size in 2035 | $35.62 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Panels, Furniture Components, Flooring, Millwork End User: Residential, Commercial, Industrial, Institutional Application: Construction, Furniture Manufacturing, Interior Design, Renovation Material Type: Plywood, Oriented Strand Board, Medium Density Fiberboard, Laminated Veneer Lumber |
| Companies Covered | BG Furniture, Weyerhaeuser Company, G. Romano, Canfor, West Fraser Timber, Amisco Industries, Herman Miller, Stella-Jones, BSG Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Secondary Wood Products Market Strategic Shifts & Innovations
Digital specification tools and automated fabrication are compressing design-to-installation timelines for engineered wood systems, while regulatory code expansion rewrites what structural roles timber can assume.
Cross-laminated timber manufacturing is hybridizing with robotic layup and adhesive monitoring systems to achieve consistent density ratings between 500-800 kg/m³. Toronto's tower developers are specifying these panels for floor plates above six stories, accelerating adoption beyond traditional low-rise limits. The technology is hybridizing procurement patterns as general contractors source complete timber structural packages rather than discrete commodity panels.
Health Canada's PMRA guidelines on formaldehyde emissions are tightening product standards nationwide, directly shaping which panel formulations gain market access. Manufacturers must reformulate bonding protocols to meet descending thresholds, raising R&D expenditure for domestic producers. Quebec and Ontario panel plants are responding fastest, leveraging proximity to CSA certification labs and provincial building code authorities.
Architects are bundling structural and aesthetic specification into single-source timber packages, collapsing the traditional separation between engineering and interior design. This consolidation is disintermediating commodity distributors who lack BIM-integrated fabrication capabilities. British Columbia's commercial tower segment shows this most visibly, where exposed mass timber cores now drive millwork and panel sourcing from unified supplier relationships.
Canada Secondary Wood Products Market Segmentation
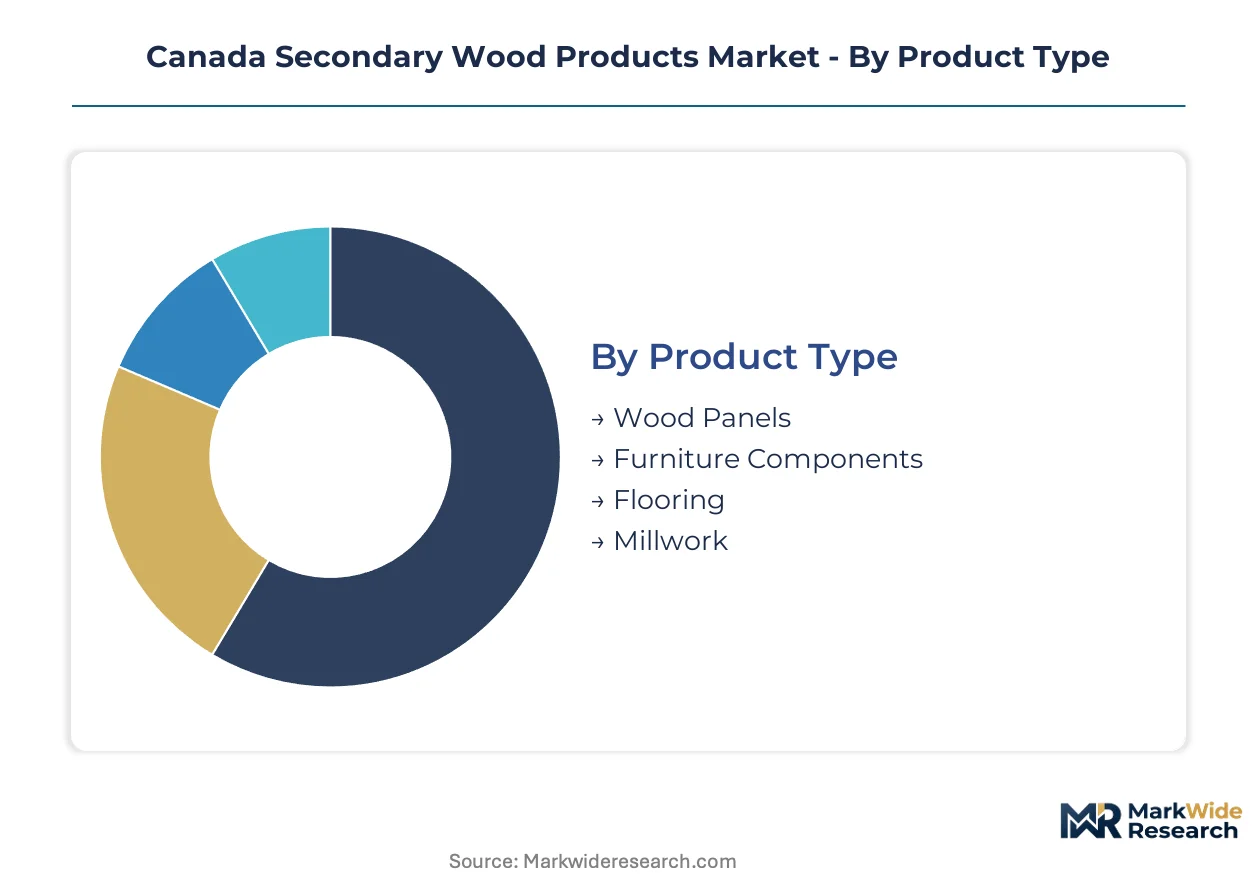
Canada's secondary wood products market fragments across four critical dimensions: product form, end-user vertical, application workflow, and engineered material substrate. Each segmentation layer reveals distinct margin structures, certification requirements, and procurement channel preferences that reshape competitive positioning.
Product Type:
Cost tier separates commodity panels from value-added millwork and custom architectural components.
- Wood Panels:Engineered sheet goods with density ratings between 500-800 kg/m³ serve structural sheathing and concrete forming. Toronto high-rise residential towers specify cross-laminated timber floor plates, compressing procurement cycles for compatible panel systems.
- Furniture Components:Precision-milled hardwood and softwood elements for seating frames, cabinet boxes, and table bases. Quebec's commercial furniture manufacturers source certified Canadian forest species to meet exposed-wood aesthetic specifications in office and hospitality builds.
- Flooring:Solid and engineered plank systems with moisture-resistant bonding protocols. Ontario and British Columbia residential construction absorbs premium-grade oak and maple flooring through distributor networks serving renovation contractors.
- Millwork:Custom architectural trim, molding, and built-in cabinetry. Digital fabrication convergence enables CNC-milled components at production-scale economics, opening specification in Toronto's luxury residential segment.
Wood panels hold installed capacity. Millwork is rotating up the share rankings.
End User:
Application context determines specification authority: architects control commercial and institutional flows, while contractors drive residential and industrial procurement.
- Residential:Single-family and multi-family builders consume engineered panels for framing and sheathing. British Columbia's mass timber code expansion accelerates cross-laminated timber adoption in mid-rise wood buildings.
- Commercial:Office, retail, and hospitality developers specify exposed structural wood aesthetics. Quebec's commercial construction corridor penetrates laminated strand lumber into institutional builds seeking biophilic design credentials.
- Industrial:Packaging, crating, and material handling applications favor commodity-grade oriented strand board. Health Canada PMRA formaldehyde protocols filter non-compliant imports, clearing shelf space for domestic panel producers.
- Institutional:Schools, healthcare facilities, and government buildings face federal procurement preferences for low-carbon structural materials. Ottawa's green building mandates tilt specification toward certified wood products with verified carbon accounting.
Residential anchors volume throughput. Commercial is climbing the fastest as architects bundle structural and aesthetic specification.
Application:
Volume concentration tracks construction cycles, while margin pools concentrate in design-forward verticals resistant to commoditization.
- Construction:Structural framing, concrete forming, and exterior sheathing dominate tonnage. Ontario and British Columbia building codes determine acceptance criteria for engineered products in mid-rise and tall wood buildings.
- Furniture Manufacturing:Case goods, seating, and fixture production differentiate on species-grade sourcing from certified Canadian forests. Custom architectural specifications resist price compression through design exclusivity.
- Interior Design:Architectural millwork, decorative paneling, and feature wall systems. Toronto's tower developers are collapsing traditional separations between engineering and interior design into single-source timber packages.
- Renovation:Replacement flooring, trim upgrades, and kitchen refacing. Atlantic Canada underpenetration in mass timber infrastructure creates distribution opportunities for panel producers establishing regional reach.
Construction commands the steepest expansion trajectory. Interior design is gaining share fastest as BIM-integrated fabrication consolidates procurement.
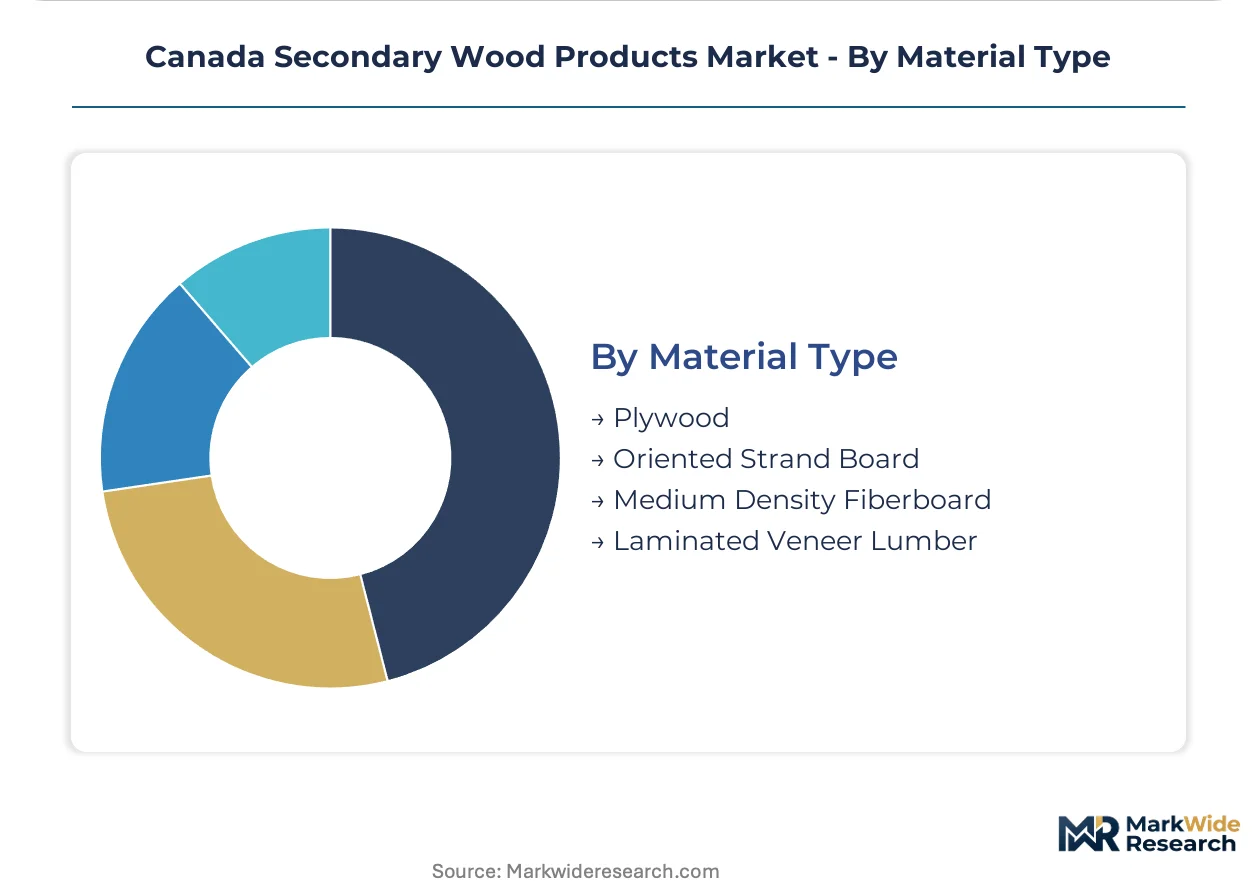
Material Type:
Supply concentration clusters around British Columbia's integrated softwood operations and Ontario's proximity to CSA certification infrastructure.
- Plywood:Cross-banded veneer construction with exterior-grade adhesive systems. Pacific Northwest fiber supply disruptions transmit directly to Canadian engineered panel margins through veneer feedstock volatility.
- Oriented Strand Board:Flake-based panel with controlled density and dimensional stability. West Fraser Timber anchors British Columbia's output through captive strand production from integrated softwood operations.
- Medium Density Fiberboard:Refined wood fiber mat with uniform surface quality for lamination and painting. Health Canada PMRA formaldehyde emission thresholds force bonding protocol reformulation, raising R&D expenditure for domestic producers.
- Laminated Veneer Lumber:Parallel-laminated veneer structural members for beams and headers. Canfor competes aggressively on this substrate, extending reach into Quebec's commercial construction corridor.
Oriented strand board holds installed capacity. Laminated veneer lumber is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada and provincial building code authorities in Ontario and British Columbia anchor regulatory momentum for engineered wood products. Provincial standards divergence creates compliance complexity for manufacturers operating across multiple jurisdictions.
Ontario
Toronto's high-rise residential tower segment specifies cross-laminated timber floor plates as standard, pulling demand for compatible secondary structural components. The Ontario Building Code's mass timber provisions exceed federal baselines, requiring additional engineering review for mid-rise applications. Manufacturing clusters concentrate in the Greater Toronto Area, where panel producers maintain proximity to CSA certification labs and major project sites.
British Columbia
Vancouver's commercial tower segment drives exposed mass timber core specifications, collapsing traditional separations between structural engineering and interior design. The province maintains divergent seismic engineering standards from Ontario, capping timber penetration in critical load-bearing applications. West Fraser Timber anchors integrated softwood operations in the region, supplying captive strand production for engineered panel output.
Quebec
Montreal's commercial construction corridor penetrates laminated strand lumber into office and institutional builds seeking biophilic design credentials. The province's building code harmonization efforts with Ontario remain incomplete, fragmenting product certification requirements for interprovincial suppliers. Manufacturing activity clusters in the Montreal-Quebec City corridor, where furniture component producers source certified Canadian forest species.
Alberta
Calgary's institutional construction segment shows rising specification for low-carbon structural materials in government and educational facilities. Federal procurement preferences for verified carbon accounting tilt specification toward certified wood products. Regional distribution infrastructure remains underdeveloped relative to Ontario and British Columbia, creating logistics challenges for eastern panel producers.
Atlantic Canada
Halifax and Moncton lack mass timber manufacturing infrastructure, creating first-mover advantage for panel producers establishing regional distribution networks. Provincial building codes in Nova Scotia and New Brunswick lag Ontario and British Columbia adoption curves for tall wood provisions. Secondary wood product demand concentrates in renovation applications, with replacement flooring and trim upgrades dominating local consumption.
Canada Secondary Wood Products Market Key Industry Players
Integrated forest products conglomerates and specialized engineered wood manufacturers split the market along capital intensity and vertical control vectors. Concentration clusters around British Columbia's fiber-rich hinterland and Ontario's proximity to major metropolitan demand centers. Three archetypes dominate: captive fiber-integrated producers, independent panel specialists, and precision millwork fabricators. Competitive moves center on CSA certification speed and mass timber engineering talent acquisition.
Among North American forest products conglomerates, Weyerhaeuser Company and West Fraser Timber exemplify the fiber-integrated archetype, leveraging Pacific Northwest and Canadian interior fiber positions respectively. Canfor occupies a position within the engineered structural products tier, competing on laminated strand lumber penetration. These entities anchor supply security for secondary manufacturers downstream.
| Leading Market Players |
|---|
| BG Furniture |
| Weyerhaeuser Company |
| G. Romano |
| Canfor |
| West Fraser Timber |
| Amisco Industries |
| Herman Miller |
| Stella-Jones |
| BSG Inc. |
| Others |
Cost & Logistics Intelligence
The Trans-Canada Highway corridor's freight cost dynamics amplify supply concentration effects in British Columbia and Ontario, compressing margins for Atlantic Canada distributors while enabling price premiums for CSA-certified panels in Toronto's tower segment.
Pricing Analysis
Ontario-British Columbia price spreads reflect the divergence between mass timber code adoption curves and certification infrastructure proximity. Three-tier pricing structure across premium, standard, and economy levels separates CSA-certified cross-laminated timber from commodity OSB and imported panels. Pricing pressure stems from Pacific Northwest veneer feedstock volatility transmitting through Weyerhaeuser's contract structures. Residential contractors show highest price sensitivity, while institutional buyers with federal green procurement mandates absorb premium tiers.
Supply Chain Analysis
Extended payment terms from British Columbia's integrated softwood operators strain working capital for independent Quebec panel specialists competing on laminated strand lumber. Supply concentrates in Canada and the United States, with Pacific Northwest fiber anchoring veneer flows and Ontario housing demand pulling engineered panels eastward. Raw material dependencies center on softwood veneer, structural adhesives, and formaldehyde-scavenging agents. Single-source vulnerability runs through Weyerhaeuser's Pacific Northwest fiber position. Distribution runs through regional building material distributors with CSA certification screening capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel-frame and concrete substitution in seismic engineering applications forces incumbents to defend specification share through code advocacy and performance demonstration.
For Market Incumbents: Build certification speed as a moat by securing priority CSA lab relationships and pre-approving panel formulations for Ontario and British Columbia code variations. Anchor supply security through backward integration into Pacific Northwest fiber or long-term offtake agreements with Weyerhaeuser. Counter steel-frame substitution in Vancouver's seismic zones by funding university research on mass timber earthquake performance. For New Entrants and Emerging Players: Pursue Atlantic Canada distribution infrastructure gaps, where Nova Scotia and New Brunswick lack mass timber manufacturing presence and provincial codes lag adoption curves. Target federal procurement channels in Ottawa and Calgary institutional builds, where green building mandates create specification pull for verified carbon accounting. Enter through BIM-integrated fabrication partnerships that collapse structural and interior design procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors panel producers with captive fiber supply and CSA certification infrastructure over pure-play distributors. Five-to-ten year viability hinges on code expansion sustaining mass timber penetration beyond current height limits. Watch for Health Canada PMRA threshold tightening as inflection signal favoring domestic reformulation capabilities over import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Fast-Track Investment | Priority lab access compresses product launch timelines against competitors facing extended testing queues. |
| Pacific Northwest Fiber Supply Agreement | Long-term veneer offtake hedges against Weyerhaeuser pricing power transmission to panel margins. |
| BIM-Integrated Fabrication Capability | CNC milling paired with digital specification tools opens premium Toronto luxury residential millwork. |
| Atlantic Canada Distribution Buildout | First-mover regional infrastructure captures Halifax and Moncton renovation and institutional demand. |
| Mass Timber Engineering Talent Pipeline | University partnership programs address specialist scarcity extending project timelines and consulting costs. |
Research Approach
A spread of perspectives from mass timber engineering consultants, CSA certification lab directors, Ontario and British Columbia building code officials, and Toronto tower development procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Health Canada PMRA filings, provincial building code amendment records, and Canadian Wood Council technical bulletins. Bottom-up demand modeling from construction permit data triangulated against top-down supply capacity assessments across British Columbia, Ontario, and Quebec panel manufacturing facilities.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework, with segmentation modeling across product form, end-user vertical, application workflow, and engineered material substrate. CAGRs derived from construction cycle correlations, code adoption elasticity estimates, and feedstock cost pass-through coefficients. Industry-specific inputs included cross-laminated timber height limit expansion scenarios and formaldehyde emission threshold compliance cost curves.
Sensitivities concentrate around Pacific Northwest fiber supply disruption severity, interprovincial code harmonization progress, and Health Canada PMRA threshold descent pace. Forecasts reflect documented assumptions on mass timber engineering talent pipeline development and federal procurement mandate enforcement intensity. Macroeconomic construction cycle downturn, regulatory reversal on tall wood provisions, or breakthrough in competing low-carbon structural materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America Slide Rails Market
Furniture
Metal Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
Back Mount Frames Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
North America High-End Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Indonesia Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Salon Chairs Market
Furniture
Italy Office Furniture Market
Furniture
Canada Home Furniture Market
Furniture
France Furniture Market
Furniture
United Kingdom Kitchen Furniture Market