
 Europe Sustainable Home Furniture Market | 2026-2036
Europe Sustainable Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Home Furniture Market Foresight
Multi-source material procurement is rebalancing toward regional certified timber networks across the Europe Sustainable Home Furniture Market. IKEA Group anchors its competitive stance through captive forestry partnerships in Romania and Poland that secure FSC-certified supply chains. Vitra International AG differentiates via its in-house materials research laboratory in Weil am Rhein, where engineers test bio-based adhesives and low-VOC finishes. Grüne Erde specializes in artisanal production cooperatives across Austria and Germany, leveraging localized craft networks that reduce transport emissions per unit.
Europe sustainable home furniture encompasses residential furnishings manufactured with certified renewable or recycled inputs, low-emission finishes, and end-of-life recyclability protocols meeting EU ecodesign criteria. Primary applications span living spaces, dining areas, bedrooms, and home offices where indoor air quality standards and circular material passports govern specification decisions. Sofas and chairs command the deepest margin pools due to upholstery complexity and consumer willingness to pay for certified organic textiles and natural latex cushioning. Online retail channels represent the fastest-growing distribution vector, though showrooms retain decisive influence among interior designers specifying projects for LEED and BREEAM-certified residential buildings.
REACH chemical restrictions, the EU Green Deal circular economy action plan, and national eco-label schemes including the German Blue Angel and Nordic Swan Ecolabel collectively raise compliance barriers for imported non-certified products while privileging domestic verified manufacturers. ECHA substance restrictions on formaldehyde emissions and flame retardants are accelerating reformulation investments among foam and textile suppliers serving furniture producers. Stakeholders must monitor evolving ecodesign delegated acts for furniture, as upcoming repairability scoring and recycled content mandates will reshape product development priorities and supplier qualification criteria across the value chain.
Market Dynamics
The EU Green Deal's circular economy action plan is forcing furniture manufacturers to reconfigure supply chains around recycled content thresholds and extended producer responsibility mandates before delegated acts take full effect.
Growth Catalysts
- REACH chemical restrictions:ECHA substance limits on formaldehyde and flame retardants are accelerating reformulation investments among foam and textile suppliers, creating first-mover advantages for compliant domestic producers.
- BREEAM certification schemes:Building assessment protocols in Germany and Scandinavia reward sustainable interior specifications, channeling specification decisions toward verified low-emission furnishings.
- Urban apartment densification:Berlin and Amsterdam dwellers are driving demand for modular, space-efficient pieces that carry certified material passports and end-of-life recyclability protocols.
Market Restraints
- Certified timber supply concentration:FSC-certified hardwood networks concentrate in Romania and Poland, exposing manufacturers to regional harvest volatility and transport emission accounting complexities.
- Organic textile input costs:Certified organic cotton and natural latex cushioning command premiums that compress margins on mid-market sofa and chair lines.
- Repairability scoring delays:Pending ecodesign delegated acts create planning uncertainty as manufacturers await final repairability metrics and recycled content percentage floors.
Strategic Opportunities
- Online retail channel expansion:Digital direct-to-consumer platforms represent underexploited vectors for certified sustainable furnishings, particularly among millennial first-time buyers in secondary Scandinavian cities.
- Material passport standardization:Digital product passports mandated under EU Green Deal frameworks enable subscription and take-back service models that extend customer lifetime value.
- Austrian artisanal craft networks:Localized production cooperatives reduce per-unit transport emissions while commanding premium positioning among design-conscious consumers.
Industry Challenges
- Bio-based adhesive R&D timelines:Vitra International AG's materials laboratory exemplifies the capital intensity required to validate low-VOC finishes at production scale.
- Cross-border compliance fragmentation:German Blue Angel and Nordic Swan Ecolabel maintain divergent testing protocols, multiplying certification costs for pan-European product lines.
- Legacy foam supplier qualification:Reformulating flame-retardant-free cushioning requires requalifying entire supplier bases against ECHA substance restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Home Furniture Market |
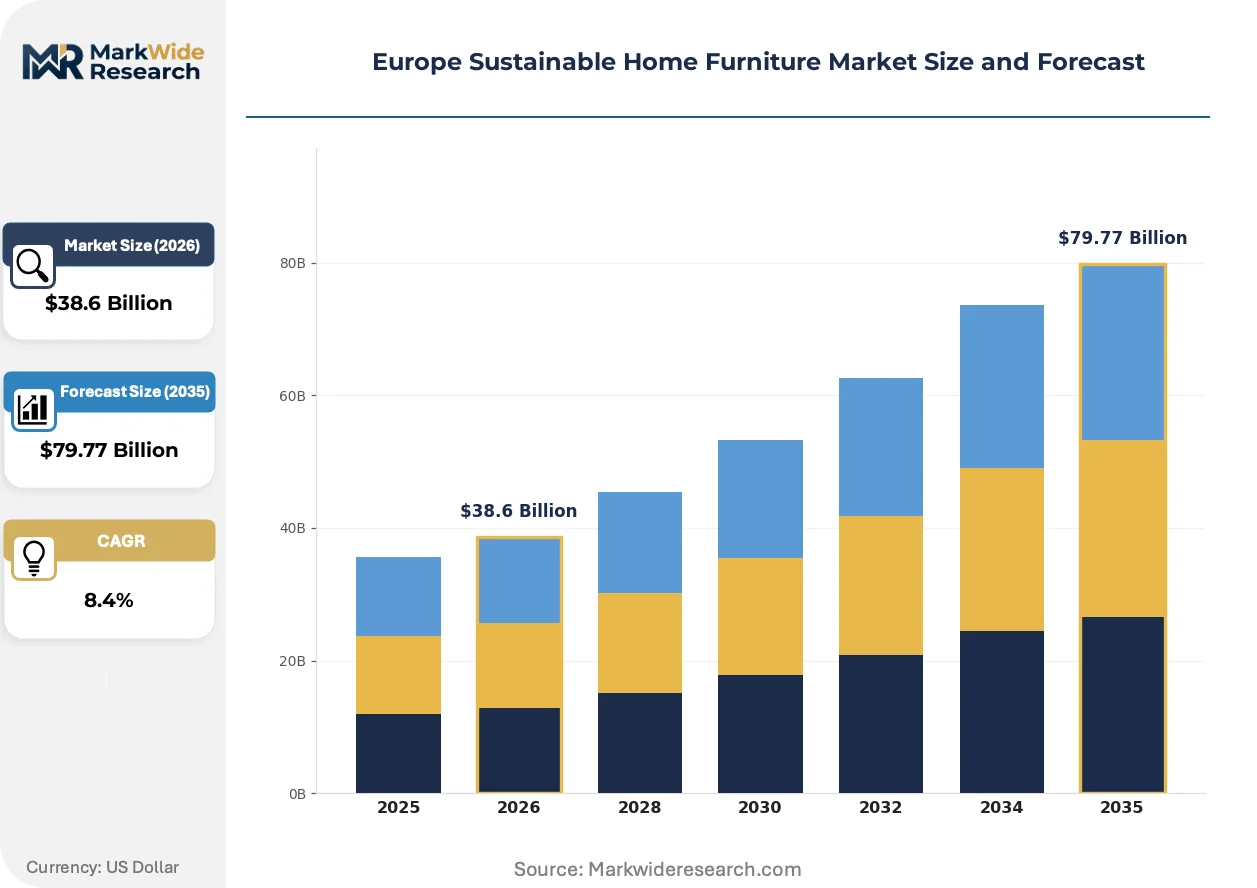
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Sofas, Shelves Material: Bamboo, Recycled Wood, Cork, Bioplastics Distribution Channel: Online Retail, Showrooms, Direct Sales, Marketplaces Consumer Segment: Eco-conscious Consumers, Interior Designers, Bulk Buyers, Wholesalers |
| Companies Covered | IKEA Group, Vitra International AG, Herman Miller Inc., Steelcase Inc., Knoll, Haworth Inc., Grüne Erde, Mater, Bolia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Home Furniture Market Shifts & Advancements
Digital product passports and decentralized material tracking systems are compressing information asymmetries between manufacturers and specification buyers across European residential construction.
Blockchain-enabled material provenance verification is decentralizing supply chain transparency. Interior designers specifying for LEED and BREEAM-certified residential buildings are adopting these tools at accelerating rates. The technology is decentralizing procurement authority from centralized purchasing departments to project-level specification consultants who demand batch-level certification data.
The EU Green Deal's upcoming ecodesign delegated acts for furniture will mandate repairability scoring and recycled content thresholds. Manufacturers are pre-positioning modular frame designs and standardized component interfaces to meet anticipated scoring criteria. Sofa and upholstery segments face the steepest compliance ramps due to multi-material construction complexity.
Certification-driven specification preferences are fragmenting traditional wholesale relationships. Architects and interior designers in Copenhagen and Hamburg are bypassing distributors to contract directly with verified manufacturers carrying German Blue Angel or Nordic Swan Ecolabel credentials. This behavioral shift concentrates margin capture with certified producers while compressing intermediary roles in high-specification residential projects.
Europe Sustainable Home Furniture Market Segmentation
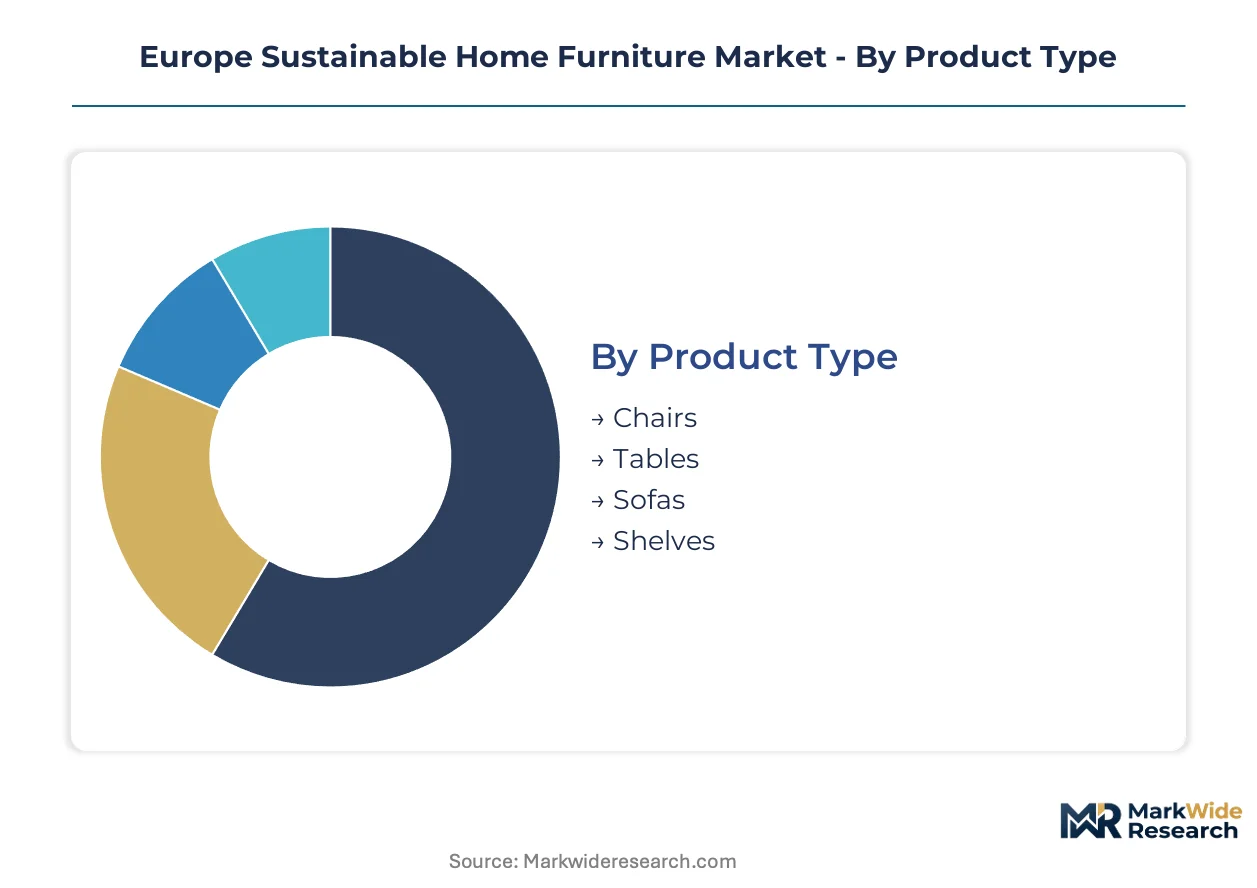
Segmentation in the Europe Sustainable Home Furniture Market reveals how certification requirements, distribution economics, and specification authority fragment across product categories and buyer types. Understanding these splits enables manufacturers to align material investments with channels where margin capture is strongest.
Product Type:
Sofas and chairs concentrate the deepest margin pools due to upholstery complexity and certified textile premiums, while tables and shelves compete more intensely on material cost efficiency.
- Sofas:Multi-material construction combining FSC-certified hardwood frames with natural latex cushioning and organic textile covers. Demand concentrates among Berlin and Amsterdam apartment dwellers seeking modular, space-efficient configurations with end-of-life recyclability protocols under EU Green Deal circular economy requirements.
- Chairs:Upholstered dining and accent chairs command premium positioning through low-VOC finishes and bio-based adhesives validated at production scale. Copenhagen and Hamburg interior designers are bypassing distributors to contract directly with German Blue Angel-certified manufacturers for BREEAM-certified residential projects.
- Tables:Dining and workspace surfaces emphasizing regional certified timber networks and recycled wood inputs.
- Shelves:Modular storage systems optimized for urban densification and material passport compatibility.
Mature deployment sits with Tables. Newer deployment is concentrated in Sofas.
Material:
Certified renewable inputs face supply concentration in Romania and Poland, while bio-based alternatives require capital-intensive R&D validation before production scale-up.
- Recycled Wood:Post-industrial and post-consumer timber streams reprocessed under EU ecodesign criteria for end-of-life recyclability. German and Scandinavian building certification schemes reward specifications carrying material passports, channeling procurement toward verified suppliers with batch-level certification data.
- Bamboo:Rapid-renewable grass species processed into dimensionally stable panels for furniture frames and surface applications. REACH chemical restrictions on formaldehyde emissions are accelerating reformulation investments among adhesive suppliers serving bamboo composite producers.
- Cork:Harvested from Mediterranean oak forests for acoustic and thermal properties in upholstered furniture backing.
- Bioplastics:Bio-based polymers derived from agricultural waste streams for non-structural components and finishes.
Volume leadership belongs to Recycled Wood. Steepest expansion trajectory is in Bioplastics.
Distribution Channel:
Digital platforms are gaining share fastest among millennial first-time buyers, though showrooms retain decisive influence where specification authority sits with architects and designers.
- Online Retail:Direct-to-consumer platforms enabling subscription and take-back service models through digital product passports mandated under EU Green Deal frameworks. Secondary Scandinavian cities represent underexploited vectors for certified sustainable furnishings among price-transparent digital natives.
- Showrooms:Physical display environments where LEED and BREEAM specification consultants demand batch-level certification data and tactile material verification. Austrian artisanal craft networks leverage localized production cooperatives to reduce per-unit transport emissions while commanding premium positioning.
- Direct Sales:Manufacturer-owned channels bypassing wholesale intermediaries for margin concentration with certified producers.
- Marketplaces:Third-party platforms aggregating multiple verified brands with standardized eco-label filtering.
Margin capture concentrates in Showrooms. Channel expansion is climbing the fastest in Online Retail.
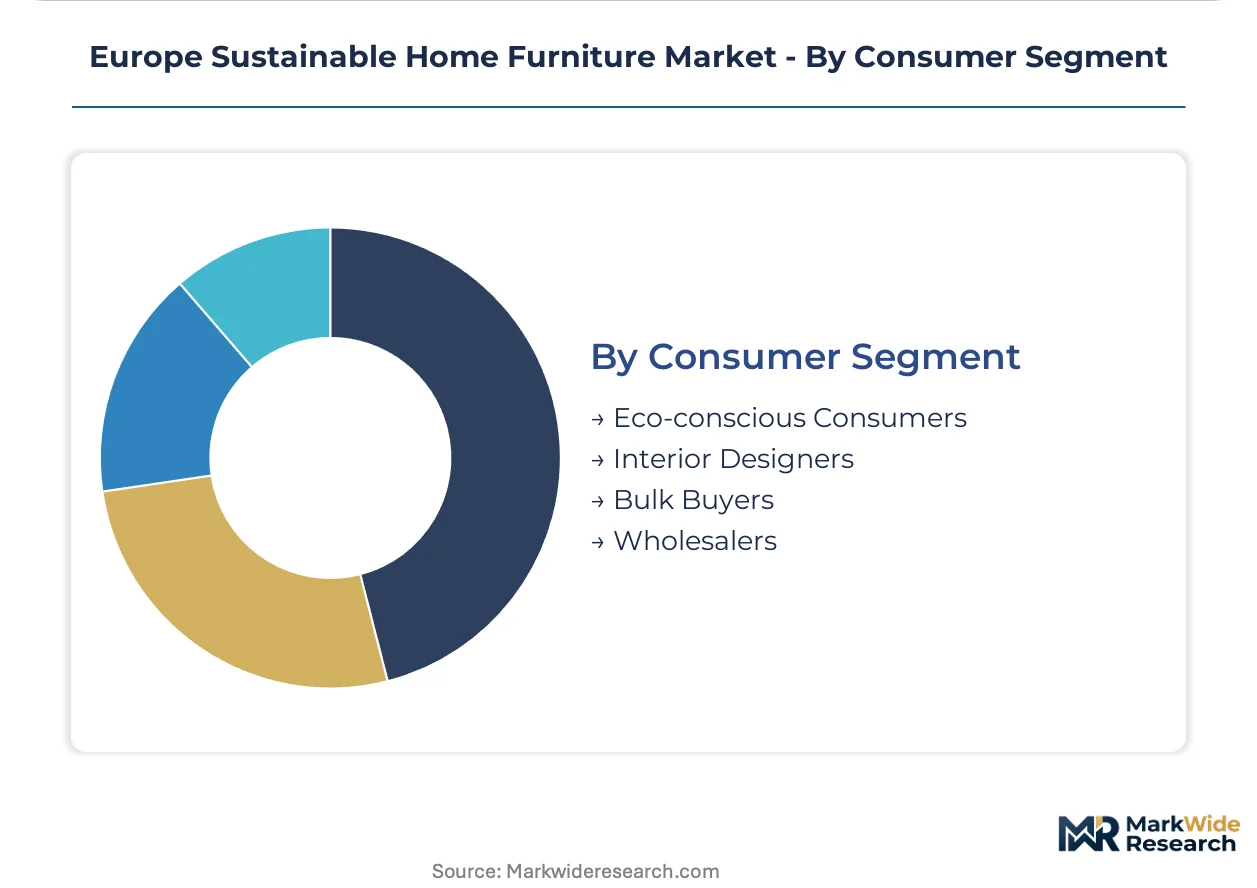
Consumer Segment:
Eco-conscious buyers respond to certification transparency, while professional specifiers prioritize compliance documentation for building assessment protocols.
- Interior Designers:Specification consultants for LEED and BREEAM-certified residential buildings adopting blockchain-enabled material provenance verification at accelerating rates. Procurement authority is decentralizing from centralized purchasing departments to project-level consultants who demand repairability scoring data ahead of pending ecodesign delegated acts.
- Eco-conscious Consumers:Residential end-users prioritizing indoor air quality standards and circular material passports in living spaces, dining areas, bedrooms, and home offices. Nordic Swan Ecolabel and German Blue Angel credentials drive willingness to pay premiums for verified low-emission furnishings.
- Bulk Buyers:Multi-unit residential developers specifying standardized sustainable interiors across portfolio properties.
- Wholesalers:Traditional distribution intermediaries facing margin compression as certification-driven preferences fragment conventional relationships.
Influence concentrates with Interior Designers. Volume scaling is expanding most quickly among Eco-conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romanian and Polish FSC-certified hardwood networks anchor the regional supply base, channeling raw material flows toward fabrication clusters in Germany and Scandinavia where building certification schemes concentrate specification demand.
Germany
Berlin apartment densification and Hamburg interior design studios drive modular furniture demand. The German Blue Angel eco-label mandates strict formaldehyde emission thresholds that privilege domestic verified manufacturers. Bavarian production cooperatives supply artisanal pieces to Munich and Stuttgart residential markets.
Sweden
LEED and BREEAM-certified residential construction in Stockholm and Gothenburg channels specification toward low-VOC furnishings. The Nordic Swan Ecolabel maintains testing protocols divergent from German standards, fragmenting pan-European product line compliance. Skåne regional timber networks feed certified supply chains for upholstery frames.
Netherlands
Amsterdam urban dwellers seek space-efficient sustainable pieces with material passports. REACH chemical restrictions enforced by ECHA accelerate reformulation investments among Dutch foam suppliers. Eindhoven design clusters prototype bio-based adhesives for production-scale validation.
Poland
FSC-certified hardwood harvests concentrate in Carpathian and Podlaskie forest regions. EU Green Deal circular economy requirements mandate recycled content thresholds for furniture exports to Western European markets. Warsaw fabrication hubs process raw timber into frame components for German and Scandinavian assemblers.
Austria
Grüne Erde anchors artisanal production cooperatives across Upper Austria and Styria. National building certification schemes reward sustainable interior specifications in Vienna and Salzburg residential developments. Localized craft networks reduce per-unit transport emissions while commanding premium positioning among design-conscious consumers.
Europe Sustainable Home Furniture Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure captive forestry access and validate bio-based material formulations. The vendor base clusters around three tiers: scale-driven retailers with integrated supply chains, mid-cap specialists leveraging regional craft networks, and design-forward studios commanding premium positioning through certification density. Two archetypes define competitive positioning: vertically integrated volume players and decentralized artisanal cooperatives. Capacity expansion in Romanian timber processing and technology licensing for digital product passports represent the dominant competitive moves reshaping supplier relationships.
Among Switzerland-based fabricators, Vitra International AG exemplifies the R&D-intensive archetype through its materials laboratory investments. IKEA Group anchors the scale-driven tier with captive forestry partnerships securing FSC-certified supply chains. Grüne Erde occupies a position within the artisanal cooperative segment, leveraging localized production networks across Austria and Germany to reduce transport emissions per unit.
| Leading Market Players |
|---|
| IKEA Group |
| Vitra International AG |
| Herman Miller Inc. |
| Steelcase Inc. |
| Knoll |
| Haworth Inc. |
| Grüne Erde |
| Mater |
| Bolia |
| Others |
Supply & Pricing Matrix
The EU Green Deal's circular economy action plan gates both qualified supply and premium-tier pricing access across European sustainable home furniture, as recycled content thresholds and extended producer responsibility mandates force manufacturers to absorb compliance costs or forfeit certification-driven specification channels.
Pricing Analysis
Take-back service bundling separates premium-tier offerings from unbundled transactional sales, with subscription models incorporating end-of-life recyclability protocols commanding sustained margin premiums. Pricing stratifies across German Blue Angel-certified premium lines, mid-market Nordic Swan Ecolabel products, and economy-tier uncertified imports. Cost compression in mid-market upholstery runs through organic textile input premiums that squeeze natural latex cushioning margins. Eco-conscious consumers in secondary Scandinavian cities demonstrate highest price transparency and sensitivity, while Hamburg and Copenhagen interior designers specifying for BREEAM-certified projects show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from ECHA substance restriction compliance force manufacturers to qualify redundant foam and adhesive suppliers across Romania, Poland, and Germany. FSC-certified hardwood frames, natural latex cushioning, and low-VOC textile finishes anchor bill-of-materials dependencies. Single-source vulnerability concentrates in Carpathian timber networks exposed to harvest volatility and transport emission accounting complexities. Distribution runs through showroom channels for specification consultants, with online retail gaining fastest among Berlin and Amsterdam apartment dwellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's pending ecodesign delegated acts for furniture erect a cost-of-compliance moat that privileges incumbent producers with validated repairability scoring and recycled content infrastructure, while fragmenting import competition.
For Market Incumbents: Anchor competitive position through captive FSC-certified forestry partnerships in Romania and Poland that secure supply continuity against harvest volatility. Deepen in-house materials research capabilities for bio-based adhesive validation at production scale, as Vitra International AG's Weil am Rhein laboratory exemplifies. Control specification channels by embedding digital product passport infrastructure ahead of mandated EU Green Deal requirements. For New Entrants and Emerging Players: Launch via direct-to-consumer online platforms targeting millennial first-time buyers in secondary Scandinavian cities where showroom penetration remains underdeveloped. Exploit white-space in Austrian artisanal craft cooperatives that reduce per-unit transport emissions while commanding premium positioning among design-conscious Vienna and Salzburg consumers. Pursue German Blue Angel certification as fastest route to specification authority with Hamburg interior design studios. For Investors and Strategic Acquirers: Ecodesign delegated act publication is the leading indicator that repairability scoring infrastructure will separate viable acquisition targets from stranded asset risks. Five-to-ten year viability favors vertically integrated mid-cap specialists with captive timber access and certified production cooperatives. Monitor ECHA substance restriction enforcement intensity as signal of reformulation investment requirements that will consolidate supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forestry Partnership | FSC-certified Romanian and Polish timber networks secure supply continuity against regional harvest volatility. |
| Digital Product Passport Deployment | EU Green Deal-mandated material tracking enables subscription and take-back service models extending customer lifetime value. |
| Bio-Based Adhesive R&D Scale-Up | Low-VOC finish validation at production scale differentiates specification positioning for BREEAM-certified projects. |
| Artisanal Craft Cooperative Expansion | Localized Austrian and German production reduces transport emissions per unit while commanding premium design positioning. |
| Online Retail Channel Buildout | Direct-to-consumer platforms penetrate secondary Scandinavian cities where showroom density remains underdeveloped. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Sustainable Home Furniture Market analysis, cross-referenced with primary interviews involving furniture manufacturing executives, sustainable materials R&D directors, interior design specification consultants, and EU regulatory affairs specialists. ECHA substance restriction databases, German Blue Angel certification registries, Nordic Swan Ecolabel audit reports, and FSC chain-of-custody documentation provided compliance verification benchmarks. Bottom-up production capacity estimates and top-down consumption flow analysis were reconciled through iterative triangulation.
Data-stream reconciliation across shipment volumes, certification database growth rates, and building permit flows for LEED and BREEAM-certified residential construction shaped the analytical framework. Segmentation dimensions spanned product type, material composition, distribution channel, and consumer segment across the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for regulatory implementation timelines. Forecast inputs incorporated EU Green Deal delegated act progression, REACH chemical restriction enforcement intensity, and urban densification patterns in Berlin and Amsterdam.
Ecodesign delegated act timing, ECHA substance restriction expansion scope, and certified timber harvest volatility are the dominant revision risks to modeled outputs. Deviation in regulatory implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Outdoor Furniture Market
Furniture
Laminated Door Market
Furniture
Bamboo Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Brazil Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
GCC Home Furniture Market
Furniture
Luxury Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
US Secondary Wood Products Market
Furniture
Rattan Furniture Market
Furniture
Europe Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Asia-Pacific Contract Furniture Market