
 Institutional Furniture Market | 2026-2036
Institutional Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Institutional Furniture Market Outlook
Asset-light leasing and furniture-as-a-service models are reshaping how institutional buyers procure workplace and educational furnishings, lowering capital barriers for mid-sized competitors. Steelcase Inc. leverages its global manufacturing footprint to sustain contract fulfillment at scale across healthcare and education verticals. Haworth Inc. differentiates through ergonomic research investment that anchors premium positioning in corporate and university installations. MillerKnoll competes via design-forward collections that occupy high-visibility public and cultural institution projects.
Institutional furniture encompasses durable, specification-grade furnishings engineered for intensive daily use in non-residential settings, typically incorporating reinforced joinery, commercial-grade finishes, and compliance-tested materials that exceed residential durability standards by factors of three to five. Seating and desks for educational end users lead volume demand, though healthcare-grade storage units command superior margin pools due to infection-control specifications and specialized material requirements. Metal and composite material segments are expanding fastest as facilities prioritize cleanability, fire resistance, and extended replacement cycles over traditional solid wood aesthetics.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, while OSHA workplace ergonomics guidelines directly shape seating and workstation specifications for institutional buyers. BIFMA certification and ANSI standards create baseline performance thresholds that filter market access for imported and domestic suppliers alike. Stakeholders must monitor evolving procurement digitization and sustainability disclosure requirements that will increasingly determine contract eligibility in public-sector and healthcare furniture tenders.
Market Dynamics
Federal infrastructure spending and hospital renovation cycles are compressing procurement timelines, forcing suppliers to accelerate specification-grade production while navigating tightening EPA emissions standards and OSHA ergonomic mandates.
Growth Catalysts
- Healthcare Facility Modernization:Hospital systems are replacing aging patient room furnishings to meet infection-control protocols, driving specification-grade orders for antimicrobial surfaces and modular storage systems.
- TSCA Title VI Compliance:EPA formaldehyde emission limits for composite wood products are filtering out non-compliant imports, creating procurement advantages for domestic manufacturers with certified supply chains.
- Ergonomic Mandates:OSHA workplace guidelines are institutionalizing adjustable seating and sit-stand workstations across university and government office installations.
Market Restraints
- Steel and Aluminum Volatility:Metal frame components face input cost swings that compress margin predictability for mid-tier contract manufacturers.
- Domestic Mill Concentration:North American particleboard and MDF supply concentrates among a handful of large-scale producers, creating bottleneck risk for composite-dependent furniture lines.
- Extended Replacement Cycles:Institutional buyers now demand 15-20 year service life guarantees, elongating revenue recognition and squeezing aftermarket attachment rates.
Strategic Opportunities
- Modular System Convergence:Furniture-as-a-service platforms combining IoT-enabled asset tracking with flexible leasing terms are opening access to budget-constrained community college systems.
- Circular Economy Incentives:Extended producer responsibility frameworks in several European markets are creating first-mover advantages for suppliers with certified take-back and refurbishment programs.
- Rural Healthcare Expansion:Federally qualified health centers in underserved U.S. regions are receiving capital grants for facility upgrades, generating concentrated demand for durable clinical furnishings.
Industry Challenges
- BIFMA Certification Bottlenecks:Third-party testing backlogs are extending product launch timelines by 4-6 months for new seating and workstation introductions.
- Legacy System Integration:Facilities management software in established hospitals and universities resists API connectivity with modern furniture sensor networks, complicating smart deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Institutional Furniture Market |
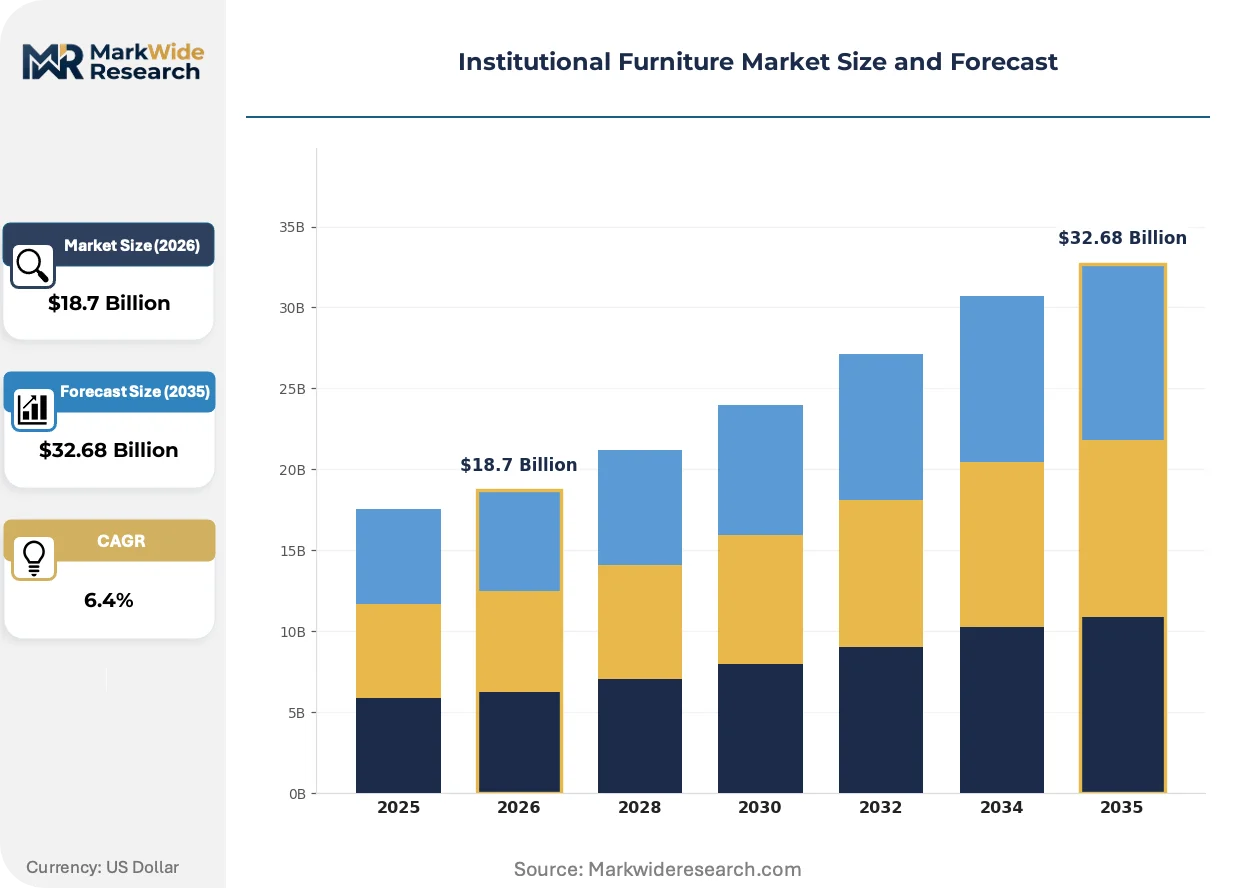
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units End User: Schools, Universities, Hospitals, Libraries Material: Wood, Metal, Plastic, Composite Design Style: Modern, Traditional, Ergonomic, Minimalist |
| Companies Covered | IKEA, Ashley Furniture Industries, Steelcase Inc., HNI Corporation, Haworth Inc., MillerKnoll, Okamura Corporation, Kimball International Inc., Masco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Institutional Furniture Market Strategic Shifts
Material science advances and procurement digitization are compressing traditional specification timelines while embedding sustainability tracking into contract furniture workflows.
Antimicrobial copper-infused laminates are collapsing the distinction between surface aesthetics and infection control in patient room furnishings. Hospital systems in the United States are specifying these materials for high-touch zones, eliminating the need for separate disinfectant protocols and reducing housekeeping labor allocation.
REACH SVHC disclosure requirements are forcing supply chain transparency down to the sub-component level across European public procurement. Manufacturers must now document chemical composition through tier-three suppliers, reshaping vendor qualification processes and disqualifying opaque Asian component sources from EU hospital tenders.
Reverse auction platforms are consolidating purchasing power among multi-campus university systems and regional hospital networks. These digital marketplaces compress vendor evaluation to price-per-unit metrics, marginalizing design differentiation and favoring suppliers with standardized, high-volume product lines in the North American education vertical.
Institutional Furniture Market Segmentation
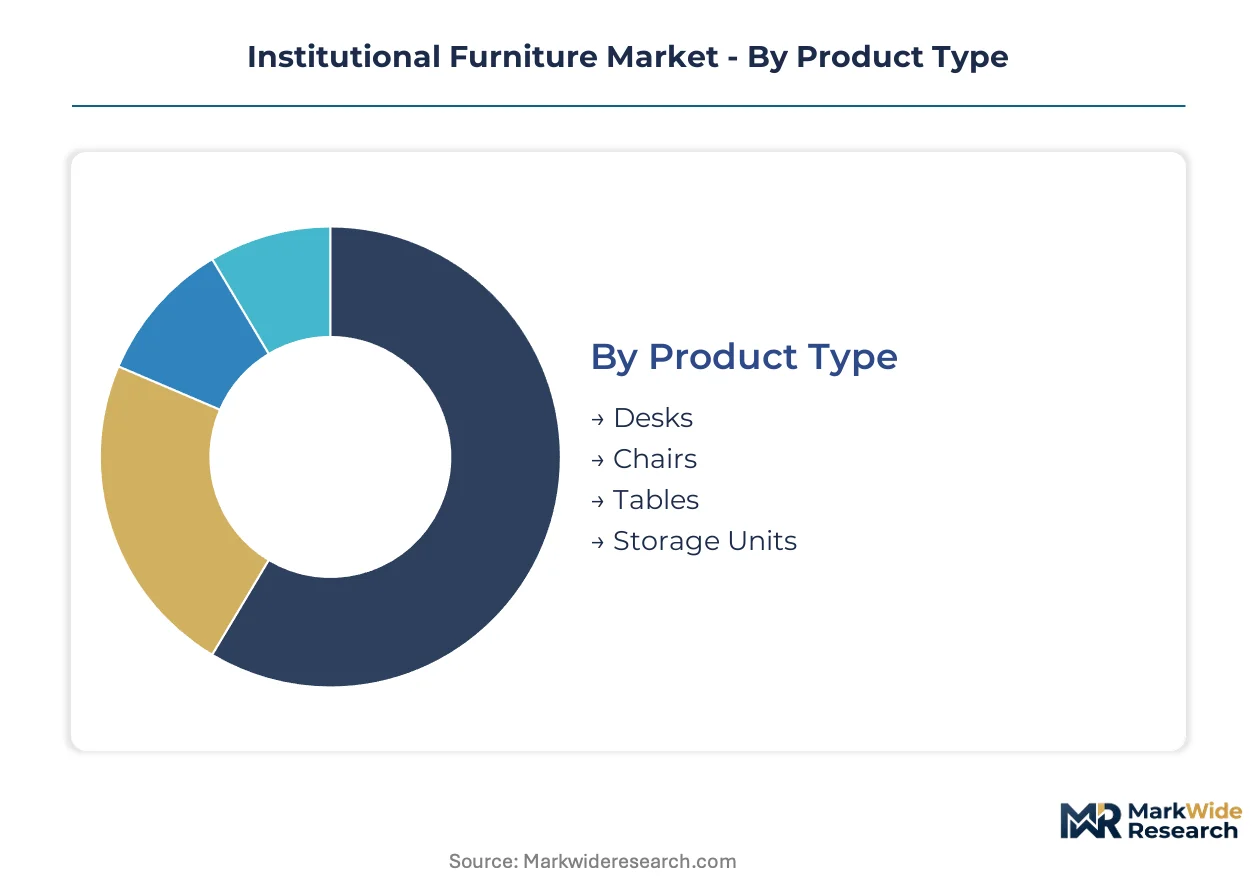
Institutional furniture procurement cycles vary dramatically by segment, with educational seating requiring replacement every 7-10 years while healthcare storage systems operate on 15-20 year lifecycles. Understanding these velocity differentials helps suppliers align inventory planning with contract renewal timing and maintenance revenue streams.
Product Type:
Seating and work surfaces turn over fastest in high-traffic educational settings, whereas infection-controlled storage systems endure longest in clinical environments.
- Desks:Specification-grade work surfaces integrate cable management channels and modular connectivity for technology-dense classrooms. Demand concentrates in United States K-12 districts modernizing STEM facilities, with federal infrastructure grants compressing procurement timelines for adjustable-height models.
- Chairs:Ergonomic seating incorporates reinforced polypropylene shells and steel frames tested to BIFMA durability standards. University systems in California and Texas are standardizing task chairs with 12-year warranties to reduce lifecycle procurement costs.
- Tables:Collaborative and cafeteria tables prioritize impact-resistant edges and nesting capabilities for space flexibility. Community college systems favor reconfigurable flip-top designs for multi-use classrooms.
- Storage Units:Healthcare-grade cabinets feature seamless welded construction and antimicrobial powder coatings. Hospital renovation cycles in Florida and Ohio are driving specification of modular casework with integrated supply tracking.
Chairs anchor the volume base while storage units gain share at the steepest rate.
End User:
Procurement sophistication and specification complexity separate budget-constrained primary education from capital-rich hospital networks.
- Schools:K-12 facilities prioritize vandal-resistant construction and rapid-replacement part availability. Rural districts in the United States Midwest are consolidating purchasing through regional cooperative agreements to access volume pricing.
- Universities:Research institutions and liberal arts colleges demand design-forward furnishings for donor-visible spaces. Ivy League campuses are specifying FSC-certified wood and cradle-to-cradle material passports for sustainability reporting.
- Hospitals:Acute care facilities require infection-control surfaces and cleanable geometries that eliminate pathogen harborage. Joint Commission accreditation standards are mandating furniture documentation for patient safety audits.
- Libraries:Public and academic reading rooms need acoustic dampening and power-integrated seating for device charging. Carnegie-class library renovations in the Northeast are specifying flexible lounge systems to accommodate programming shifts.
Hospitals command the highest specification tiers while schools generate the largest unit volumes.
Material:
Cost-performance tradeoffs and regulatory compliance are reshaping material selection away from traditional solid wood toward engineered alternatives.
- Wood:Hard maple and oak remain preferred for executive and judicial settings where permanence signals institutional authority. TSCA Title VI certification requirements are filtering out non-compliant imported hardwood plywood from federal procurement.
- Metal:Steel and aluminum frames dominate high-abuse environments with powder-coated finishes providing scratch resistance. Steel price volatility is forcing contract manufacturers toward fixed-price annual agreements with tier-one mills.
- Plastic:High-density polyethylene and polypropylene offer color consistency and moisture immunity for outdoor and pool-adjacent installations. Recreation centers are specifying UV-stabilized grades for extended fade resistance.
- Composite:Medium-density fiberboard and particleboard with thermally fused laminates balance cost and cleanability. EPA formaldehyde emission limits are advantaging domestic producers with certified supply chains over Asian imports.
Metal and composite materials are climbing the fastest as facilities prioritize durability and regulatory compliance over aesthetic tradition.
Design Style:
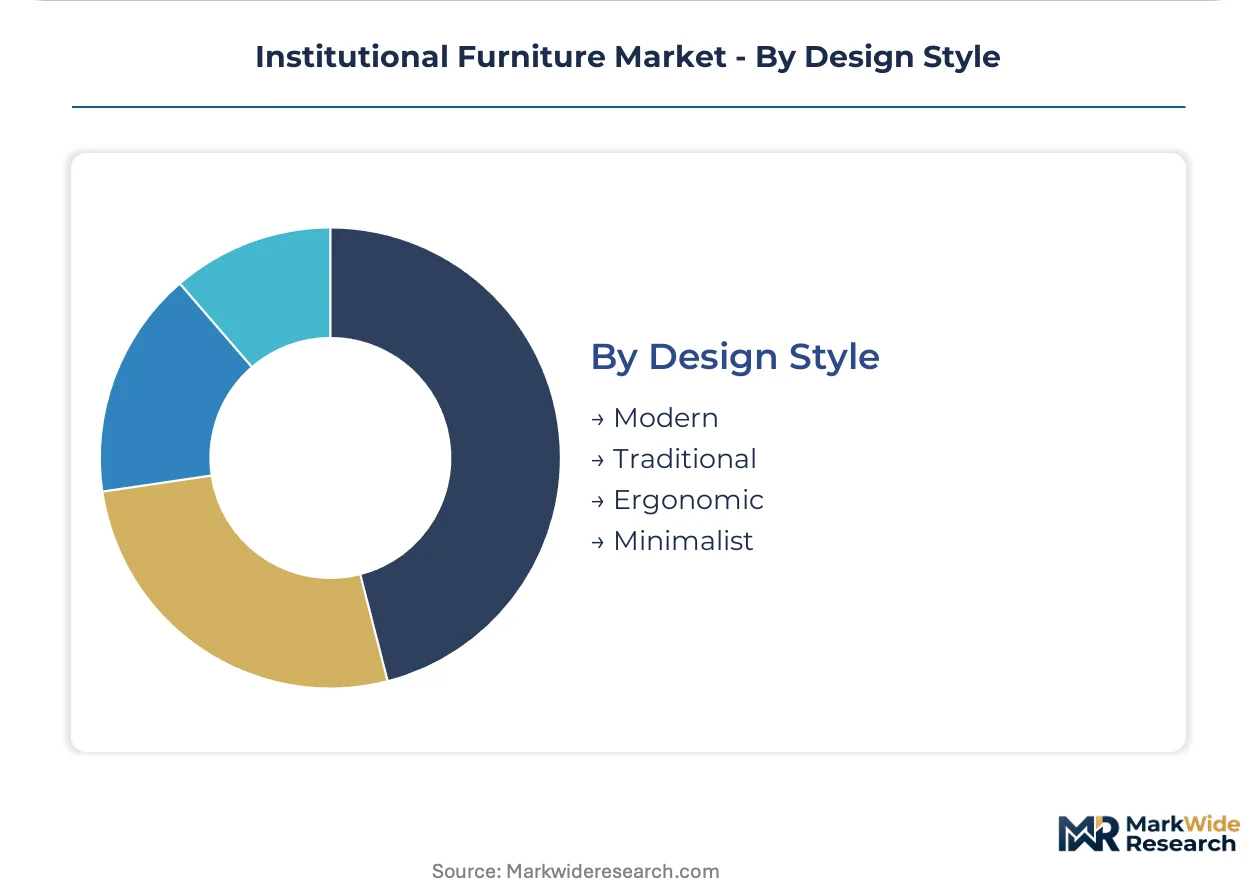
Visibility and user population determine whether institutions prioritize timeless authority or contemporary flexibility.
- Modern:Clean lines and neutral palettes dominate technology sector partnerships and innovation hubs. Corporate-affiliated university research parks are specifying open-plan benching systems with minimal visual weight.
- Traditional:Raised panel details and rich wood tones persist in legal, financial, and ceremonial settings. State capitols and federal courthouses maintain specification preferences for mahogany and cherry veneers.
- Ergonomic:Anthropometric adjustability and movement encouragement define OSHA-compliant workplace installations. State government office consolidations are mandating sit-stand workstations and task lighting integration.
- Minimalist:Reduced visual complexity and material honesty appeal to wellness-focused healthcare and meditation spaces. Cancer treatment centers are specifying pared-down patient room furnishings to reduce environmental stress.
Ergonomic design anchors the specification pipeline while modern styling gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal concentrated manufacturing in North America and Europe against rising Asian assembly capacity. The United States maintains a structural furniture trade deficit, importing finished goods while exporting design services and specification expertise. Germany and China anchor continental supply bases with divergent regulatory compliance frameworks.
United States
Federal education infrastructure grants and hospital renovation cycles compress procurement timelines for specification-grade furnishings. EPA TSCA Title VI formaldehyde emission standards filter non-compliant composite wood imports, advantaging domestic manufacturers with certified supply chains. Grand Rapids, Michigan anchors contract furniture manufacturing, with Steelcase and Haworth sustaining vertical integration from component fabrication to final assembly.
Germany
REACH SVHC disclosure requirements force chemical transparency through tier-three suppliers, reshaping vendor qualification for EU hospital tenders. The country's national furniture association coordinates BIFMA-equivalent testing protocols that filter market access for imported and domestic suppliers alike. North Rhine-Westphalia concentrates engineered wood processing, with particleboard mills supplying contract manufacturers across the Benelux region.
China
Domestic hospital construction and university expansion drive specification-grade demand for antimicrobial surfaces and modular storage systems. GB standards for indoor air quality and workplace ergonomics tighten material and design specifications for institutional buyers. The Yangtze River Delta hosts composite material clusters, with MDF and particleboard producers serving both export assembly and domestic contract furniture lines.
Japan
Aging care facility construction and school consolidation programs sustain replacement demand for durable clinical and educational furnishings. METI guidelines on circular economy implementation incentivize take-back and refurbishment programs among institutional suppliers. Osaka Prefecture concentrates metal frame fabrication, with powder-coating facilities serving healthcare-grade casework specifications.
Institutional Furniture Market Competitive Environment
On the supply side, the industry is moderately consolidated around full-line contract manufacturers with specification-grade capabilities, while fragmented specialty producers occupy niche infection-control and ergonomic segments. Three strategic archetypes dominate: vertically integrated North American giants with global manufacturing footprints, European design-forward specialists with sustainability certifications, and Asian scale producers with cost-optimized composite lines. Competitive intensity centers on M&A-driven portfolio expansion and strategic partnerships for IoT-enabled asset tracking platforms.
Within the vertically integrated tier, Steelcase Inc. and Haworth Inc. exemplify supply chain control from raw material sourcing through certified finished goods production. MillerKnoll occupies a position bridging design prestige with institutional scale, representing the premium-mid-market convergence archetype. These three anchors illustrate how geographic manufacturing footprint and specification expertise determine contract eligibility in federal education and healthcare tenders.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| Steelcase Inc. |
| HNI Corporation |
| Haworth Inc. |
| MillerKnoll |
| Okamura Corporation |
| Kimball International Inc. |
| Masco Corporation |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum input volatility compresses margin predictability across specification-grade production tiers while simultaneously forcing contract manufacturers toward fixed-price sourcing agreements that reshape tiered pricing spreads and upstream procurement geography. This commodity exposure differentially advantages vertically integrated producers with captive metal fabrication against import-dependent assemblers facing spot market swings.
Pricing Analysis
Institutional procurement officers anchor three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale serving as the primary differentiation drivers. BIFMA Level certification and FSC chain-of-custody documentation command 15-25 percent premiums over uncertified equivalents in federal education tenders. Pricing pressure stems from reverse auction platform consolidation among multi-campus university systems, compressing vendor evaluation to unit economics. Rural K-12 districts exhibit highest price sensitivity, while Ivy League and acute care hospital networks prioritize specification compliance over cost minimization.
Supply Chain Analysis
Particleboard and MDF feedstock draws from concentrated North American mill capacity in Michigan, Wisconsin, and Quebec, with formaldehyde-compliant domestic supply chains advantaged over Asian imports under TSCA Title VI. Steel frame components hinge on Ohio Valley and Ontario fabrication clusters, while antimicrobial powder coatings source from specialty chemical producers in Germany and the United States. Tariff exposure on Chinese component imports creates bottleneck risk for cost-optimized assembly operations. Distribution runs through manufacturer-direct specification sales for large hospital networks, with regional dealer cooperatives serving fragmented K-12 procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters a cyclical recovery phase as deferred hospital renovation cycles and federal education infrastructure grants compress procurement timelines, with replacement demand from aging 1990s-era installations providing sustained order visibility.
For Market Incumbents: Harden specification-grade production capacity against Asian cost competition by deepening backward integration into certified composite wood supply chains and securing exclusive BIFMA testing laboratory partnerships. Accelerate IoT-enabled asset tracking platform development to defend service revenue streams against furniture-as-a-service entrants targeting community college systems with flexible leasing terms.
For New Entrants and Emerging Players: Rural healthcare expansion zones in federally qualified health centers present the most penetrable white-space opportunity, with capital grant funding insulating price-sensitive procurement from budget constraints. Target antimicrobial surface specialization for infection-control applications where domestic certification requirements filter import competition. Pursue regional cooperative purchasing agreements as the primary go-to-market channel, bypassing entrenched specification sales relationships.
For Investors and Strategic Acquirers: EPA TSCA Title VI enforcement reshapes the acquisition landscape by devaluing import-dependent assembly operations while premiumizing domestic certified supply chain assets. Five-to-ten year viability favors targets with vertical integration into engineered wood processing and established hospital system specification relationships. Monitor BIFMA certification backlog durations as an inflection indicator for production capacity constraints and pricing power accumulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Composite Supply | TSCA Title VI compliance secures federal procurement eligibility against import competition. |
| IoT-Enabled Asset Tracking Platform Launch | Smart furniture sensors unlock recurring service revenue from hospital facilities management contracts. |
| Antimicrobial Surface Technology Licensing | Copper-infused laminate patents command premium positioning in Joint Commission-accredited renovations. |
| Regional Cooperative Purchasing Partnership | Consolidated K-12 procurement access circumvents fragmented district-level sales cycles. |
| Take-Back and Refurbishment Program Certification | Circular economy credentials qualify suppliers for extended producer responsibility frameworks in European tenders. |
Study Parameters
A spread of perspectives from contract furniture specification sales directors, hospital facilities procurement managers, K-12 cooperative purchasing administrators, and EPA compliance officers converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against BIFMA certification databases, federal procurement records, and SEC filings from publicly traded manufacturers. Trade flow data from customs records and particleboard production statistics from the Composite Panel Association anchored supply-side quantification. Bottom-up contract value aggregation and top-down macroeconomic adjustment produced convergent market size estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, end-user vertical, material composition, and design style, with healthcare infection-control specifications and educational durability standards as cross-cutting qualification filters. CAGRs derived from historical replacement cycle analysis and announced hospital renovation pipelines, weighted by federal infrastructure grant allocation timing. Forecast inputs included steel price futures curves, particleboard capacity utilization rates, and BIFMA certification queue lengths.
Practitioners should monitor steel tariff policy shifts, EPA formaldehyde enforcement actions, and hospital capital expenditure guidance revisions for early signals requiring forecast reassessment. Cross-checking against American Hospital Association facility investment surveys and National Center for Education Statistics modernization expenditure data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Office Furniture Edgebands Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Standing Desk Market
Office Furniture
Home Office Spending Market
Office Furniture
Desk Chairs Market
Office Furniture
Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
United States Furniture Market