
 North America Home Furniture Market | 2026-2036
North America Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Furniture Market Analytics
Multi-source sourcing toward domestic and near-shore manufacturing is recalibrating procurement strategies across the North America home furniture sector. Ashley Furniture Industries anchors its competitive stance through captive manufacturing scale across Mississippi, North Carolina, and Wisconsin. Wayfair Inc. navigates a pure digital model that leverages algorithmic demand forecasting to optimize drop-ship fulfillment. Williams-Sonoma Inc. differentiates through design-forward upholstery and direct-to-consumer channel control.
North America home furniture encompasses movable residential fixtures constructed from wood, metal, plastic, or upholstery materials, designed for seating, storage, surface, and sleep functions within dwelling units. Engineered wood substrates, eight-way hand-tied spring suspension, and CertiPUR-US certified foam define performance benchmarks for durability and indoor air quality. Sofas and upholstered seating command the largest revenue pool, while cabinets and storage systems capture disproportionate margin in the custom and semi-custom channel. Wood material formulations face pressure from volatile lumber futures, yet metal and upholstery segments gain traction in rental housing and multifamily applications where durability requirements intensify.
EPA formaldehyde emissions standards under TSCA Title VI, California Air Resources Board (CARB) Phase 2 compliance protocols, and CPSC flammability regulations govern product composition and market access across the United States and Canada. These frameworks elevate testing and certification costs for imports while advantaging domestic producers with established laboratory relationships and supply chain traceability systems. Stakeholders must monitor evolving state-level chemical disclosure mandates and building code harmonization between the US and Canada to anticipate compliance-driven sourcing shifts and product line restructuring.
Market Dynamics
California's Title 20 energy efficiency standards are compressing foam and fabric specifications across upholstered furniture supply chains, forcing reformulation investments while creating compliance advantages for domestic producers with established testing infrastructure.
Growth Catalysts
- Millennial First-Time Homebuyers:Residential renovation activity among this demographic is expanding order volumes for entry-to-mid-tier furniture categories. Texas, Florida, and Georgia housing starts concentrate demand geographically.
- CARB Phase 2 Compliance:California Air Resources Board protocols for formaldehyde emissions are accelerating domestic laboratory certification investments. Established producers gain market access advantages over import-dependent competitors.
- Engineered Wood Substrates:Performance benchmarks for durability and indoor air quality are advancing material specifications. CertiPUR-US certified foam penetration is deepening across rental housing and multifamily applications.
Market Restraints
- Volatile Lumber Futures:Wood material formulations face sustained input cost pressure from commodity market swings. Margin compression concentrates in mass-market wood furniture segments.
- Import Certification Friction:EPA TSCA Title VI emissions standards elevate testing costs for offshore manufacturing. CPSC flammability regulations create timeline uncertainty for containerized shipments.
- Metal Segment Substitution:Upholstery and metal furniture gains traction in durability-intensive rental applications. Wood dominance in residential core categories faces structural displacement risk.
Strategic Opportunities
- Near-Shore Manufacturing Migration:Multi-source sourcing recalibration creates capacity expansion openings in Mexico and Central America. Labor cost arbitrage persists against Asian alternatives with reduced logistics exposure.
- Direct-to-Consumer Channel Control:Algorithmic demand forecasting integration enables drop-ship fulfillment optimization. Digital-native inventory models compress working capital requirements relative to legacy retail.
- State-Level Chemical Disclosure Mandates:Evolving building code harmonization between the United States and Canada anticipates compliance-driven product line restructuring. Early movers capture specification advantages.
Industry Challenges
- Eight-Way Hand-Tied Spring Suspension Craft Gap:Skilled upholstery labor scarcity constrains custom and semi-custom channel expansion. Training pipeline inadequacy limits capacity scaling.
- Supply Chain Traceability System Integration:Laboratory relationship investments required for multi-jurisdiction compliance create fixed cost barriers. Mid-tier producers face disproportionate certification burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Furniture Market |
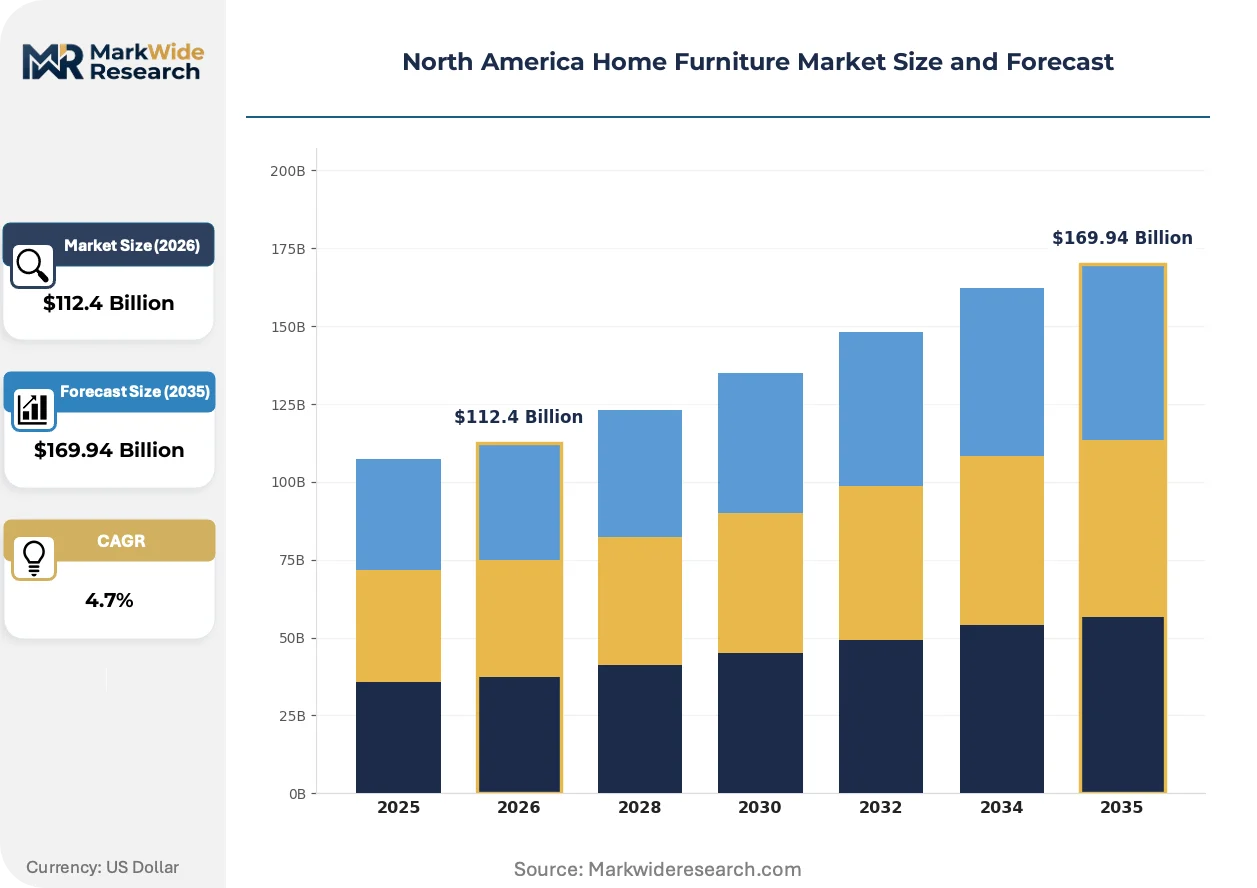
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Plastic, Upholstery Style: Modern, Traditional, Rustic, Minimalist Distribution Channel: Online, Offline, Home Improvement Stores, Furniture Retailers |
| Companies Covered | Ashley Furniture Industries, Wayfair Inc., Williams-Sonoma Inc., La-Z-Boy Incorporated, IKEA North America Services, RH, Ethan Allen Interiors Inc., Bassett Furniture Industries, Rooms To Go Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Furniture Market Evolving Landscape
Digital demand forecasting and algorithmic inventory management are compressing traditional furniture procurement cycles, while regulatory chemistry restrictions and material performance standards reshape product development priorities.
Modular sofa platforms with configurable sectionals is unifying seating, storage, and sleep functions within single product architectures. Multifamily developers and co-living operators are adopting these systems at accelerated pace to maximize spatial efficiency in compact units. This convergence is unifying previously separate furniture categories, compressing supplier counts per project while elevating performance requirements for integrated mechanisms.
California Title 20 energy efficiency standards are mandating specific foam density and fabric permeability thresholds for upholstered furniture sold in the state. Manufacturers must reformulate core materials or forfeit access to the largest United States regional economy. Domestic producers with captive foam pouring operations and established relationships with CARB-certified laboratories are capturing specification share from import-dependent competitors facing testing timeline delays.
Algorithmic drop-ship fulfillment is displacing traditional wholesale-retail inventory models across mid-market furniture segments. Wayfair's pure digital platform demonstrates demand forecasting precision that reduces carrying costs versus brick-and-mortar competitors. This behavioral shift concentrates most visibly in suburban markets where millennial homebuyers prioritize delivery speed and configuration flexibility over showroom tactile evaluation.
North America Home Furniture Market Segmentation
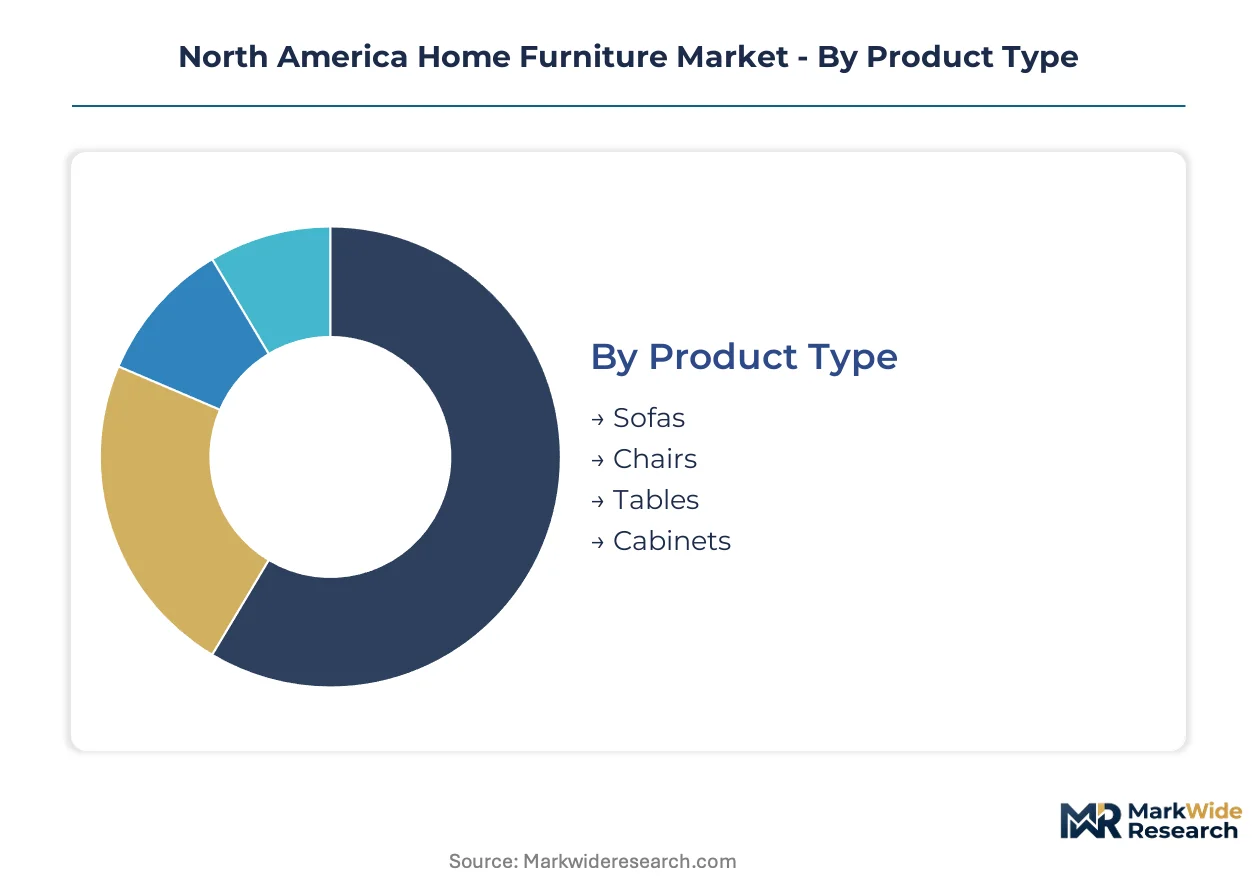
Segmentation in North American home furniture reveals how material specifications, distribution economics, and design preferences fragment procurement decisions. Buyers trade off CARB compliance costs against delivery speed and spatial configuration needs.
Product Type:
Buyers prioritize functional versatility and room-scale integration when selecting furniture categories for residential spaces.
- Sofas:Configurable sectionals with integrated storage mechanisms dominate multifamily specifications. Texas and Florida developers specify these for co-living units where spatial efficiency commands premium pricing.
- Chairs:Accent and dining seating categories concentrate demand in renovation-driven suburban markets. Millennial first-time homebuyers in Georgia prioritize ergonomic designs with quick-ship availability over custom lead times.
- Tables:Dining and surface furniture face substitution pressure from engineered wood alternatives. California Title 20 compliance costs compress margins in mass-market wood table segments.
- Cabinets:Storage systems capture disproportionate margin in custom channels. Semi-custom kitchen and bath cabinetry requires CARB Phase 2 certification investments that favor domestic producers.
Volume sits with Sofas; growth tilts toward Cabinets.
Material:
Cost tier positioning and durability requirements split procurement strategies across residential versus rental housing applications.
- Wood:Engineered substrates with TSCA Title VI compliance anchor premium residential positioning. Volatile lumber futures force reformulation toward medium-density fiberboard in entry-price tiers.
- Metal:Powder-coated steel frames gain specification share in durability-intensive rental applications. Multifamily operators in Texas and Florida prioritize metal for common-area seating over wood alternatives.
- Plastic:Polypropylene and polycarbonate formulations serve outdoor and children's furniture niches. Injection-molded production enables rapid SKU proliferation for seasonal demand spikes.
- Upholstery:CertiPUR-US certified foam penetration deepens across all price tiers. California Title 20 density mandates force domestic foam pouring investment or market exclusion.
Wood dominates current revenue; upholstery climbs the fastest on regulatory-driven specification shifts.
Style:
Customer lifecycle stage and housing type concentration determine style preference distribution across regional markets.
- Modern:Clean lines and modular platforms align with millennial homebuyer preferences in suburban Georgia and Florida. Digital-native retailers capture disproportionate share through algorithmic demand forecasting.
- Traditional:Classic silhouettes concentrate in established Northeast and Midwest markets. Eight-way hand-tied suspension craftsmanship scarcity constrains capacity scaling.
- Rustic:Reclaimed wood aesthetics and distressed finishes target vacation and second-home segments. Supply chain traceability requirements elevate sourcing costs for authentic reclaimed materials.
- Minimalist:Space-conscious designs gain traction in urban multifamily and co-living developments. Japanese and Scandinavian influences penetrate through direct-to-consumer digital channels.
Modern commands volume share; minimalist gains share fastest on urban density trends.
Distribution Channel:
Speed-to-delivery and tactile evaluation trade-offs fragment buyer channel selection by geography and purchase urgency.
- Online:Pure digital platforms leverage drop-ship fulfillment to compress working capital. Algorithmic inventory management enables configuration flexibility that suburban millennial buyers prioritize.
- Offline:Brick-and-mortar showrooms retain importance for upholstery tactile evaluation. Custom and semi-custom segments depend on designer-assisted selling environments.
- Home Improvement Stores:Big-box retail captures entry-price storage and surface furniture volume. Texas and Florida housing starts concentrate demand in contractor-driven bulk purchasing.
- Furniture Retailers:Specialty chains control mid-market upholstered goods through captive financing. Regional players in Georgia and North Carolina leverage proximity to manufacturing clusters.
Offline retains margin concentration; online expands most quickly on fulfillment speed advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern yellow pine forests anchor raw material flows across the southeastern United States, feeding engineered wood substrate production for residential furniture manufacturing clusters.
United States
Millennial first-time homebuyers in Texas, Florida, and Georgia are expanding order volumes for entry-to-mid-tier categories. EPA TSCA Title VI formaldehyde emissions standards govern composite wood products nationwide, elevating laboratory certification costs for imports. High Point, North Carolina hosts the largest furniture manufacturing cluster, where captive foam pouring operations and CARB-certified testing infrastructure concentrate.
Canada
Cross-border supply chain integration with US manufacturers sustains demand for Canadian softwood lumber and upholstered components. Health Canada administers the Canada Consumer Product Safety Act alongside provincial building codes that harmonize with US standards. The Greater Toronto Area anchors distribution networks serving Ontario and Quebec renovation markets with quick-ship inventory models.
Mexico
Near-shore manufacturing migration accelerates capacity expansion for US-bound furniture assembly and upholstery finishing. Mexican federal environmental regulations through SEMARNAT align with California Air Resources Board protocols for formaldehyde emissions. Nuevo León and Jalisco industrial corridors attract domestic and Asian capital for captive foam production and metal frame fabrication.
California
Title 20 energy efficiency standards mandate specific foam density and fabric permeability thresholds for upholstered furniture sold statewide. The California Air Resources Board operates the nation's most stringent composite wood product certification program. Los Angeles and San Francisco metropolitan areas concentrate demand for design-forward, quick-ship furniture through direct-to-consumer digital channels.
Texas
Population inflows and new housing starts in Dallas-Fort Worth and Houston concentrate demand for durable, value-positioned furniture categories. State-level energy codes influence building material specifications without preempting federal EPA authority. The Dallas Design District hosts regional distribution centers for national retailers targeting Sun Belt expansion.
North America Home Furniture Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers recalibrate procurement strategies toward domestic and near-shore production bases. The vendor base exhibits moderate concentration, with integrated producers controlling captive manufacturing scale and digital-native platforms commanding algorithmic demand forecasting capabilities. Three archetypes define competitive positioning: vertically integrated manufacturers with laboratory certification infrastructure, pure digital retailers leveraging drop-ship fulfillment, and design-forward brands with direct-to-consumer channel control. Geographic expansion into Mexico and Central America, alongside portfolio diversification into modular and multifunctional product architectures, represents the dominant competitive moves.
Among integrated domestic manufacturers, Ashley Furniture Industries anchors the scale-driven tier with captive production across Mississippi, North Carolina, and Wisconsin. Wayfair Inc. exemplifies the pure digital archetype through algorithmic inventory management and drop-ship fulfillment optimization. Williams-Sonoma Inc. occupies a position within the design-forward, direct-to-consumer segment, controlling channel economics through owned retail and e-commerce platforms.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| Wayfair Inc. |
| Williams-Sonoma Inc. |
| La-Z-Boy Incorporated |
| IKEA North America Services |
| RH |
| Ethan Allen Interiors Inc. |
| Bassett Furniture Industries |
| Rooms To Go Incorporated |
| Others |
Value Network & Pricing Analysis
Volatile lumber futures transmit cost pressure downstream through engineered wood substrate tiers, with CARB Phase 2 compliance investments stratifying pricing across domestic laboratory-certified producers and import-dependent competitors facing testing timeline delays.
Pricing Analysis
Warranty and white-glove delivery bundling separates premium upholstery tiers from unbundled economy positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by CertiPUR-US certification status and eight-way hand-tied suspension craftsmanship. Cost compression in mass-market wood furniture intensifies because medium-density fiberboard substitution erodes margin buffers. Millennial first-time homebuyers in Texas and Florida exhibit highest price sensitivity, while custom channel buyers in California prioritize lead time certainty over absolute cost.
Supply Chain Analysis
Domestic-content mandates through California Title 20 foam density specifications and EPA TSCA Title VI composite wood certification reshape sourcing toward captive North American production. Raw material flows draw from Southern yellow pine forests in Mississippi and North Carolina, CertiPUR-US certified foam pouring operations in Wisconsin, and powder-coated steel frame fabrication in Nuevo León. Single-source vulnerability concentrates in CARB-certified laboratory capacity for emissions testing. Distribution runs through High Point, North Carolina manufacturing clusters feeding direct-to-consumer digital channels and brick-and-mortar specialty chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance infrastructure investments that force smaller import-dependent competitors into acquisition or exit, with California Title 20 and EPA certification costs accelerating shakeout timelines.
For Market Incumbents: Hedge against metal segment substitution in rental housing by deepening upholstery craftsmanship capacity in North Carolina and Wisconsin. Secure captive foam pouring operations to neutralize California Title 20 reformulation risks. Laboratory certification relationships with CARB-approved facilities anchor defensive positioning against testing-timeline delays that disadvantage offshore sourcing. For New Entrants and Emerging Players: Digital-native retailers with algorithmic demand forecasting capabilities capture white-space in suburban Georgia and Florida renovation markets where quick-ship configuration flexibility outranks showroom tactile evaluation. Modular sofa platforms with integrated storage mechanisms penetrate multifamily developer specifications fastest. Drop-ship fulfillment partnerships with Mexican upholstery finishing operations compress working capital requirements versus inventory-heavy models. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier domestic producers with latent CARB certification infrastructure in Mississippi and North Carolina laboratory corridors. Long-term viability centers on compliance-driven specification capture as Title 20 harmonization spreads to additional states. Watch for EPA enforcement intensity signals as inflection indicators for import-dependent competitor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Near-Shore Manufacturing Migration | Mexican and Central American capacity expansion reduces logistics exposure while preserving labor cost arbitrage against Asian alternatives. |
| Direct-to-Consumer Channel Control | Owned e-commerce platforms with algorithmic inventory management compress working capital versus wholesale-retail models. |
| Certification Infrastructure Investment | CARB Phase 2 and EPA TSCA Title VI laboratory relationships create market access barriers against import-dependent competitors. |
| Modular Product Architecture Development | Configurable sectionals with integrated storage mechanisms capture multifamily developer specifications for spatial efficiency. |
| Craftsmanship Pipeline Rebuilding | Eight-way hand-tied suspension training programs address skilled upholstery labor scarcity constraining custom channel expansion. |
Research Methodology
Document review covered EPA TSCA Title VI regulatory filings, California Air Resources Board certification databases, and customs trade records, complemented by interviews with furniture manufacturing executives, upholstery plant managers, multifamily developer procurement leads, and CARB-certified laboratory directors. Secondary validation drew from SEC 10-K disclosures, housing starts data, and lumber futures market records. Bottom-up production capacity estimates triangulated against top-down demand modeling across millennial homebuyer demographic projections.
Cross-referencing historical price elasticity patterns against expert panel input on regulatory compliance cost pass-through shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material formulation, distribution channel, and regional housing market concentration. CAGRs derived from trend extrapolation adjusted for California Title 20 implementation timing and near-shore manufacturing capacity buildout trajectories. Forecast inputs incorporated engineered wood substrate substitution rates and CertiPUR-US foam penetration curves.
Several conditions sit outside the modeled scope, including extreme lumber commodity volatility, unanticipated EPA enforcement escalations, and rapid building code harmonization between the United States and Canada. Forecasts reflect documented assumptions about millennial homeownership rates and multifamily development permit approvals. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
France Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Home Furnishings Market
Furniture
Entryway Furniture Market
Furniture
Global Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Russia Home Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
High End Furnitures Market
Furniture
China Upholstered Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
China Home Furniture Market
Furniture
Europe Wood Decorative Wall Panel Market