
 United Kingdom Home Furniture Market | 2026-2036
United Kingdom Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Home Furniture Market Analytics
Skilled upholstery craft shortages across the West Midlands is reorganizing how domestic manufacturers approach workforce development and automation. DFS Furniture plc sustains its national store network while navigating labor constraints through in-house training academies. Dunelm Group plc leverages vertically integrated textile sourcing to control margin pools in soft furnishings. Oak Furnitureland anchors its proposition around solid-wood specialization, competing against flat-pack imports through made-to-order craftsmanship.
United Kingdom home furniture encompasses movable residential fixtures designed for domestic living spaces, typically constructed from timber frames, engineered boards, metal hardware, and textile coverings through CNC machining, hand-finishing, and upholstery assembly processes. These products serve the functional and aesthetic furnishing of dwellings across seating, storage, sleeping, and surface applications. Seating and storage categories dominate volume throughput, while upholstered products command premium margin pools due to higher labor intensity and fabric customization. Online sales channels are expanding fastest, though showrooms retain decisive influence in high-consideration purchases of beds and dining sets.
The UK's Furniture and Furnishings (Fire Safety) Regulations, enforced by local trading standards authorities, mandate specific ignition resistance standards for domestic upholstered products, directly shaping foam and fabric specification choices. BSI Kitemark certification and EU-originated CE marking transitions under UKCA requirements further condition market access for imported goods. Stakeholders must monitor evolving fire safety test protocol amendments and post-Brexit conformity assessment recognition agreements to preserve supply chain fluidity.
Market Dynamics
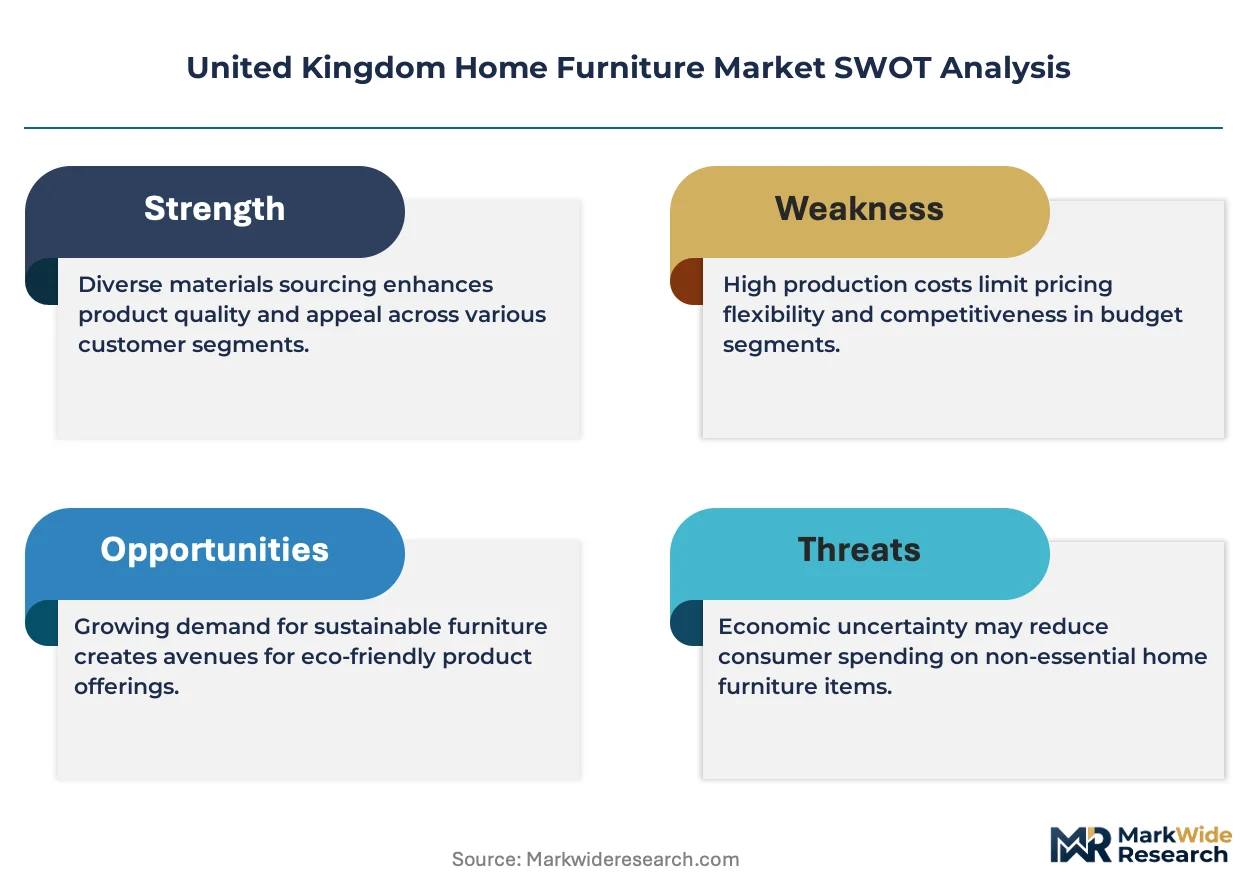
The UK's Furniture and Furnishings (Fire Safety) Regulations are compressing domestic manufacturing margins while accelerating compliance-driven consolidation among upholstery specialists. This regulatory pressure intersects with skilled craft shortages to reshape competitive positioning across the West Midlands production cluster.
Growth Catalysts
- Urban Rental Expansion:Furniture-as-a-service penetration in London and Manchester rental markets is creating recurring revenue streams for modular seating and storage providers. Subscription models reduce upfront purchase barriers for mobile young professionals.
- UKCA Transition:Post-Brexit conformity assessment requirements for imported goods are creating regulatory moats for domestic manufacturers with established certification infrastructure. Trading standards enforcement is tightening market access for non-compliant imports.
- Southeast Premium Corridor:Commuter belt households in England's Southeast are concentrating demand for certified sustainable timber and traceable upholstery fabrics. This geography commands margin premiums for verified supply chains.
Market Restraints
- Timber Input Volatility:Solid oak and hardwood price swings compress margins for made-to-order specialists dependent on specific grain specifications. Baltic and Scandinavian supply routes face shipping cost instability.
- Foam Specification Lock-in:Ignition-resistant foam chemistry requirements under UK fire safety rules limit supplier flexibility. Domestic foam converters concentrate around three production sites, creating geographic supply risk.
- Flat-Pack Substitution:Engineered board furniture from automated European production lines competes on cost for first-time buyer segments. CNC-cut particleboard displaces solid wood in entry-level dining and bedroom categories.
Strategic Opportunities
- Scottish Highlands Underpenetration:Remote delivery infrastructure gaps in northern Scotland create first-mover potential for regional fulfillment partnerships. Local craft networks could anchor distributed production models.
- Textile Circularity Mandates:Extended producer responsibility frameworks for furniture textiles are accelerating demand for recyclable fabric systems. Design-for-disassembly upholstery creates compliance-aligned differentiation.
- AI-Assisted Customization:Machine learning configurators converging with CNC machining are enabling mass-customization at scale. Made-to-order lead times compress without sacrificing specification range.
Industry Challenges
- Upholstery Craft Pipeline Collapse:Traditional hand-tuition pathways through West Midlands workshops have contracted. Manufacturers must rebuild training infrastructure or automate core assembly stages.
- Dual Certification Burden:Parallel UKCA and residual CE marking requirements for Northern Ireland trade create compliance duplication. Testing timelines extend product development cycles.
- Legacy ERP Integration:Made-to-order specialists rely on fragmented scheduling systems that resist real-time inventory synchronization. Cloud migration capex demands strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Home Furniture Market |
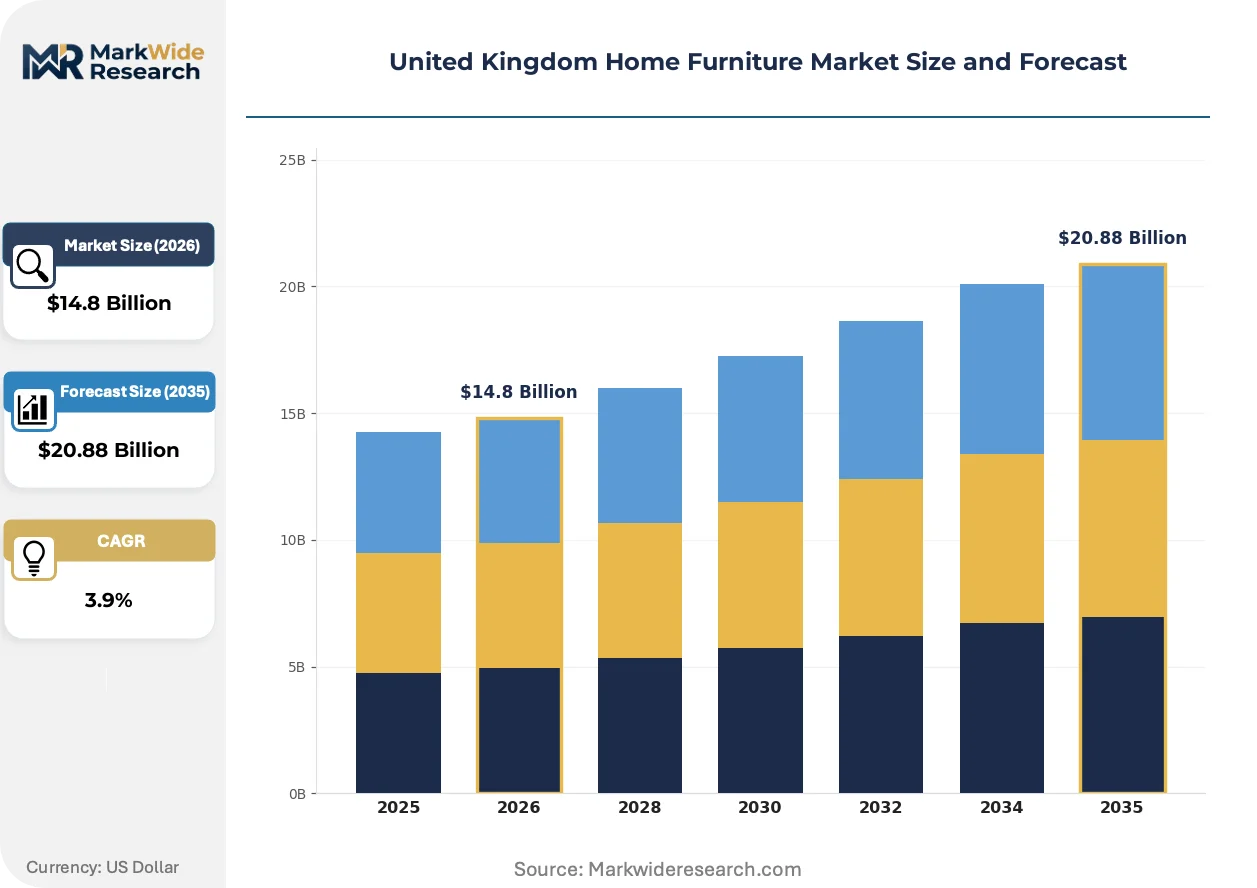
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.88 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Storage, Beds Material: Wood, Metal, Upholstered, Glass Style: Modern, Traditional, Rustic, Contemporary Sales Channel: Online, Retail Stores, Direct Sales, Showrooms |
| Companies Covered | IKEA, Dunelm Group plc, DFS Furniture plc, John Lewis & Partners, SCS Group plc, Furniture Village, Oak Furnitureland, Wren Kitchens, Wayfair UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Home Furniture Market Evolving Landscape
Digital configuration tools and regulatory compliance automation are bifurcating competitive advantage between capital-intensive scale players and craft-positioned specialists. The market is separating along capability lines that favor either automation depth or artisan credibility.
Mass-customization platforms leveraging parametric design software are bifurcating the seating category. Affluent suburban buyers in the Southeast commuter corridor are adopting these tools at accelerating rates. The technology is bifurcating market structure by compressing made-to-order lead times while raising capital barriers for traditional craft-positioned competitors.
Trading standards authorities are intensifying Furniture and Furnishings (Fire Safety) Regulations enforcement through expanded testing protocols for domestic upholstered products. Upholstery foam and fabric specification choices are narrowing as compliance documentation requirements expand. Premium segment manufacturers in England are responding by vertically integrating testing capabilities to accelerate certification cycles.
Rental household procurement patterns are fragmenting traditional retail channel concentration. Young professional tenants in Manchester and London are sourcing furniture through subscription platforms and peer-to-peer marketplaces rather than showroom visits. This behavioral shift is most visible in metropolitan rental corridors where mobility preferences override ownership accumulation.
United Kingdom Home Furniture Market Segmentation
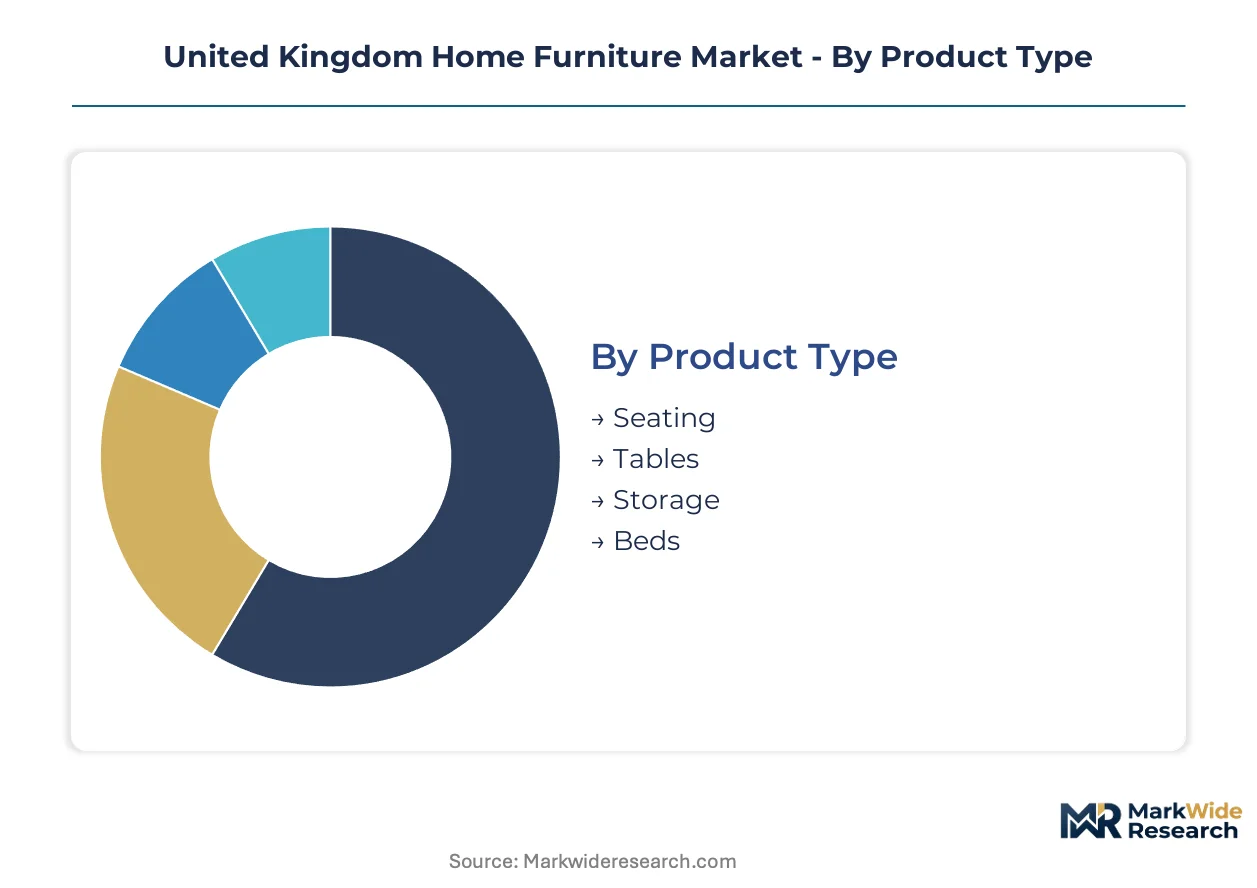
Segmentation in the UK home furniture market reveals how fire safety regulations, urban rental patterns, and craft scarcity reshape competitive boundaries. Each dimension exposes different pressure points for substitution, margin compression, and channel migration.
Product Type:
Flat-pack imports and furniture-as-a-service models exert the strongest substitution pressure on volume categories, while premium craft-positioned segments defend through specification complexity.
- Seating:Upholstered armchairs and sofas incorporate timber frames, webbing suspension, and ignition-resistant foam padding. Demand concentrates in London rental corridors where subscription providers supply modular configurations to mobile professionals. DFS Furniture plc trains upholstery craftspeople through in-house academies to offset West Midlands labor shortages.
- Beds:Divan bases and mattress platforms combine sprung slat systems with headboard upholstery. Southeast commuter belt households drive premium demand for certified sustainable timber and traceable fabric provenance. Oak Furnitureland anchors its proposition around solid-wood specialization against engineered board competition.
- Tables:Dining and occasional surfaces span solid timber, veneered board, and metal-frame constructions.
- Storage:Freestanding cabinets and shelving units face intense flat-pack substitution from automated European production lines.
Seating retains volume leadership; beds hold the steepest expansion curve through premium corridor demand concentration.
Material:
Cost tier stratification separates commodity inputs from specification-locked materials where compliance and craft scarcity create defensive moats.
- Wood:Solid oak and hardwood specifications face Baltic supply route volatility and grain-matching complexity for made-to-order production. West Midlands manufacturers absorb margin compression from timber price swings while defending craft credibility against particleboard alternatives.
- Upholstered:Fabric-covered frames require UK Furniture and Furnishings (Fire Safety) Regulations compliance through certified foam and treated textiles. Dunelm Group plc leverages vertically integrated textile sourcing to control margin pools in soft furnishings.
- Metal:Powder-coated steel and aluminum frames serve industrial and minimalist aesthetic segments.
- Glass:Tempered surfaces accent contemporary styling with limited structural application.
Wood commands the widest application footprint; upholstered materials climb the fastest through premium specification premiums.
Style:
Customer type fragmentation between metropolitan renters and suburban owner-occupiers drives divergent styling preferences across geography.
- Modern:Clean lines and minimal ornamentation align with London and Manchester rental household preferences. Young professionals source through online configurators and subscription platforms rather than showroom visits.
- Contemporary:Evolving aesthetics bridge transitional spaces between traditional and modern sensibilities. Southeast commuter belt households adopt these specifications for family homes requiring durability and design flexibility.
- Traditional:Ornate detailing and period references serve established suburban owner-occupiers.
- Rustic:Distressed finishes and farmhouse references appeal to regional taste clusters.
Modern styling captures rental corridor volume; contemporary specifications gain share fastest through suburban household upgrading.
Sales Channel:
Supply concentration in digital infrastructure and showroom real estate determines channel economics and customer acquisition costs.
- Online:Digital configurators and AI-assisted customization tools compress made-to-order lead times. Mass-customization platforms expand fastest among affluent Southeast buyers adopting parametric design software for seating specification.
- Showrooms:Physical display retains decisive influence for high-consideration purchases of beds and dining sets. DFS Furniture plc sustains its national store network while navigating labor constraints through experiential merchandising.
- Retail Stores:Multi-brand furniture outlets aggregate comparison shopping for entry-level segments.
- Direct Sales:Manufacturer-owned channels bypass wholesale margins for made-to-order specialists.
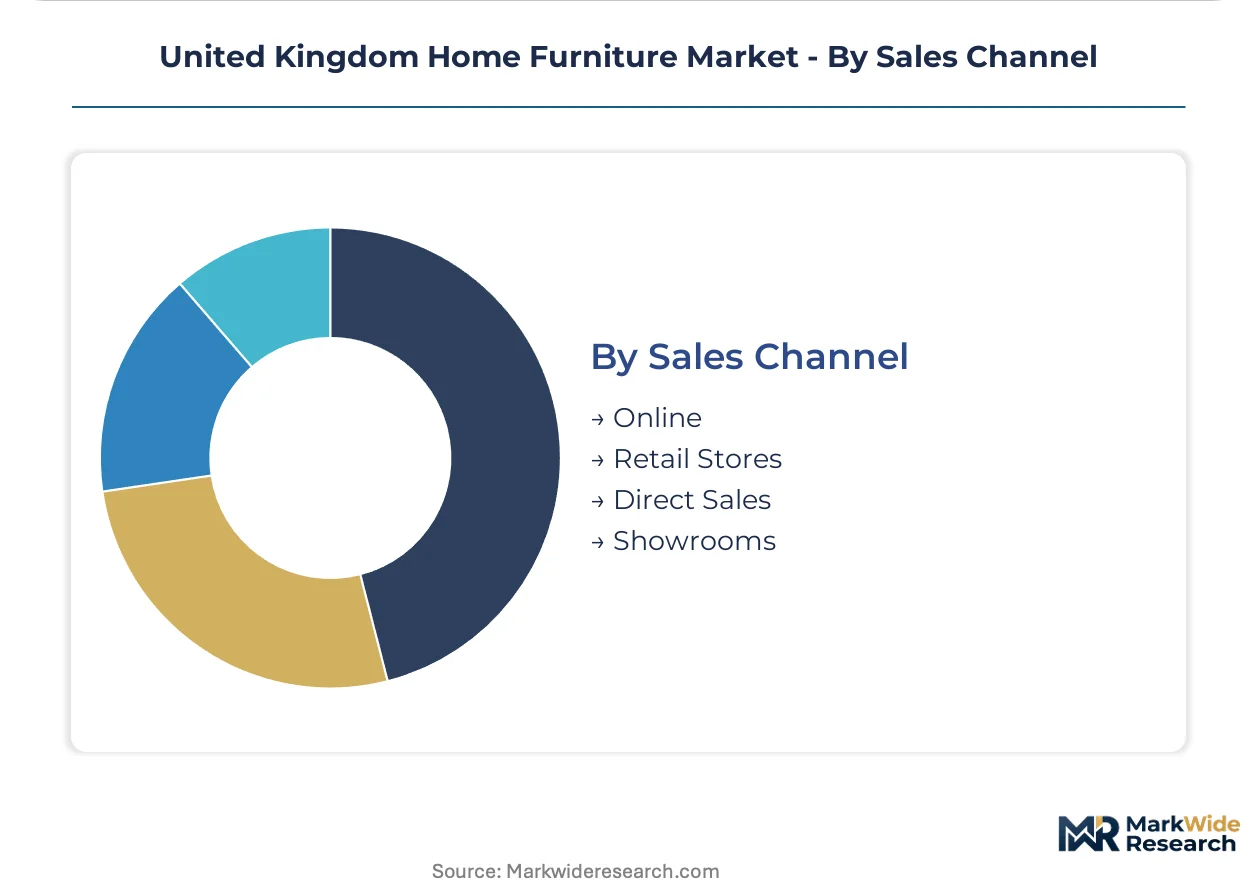
Showrooms retain volume leadership through high-consideration conversion; online channels post the steepest expansion curve through rental market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK's Furniture and Furnishings (Fire Safety) Regulations, enforced by local trading standards authorities, anchor regulatory compliance requirements across England, Scotland, Wales, and Northern Ireland. Trading standards bodies in each jurisdiction administer testing protocols and market surveillance.
London and Southeast England
Affluent commuter belt households concentrate premium demand for certified sustainable timber and traceable upholstery fabrics. The Furniture and Furnishings (Fire Safety) Regulations mandate ignition-resistant foam specifications that reshape supplier selection for Southeast manufacturers. Guildford and Reading host upholstery specialists vertically integrating testing capabilities to accelerate certification cycles.
West Midlands
Traditional upholstery craft workshops face acute skilled labor shortages that compress production capacity for made-to-order seating. The West Midlands Combined Authority coordinates workforce development initiatives targeting furniture manufacturing apprenticeships. Birmingham and Coventry production clusters absorb margin pressure while defending craft credibility against automated European competitors.
North England
Manchester's expanding rental household base accelerates furniture-as-a-service adoption among mobile young professionals. Greater Manchester Combined Authority supports circular economy pilots for furniture reuse and remanufacturing. Leeds and Sheffield distribution hubs enable rapid fulfillment for subscription-based seating providers.
Scotland
Remote delivery infrastructure gaps in the Scottish Highlands create underpenetrated territory for regional fulfillment partnerships. Scottish Government procurement guidelines prioritize sustainable timber certification for public sector furniture contracts. Glasgow and Edinburgh anchor distributed production models leveraging local craft networks.
Wales
Timber processing capacity in Welsh border regions supplies solid-wood feedstock for domestic manufacturers. Natural Resources Wales administers forest certification schemes that condition sustainable sourcing claims. Newport and Cardiff host emerging upholstery specialists targeting UKCA compliance for export to England.
United Kingdom Home Furniture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national store networks and vertically controlled supply chains commanding disproportionate margin capture. The middle tier fragments between craft-positioned solid-wood specialists and flat-pack assemblers competing on cost. Three archetypes dominate: vertically integrated retailers controlling textile sourcing, made-to-order craft specialists defending specification complexity, and digital-native platforms leveraging AI-assisted configuration. Consolidation pressure intensifies through regulatory compliance burdens and upholstery craft scarcity, while automation investments separate capital-intensive scale players from labor-dependent workshops.
Among UK-based retailers, Dunelm Group plc, DFS Furniture plc, and Oak Furnitureland occupy distinct competitive positions. Dunelm exemplifies vertically integrated textile control through captive sourcing infrastructure. DFS represents the national showroom network archetype sustaining experiential merchandising despite labor constraints. Oak Furnitureland anchors the solid-wood specialization vector, competing against engineered board alternatives through craft credibility and made-to-order flexibility.
| Leading Market Players |
|---|
| IKEA |
| Dunelm Group plc |
| DFS Furniture plc |
| John Lewis & Partners |
| SCS Group plc |
| Furniture Village |
| Oak Furnitureland |
| Wren Kitchens |
| Wayfair UK |
| Others |
Value Network & Pricing Analysis
UKCA marking requirements and Furniture and Furnishings (Fire Safety) Regulations compliance simultaneously gate supplier qualification and enable price differentiation through certification tiering. Trading standards enforcement creates a dual-track market where documented foam and fabric provenance commands measurable premiums from Southeast commuter belt buyers.
Pricing Analysis
Geographic price spreads between London rental corridors and Scottish Highlands delivery zones exceed transport cost differentials alone. Three-tier pricing structure across premium certified-sustainable, standard compliant-grade, and economy flat-pack levels dominates category economics. Pricing pressure stems from Baltic timber input volatility compressing made-to-order margins. First-time buyers in entry-level segments exhibit highest price sensitivity; Southeast owner-occupiers demonstrate lowest elasticity for traceable provenance.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time foam and fabric sourcing for subscription providers versus strategic timber stockpiling among solid-wood specialists. Supply concentrates in Baltic states for oak feedstock, China for engineered board components, and domestic West Midlands for upholstery assembly. Raw material dependencies span ignition-resistant foam chemistry, certified timber grades, and traceable textile origins. Single-source vulnerability concentrates around three domestic foam converter sites. Distribution runs through national showroom networks for high-consideration purchases alongside direct-to-consumer digital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture-as-a-service platform economics are reaching an inflection as subscription APIs and modular configuration standards enable interoperability between rental housing portals and inventory systems. This ecosystem shift restructures competitive moats from asset ownership to data-network density.
For Market Incumbents: Fortify upholstery craft pipelines through captive training academies before automation investments mature. Deepen backward integration into textile testing capabilities to compress UKCA certification cycles. Defend against flat-pack substitution by anchoring specification complexity in solid-wood grain matching and custom finishing.
For New Entrants and Emerging Players: Remote delivery infrastructure gaps in Scottish Highlands and northern England represent underexploited service-layer territory where national networks struggle with unit economics. Target subscription fulfillment partnerships with Manchester and London rental housing platforms as the most penetrable entry vector. Lead with AI-assisted configuration tools that compress made-to-order lead times without capital-intensive showroom footprints.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mass-customization platform development as CNC machining and parametric design software become table stakes. Long-term viability favors acquisition targets combining established UKCA compliance infrastructure with modular product architectures adaptable to circular economy mandates. Watch textile circularity framework implementation timelines as the critical inflection signal for asset valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Infrastructure Investment | Accelerates market access velocity while creating regulatory moats against non-compliant imports. |
| AI-Assisted Customization Platform Launch | Compresses made-to-order lead times for Southeast commuter belt buyers adopting parametric design tools. |
| Textile Circularity System Development | Aligns product architectures with extended producer responsibility frameworks before mandate enforcement. |
| Regional Fulfillment Partnership Expansion | Captures first-mover advantage in Scottish Highlands and northern England remote delivery corridors. |
| Upholstery Craft Academy Establishment | Rebuilds West Midlands labor pipeline while defending craft credibility against automated European competitors. |
Research Methodology
Desk research of trade association publications, customs import records, and trading standards enforcement reports preceded structured interviews with upholstery production managers, furniture retail category buyers, foam converter technical directors, and rental housing platform procurement leads. Primary fieldwork across West Midlands workshops and Southeast showrooms was cross-validated against secondary data from British Furniture Manufacturers association outputs and Office for National Statistics household expenditure surveys. Bottom-up unit economics modeling was triangulated with top-down market sizing from production capacity assessments.
Variance decomposition across product type, material grade, sales channel, and geographic demand cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Forecast inputs incorporated UKCA transition timelines, timber price volatility indices, and rental household formation rates across metropolitan corridors.
Underlying assumptions cover regulatory enforcement continuity, Baltic supply route stability, and craft training pipeline recovery, with deviation risk concentrated in foam chemistry specification amendments and extended producer responsibility acceleration. Practitioners should keep alternative scenarios live as trading standards testing protocol evolution and circular economy mandate timing unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Portering Chair Market
Furniture
Europe Sustainable Mattress Market
Furniture
Italy Office Furniture Market
Furniture
Germany Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
US School Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
UAE Home Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Rattan Furniture Market
Furniture
Kids Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
North America School Furniture Market
Furniture
HORECA Furniture Market
Furniture
Europe Multifunctional Furniture Market