
 High Density Fiberboard (HDF) Market | 2026-2036
High Density Fiberboard (HDF) Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Fiberboard (HDF) Market Foresight
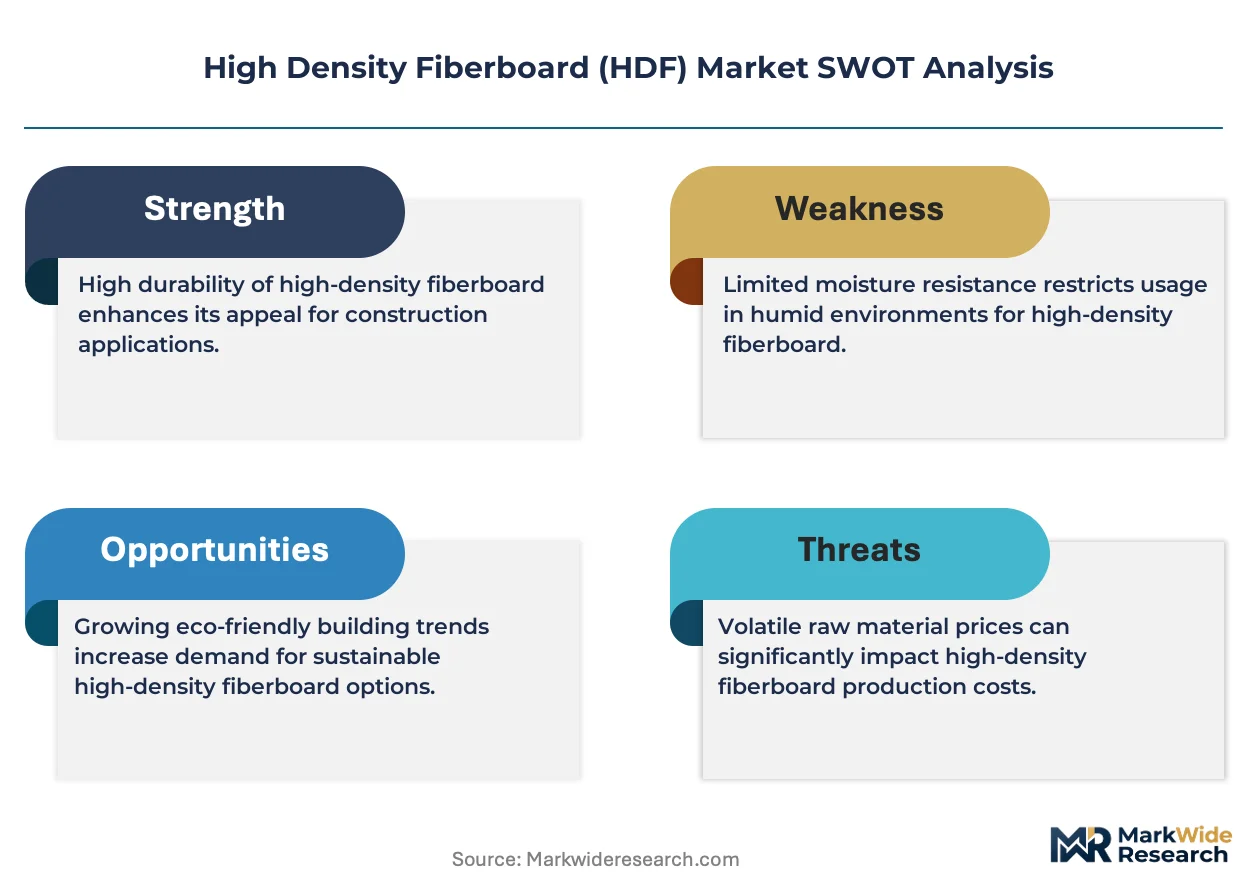
Residential flooring installers is bifurcating from commercial construction buyers as laminate flooring replacement cycles compress and homeowners prioritize moisture-resistant substrates. Kronospan leverages its captive resin production and European mill network to anchor supply continuity for large-format retailers. Egger Group sustains R&D intensity in low-formaldehyde binders that meet evolving indoor air quality protocols. Greenpanel Industries Limited dominates South Asian distribution through vertically integrated pulp-to-panel operations near Gujarat's timber processing corridor.
High Density Fiberboard is an engineered wood product manufactured from compressed wood fibers bonded with synthetic resin under heat and pressure, typically achieving densities above 800 kg per cubic meter for structural rigidity. Standard HDF serves as the dominant substrate for laminate flooring cores due to its dimensional stability and machinability, while water-resistant HDF commands expanding share in kitchen cabinetry and bath applications where moisture exposure exceeds nominal thresholds. Acoustic HDF occupies a specialized niche in commercial interiors where sound attenuation ratings drive specification, though its premium positioning limits volume penetration relative to standard grades.
EPA TSCA Title VI formaldehyde emissions standards govern panel products sold in the United States, compelling manufacturers to certify compliance through third-party testing or forfeit market access. The EU Green Deal's cascading carbon footprint disclosure requirements and ECHA REACH restrictions on phenol-formaldehyde resins are reshaping binder chemistry investments across European production bases. Stakeholders must monitor evolving certification thresholds in California's CARB phase 3 trajectory and Germany's Blue Angel eco-label updates, as these frameworks increasingly determine specification eligibility in premium residential and healthcare construction channels.
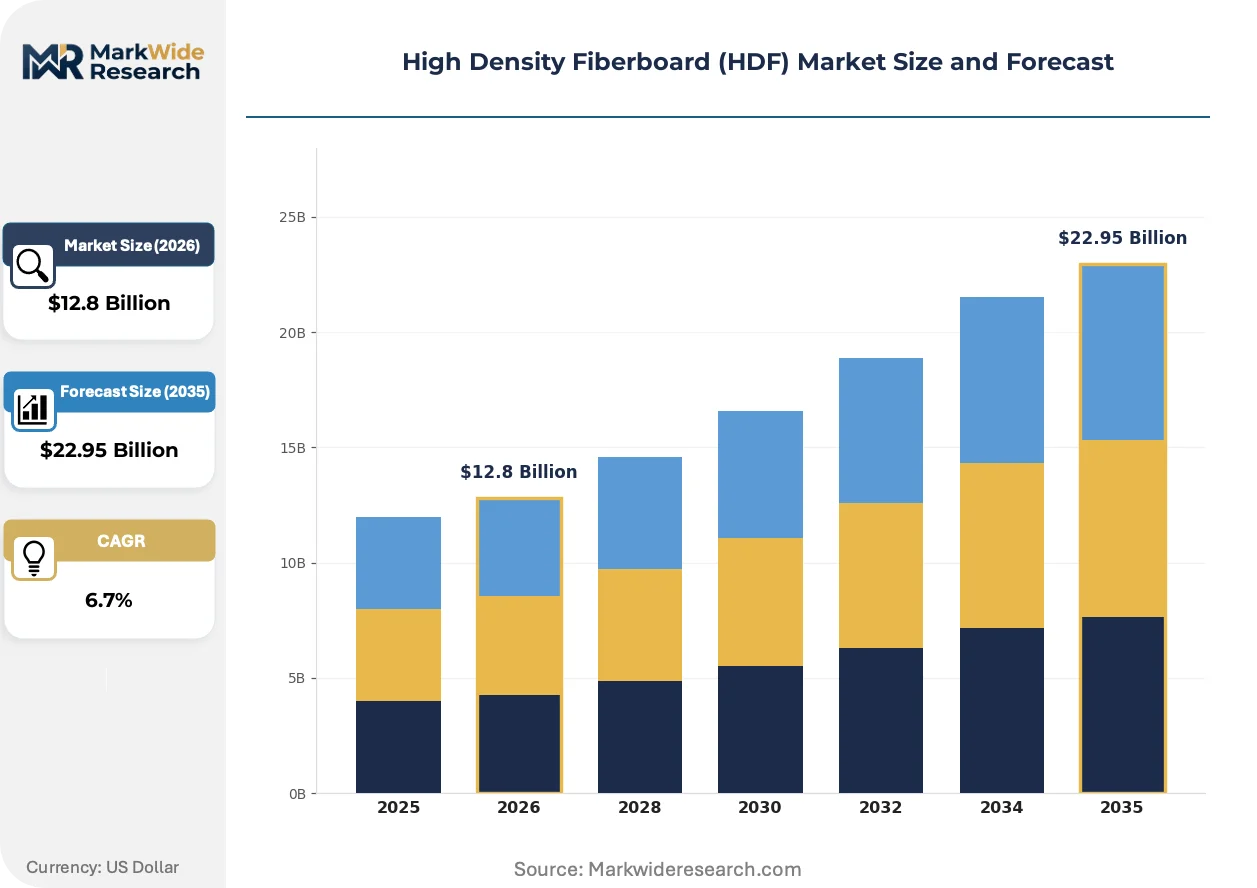
Market Dynamics
Residential flooring replacement cycles are compressing as moisture-resistant substrate specifications tighten, bifurcating procurement between certified low-emission panels for premium residential channels and standard grades for commercial construction. This specification divergence is concentrating volume with vertically integrated mills capable of resin-to-panel traceability.
Growth Catalysts
- EU Green Deal embodied carbon rules:Procurement is redirecting toward EPD-certified panels across German furniture manufacturing clusters, locking in premium positioning for compliant suppliers.
- Laminate flooring substrate upgrading:Residential installers specify water-resistant HDF cores for kitchen and bath renovations, displacing standard particleboard in moisture-exposed zones.
- Gujarat timber processing corridor:Vertically integrated pulp-to-panel operations near Indian ports capture export demand for cost-competitive standard grades.
Market Restraints
- Phenol-formaldehyde resin cost volatility:Petrochemical feedstock fluctuations compress margins for non-integrated producers dependent on spot resin markets.
- European mill concentration:Supply risk concentrates in Bielefeld-Herford manufacturing belt where three integrated groups control majority capacity.
- Oriented strand board substitution:OSB pricing pressure in North American construction sheeting limits HDF penetration in structural subfloor applications.
Strategic Opportunities
- India residential flooring expansion:Underpenetrated laminate installation rates in tier-two cities create white space for moisture-resistant grade distribution.
- Acoustic HDF specification:Commercial interior projects in healthcare and education verticals adopt sound-attenuation rated panels for open-plan environments.
- Blue Angel eco-label alignment:German federal procurement mandates for low-emission materials open specification channels in public construction.
Industry Challenges
- EPA TSCA Title VI certification timelines:Third-party testing bottlenecks delay market access for new product formulations.
- CARB phase 3 threshold uncertainty:Evolving California emission standards force dual-track R&D investment without clarity on final thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Fiberboard (HDF) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard HDF, Water-resistant HDF, Acoustic HDF, Fire-rated HDF End Use Industry: Furniture, Flooring, Construction, Automotive Thickness: 6mm, 8mm, 12mm, 18mm Surface Finish: Melamine Faced, Veneer Faced, Laminated, Plain |
| Companies Covered | Egger Group, Masonite International Corporation, Arauco, Masisa S.A., Finsa, Kronospan, Greenpanel Industries Limited, Duratex S.A., Swiss Krono Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Fiberboard (HDF) Market Shifts & Advancements
Digital printing surface technologies and bio-based binder chemistries are fragmenting traditional grade hierarchies, while embodied carbon disclosure mandates reshape specification workflows across construction procurement channels.
Continuous pressing technology with in-line moisture profiling is fragmenting the cost structure advantage of traditional multi-opening presses. Flooring manufacturers in Poland and the Czech Republic adopt these lines for just-in-time laminate core production. The capital efficiency gap between continuous and batch processing is compressing viable scale thresholds for new market entrants.
REACH restrictions on phenol-formaldehyde resins are accelerating bio-based binder pilot programs at European production bases. ECHA's sunset date proposals for high-emission chemistries force dual-track formulation development. German and Austrian mills with captive resin research facilities are consolidating specification relationships with healthcare and childcare construction channels.
Specification decisions are migrating from general contractors to flooring installation contractors as laminate replacement cycles compress and warranty liability concentrates at the substrate level. Large-format retail channels in France and Spain now demand batch-level emission documentation direct from mills. This disintermediation is fragmenting traditional distributor relationships and compressing margin pools for non-integrated intermediaries.
High Density Fiberboard (HDF) Market Segmentation
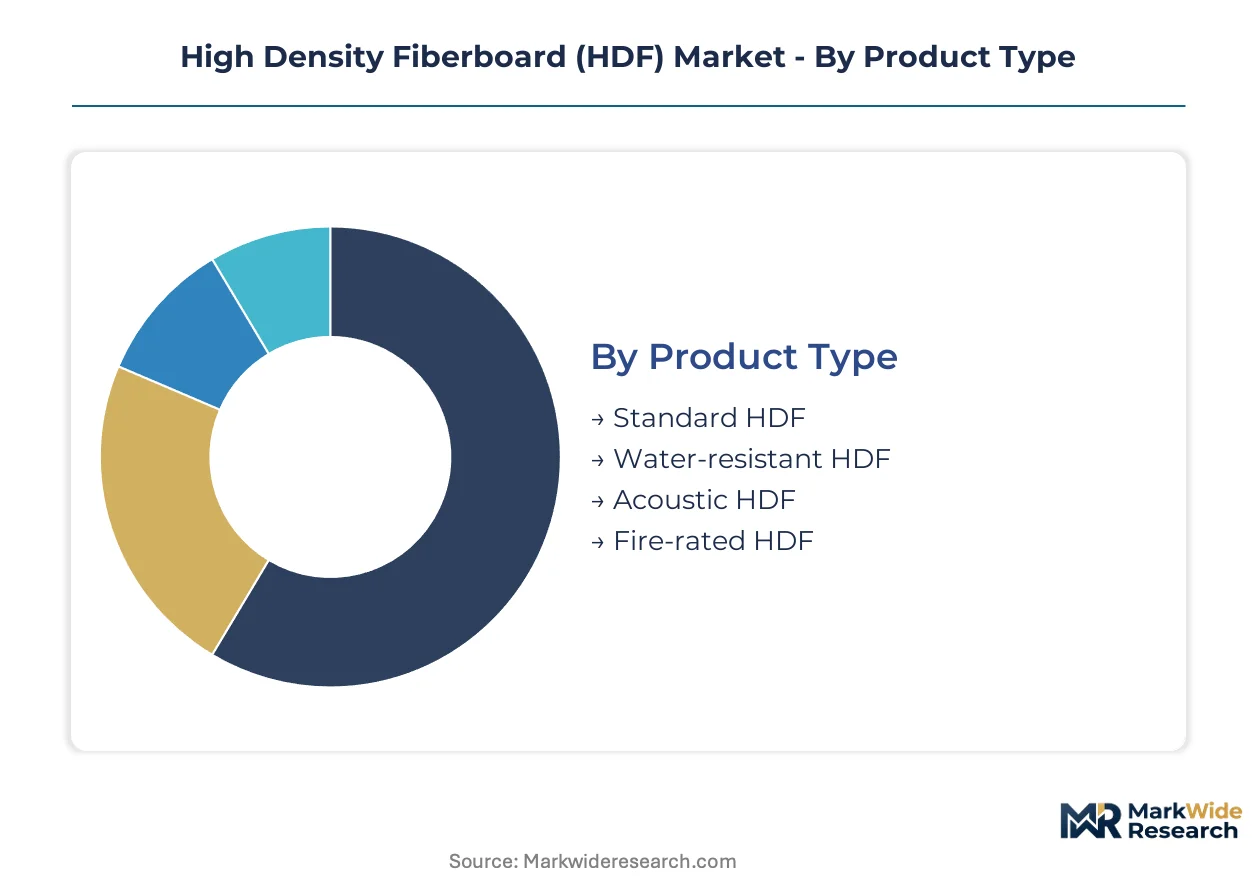
HDF grade specifications determine channel access and pricing power. Water-resistant and acoustic variants command specification premiums in moisture-exposed and sound-sensitive applications, while standard grades flow through high-volume retail distribution.
Product Type:
Channel mix bifurcates between specification-driven premium grades and commoditized standard volumes. Water-resistant and acoustic variants penetrate through contractor-direct and project-specification channels, while standard HDF dominates mass retail and distributor networks.
- Standard HDF:Compressed wood fiber substrate bonded with urea-formaldehyde resin achieves densities above 800 kg per cubic meter for dimensional stability. Flooring manufacturers in Poland and the Czech Republic source this grade through just-in-time continuous press lines for laminate core production. Standard HDF dominates installed base. Water-resistant HDF is where expansion concentrates.
- Water-resistant HDF:Modified resin systems and wax additives elevate moisture resistance thresholds for kitchen cabinetry and bath applications. German furniture manufacturing clusters around Bielefeld and Herford specify this grade for residential renovation projects where warranty liability concentrates at the substrate level. Water-resistant HDF gains share fastest as laminate replacement cycles compress and homeowners prioritize moisture-resistant substrates.
- Acoustic HDF:Engineered density gradients and porous core structures attenuate sound transmission in commercial interiors. Healthcare and education verticals in France and Spain adopt this grade for open-plan environments where sound ratings drive specification.
- Fire-rated HDF:Intumescent additives and mineral loading achieve Class A or B flame spread ratings for commercial code compliance. Airport terminals and hospitality projects specify this grade through architect-led procurement channels.
Standard HDF anchors volume throughput. Water-resistant HDF captures margin expansion as moisture specifications tighten.
End Use Industry:
Application mix shifts with construction cycle positioning and replacement demand timing. Residential flooring and furniture manufacturing concentrate procurement in economic expansion phases, while construction and automotive applications track infrastructure and vehicle production cycles.
- Furniture:Cabinetry, shelving, and casegood substrates demand machinability and screw-holding strength. German manufacturers specify low-emission panels certified under Blue Angel eco-label protocols for federal procurement eligibility.
- Flooring:Laminate flooring cores require dimensional stability across humidity cycles. Residential installers now account for rising volume offtake as large-format retail channels in France and Spain demand batch-level emission documentation direct from mills.
- Construction:Wall paneling, door cores, and millwork applications span commercial and residential verticals. EU Green Deal embodied carbon reporting rules redirect procurement toward EPD-certified panels across German construction clusters.
- Automotive:Headliners, trunk liners, and interior trim panels utilize lightweight fiberboard for acoustic and thermal management. Tier-one suppliers specify this grade through OEM-directed material approval processes.
Flooring commands the largest addressable volume. Furniture manufacturing delivers the steepest specification premium capture.
Thickness:
Thickness selection correlates with structural load requirements and surface finish compatibility. Thinner panels reduce material cost and weight; thicker panels improve screw retention and edge stability.
- 6mm:Lightweight substrate for non-structural applications including drawer bottoms and cabinet backs. Cost-sensitive furniture manufacturers in South Asia specify this grade for export-oriented production.
- 8mm:Dominant laminate flooring core thickness balancing material efficiency with installation durability. Retail flooring channels standardize on this specification for residential replacement demand.
- 12mm:Enhanced structural rigidity for commercial flooring and heavy-use furniture applications. German contract furniture manufacturers specify this grade for high-traffic office installations.
- 18mm:Maximum load-bearing capacity for shelving, work surfaces, and structural millwork. Kitchen cabinetry and laboratory furniture applications drive specification through durability requirements.
8mm thickness anchors laminate flooring volume. 12mm specification climbs fastest in commercial furniture channels.
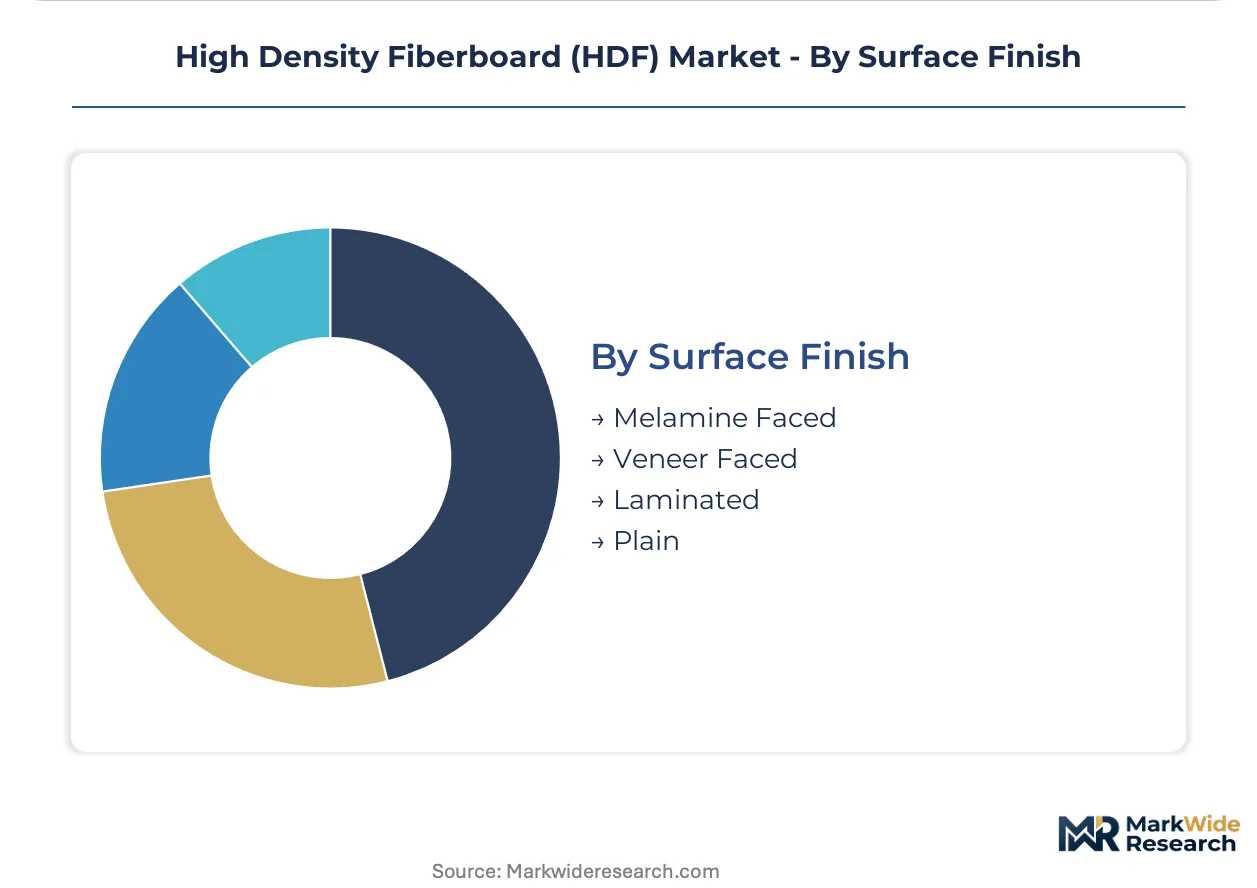
Surface Finish:
Finish type determines downstream processing steps and end-use aesthetic requirements. Pre-finished panels reduce manufacturing steps for fabricators; raw substrates preserve flexibility for custom finishing.
- Melamine Faced:Thermally fused decorative paper overlay provides scratch and moisture resistance for furniture and cabinetry. Continuous press lines in Poland integrate in-line melamine lamination for just-in-time delivery to flooring manufacturers.
- Veneer Faced:Natural wood veneer overlay delivers premium aesthetic for architectural millwork and high-end furniture. German and Austrian mills consolidate specification relationships with healthcare and childcare construction channels through low-emission veneer adhesive systems.
- Laminated:High-pressure laminate or direct-printed surface for flooring and countertop applications. Digital printing surface technologies fragment traditional grade hierarchies by enabling short-run customization.
- Plain:Unfinished substrate for on-site finishing or further processing by fabricators. Distributor networks stock this grade for custom cabinet shops and millwork contractors.
Melamine facing dominates volume throughput. Veneer facing secures specification in premium architectural channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mills export water-resistant grades to French and Spanish flooring channels, while Indian producers ship standard substrates to Middle East construction markets. Trade corridors concentrate premium specification flows toward EU furniture clusters and cost-grade volumes toward Asian emerging markets.
Germany
Furniture manufacturers around Bielefeld and Herford specify low-emission panels for federal procurement eligibility under Blue Angel eco-label protocols. EU Green Deal embodied carbon disclosure rules redirect construction procurement toward EPD-certified suppliers. The North Rhine-Westphalia manufacturing belt concentrates integrated resin-to-panel capacity serving premium residential channels.
France
Large-format retail channels demand batch-level emission documentation direct from mills, disintermediating traditional distributors. REACH restrictions on phenol-formaldehyde resins accelerate bio-based binder pilot programs at domestic production bases. The Paris Basin construction corridor adopts acoustic HDF specifications for healthcare and education verticals.
India
Tier-two cities generate underpenetrated laminate installation demand as residential flooring replacement accelerates. BIS certification requirements govern panel product quality standards for domestic market access. Vertically integrated pulp-to-panel operations near Gujarat's timber processing corridor capture export demand for cost-competitive standard grades.
United States
EPA TSCA Title VI formaldehyde emissions standards compel third-party certification for market access, creating testing bottlenecks for new formulations. Laminate flooring installers in the Southeast and Southwest prioritize moisture-resistant substrates for kitchen and bath renovations. California's CARB phase 3 trajectory forces dual-track R&D investment without clarity on final thresholds.
Poland
Continuous pressing technology with in-line moisture profiling enables just-in-time laminate core production for flooring manufacturers. EU Green Deal procurement rules redirect specification toward EPD-certified panels for public construction projects. The Silesian manufacturing zone adopts these press lines to serve German and Austrian export channels.
High Density Fiberboard (HDF) Market Competitive Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The vendor base concentrates around integrated European groups controlling captive resin production, while Asian specialists exploit cost-position advantages in standard-grade exports. Three archetypes dominate: vertically integrated mill-and-resin operators, regional distribution-focused fabricators, and pulp-to-panel specialists in timber-rich geographies. Competitive moves center on continuous press technology adoption and backward integration into resin chemistry.
Within the integrated European tier, Kronospan and Egger Group exemplify the resin-to-panel traceability model that secures specification relationships with large-format retailers. Greenpanel Industries Limited occupies a position among Asian pulp-to-panel specialists leveraging proximity to Gujarat's timber corridor. Swiss Krono Group represents the mid-cap integrated archetype serving Central European furniture manufacturing clusters with low-emission certified production.
| Leading Market Players |
|---|
| Egger Group |
| Masonite International Corporation |
| Arauco |
| Masisa S.A. |
| Finsa |
| Kronospan |
| Greenpanel Industries Limited |
| Duratex S.A. |
| Swiss Krono Group |
| Others |
Supply & Pricing Matrix
Phenol-formaldehyde resin substitution by bio-based binders simultaneously shifts production geography toward German and Austrian mills with captive research facilities and compresses pricing premiums for conventional urea-formaldehyde grades. This chemistry transition concentrates supply-side investment in integrated European operations while fragmenting cost structures for spot-market resin buyers.
Pricing Analysis
Continuous press technology pricing gaps separate legacy multi-opening press outputs from next-generation in-line moisture profiling systems, with Polish and Czech flooring manufacturers capturing intermediate positioning. Three-tier pricing structure across water-resistant premium, standard certified, and economy spot grades reflects certification level and resin chemistry differentiation. Pricing pressure stems from petrochemical feedstock volatility squeezing non-integrated producers. Large-format retail channels exhibit lowest price sensitivity through direct mill relationships, while distributor-dependent fabricators face margin compression.
Supply Chain Analysis
Baltic Sea port congestion chokepoints constrain resin import flows to Bielefeld-Herford manufacturing clusters, elevating logistics risk for German furniture producers. Supply concentrates in Germany, Poland, and India, with raw material dependencies on wood fiber pulp, formaldehyde resins, and wax additives. Single-source vulnerability concentrates in phenol-formaldehyde resin supply from petrochemical networks. Distribution runs through vertically integrated mill-direct channels for premium grades and fragmented distributor networks for standard volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as specification decisions migrate from general contractors to flooring installation contractors, creating niche entry points around moisture-resistant certification and acoustic performance tiers.
For Market Incumbents: Fortify specification relationships with large-format retailers through batch-level emission documentation and captive resin traceability. Backward integration into bio-based binder chemistry defends margin position against REACH restriction timelines. Blue Angel eco-label certification investment locks in German federal procurement channels before mandate expansion. For New Entrants and Emerging Players: Lead with acoustic HDF specification for healthcare and education verticals in France and Spain, where sound-attenuation ratings drive procurement and incumbent coverage remains thin. India's tier-two cities offer penetrable white space for moisture-resistant grade distribution through contractor-direct models. Partner with continuous press technology providers for capital-efficient scale entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European mill-and-resin operators facing succession planning and ESG compliance capex demands. Long-term viability centers on backward integration depth and certification portfolio breadth. Watch EU Green Deal embodied carbon threshold announcements as inflection indicators for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | ECHA REACH sunset dates force dual-track formulation development at German and Austrian production bases. |
| Continuous Press Technology Adoption | Polish and Czech manufacturers compress viable scale thresholds through in-line moisture profiling systems. |
| Blue Angel Eco-Label Certification | German federal procurement mandates open specification channels in public construction and healthcare verticals. |
| Direct Mill-to-Retailer Distribution | Large-format channels in France and Spain disintermediate traditional distributors through batch-level documentation demands. |
| Acoustic Grade R&D Investment | Healthcare and education construction in Paris Basin drives specification for sound-attenuation rated panels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EU EPD certification registries, and SEC filings from listed building materials groups. Primary interviews incorporated plant managers at integrated European mills, procurement leads at French flooring retailers, resin chemistry R&D directors, and distribution channel partners across German furniture manufacturing clusters. Bottom-up volume estimates from grade-level production data triangulate against top-down construction spending and laminate flooring replacement cycle analysis.
Segmentation dimensions modeled span product type, end-use industry, thickness specification, surface finish, and regional production hub clustering across the analysis window. CAGRs derive from regression analysis of historical volume trajectories against macro construction indicators and regulatory compliance cost curves. Forecast inputs incorporate embodied carbon disclosure mandate adoption timelines and continuous press technology diffusion rates through Central European manufacturing bases.
Forecasts assume regulatory continuity in EU Green Deal implementation and EPA TSCA Title VI certification frameworks; material policy shifts in CARB phase 3 thresholds or ECHA REACH sunset dates would require re-modeling. Practitioners should keep alternative scenarios live as bio-based binder scale-up economics and Baltic logistics capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Taiwan Home Furniture Market
Furniture
Back Mount Frames Market
Furniture
Spain Furniture Market
Furniture
India Luxury Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Ergonomic Chair Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
North America Smart Furniture Market
Furniture
India Home Furniture Market
Furniture
Japan Home Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Luxury Furniture Market
Furniture
Exam Tables Market
Furniture
Japan Furniture Market
Furniture
Piano Stools Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market