
 UAE Luxury Furniture Market | 2026-2036
UAE Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Luxury Furniture Market Analytics
The gap between artisan-crafted luxury furniture and mass-market alternatives is consolidating around material provenance and bespoke design services. Poltrona Frau leverages its Italian leatherworking heritage to anchor ultra-premium positioning in Abu Dhabi villas. Marina Home Interiors competes through controlled retail showrooms across Dubai's premium malls. Natuzzi Italia differentiates via its modular sofa systems tailored to regional spatial preferences.
Luxury furniture comprises high-end movable fixtures engineered from premium hardwoods, full-grain leathers, and precision-machined metals, typically involving hand-finishing processes that exceed standard commercial specifications. These pieces serve both functional and status-signaling purposes in residential estates, hospitality venues, and executive commercial environments. The wood and leather material segments command the deepest margin pools due to raw material scarcity and craftsmanship premiums. Sofas dominate product type revenue given their centrality to spatial design, while the hotels end user category is expanding fastest as Dubai and Abu Dhabi add luxury hospitality inventory.
MOHAP product safety standards and Dubai Municipality's building code amendments govern flammability, material emissions, and structural integrity for imported furnishings. The UAE's PLI scheme for domestic manufacturing is reshaping local production incentives and import substitution dynamics. Stakeholders must monitor how evolving Gulf Cooperation Council customs harmonization affects landed costs for European and Asian suppliers.
Market Dynamics
MOHAP's tightened flammability and emissions standards for imported furnishings are compressing supplier margins while accelerating domestic certification investments among distributors serving Dubai's villa developments.
Growth Catalysts
- Dubai's Palm Jumeirah villa pipeline:Waterfront residential developments are specifying Italian leather and precision-machined hardwood fixtures, creating pull-through demand for full-service interior fit-out contracts.
- Abu Dhabi luxury hospitality licensing:New hotel developments must source furnishings meeting Dubai Municipality's amended building codes, which mandate enhanced material traceability documentation.
- Modular sofa customization:Regional spatial preferences for expansive majlis-style seating configurations are driving demand for reconfigurable leather systems with hand-finished joinery.
Market Restraints
- European leather supply concentration:Full-grain hide sourcing clusters in Italian tanneries, exposing UAE distributors to euro-denominated input volatility and extended lead times.
- MOHAP certification timelines:Product safety testing for flammability and VOC emissions adds six to twelve weeks to import clearance, compressing project delivery windows.
- Skilled upholstery labor scarcity:Artisan hand-finishing capacity in the Emirates remains insufficient for bespoke villa commissioning volumes, forcing reliance on Italian and Portuguese workshops.
Strategic Opportunities
- Abu Dhabi villa underpenetration:Saadiyat Island and Yas Island residential developments show lower bespoke furniture saturation than Dubai equivalents, presenting white-space for design-led entry.
- Domestic PLI manufacturing incentives:The UAE's production-linked incentive scheme for domestic manufacturing is reshaping local assembly economics for metal frame and wood component production.
- Direct-to-developer digital platforms:Virtual showroom technology enabling real-time material customization is bypassing traditional mall-based retail intermediaries for commercial interior projects.
Industry Challenges
- Master upholsterer talent pipeline:Traditional hand-stitching and leatherworking expertise requires multi-year apprenticeship cycles that regional vocational programs have not scaled to match demand.
- Legacy inventory harmonization:Showrooms holding pre-2023 stock face write-down pressure as MOHAP's amended emission standards render non-compliant pieces unsellable for new construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Luxury Furniture Market |
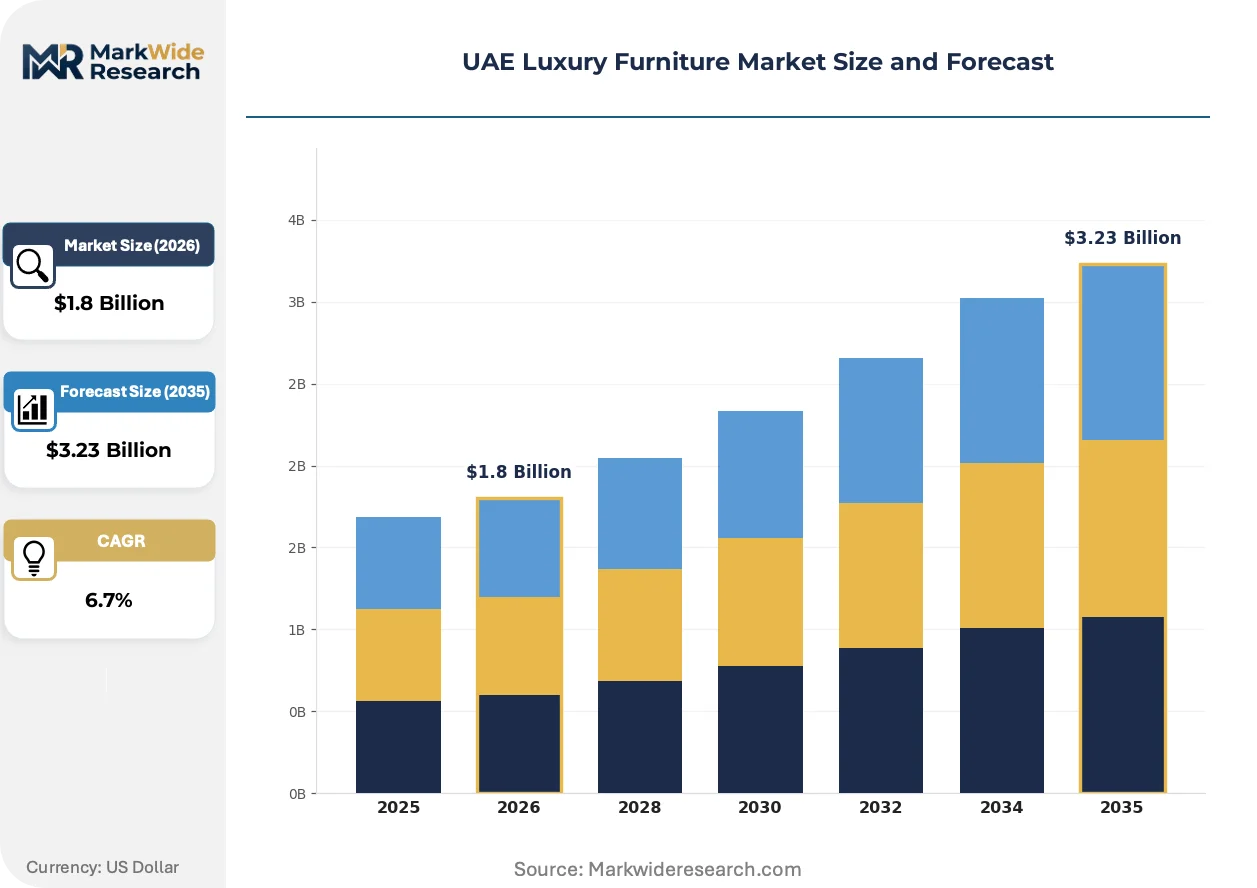
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Beds, Cabinets Material: Wood, Leather, Metal, Fabric End User: Residential, Commercial, Hotels, Offices Distribution Channel: Online, Retail Stores, Direct Sales, Showrooms |
| Companies Covered | Poltrona Frau, PAN Emirates, Marina Home Interiors, Danube, Royal Furniture, Roche Bobois, B&B Italia, BoConcept, Natuzzi Italia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Luxury Furniture Market Evolving Landscape
Digital fabrication and material traceability systems are compressing the gap between artisan craftsmanship and scalable production, while regulatory pressure on emissions and sourcing documentation reshapes competitive requirements.
Computer-numerical-control machining combined with robotic sanding and finishing is electrifying production economics for complex hardwood joinery. Dubai-based manufacturers serving hotel fit-out contracts are adopting these systems to compress delivery timelines from sixteen weeks to under ten. The technology is enabling mid-scale workshops to bid on prestige hospitality projects previously reserved for European ateliers.
MOHAP's 2024 amendments to product safety standards now mandate third-party certification for formaldehyde emissions and flame-retardant chemical content in all imported upholstered goods. This regulatory tightening is disqualifying lower-cost Asian suppliers lacking testing documentation, while rewarding distributors with established European supply relationships. Hotels and commercial interiors face the steepest compliance burden, as their public occupancy status triggers enhanced inspection protocols.
Developer-led bulk procurement is displacing individual consumer purchases as the dominant demand channel for luxury residential furnishings. Emaar and Aldar are now specifying complete interior packages for villa handovers, compressing independent retail traffic in Dubai Mall and Mall of the Emirates showrooms. This concentration is most visible in Downtown Dubai and Dubai Hills Estate, where turnkey delivery models now capture over half of new unit furniture expenditure.
UAE Luxury Furniture Market Segmentation
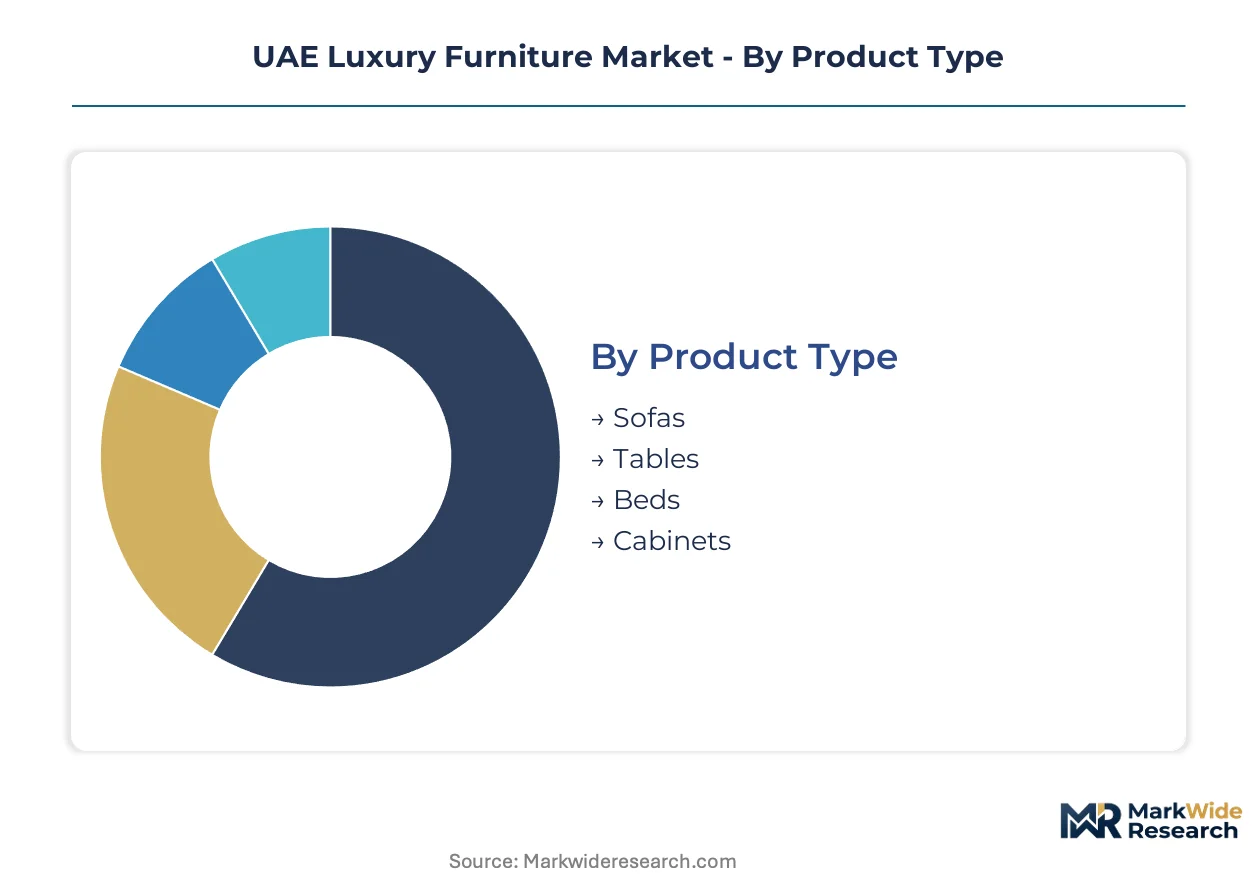
Segmentation in the UAE luxury furniture market reveals how supply-side capabilities align with divergent buyer requirements across residential estates, hospitality developments, and commercial interiors. Understanding these splits enables distributors to calibrate inventory depth, certification investments, and service models against specific project economics.
Product Type:
Production capacity clusters around seating and surface categories where craftsmanship premiums command the widest margins.
- Sofas:Modular leather systems with hand-finished joinery dominate villa majlis specifications and hotel lobby configurations. Dubai's Palm Jumeirah developments are pulling full-service fit-out contracts that specify Italian-tanned full-grain hides with reconfigurable frame systems.
- Tables:Precision-machined hardwood dining and conference surfaces require extended curing cycles for tropical hardwoods. Abu Dhabi luxury hospitality licensing mandates enhanced material traceability documentation for these high-visibility fixtures.
- Beds:Upholstered headboard systems with integrated storage command premium positioning in Saadiyat Island villa developments.
- Cabinets:Built-in millwork and freestanding storage units serve commercial interior specifications across Downtown Dubai office towers.
Sofas absorb the bulk of installed capacity; beds are expanding most quickly as villa developers specify complete sleeping quarters packages.
Material:
Raw material scarcity and processing complexity create tiered margin pools that reshape competitive positioning.
- Wood:Premium tropical hardwoods and European oak require controlled humidity curing and CNC-machined joinery. Dubai-based manufacturers serving hotel fit-out contracts are adopting robotic sanding systems to compress delivery timelines for complex hardwood pieces.
- Leather:Full-grain Italian hides involve euro-denominated input exposure and extended tannery lead times. MOHAP's amended flammability standards are disqualifying lower-cost Asian suppliers lacking third-party certification documentation.
- Metal:Precision-machined brass and stainless steel frames support contemporary aesthetic specifications in commercial interiors.
- Fabric:High-performance textiles with enhanced durability ratings serve hospitality applications requiring frequent turnover resilience.
Wood and leather capture the deepest margin pools; metal is gaining share fastest as contemporary aesthetic preferences shift toward machined industrial finishes.
End User:
Buyer concentration patterns diverge sharply between individual procurement and developer-led bulk contracting.
- Residential:High-net-worth villa owners in Dubai and Abu Dhabi commission bespoke pieces through design-led ateliers. Emaar and Aldar turnkey delivery models now capture over half of new unit furniture expenditure in Downtown Dubai and Dubai Hills Estate.
- Hotels:Luxury hospitality inventory expansion across Dubai and Abu Dhabi mandates furnishings meeting Dubai Municipality's amended building codes. Public occupancy status triggers enhanced MOHAP inspection protocols for flame-retardant chemical content.
- Commercial:Executive office environments in Dubai International Financial Centre specify status-signaling reception and boardroom fixtures.
- Offices:Corporate workspace fit-outs prioritize modular systems enabling rapid reconfiguration.
Residential absorbs the bulk of installed capacity; hotels are climbing the fastest as new development licensing accelerates procurement cycles.
Distribution Channel:
Channel economics are restructuring around project-scale contracting versus individual consumer access.
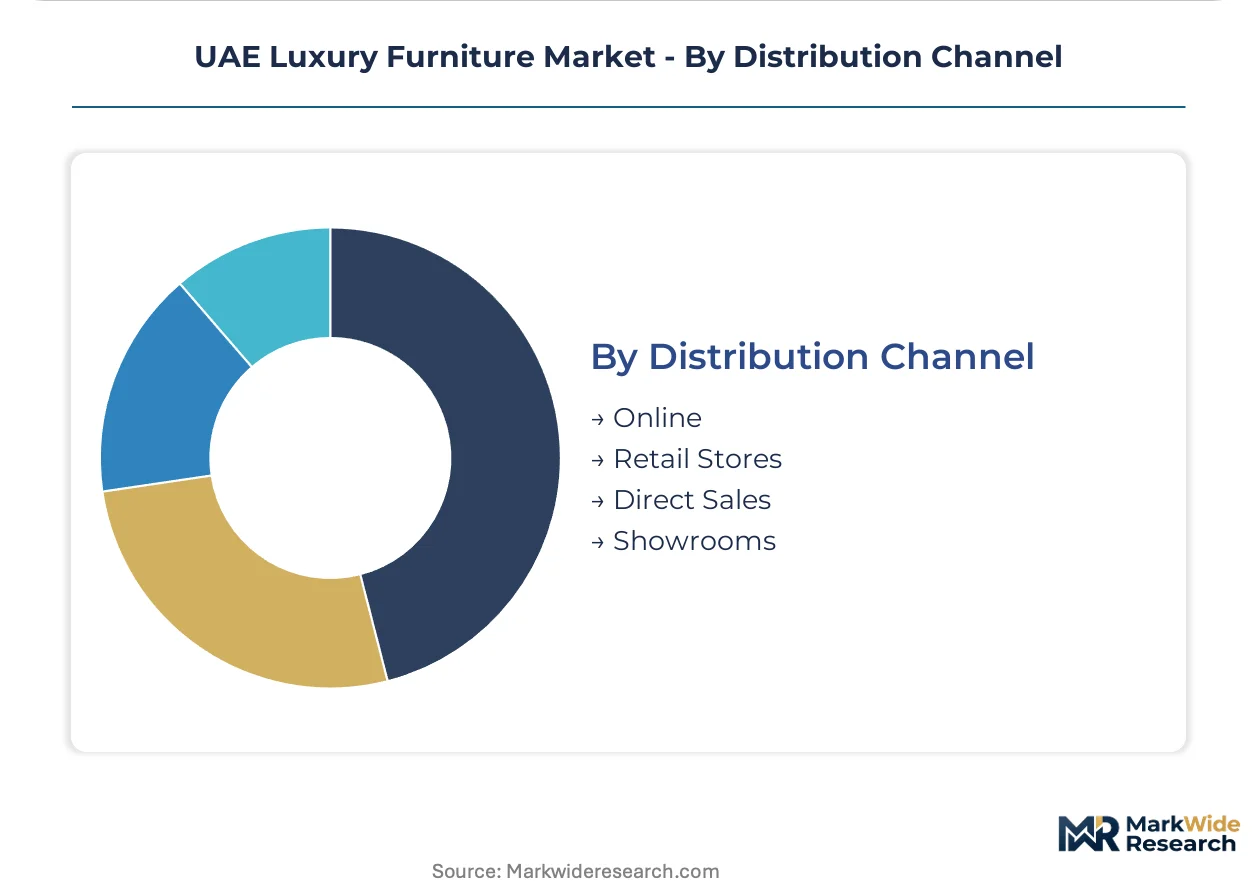
- Showrooms:Mall-based retail in Dubai Mall and Mall of the Emirates faces compressed traffic as developer-led bulk procurement displaces individual purchases. Marina Home Interiors competes through controlled retail footprints across these premium locations.
- Direct Sales:Design studios and ateliers maintain relationships with villa developers for turnkey interior packages. Virtual showroom technology is bypassing traditional intermediaries for commercial interior projects.
- Retail Stores:Independent furniture galleries serve expatriate residential buyers seeking immediate availability.
- Online:Digital platforms enable real-time material customization for developer procurement teams.
Showrooms retain the bulk of installed capacity; direct sales are expanding most quickly as virtual configuration tools compress sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors the UAE's luxury furniture demand through its Palm Jumeirah and Downtown Dubai villa developments, where developer-led turnkey interiors now dominate procurement patterns. The emirate's Department of Economy and Tourism licensing requirements are tightening material sourcing standards across commercial and residential segments.
Dubai
Waterfront residential developments on Palm Jumeirah are specifying Italian leather and precision-machined hardwood fixtures, creating pull-through demand for full-service interior fit-out contracts. Dubai Municipality's amended building codes mandate enhanced material traceability documentation for all imported furnishings. Downtown Dubai and Dubai Hills Estate have become the primary clusters where Emaar and Aldar turnkey delivery models capture over half of new unit furniture expenditure.
Abu Dhabi
Saadiyat Island and Yas Island residential developments show lower bespoke furniture saturation than Dubai equivalents, presenting white-space for design-led market entry. New hotel developments must source furnishings meeting Dubai Municipality's amended building codes, which require third-party certification for flame-retardant chemical content. The emirate's luxury hospitality licensing pipeline is accelerating procurement cycles for public-occupancy spaces.
Sharjah
Mid-market residential expansion in Sharjah's university corridor is generating demand for contemporary aesthetic specifications at accessible price points. MOHAP's 2024 amendments to product safety standards apply uniformly across all emirates, compressing supplier margins through extended certification timelines. Sharjah's industrial zones are attracting domestic assembly operations seeking proximity to Dubai's distribution infrastructure.
Northern Emirates
Ras Al Khaimah's hospitality development pipeline is sourcing furnishings for beachfront resort configurations requiring enhanced durability ratings. The UAE's production-linked incentive scheme for domestic manufacturing is reshaping local assembly economics for metal frame and wood component production. Ajman and Fujairah serve as secondary logistics nodes for inventory staging ahead of Dubai project deliveries.
UAE Luxury Furniture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material provenance and craftsmanship certification dimensions, with Italian leatherworking heritage anchoring ultra-premium positioning. The vendor base clusters around three strategic archetypes: European heritage ateliers leveraging centuries-old craft traditions, regional distributors controlling mall-based retail footprints, and developer-facing direct sales operations deploying virtual showroom technology. Competitive moves concentrate on strategic partnerships with real estate developers for turnkey interior packages and backward integration into domestic assembly through PLI scheme participation.
Among Italian heritage specialists, Poltrona Frau and Natuzzi Italia exemplify the craftsmanship-premium archetype, anchoring positioning through full-grain leather sourcing relationships and modular system engineering. Marina Home Interiors occupies the regional distributor tier with controlled retail showrooms across Dubai's premium malls. These three entities represent the dominant competitive vectors: European craft heritage, regional retail scale, and developer-direct digital platforms.
| Leading Market Players |
|---|
| Poltrona Frau |
| PAN Emirates |
| Marina Home Interiors |
| Danube |
| Royal Furniture |
| Roche Bobois |
| B&B Italia |
| BoConcept |
| Natuzzi Italia |
| Others |
Value Network & Pricing Analysis
Captive sourcing relationships with Italian tanneries anchor the premium tier's supply position while insulating Poltrona Frau and Natuzzi Italia from euro volatility that compresses distributor margins. This backward integration into full-grain hide procurement locks in material provenance documentation required by MOHAP's amended flammability standards, translating directly into pricing power over showroom competitors sourcing through spot markets.
Pricing Analysis
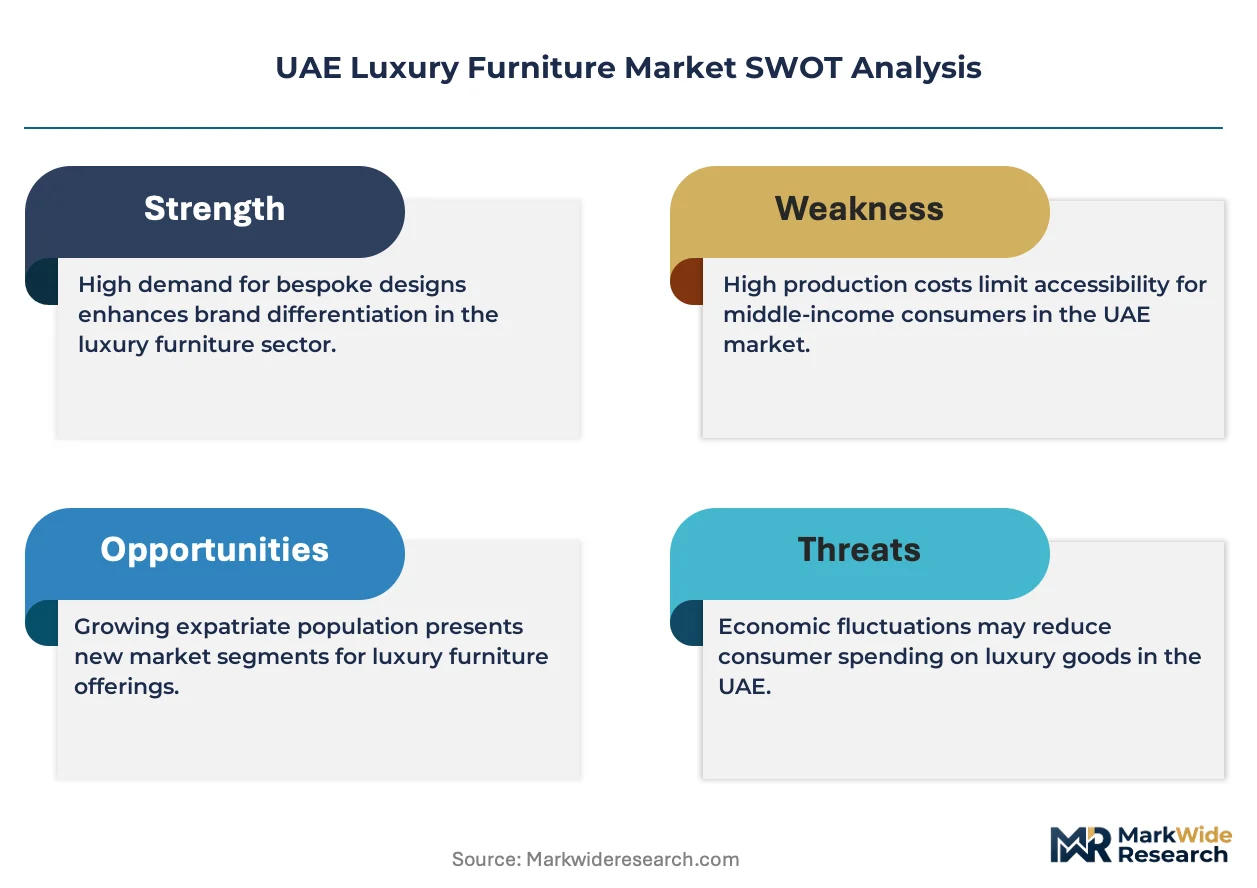
Certification-grade pricing anchors value capture in this market, with MOHAP-compliant Italian leather systems commanding substantial premiums over Asian alternatives lacking third-party documentation. Price differentiation rests on material traceability depth and hand-finishing intensity, with villa developers least sensitive to cost and Sharjah's university corridor buyers most responsive to accessible price points. Cost compression in the mid-market tier is intensifying because European leather supply concentration exposes distributors to euro-denominated input volatility.
Supply Chain Analysis
Certification gating through MOHAP's 2024 amendments is disqualifying lower-cost Asian suppliers lacking formaldehyde and flame-retardant documentation, reshaping competitive access. Manufacturing concentrates in Italy, Portugal, and domestic UAE assembly operations feeding from Dubai's distribution infrastructure. Raw material dependencies center on full-grain Italian hides, tropical hardwoods, and precision-machined brass components. Single-source vulnerability runs through Italian tannery concentration for premium leather inputs. Distribution runs through developer-direct digital platforms and mall-based showrooms serving distinct procurement archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisan upholstery capacity scarcity props pricing across Dubai's villa commissioning pipeline, constraining volume expansion regardless of developer demand acceleration. This bottleneck rewards players with secured European workshop relationships.
For Market Incumbents: Anticipate margin compression from developer-led bulk procurement consolidation by securing exclusive fit-out contracts with Emaar and Aldar before virtual showroom platforms displace mall-based intermediaries. Prioritize certification investment ahead of MOHAP's potential emissions standard tightening. Backward integration into domestic wood component assembly through PLI scheme participation defends cost position against European atelier competitors. For New Entrants and Emerging Players: Virtual showroom technology enabling real-time leather customization offers entry leverage against established mall-based retailers. Target Abu Dhabi's Saadiyat Island and Yas Island villa developments, where bespoke furniture saturation trails Dubai equivalents. Deploy direct-to-developer digital platforms with integrated material traceability documentation to bypass traditional retail intermediaries and compress sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in developer-facing direct sales operations with secured hospitality fit-out contracts and established European supply relationships. Long-term viability favors entities with multi-year Italian tannery sourcing agreements and domestic assembly scale through PLI participation. Watch for MOHAP certification timeline compression as an inflection signal indicating regulatory barriers to entry hardening.| Strategic Initiative | Industry Significance |
|---|---|
| European Tannery Supply Agreement | Locks in full-grain hide access required for MOHAP compliance and villa developer specifications. |
| Domestic Assembly Scale-Up | Captures PLI incentives while compressing delivery timelines for Dubai hotel fit-out contracts. |
| Virtual Showroom Deployment | Bypasses Mall of Emirates retail intermediaries for direct developer procurement engagement. |
| Master Upholsterer Apprenticeship Program | Addresses artisan labor scarcity constraining bespoke villa commissioning volumes. |
| Material Traceability Platform | Generates documentation required by Dubai Municipality's amended building code amendments. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed furniture manufacturers, and hospitality development licensing records, complemented by interviews with interior fit-out contractors, villa procurement managers at Emaar and Aldar, MOHAP certification specialists, and Italian tannery export directors. Secondary validation drew from Dubai Department of Economy and Tourism licensing databases, Dubai Municipality building code amendments, and UAE PLI scheme documentation. Bottom-up project pipeline enumeration triangulated against top-down emirate-level furniture expenditure estimates.
Segment-level outputs across product type, material, end user, and distribution channel dimensions were generated through the projection horizon. CAGRs were derived from fitted growth curves calibrated against historical villa completion rates and hospitality licensing trajectories. Forecast inputs incorporated Palm Jumeirah and Saadiyat Island development pipelines, euro-dirham exchange rate assumptions, and MOHAP certification timeline evolution.
Several conditions sit outside the modeled scope, including Gulf Cooperation Council customs harmonization changes, eurozone monetary policy shifts affecting tannery input costs, and abrupt MOHAP standard amendments. Forecasts reflect documented assumptions about artisan labor availability and developer procurement concentration. A model refresh is warranted upon material change in European leather supply chain stability or PLI scheme incentive structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
UK Sustainable Office Furniture Market
Furniture
Global Home Furniture Market
Furniture
Bar Stools Market
Furniture
India Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Japan Home Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
North America Smart Furniture Market
Furniture
Piano Stools Market
Furniture
GCC Home Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Back Mount Frames Market
Furniture
Germany Furniture Market
Furniture
Europe Smart Furniture Market