
 Furniture and Home Furnishing Store Market | 2026-2036
Furniture and Home Furnishing Store Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture and Home Furnishing Store Market Analysis
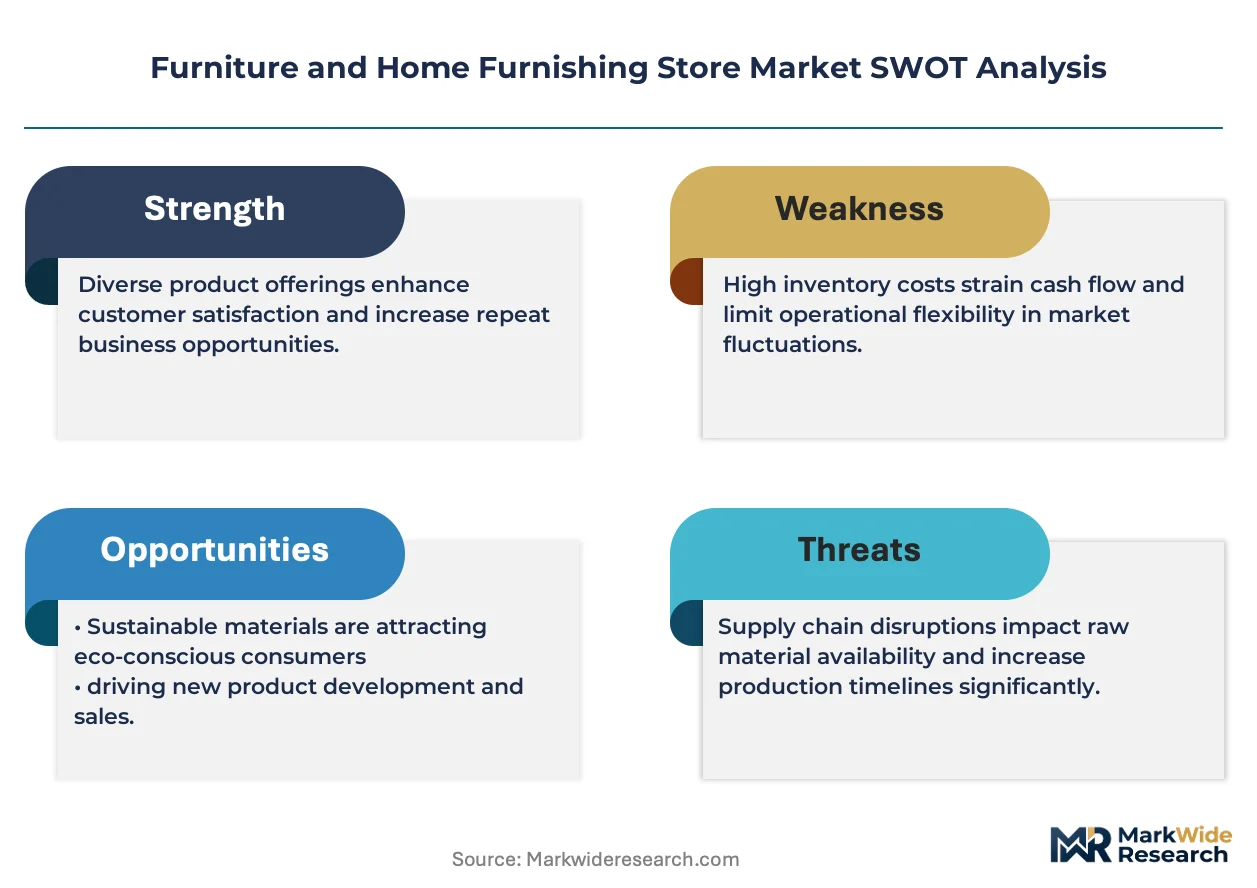
Single-source timber procurement is decoupling from mass-market furniture production as brands diversify supply origins. IKEA anchors its competitive stance through captive forest holdings and flat-pack logistics networks. Ashley Furniture Industries dominates North American manufacturing with vertically integrated upholstery plants. Wayfair leverages proprietary logistics technology to sustain marketplace breadth without inventory ownership.
Furniture and home furnishing stores retail finished goods for interior spaces, typically merchandising items constructed from engineered wood, solid timber, metal framing, foam cushioning, and synthetic or natural textiles through showrooms or digital platforms. These establishments serve residential, commercial, hospitality, and office end users by providing functional and aesthetic environment solutions. Sofas and beds command the largest revenue pools within product type segmentation, reflecting replacement cycles and room centrality. The online distribution channel is capturing the fastest growth trajectory as augmented reality visualization tools reduce purchase uncertainty. Wood material categories retain margin strength through certified sustainable sourcing premiums that resonate with environmentally segmented buyers.
The EPA regulates formaldehyde emissions in composite wood products under TSCA Title VI, compelling domestic manufacturers to certify supply chain compliance. The EU ECHA enforces REACH chemical restrictions on furniture finishes and flame retardants, creating market access barriers for non-compliant imports. California's Air Resources Board maintains stricter-than-federal emission standards that de facto shape national product specifications. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America that will shift end-of-life costs onto retailers and manufacturers.
Market Dynamics
The EU Green Deal's product sustainability requirements are forcing furniture retailers to reconfigure material sourcing networks and certification documentation systems. This regulatory pressure intersects with residential buyers expanding purchases for home office and outdoor living spaces, creating simultaneous compliance and demand complexity.
Growth Catalysts
- REACH chemical restrictions:The EU ECHA's enforcement of furniture finish and flame retardant standards is creating certified-sourcing premiums that environmentally segmented buyers willingly absorb.
- Home office furniture demand:Residential buyers are expanding dedicated workspace purchases, extending replacement cycles beyond traditional living room and bedroom categories.
- Augmented reality visualization:Online retailers deploying AR tools are reducing purchase uncertainty and accelerating digital channel conversion rates.
Market Restraints
- Solid timber input volatility:Single-source timber procurement is decoupling from mass-market production as brands diversify supply origins, fragmenting volume discounts.
- Composite wood emission compliance:The EPA's TSCA Title VI formaldehyde standards and California Air Resources Board stricter thresholds de facto shape national product specifications, raising certification costs.
- Extended producer responsibility frameworks:Evolving end-of-life cost shifts in Europe and North America will transfer disposal burden onto retailers and manufacturers.
Strategic Opportunities
- Outdoor living space expansion:Residential buyers in the United States are increasing weather-resistant furniture purchases for patios and terraces.
- Captive forest holdings:Flat-pack logistics networks combined with captive timber supply are enabling margin defense through backward integration into raw material control.
- Proprietary logistics technology:Marketplace operators without inventory ownership can sustain breadth through algorithmic demand forecasting and supplier coordination platforms.
Industry Challenges
- Certification documentation systems:Retailers must maintain chain-of-custody records for certified sustainable wood categories across fragmented supplier bases.
- Supply chain reconfiguration friction:Diversifying timber origins away from concentrated sourcing regions requires new quality assurance protocols and longer lead times.
- Legacy showroom inventory models:Traditional furniture retailers face capex intensity in converting floor space to accommodate flat-pack and direct-ship fulfillment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture and Home Furnishing Store Market |
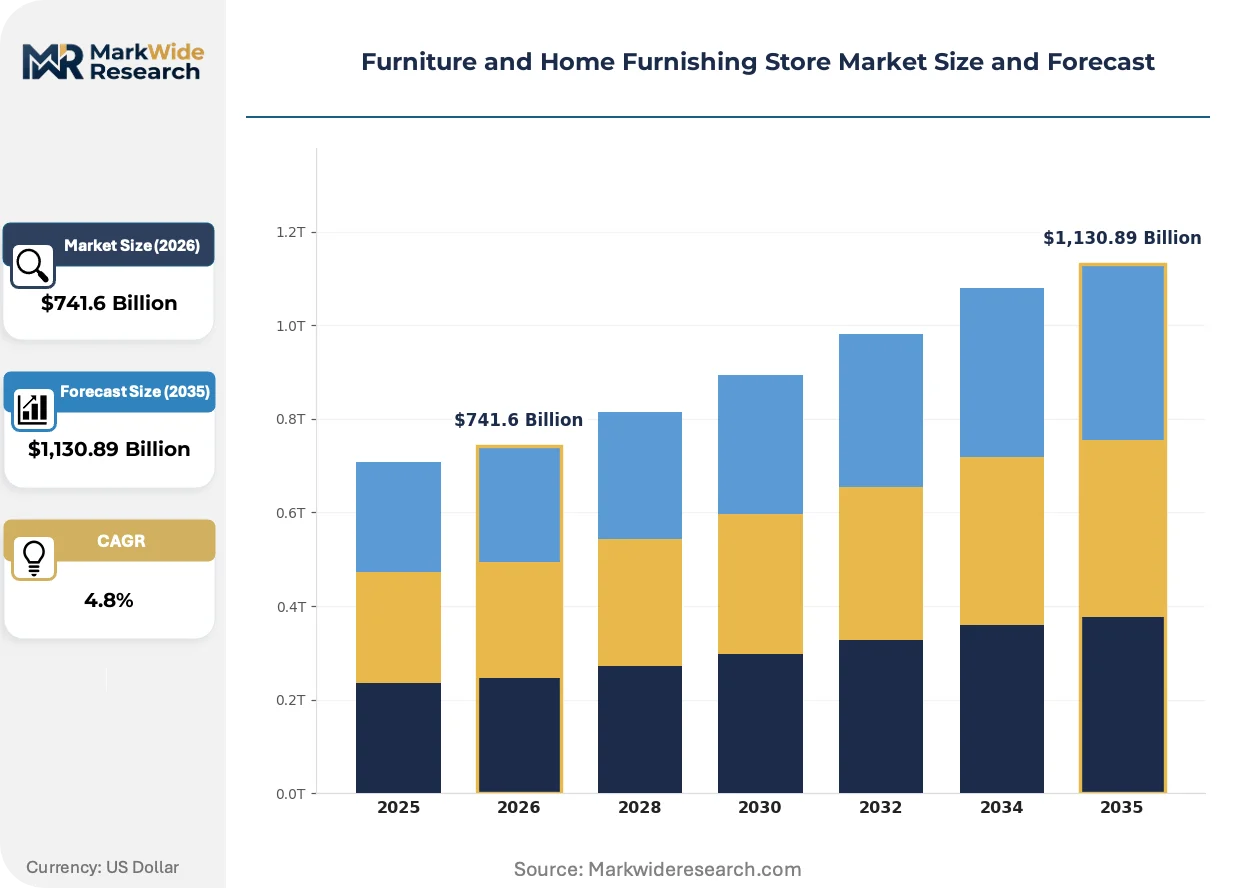
| Market Size in 2026 | $741.6 Billion |
| Market Size in 2035 | $1,130.89 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
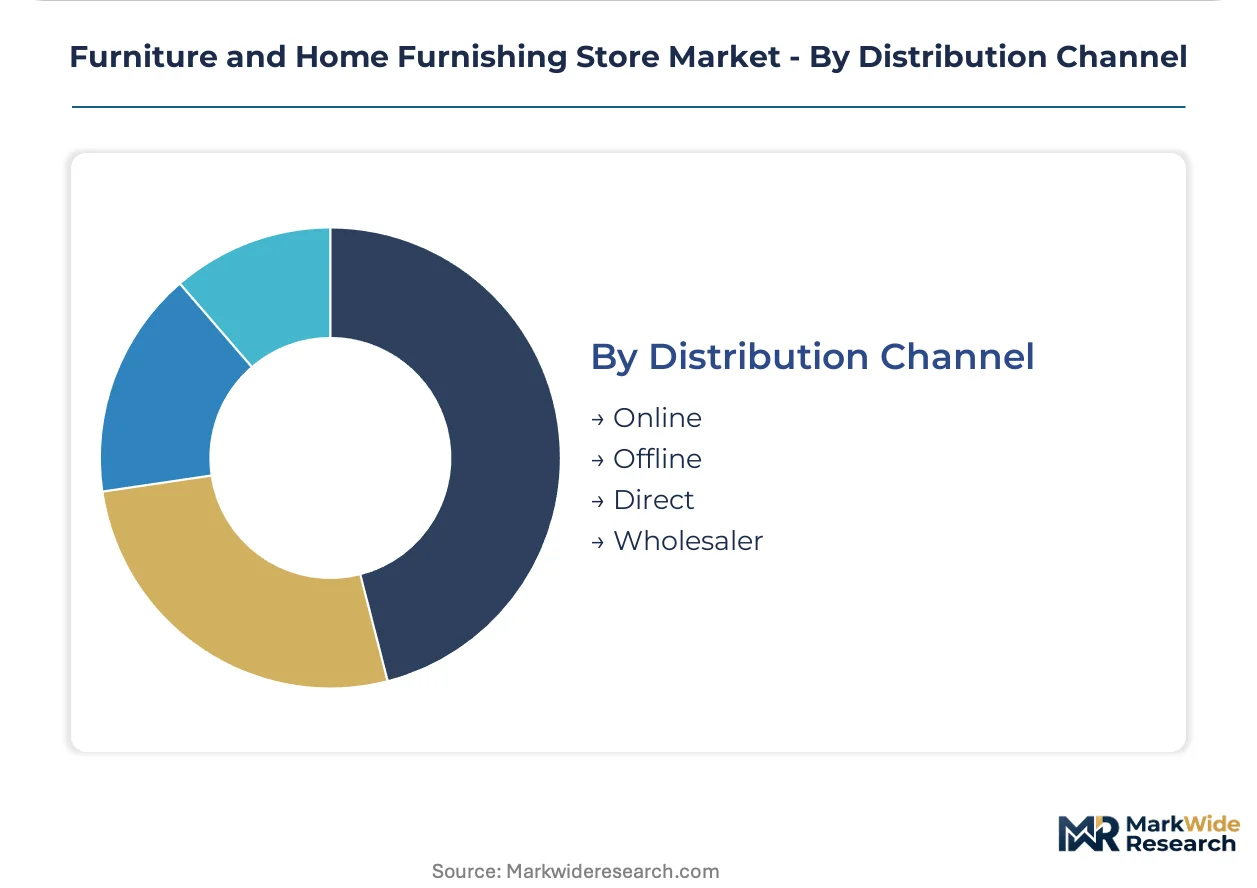
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Upholstered, Glass End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Offline, Direct, Wholesaler |
| Companies Covered | Wayfair, Ashley Furniture Industries, Williams-Sonoma, IKEA, RH, La-Z-Boy, HomeGoods, Nitori Holdings, The Home Depot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture and Home Furnishing Store Market Emerging Trajectories
Digital visualization tools and regulatory sustainability mandates are converging to reshape how furniture retailers merchandise, source, and fulfill orders. These forces are compressing traditional showroom-dependent purchase journeys.
Augmented reality product visualization is decentralizing the furniture purchase decision away from physical showrooms. Residential buyers now configure sofas and beds through smartphone applications that render scale-accurate overlays in their actual rooms. This technology is compressing the consideration phase and reducing return rates for online-only retailers.
The EU Green Deal's product sustainability requirements are mandating circular economy design principles across furniture imports. Manufacturers must now document material origin, recyclability pathways, and chemical content for EU market access. Upholstery plants serving European distribution channels are retooling finishing processes to eliminate restricted flame retardants.
Residential procurement patterns are fragmenting across project-based and replacement-driven purchase cycles. Home office setups and outdoor living renovations operate on renovation timelines distinct from traditional furniture replacement schedules. This bifurcation is most visible in the United States, where housing turnover and remote work permanence are creating dual demand signals that inventory planning systems must reconcile.
Furniture and Home Furnishing Store Market Segmentation
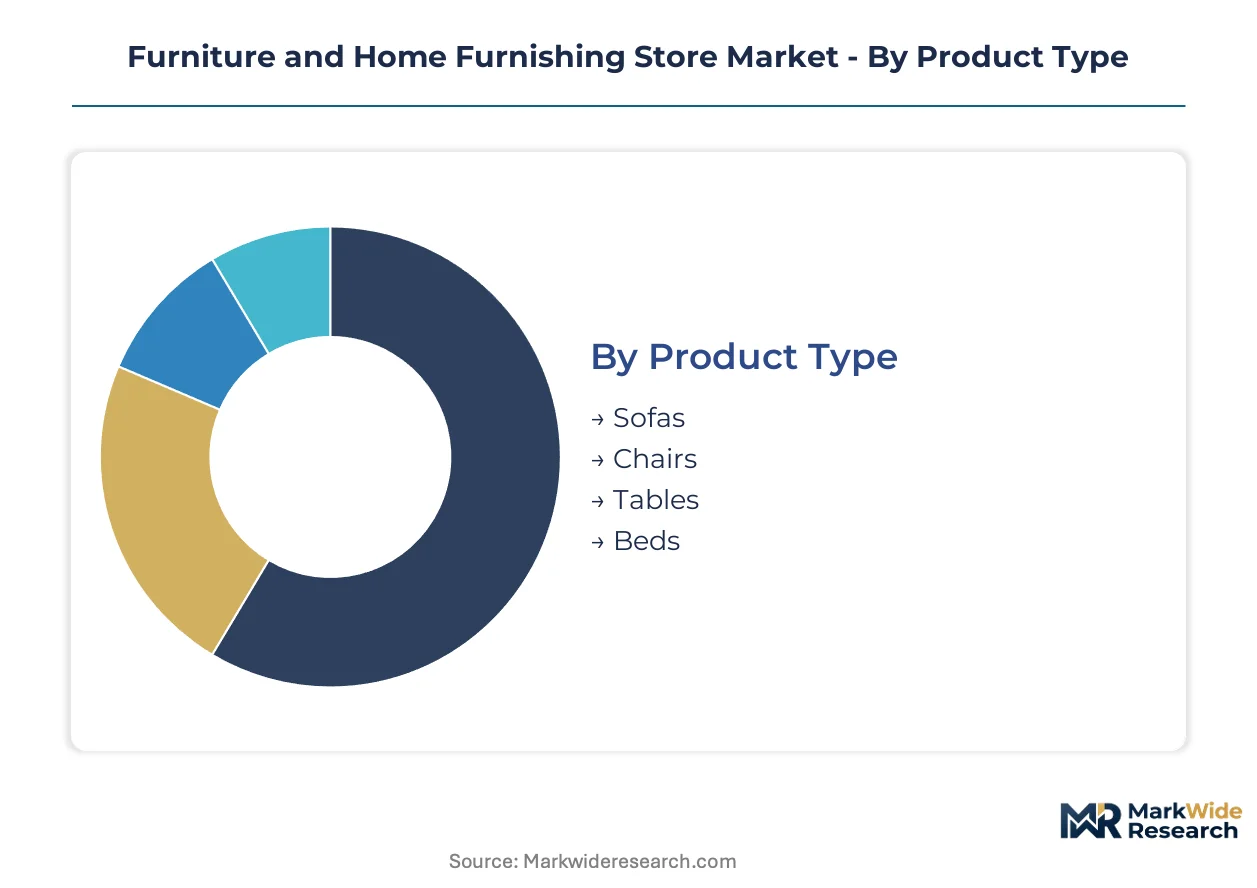
Segmentation in furniture retail reveals divergent margin profiles and sourcing requirements across product construction, material origin, and purchase channel. Each dimension carries distinct certification burdens and logistics configurations that shape competitive positioning.
Product Type:
Volume concentration tilts toward replacement-driven categories with shorter purchase cycles, while premium capture concentrates in statement pieces with extended deliberation periods.
- Sofas:Multi-seat upholstered constructions with foam cushioning and fabric or leather coverings dominate residential living room procurement. Demand clusters in United States suburban markets where housing turnover and remote work permanence drive replacement schedules.
- Beds:Mattress and frame assemblies command the highest per-unit expenditure in residential furniture budgets. Germany and China lead volume absorption through distinct channel preferences—specialty sleep retailers versus integrated home goods platforms.
- Chairs:Dining, accent, and task seating span price tiers from mass-market flat-pack to artisan-crafted timber.
- Tables:Surface assemblies for dining, work, and display purposes vary dramatically in material intensity and shipping economics.
Mature deployment sits with beds. Newer deployment is concentrated in sofas as living room reconfiguration accelerates post-pandemic.
Material:
Cost tier stratification separates certified sustainable inputs from commodity-grade alternatives, with compliance premiums widening price spreads.
- Wood:Solid timber and engineered wood products face divergent regulatory treatment under EPA TSCA Title VI and EU ECHA REACH frameworks. United States residential buyers absorb certified-sourcing premiums for FSC-chain-of-custody documentation.
- Upholstered:Fabric-wrapped foam and spring constructions require flame retardant compliance that varies by California Air Resources Board thresholds versus EU chemical restrictions.
- Metal:Steel and aluminum framing enables flat-pack shipping density and outdoor durability specifications.
- Glass:Tempered surface applications concentrate in accent and display furniture with higher damage rates in direct-ship fulfillment.
Certified wood commands margin premiums in European markets. Upholstered materials face the steepest compliance cost escalation trajectory.
End User:
Application context determines durability specifications, volume procurement patterns, and project-based versus replacement-driven demand timing.
- Residential:Individual household purchases span single-item replacement to whole-home furnishing projects with extended consideration phases.
- Commercial:Corporate workspace procurement operates on contract furniture schedules with bulk specification and installation services.
- Hospitality:Hotel and restaurant fit-outs demand fire-rated materials and accelerated replacement cycles under heavy-use conditions.
- Office:Dedicated workspace furniture has bifurcated between enterprise fleet orders and home office individual purchases.
Enterprise office procurement retains established supplier relationships. Home office expansion is gaining share fastest among end user categories.
Distribution Channel:
Customer type and purchase urgency separate immediate-need buyers from planned-project procurement with divergent channel preferences.
- Online:Digital platforms with augmented reality visualization tools reduce return rates and compress consideration phases for standard-size items.
- Offline:Showroom-dependent purchases persist for tactile evaluation of upholstery comfort and wood grain aesthetics.
- Direct:Manufacturer-owned channels bypass retail markups for custom or made-to-order specifications.
- Wholesaler:Trade-only distribution serves interior designers and commercial specifiers with volume pricing and project coordination.
Established wholesale relationships anchor commercial project flow. Direct-to-consumer channels are expanding most quickly as captive logistics networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian rubberwood plantations and Baltic birch forests anchor raw material flows for furniture manufacturing clusters across three continents. Retail infrastructure density and regulatory stringency create divergent competitive conditions in major consumption markets.
United States
Suburban housing turnover and permanent remote work arrangements drive living room reconfiguration demand. The EPA's TSCA Title VI formaldehyde emission standards compel composite wood certification across domestic and imported supply. High Point, North Carolina anchors upholstered furniture manufacturing with vertically integrated production corridors serving eastern distribution networks.
Germany
Specialty sleep retailers and integrated home goods platforms sustain bed and mattress procurement cycles. The EU ECHA enforces REACH chemical restrictions on furniture finishes and flame retardants that reshape finishing plant operations. North Rhine-Westphalia hosts dense upholstery manufacturing clusters adapting to circular economy documentation requirements.
China
Integrated home goods platforms and export-oriented manufacturing zones absorb volume across domestic and international channels. The country's national quality regulator maintains GB standards for furniture structural safety and chemical content. The Pearl River Delta concentrates flat-pack production and engineered wood panel manufacturing for global supply.
Japan
Compact urban dwellings and aging household demographics favor space-efficient and ergonomic furniture specifications. METI oversees product safety standards and recycling framework compliance for household goods. The Kanto region surrounding Tokyo maintains showroom density and direct-to-consumer logistics infrastructure.
India
Rising residential construction and urban household formation expand addressable demand for bedroom and dining furniture. The Bureau of Indian Standards mandates structural safety and material quality certifications for domestic market access. Maharashtra and Gujarat host emerging manufacturing clusters serving domestic retail chains and export channels.
Furniture and Home Furnishing Store Market Vendor Landscape
Backward integration into raw material supply dominates the current landscape as margin pressure intensifies across mass-market segments. The vendor base separates into three distinct tiers: flat-pack logistics specialists, vertically integrated upholstery manufacturers, and digital marketplace operators without inventory ownership. Two strategic archetypes define competitive positioning—captive forest holders defending margin through supply control, and algorithmic demand forecasters coordinating fragmented supplier bases. M&A activity and proprietary logistics technology deployment represent the dominant competitive moves reshaping market structure.
Among flat-pack logistics specialists, IKEA exemplifies captive forest holding combined with global distribution density. Wayfair and Ashley Furniture Industries occupy contrasting positions within the competitive map—Wayfair represents algorithmic marketplace coordination without inventory ownership, while Ashley Furniture Industries anchors vertically integrated upholstery manufacturing with domestic production scale. These three companies illustrate the strategic divergence between supply-side control and demand-side coordination that defines current competitive dynamics.
| Leading Market Players |
|---|
| Wayfair |
| Ashley Furniture Industries |
| Williams-Sonoma |
| IKEA |
| RH |
| La-Z-Boy |
| HomeGoods |
| Nitori Holdings |
| The Home Depot |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's product sustainability requirements gate qualified supply and premium-tier pricing access for furniture retailers serving environmentally segmented buyers. Certified-sourcing premiums for FSC-chain-of-custody documentation now separate accessible mass-market tiers from margin-defended sustainable segments, while compliance cost escalation compresses pricing flexibility for non-compliant imports.
Pricing Analysis
Warranty and white-glove delivery bundling now separates premium furniture tiers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in mass-market upholstered segments is intensifying because foam and fabric input volatility outpaces pricing power recovery. Commercial hospitality buyers demonstrate lowest price sensitivity due to fire-rated specification requirements, while residential replacement buyers absorb premiums only for certified sustainable wood categories.
Supply Chain Analysis
Reverse-logistics flows for furniture returns and refurbishment are emerging as cost centers as extended producer responsibility frameworks shift disposal burden onto retailers. Raw material supply concentrates in China for engineered wood panel manufacturing, Vietnam for upholstery assembly, and the Baltic states for certified birch timber. Production draws from rubberwood plantations in Southeast Asia, foam chemical feedstocks from Middle Eastern petrochemical complexes, and steel framing from Chinese integrated mills. Single-source timber vulnerability persists as brands diversify origins away from concentrated sourcing regions. Distribution runs through flat-pack logistics networks for mass-market penetration and direct-ship fulfillment for online marketplace operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture retail is consolidating around players with captive supply control and algorithmic demand coordination, as regulatory compliance costs force weaker participants toward exit or acquisition.
For Market Incumbents: Acquire captive forest holdings and flat-pack logistics infrastructure to defend margin against input volatility and certification documentation burdens. Consolidate upholstery manufacturing capacity in North American production corridors to offset REACH compliance cost escalation for European market access. Deepen backward integration into engineered wood panel supply to secure TSCA Title VI certification continuity. For New Entrants and Emerging Players: Begin with outdoor living space specialization targeting United States suburban markets where housing turnover and remote work permanence drive replacement schedules. White-space concentration sits with weather-resistant patio furniture and home office ergonomic seating, segments where established players retain legacy showroom inventory models. Launch through direct-to-consumer channels with augmented reality visualization tools to bypass capex-intensive floor space requirements. For Investors and Strategic Acquirers: M&A activity targeting proprietary logistics technology is the leading indicator that algorithmic demand forecasting capabilities are becoming the scarce competitive asset. Long-term viability favors marketplace operators coordinating fragmented supplier bases without inventory ownership, alongside flat-pack specialists with captive timber supply. Monitor EU Green Deal enforcement escalation and extended producer responsibility framework adoption as signals for compliance-cost-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forest Acquisition | Backward integration into timber supply secures FSC certification continuity for EU market access. |
| Proprietary Logistics Platform Deployment | Algorithmic demand forecasting enables marketplace breadth without inventory ownership cost structure. |
| Flat-Pack Production Footprint Expansion | Shipping density optimization reduces last-mile cost for residential direct-to-consumer fulfillment. |
| REACH-Compliant Finishing Plant Retooling | Elimination of restricted flame retardants preserves European distribution channel market access. |
| Augmented Reality Visualization Integration | Smartphone-based room rendering compresses consideration phases and reduces online return rates. |
Methodological Framework
Independent corroboration across furniture manufacturing executives, retail procurement directors, logistics technology specialists, and sustainability certification auditors underwrites the qualitative findings. Primary fieldwork captured operational practices from flat-pack production managers, upholstery plant operators, and marketplace demand forecasting teams. Secondary validation drew from EPA TSCA Title VI certification databases, EU ECHA REACH restriction updates, customs trade flow records, and SEC filings from publicly traded home goods retailers. Bottom-up segment sizing and top-down market reconciliation ensured methodological triangulation.
Rate-of-change decomposition across product type, material origin, end-user application, and distribution channel dimensions structured the analytical framework. CAGRs were derived from volume and value trajectory modeling throughout the forecast period. Segmentation inputs included replacement cycle timing for sofas and beds, certification penetration rates for sustainable wood categories, and digital channel conversion acceleration from augmented reality deployment.
Underlying measurement precision varies by segment; online distribution channel estimates carry tighter precision than direct-to-consumer projections given disclosure practices. Forecasts reflect documented assumptions regarding regulatory enforcement timing and remote work permanence durability. Practitioners should monitor EU Green Deal implementation velocity and extended producer responsibility framework adoption for early signals of supply chain reconfiguration pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Pool Tables Market
Furniture
Contract Furniture Market
Furniture
Chair Hardware Market
Furniture
RTA Furniture Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
Global Furniture Market
Furniture
Ergonomic Chair Market
Furniture
China Upholstered Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
School Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
GCC Furniture Market