
 Saudi Arabia Modular Kitchen Market | 2026-2036
Saudi Arabia Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Modular Kitchen Market Outlook
SFDA material safety standards is realigning the cost-of-entry calculus for imported kitchen components, forcing foreign suppliers to certify surface treatments and adhesives before customs clearance. Al-Muhaidib Group leverages its domestic manufacturing footprint to bypass import certification delays and anchor project contracts with Saudi developers. Hafele competes through hardware specialization, sustaining premium positioning via its built-in appliance and fitting ecosystems. IKEA Systems navigates price-sensitive segments through flat-pack logistics and localized assembly partnerships.
A modular kitchen is an integrated cabinetry system comprising standardized frame cabinets, base cabinets, wall cabinets, and modular islands that are pre-manufactured off-site and assembled in residential or commercial spaces, typically engineered with moisture-resistant engineered wood or aluminum-framed substrates to withstand Saudi climatic conditions. By material, laminate surfaces dominate volume due to cost efficiency and heat tolerance, while wood and glass segments capture margin pools in luxury developments across Riyadh and the Red Sea coast. Modern and contemporary design styles lead new construction, whereas traditional styling retains share in heritage-influenced villa segments in Jeddah and the Eastern Province.
Saudi Building Code enforcement through the Saudi Standards, Metrology and Quality Organization (SASO) dictates fire-retardant and load-bearing specifications for installed cabinetry, while SFDA oversight governs food-contact surface safety for integrated countertops and sinks. Municipal building permit offices in Riyadh, Jeddah, and Dammam now require modular kitchen compliance documentation as a condition for final occupancy certification. Stakeholders must monitor evolving giga-project procurement standards and SASO technical regulation updates to anticipate specification shifts before contract bidding cycles close.
Market Dynamics
Giga-project housing deliveries across Riyadh and the Red Sea coast are compressing procurement cycles and forcing modular kitchen suppliers to pre-certify materials under SASO technical regulations before bidding closes.
Growth Catalysts
- SASO fire-retardant specifications:Mandatory compliance documentation for installed cabinetry now accompanies every municipal occupancy permit in Riyadh, Jeddah, and Dammam, creating standardized demand pull.
- Luxury villa developers:Premium project pipelines in Riyadh and Jeddah specify imported hardware and surface materials, expanding the addressable market for certified suppliers.
- Aluminum-framed substrates:Moisture-resistant engineering adapted to Saudi climatic conditions extends product lifecycle and reduces replacement frequency in coastal humidity zones.
Market Restraints
- SFDA certification timelines:Food-contact surface safety clearance for integrated countertops and sinks delays customs release by four to eight weeks, compressing project margins.
- Imported engineered wood concentration:Supply dependency on European and Southeast Asian substrate manufacturers exposes contractors to freight rate volatility and currency fluctuation.
- Adhesive formulation restrictions:VOC emission limits under Saudi Building Code eliminate certain low-cost bonding agents, forcing reformulation investment.
Strategic Opportunities
- NEOM and Red Sea Project corridors:Giga-project procurement standards for integrated living spaces specify modular kitchen systems as base build elements, not fit-out options.
- Localized assembly partnerships:Flat-pack logistics models bypass finished-goods import duties and reduce last-mile delivery costs to remote construction sites.
- Heritage-influenced villa segments:Traditional styling preferences in Jeddah and the Eastern Province remain underserved by contemporary-focused product catalogs.
Industry Challenges
- Certified installer scarcity:Municipal permit offices now require documented compliance training for final occupancy sign-off, and qualified technician pipelines lag demand.
- Legacy procurement system integration:Developer ERP platforms lack SKU-level tracking for modular components, forcing manual reconciliation between factory orders and site delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Modular Kitchen Market |
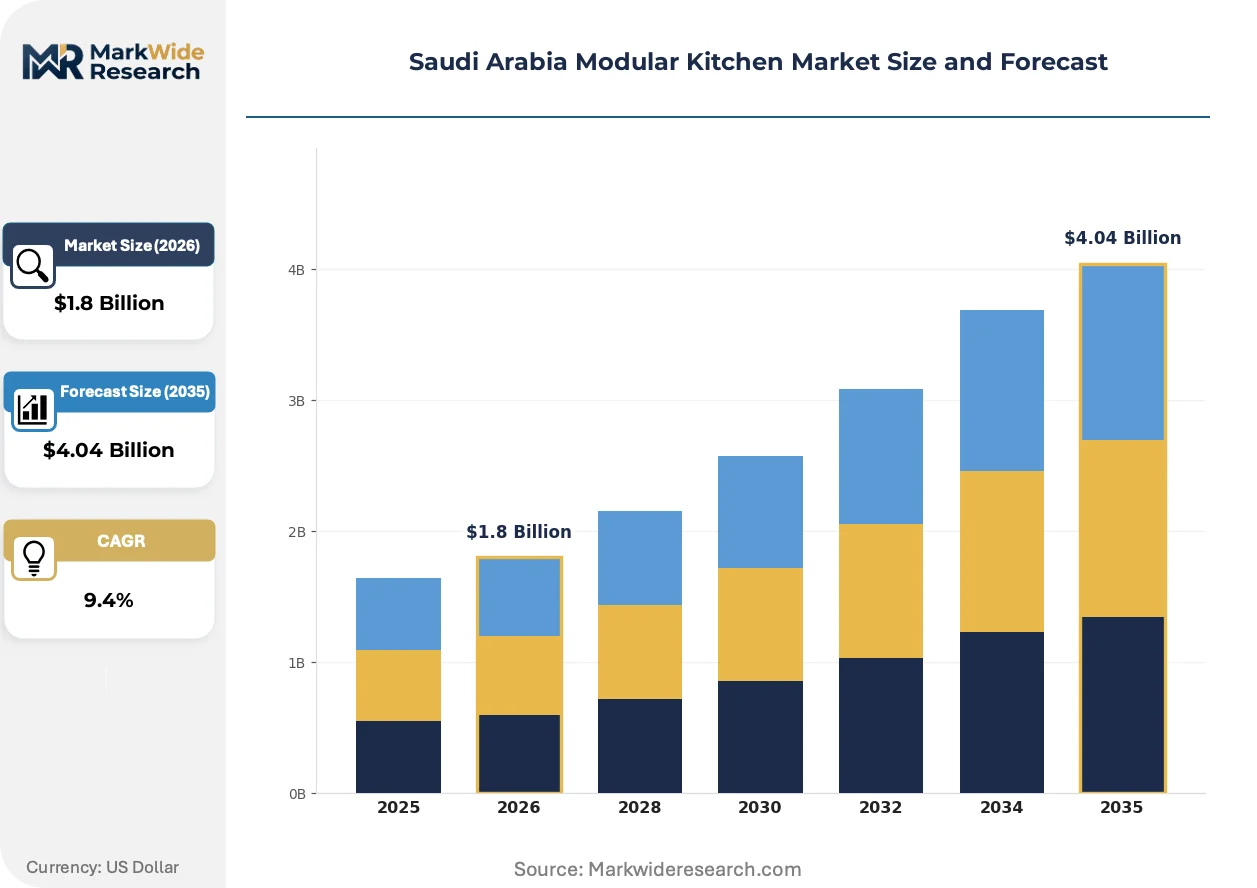
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Cabinets, Base Cabinets, Wall Cabinets, Modular Islands Material: Wood, Metal, Laminate, Glass Design Style: Modern, Traditional, Rustic, Contemporary End User: Homeowners, Builders, Interior Designers, Realtors |
| Companies Covered | AlKhaleejion Kitchens, Pedini Cucine Saudi Arabia, Saudi Kitchen Line Company, Al-Muhaidib Group, Hafele, IKEA Systems, Hacker Kitchens, Nobilia International, Snaidero Kitchens Saudi Arabia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Modular Kitchen Market Strategic Shifts
Smart hardware integration and climate-adaptive materials are redefining product specifications, while regulatory pre-certification requirements are reshaping supplier qualification workflows before contract award.
Aluminum-framed cabinet substrates with thermal break engineering are overtaking conventional particleboard in coastal developments. Red Sea Project contractors specify these systems for humidity resistance. The shift is compressing the addressable market for untreated wood products and elevating metal fabrication capacity requirements among tier-one suppliers.
SASO technical regulation updates for load-bearing cabinetry enforcement are tightening fire-safety documentation requirements. Developer procurement teams now demand factory-test certificates before bid submission. Luxury villa segments in Riyadh absorb compliance costs through specification premiums, while mid-market projects delay adoption pending certified local supply alternatives.
Developer procurement teams are consolidating vendor panels around pre-qualified modular kitchen suppliers with in-country assembly capability. Traditional distributor networks lose share to direct factory-site relationships. The pattern concentrates in Riyadh metropolitan corridor projects where giga-project procurement offices bypass conventional channel intermediaries entirely.
Saudi Arabia Modular Kitchen Market Segmentation
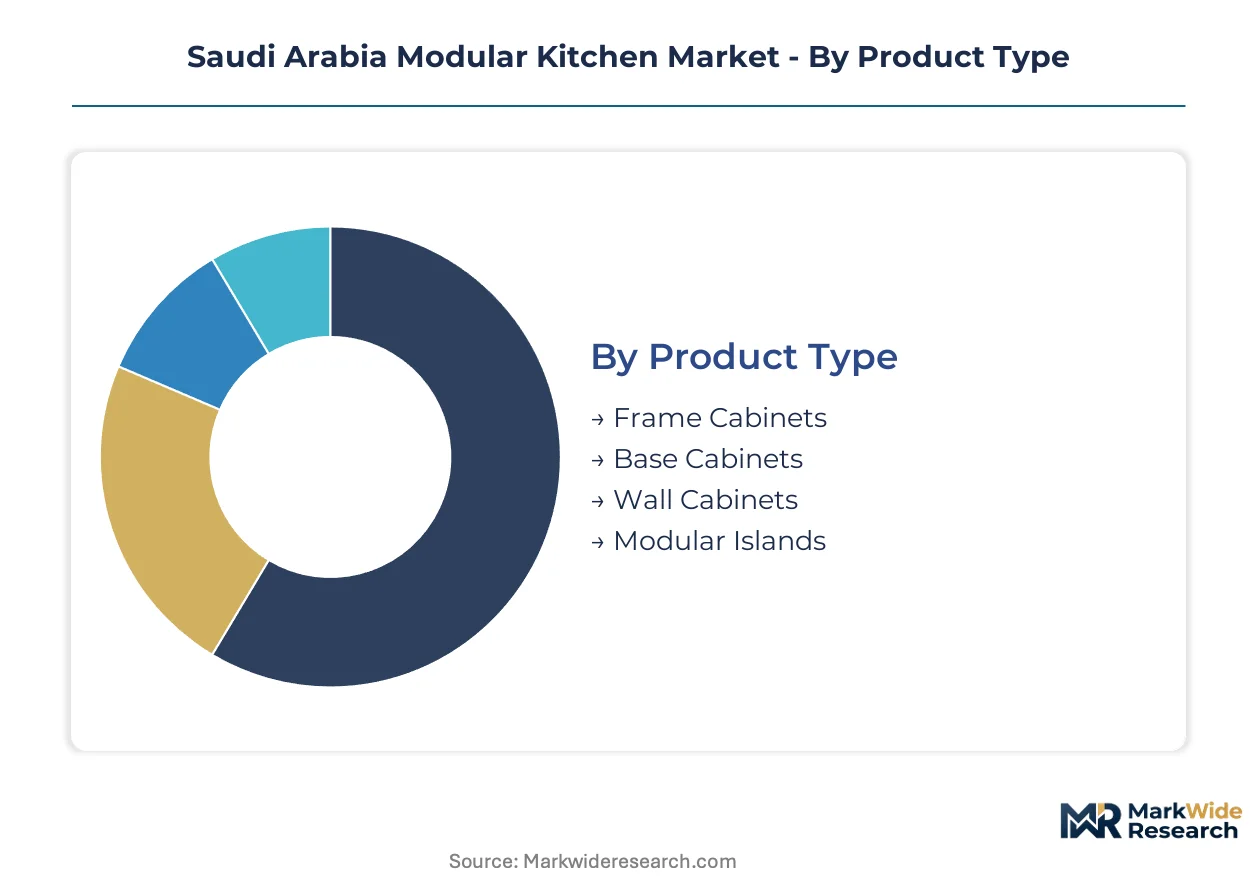
Modular kitchen suppliers in Saudi Arabia face divergent specification requirements across Riyadh's luxury villa pipeline versus Jeddah's heritage-influenced residential clusters. Material selection and design styling decisions cascade through compliance obligations under SASO technical regulations and SFDA surface safety standards. Understanding these segment boundaries enables targeted certification investment and assembly partnership prioritization.
Product Type:
Volume concentrates in standardized cabinetry units while premium project pipelines elevate island configurations as differentiation anchors.
- Frame Cabinets:Aluminum-framed substrates with thermal break engineering withstand Red Sea coastal humidity. Riyadh metropolitan corridor developers specify these for giga-project housing deliveries requiring extended lifecycle performance under Saudi Building Code load-bearing mandates.
- Base Cabinets:Floor-mounted units integrate moisture-resistant engineered wood or metal substrates. Demand clusters in municipal permit pipelines across Riyadh, Jeddah, and Dammam where SASO fire-retardant documentation accompanies every occupancy certification.
- Wall Cabinets:Overhead storage systems anchor kitchen workflow efficiency in compact urban apartments.
- Modular Islands:Freestanding units command specification premiums in luxury villa developments.
Today's leader: Base Cabinets. Tomorrow's challenger: Modular Islands.
Material:
Cost efficiency separates volume segments from margin pools where certification premiums reshape supplier economics.
- Laminate:Heat-tolerant synthetic surfaces dominate unit volume through cost efficiency and climatic durability. SFDA food-contact surface safety clearance requirements compress margins for imported laminate suppliers facing four-to-eight-week customs delays.
- Wood:Natural substrates capture heritage-influenced villa specifications in Jeddah and the Eastern Province. Traditional styling preferences here remain underserved by contemporary-focused product catalogs from major suppliers.
- Metal:Aluminum-framed systems extend replacement cycles in coastal humidity zones.
- Glass:Aesthetic surface treatments anchor premium positioning in Red Sea Project corridors.
Laminate holds volume leadership. Wood segments gain fastest where heritage styling commands specification premiums.
Design Style:
New construction pipelines favor contemporary aesthetics while renovation demand sustains traditional alternatives.
- Modern:Clean-line aesthetics with integrated hardware systems dominate Riyadh giga-project procurement. NEOM and Red Sea Project specifications treat modular kitchens as base build elements rather than fit-out options, standardizing modern styling across integrated living spaces.
- Contemporary:Evolving aesthetic hybrids blend modern functionality with regional material preferences. Jeddah luxury villa developers specify these for coastal properties requiring climate-adaptive engineering without traditional ornamental detailing.
- Traditional:Ornate detailing retains share in heritage-conscious Eastern Province developments.
- Rustic:Textured finishes serve niche vacation property segments in mountainous and desert-edge locations.
Modern styling anchors new construction. Contemporary variants climb fastest as developers seek differentiated premium positioning.
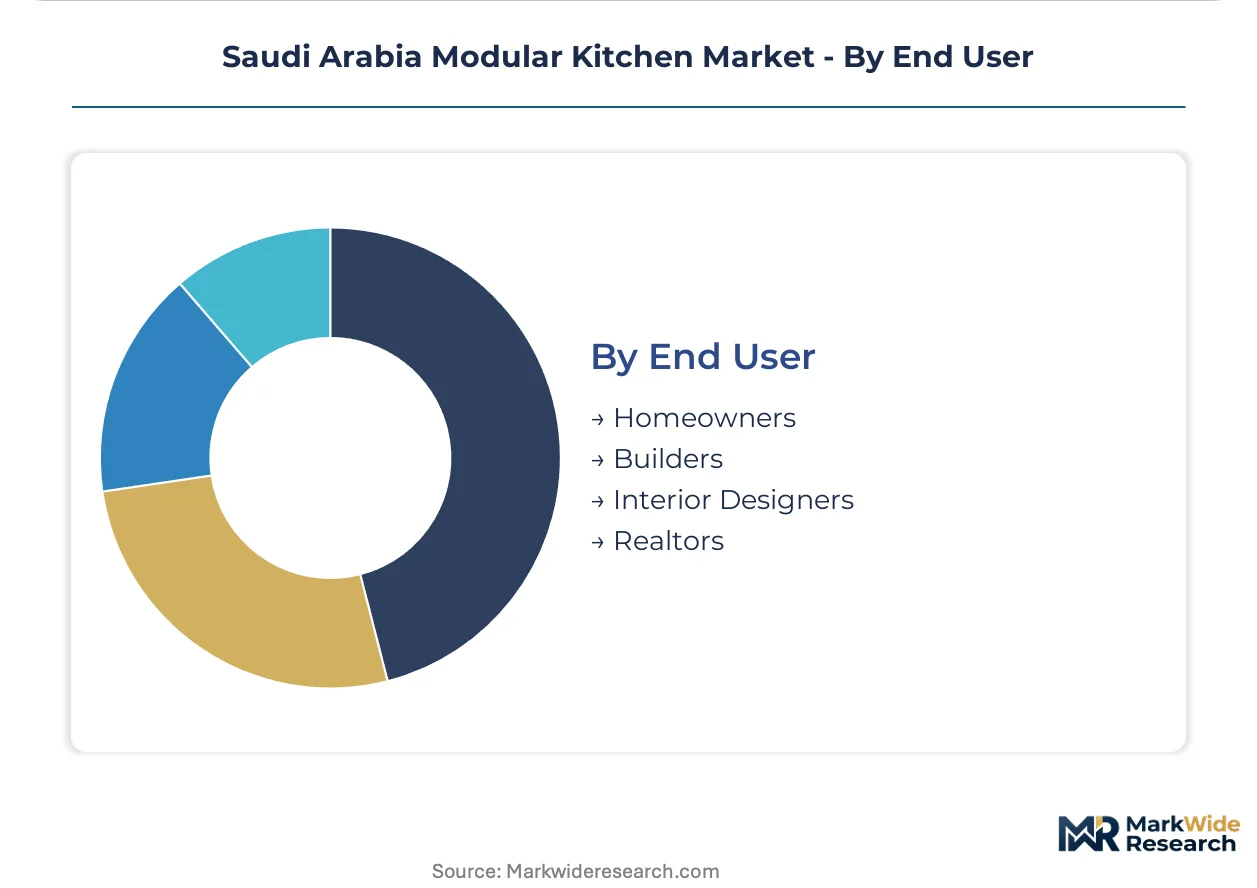
End User:
Procurement authority concentrates with builders while influencer roles fragment across design professionals.
- Builders:Large-scale developers in Riyadh metropolitan corridor consolidate vendor panels around pre-qualified suppliers with in-country assembly capability. Direct factory-site relationships bypass traditional distributor networks entirely.
- Homeowners:Individual purchasers drive replacement demand through IKEA Systems flat-pack logistics and localized assembly partnerships serving price-sensitive segments.
- Interior Designers:Specification influencers in luxury villa projects source imported hardware and surface materials.
- Realtors:Staging requirements for resale properties sustain mid-market modular kitchen refresh cycles.
Builders control volume. Interior designers shape fastest-growing premium specification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's modular kitchen industry traces its commercial scale to the 1970s oil boom, when European kitchen systems first entered the kingdom through Jeddah's port infrastructure. Domestic manufacturing capacity expanded through the 1990s as Riyadh-based fabricators localized assembly operations.
Riyadh
Giga-project housing deliveries compress procurement cycles for certified suppliers. SASO technical regulations mandate fire-retardant documentation for every municipal occupancy permit. The Riyadh metropolitan corridor concentrates vendor panel consolidation around pre-qualified modular kitchen suppliers with in-country assembly capability.
Jeddah
Heritage-influenced villa segments sustain demand for traditional styling that major catalogs underserve. SFDA food-contact surface safety clearance requirements delay imported countertop shipments through the Red Sea port. Western Region developers balance climate-adaptive aluminum framing with ornamental detailing preferences.
Eastern Province
Petrochemical industry executive housing drives premium specification demand in Dammam and Al-Khobar. Municipal permit offices require modular kitchen compliance documentation as a condition for final occupancy certification. Industrial city adjacency supports localized metal fabrication capacity for aluminum-framed substrates.
NEOM Northwest
Giga-project procurement standards treat modular kitchens as base build elements rather than fit-out options. Integrated living space specifications standardize modern styling across residential clusters. Remote site logistics favor flat-pack delivery models with on-site assembly partnerships.
Red Sea Coast
Coastal humidity zones elevate aluminum-framed systems with thermal break engineering over conventional particleboard. Luxury tourism property pipelines specify imported hardware and surface materials. Red Sea Project contractors pre-certify materials under SASO technical regulations before bidding closes.
Saudi Arabia Modular Kitchen Market Competitive Environment
The competitive structure tilts toward domestic manufacturing archetypes with regulatory bypass advantages. Tier-one suppliers anchor project contracts through in-country assembly footprints that circumvent import certification delays. Three strategic archetypes dominate: European luxury specialists, regional manufacturing conglomerates, and flat-pack logistics operators. Consolidation pressures intensify as developer procurement teams narrow vendor panels around pre-qualified partners.
Among domestic manufacturing conglomerates, Al-Muhaidib Group anchors the landscape through its Saudi-based production footprint that bypasses customs delays. Hafele occupies a position exemplifying European hardware specialization with premium positioning through fitting ecosystems. IKEA Systems sits within the flat-pack logistics archetype, navigating price-sensitive segments through localized assembly partnerships.
| Leading Market Players |
|---|
| AlKhaleejion Kitchens |
| Pedini Cucine Saudi Arabia |
| Saudi Kitchen Line Company |
| Al-Muhaidib Group |
| Hafele |
| IKEA Systems |
| Hacker Kitchens |
| Nobilia International |
| Snaidero Kitchens Saudi Arabia |
| Others |
Value Chain & Pricing Dynamics
Captive in-country assembly partnerships anchor supply positions for tier-one suppliers while insulating project margins from SFDA certification delays and customs volatility. Al-Muhaidib Group leverages its Riyadh manufacturing footprint to bypass import documentation bottlenecks that compress pricing power for European competitors.
Pricing Analysis
Bundled installation-and-certification services command premiums over unbundled component supply in municipal permit pipelines across Riyadh, Jeddah, and Dammam. Three-tier pricing structure across premium, standard, and economy levels separates giga-project specifications from mid-market residential and flat-pack consumer segments. Cost compression in standard tiers intensifies as IKEA Systems and local fabricators compete on last-mile efficiency. Homeowners drive price sensitivity through flat-pack logistics, while luxury villa developers absorb certification premiums for imported hardware ecosystems.
Supply Chain Analysis
SASO local-content requirements and Saudi Building Code enforcement are reshaping sourcing patterns toward domestic metal fabrication and engineered wood finishing. European and Southeast Asian substrate manufacturers feed raw material pipelines for laminate surfaces and moisture-resistant particleboard. Adhesive formulation restrictions under VOC emission limits create regulatory friction for low-cost bonding agents. Single-source vulnerability concentrates in aluminum extrusion supply from Gulf Cooperation Council fabricators. Distribution runs through direct factory-site relationships that bypass traditional distributor networks in giga-project corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's modular kitchen market operates as a geographic-arbitrage play where domestic manufacturing footprints capture margin pools unavailable to import-dependent competitors facing SFDA clearance delays.
For Market Incumbents: Lock in pre-qualified vendor panel positions with Riyadh metropolitan corridor developers by expanding in-country assembly capacity ahead of SASO technical regulation updates. Al-Muhaidib Group's captive manufacturing model demonstrates how backward integration into aluminum framing and laminate finishing neutralizes customs volatility threats. Certification investment in SFDA food-contact surface documentation creates switching costs for project procurement teams. For New Entrants and Emerging Players: The premium-to-economy price-point gap in heritage-influenced villa segments offers white-space entry where traditional styling preferences remain underserved by contemporary-focused catalogs. Jeddah and Eastern Province residential clusters present penetrable targets for wood-substrate specialists with ornamental detailing capabilities. Flat-pack logistics partnerships with local assembly networks provide a viable go-to-market angle for mid-market positioning without giga-project procurement access. For Investors and Strategic Acquirers: Roll-up economics work for regional manufacturing conglomerates because municipal permit documentation requirements and certified installer scarcity create barriers that favor scaled domestic players over fragmented import distributors. Acquisition targets should demonstrate in-country assembly footprints and SASO pre-certification workflows. The signal to monitor is giga-project procurement office consolidation patterns around pre-qualified supplier panels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Framing | Captive metal fabrication capacity neutralizes humidity-zone replacement cycles and SASO load-bearing compliance costs. |
| SFDA Pre-Certification Investment | Food-contact surface documentation accelerates customs clearance and compresses project delivery timelines for countertop suppliers. |
| Localized Assembly Partnership Expansion | Flat-pack logistics bypass finished-goods import duties and reduce last-mile costs to remote NEOM and Red Sea construction sites. |
| Heritage Styling Product Line Development | Traditional ornamental detailing captures underserved Jeddah and Eastern Province villa segments bypassed by modern-focused catalogs. |
| Certified Installer Training Pipeline | Municipal occupancy permit requirements create technician scarcity that favors suppliers with documented compliance training programs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with developer procurement teams, municipal building permit officers, modular kitchen fabricators, and interior design specification influencers against secondary validation through SASO technical regulation filings, Saudi Building Code updates, customs import documentation datasets, and giga-project procurement standard disclosures. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across product type, material, design style, and end user segments.
Historical reference periods anchored growth trajectory modeling across the projection horizon, with segmentation dimensions spanning frame cabinet configurations, substrate material grades, climate-adaptive engineering specifications, and procurement authority concentration. CAGRs were derived through regression analysis of permit issuance patterns and housing delivery schedules, incorporating aluminum framing adoption curves and laminate surface certification timelines as industry-specific forecast inputs.
Caveats apply where SASO regulatory updates, SFDA enforcement intensity shifts, or giga-project delivery delays could materially shift the outlook beyond modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Stove Cover Market