
 Europe High-End Furniture Market | 2026-2036
Europe High-End Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe High-End Furniture Market Foresight
Multi-source artisan networks is decoupling from vertically integrated factory models across the European supply base. Roche Bobois leverages a decentralized maker network to sustain design agility across Paris and Milan showrooms. Minotti anchors its output in Brianza-based upholstery ateliers with in-house leather cutting. Natuzzi competes through controlled tanning partnerships in Italy's Puglia region.
Europe high-end furniture comprises premium seating, surfaces, and storage systems engineered to residential and contract interior specifications, typically employing kiln-dried hardwood frames, multi-density foam cushioning, and hand-finished veneers or full-grain leather. These products serve architects, hospitality developers, and private clients seeking durability certification alongside aesthetic distinction. Sofas and armchairs occupy the largest margin pool given upholstery labor intensity and leather grading premiums. Wood-based case goods dominate volume in traditional and rustic styling channels across Central European markets. Online retail and custom commission channels are expanding fastest as digital visualization tools reduce specification friction for remote buyers.
The EU Green Deal's embodied-carbon tracking requirements and ECHA REACH chemical restrictions on finishes are elevating compliance costs for imported components while favoring FSC-certified European timber suppliers. CE marking under the Construction Products Regulation governs fire-resistance ratings for contract furniture deployed in public buildings. Stakeholders must monitor how CSRD supply-chain disclosure rules reshape procurement scoring for hospitality and corporate fit-out projects.
Market Dynamics
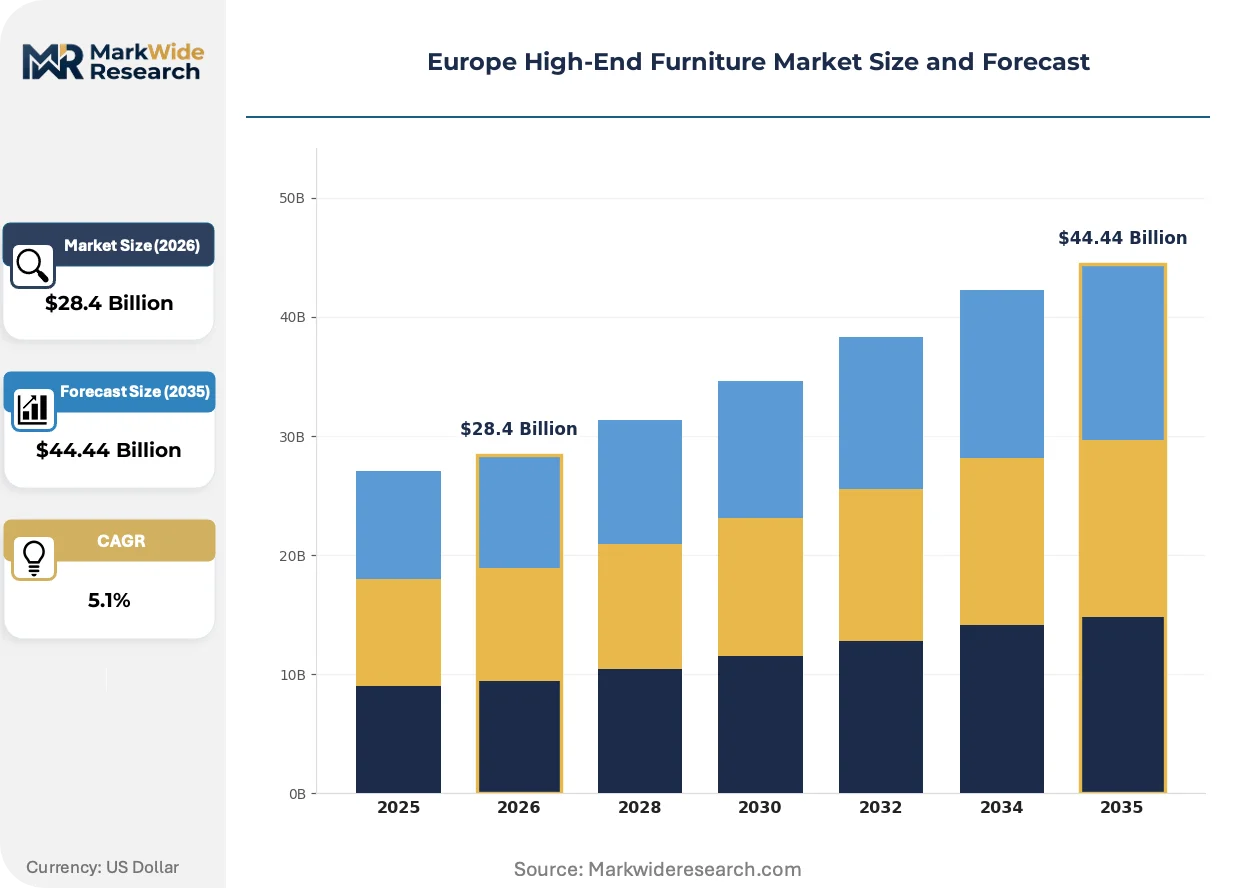
The EU Green Deal's embodied-carbon disclosure mandate is redirecting specification authority toward certified European timber suppliers and away from import-dependent manufacturers. This regulatory pivot is compressing margins for non-compliant producers while concentrating procurement power with hospitality developers and corporate fit-out managers who face CSRD supply-chain reporting obligations.
Growth Catalysts
- Hospitality refurbishment cycles:German and French hotel operators are replacing interior suites at accelerated cadences to meet sustainability certification thresholds for premium properties.
- ECHA REACH chemical restrictions:Finish coating standards are elevating demand for water-based European alternatives, favoring domestic finishing ateliers over Asian import suppliers.
- Brianza manufacturing cluster density:Northern Italy's concentration of automated cutting systems alongside artisan upholstery workshops enables rapid custom prototyping for architect-specified contract projects.
Market Restraints
- Full-grain leather supply concentration:Italian tanneries in Puglia and Tuscany control premium hide sourcing, creating input cost volatility for seating manufacturers without captive tanning partnerships.
- FSC-certified timber scarcity:Certified European hardwood availability lags specification demand from hospitality developers pursuing BREEAM and LEED building certifications.
- CE marking compliance complexity:Fire-resistance testing under the Construction Products Regulation imposes multi-month certification timelines for contract furniture entering public building projects.
Strategic Opportunities
- Eastern European manufacturing expansion:Romania and Poland offer lower-cost finishing capacity for standard-grade case goods serving Central European retail channels.
- Digital visualization platforms:Real-time rendering tools are compressing specification cycles for remote private clients and architect firms in secondary European cities.
- CSRD procurement scoring:Corporate sustainability reporting requirements are creating preference windows for furniture suppliers with verified supply-chain carbon accounting.
Industry Challenges
- Upholstery craft labor scarcity:Multi-density foam hand-finishing and eight-way hand-tied spring systems require skilled artisans whose training pipelines have contracted across Italy and Portugal.
- Legacy ERP integration friction:Brianza-based workshops migrating from paper-based order systems to cloud-based specification platforms face workflow disruption during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe High-End Furniture Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.44 Billion |
| CAGR (2026 – 2036) | 5.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Sofas, Cabinets Material: Wood, Metal, Glass, Leather Style: Modern, Contemporary, Traditional, Rustic Distribution Channel: Online Retail, Showrooms, Wholesale, Custom |
| Companies Covered | Giorgio Armani, BoConcept, Roche Bobois, Casamilano, Porada, Minotti, Eichholtz, Capital, Natuzzi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe High-End Furniture Market Shifts & Advancements
Digital specification tools and carbon-accounting mandates are converging to reshape how high-end furniture reaches architects and hospitality developers across European markets.
Parametric design software paired with CNC routing systems is absorbing traditional hand-carving workflows in wood case goods production. Italian manufacturers serving Milan and Paris showrooms are deploying these systems for rapid prototype iteration on architect-commissioned pieces. The technology is absorbing weeks from traditional sample-to-production timelines while preserving surface finish quality indistinguishable from handwork.
EU Green Deal embodied-carbon tracking requirements are mandating lifecycle disclosure for building products entering public procurement. Furniture suppliers must now document kiln-drying energy inputs, finish chemical content, and transport emissions to qualify for hospitality and corporate fit-out tenders. Northern European markets, particularly Denmark and Sweden, are enforcing the strictest verification thresholds, pushing specification decisions toward domestic and near-shore suppliers.
Architect-led procurement consortiums are consolidating purchasing power for large-scale hospitality and residential tower projects. These buying groups are disintermediating traditional showroom networks by negotiating directly with Brianza manufacturers for bespoke interior packages. The model is most advanced in German-speaking markets, where developer-architect relationships dominate premium residential construction.
Europe High-End Furniture Market Segmentation
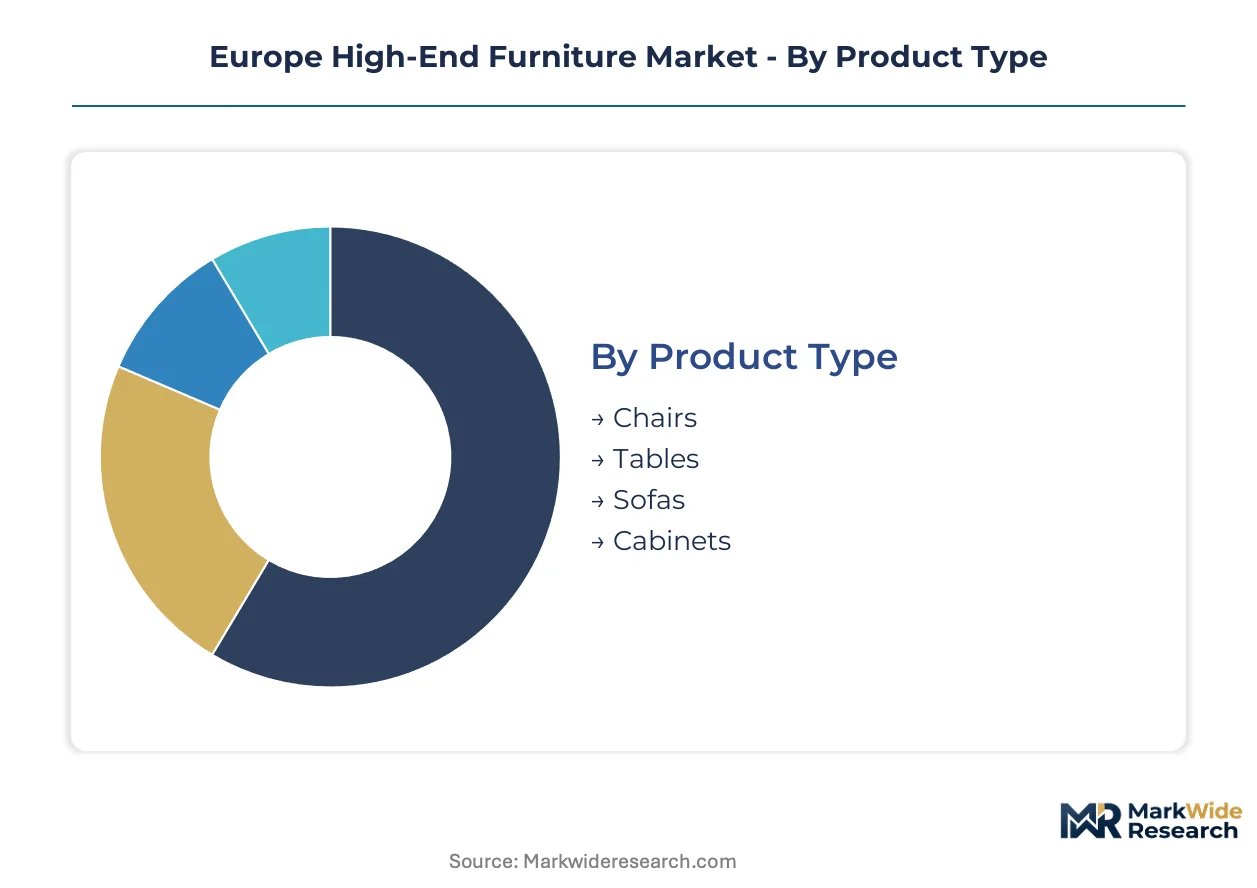
Segmentation in European high-end furniture reveals how procurement authority splits between hospitality developers seeking contract durability and private clients prioritizing bespoke craftsmanship. Specification decisions increasingly hinge on embodied-carbon credentials and digital visualization capabilities rather than traditional showroom relationships.
Product Type:
Replacement cycles in hospitality and residential sectors concentrate upgrade spending on seating and surface categories that absorb daily wear while defining interior aesthetics.
- Sofas:Multi-density foam cushioning systems with kiln-dried hardwood frames command premium pricing through upholstery labor intensity and full-grain leather grading differentials. German hotel operators and Parisian residential developers drive specification volume for modular contract configurations that withstand accelerated refurbishment timelines.
- Tables:Dining and conference surfaces employ engineered stone, solid timber, or metal substrates with parametric CNC-routed bases for architect-commissioned pieces. Brianza manufacturers pair automated cutting with hand-finishing to compress prototype-to-production cycles for Milan and Paris showroom collections.
- Chairs:Upholstered dining and occasional seating requires eight-way hand-tied spring systems whose craft labor scarcity constrains output across Italian and Portuguese workshops.
- Cabinets:Wood-based case goods dominate volume in Central European traditional styling channels through standardized dimensions for retail distribution.
Sofas sit at the top of the volume ranking, with tables climbing the fastest as architect-led procurement consortiums consolidate surface specification for hospitality projects.
Material:
Cost tier differentiation separates certified sustainable inputs from conventional alternatives as EU Green Deal disclosure rules reshape procurement scoring.
- Wood:FSC-certified European hardwood faces availability constraints against hospitality developer demand for BREEAM and LEED building certifications. Kiln-drying energy inputs must now document lifecycle emissions under embodied-carbon tracking mandates, favoring domestic suppliers over import-dependent manufacturers.
- Leather:Italian tanneries in Puglia and Tuscany control premium hide sourcing, creating input cost volatility for seating manufacturers without captive tanning partnerships or controlled supply agreements.
- Metal:Recycled aluminum and steel frames gain specification share in contemporary styling channels through lower embodied-carbon profiles versus virgin material extraction.
- Glass:Tempered and laminated surfaces serve occasional tabletops and display casework in modern styling segments with limited contract penetration.
Wood holds the largest share by specification volume, while metal gains share fastest as carbon-accounting transparency reshapes material selection criteria.
Style:
Customer type segmentation splits between hospitality developers pursuing contemporary standardization and residential clients seeking traditional or rustic differentiation.
- Contemporary:Clean-lined silhouettes with minimal ornamentation dominate contract hospitality specifications across German and French premium properties. Brianza manufacturers deploy parametric design software paired with CNC routing to absorb traditional hand-carving workflows while preserving surface finish quality.
- Modern:Mid-century influenced forms with exposed structural elements concentrate in urban residential towers and boutique hotel lobbies where architect-specified pieces define brand identity.
- Traditional:Ornate carving and classical proportions retain volume in Central European retail channels through standardized case goods production.
- Rustic:Distressed finishes and reclaimed material aesthetics serve secondary city residential markets with lower contract penetration.
Contemporary styling leads by hospitality contract value, with modern segments expanding most quickly in residential tower developments across Northern European markets.
Distribution Channel:
Supply concentration in Northern Italy's manufacturing cluster enables channel differentiation based on specification complexity and client proximity.
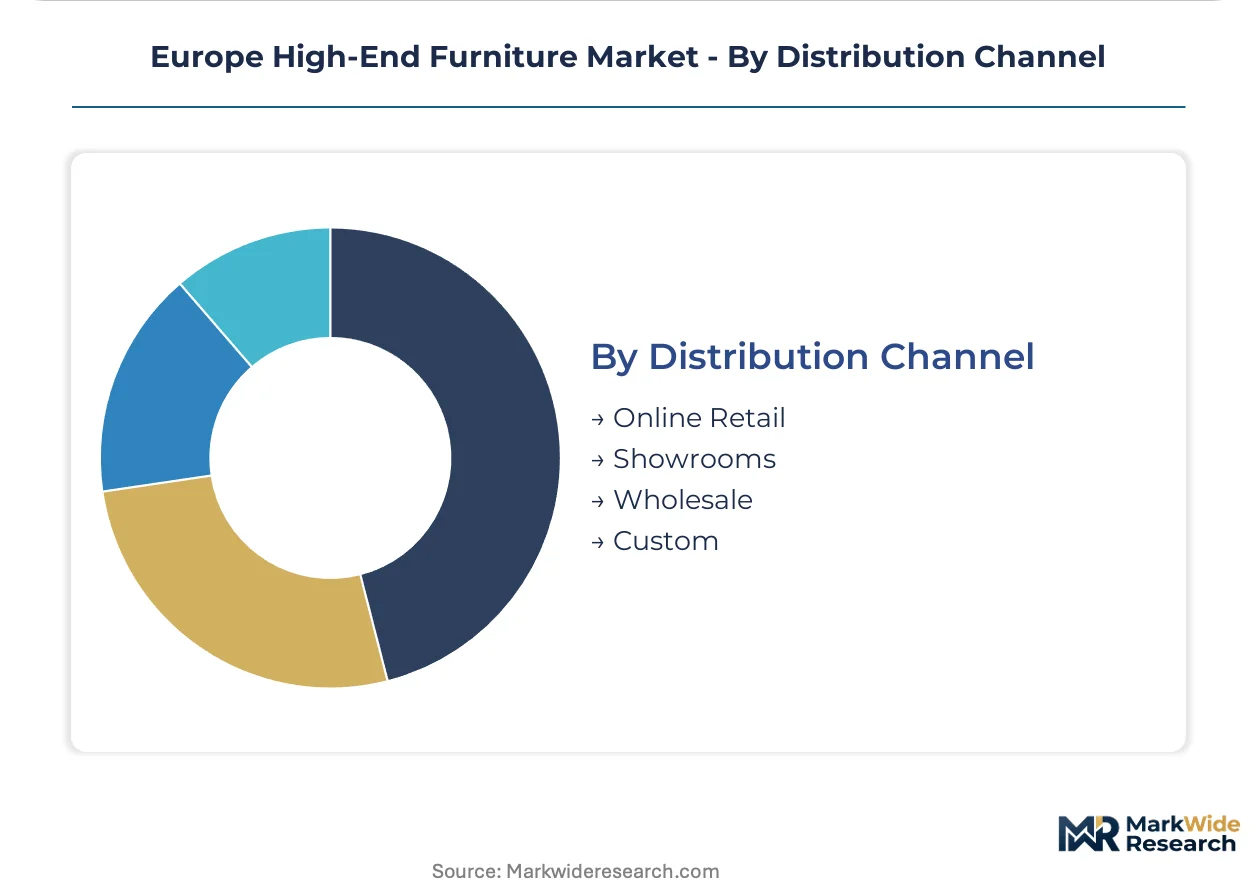
- Custom:Architect and interior designer commissions for bespoke interior packages bypass traditional showroom networks through direct Brianza manufacturer negotiation. German-speaking markets advance this model most rapidly where developer-architect relationships dominate premium residential construction.
- Online Retail:Digital visualization platforms compress specification cycles for remote private clients through real-time rendering tools that reduce friction in leather grading and finish selection.
- Showrooms:Paris and Milan flagship locations sustain design agility through decentralized maker networks that prototype rapidly for immediate client feedback.
- Wholesale:Standard-grade case goods for Central European retail channels leverage lower-cost finishing capacity in Romania and Poland.
Custom channels command the highest average transaction value, with online retail climbing the fastest as visualization technology matures for remote specification confidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brianza's manufacturing cluster anchors European high-end furniture output, with artisan workshops and automated finishing lines serving architect-specified contract projects across the continent. Procurement authority concentrates with hospitality developers and corporate fit-out managers navigating CSRD supply-chain disclosure obligations. Specification decisions increasingly favor domestic and near-shore suppliers capable of documenting embodied-carbon credentials under EU Green Deal mandates.
Germany
Hospitality operators in Berlin and Munich are accelerating interior suite replacement cycles to meet sustainability certification thresholds for premium properties. The country's national building regulator enforces strict fire-resistance standards under harmonized EU construction product rules, compressing timelines for contract furniture entering public procurement. North Rhine-Westphalia hosts several finishing ateliers supplying water-based coating alternatives compliant with ECHA REACH chemical restrictions.
Italy
Milan and Paris showroom networks rely on Brianza-based upholstery workshops for rapid custom prototyping of architect-commissioned pieces. CE marking under the Construction Products Regulation governs fire-resistance ratings for contract furniture deployed in hospitality developments across Italian metropolitan markets. Lombardy's manufacturing corridor sustains the continent's densest concentration of automated cutting systems alongside traditional hand-finishing craft.
France
Parisian residential developers and boutique hotel operators drive specification volume for modular contract seating configurations. The country's national environmental agency implements embodied-carbon disclosure protocols aligned with EU Green Deal building product requirements, elevating compliance costs for import-dependent manufacturers. Île-de-France maintains flagship showroom locations leveraging decentralized maker networks for design agility.
United Kingdom
London-based architect-led procurement consortiums are consolidating purchasing power for large-scale residential tower projects, disintermediating traditional showroom networks. The country's national standards body oversees construction product safety marking regimes post-EU withdrawal, creating parallel compliance pathways for contract furniture entering public buildings. Southeast England hosts several specification firms negotiating directly with Northern Italian manufacturers for bespoke interior packages.
Poland
Standard-grade case goods producers serving Central European retail channels are expanding finishing capacity to capture volume displaced by sustainability-driven specification shifts in Western markets. The country's national standards institute coordinates with EU bodies on construction product regulation alignment, facilitating cross-border trade in certified timber frames. Lower Silesia and Greater Poland regions offer lower-cost production alternatives for non-contract residential furniture distribution.
Europe High-End Furniture Market Competitive Landscape
Global majors compete with regional champions across design heritage and supply-chain proximity dimensions, producing a tiered structure where Italian artisan networks coexist with Scandinavian retail-scale operators. Market concentration reflects geographic clustering rather than scale economics, with Brianza-based workshops commanding premium positioning through craft labor scarcity. Three archetypes dominate: heritage design houses with showroom networks, manufacturing specialists with captive material partnerships, and retail-scale operators with digital visualization platforms. Competitive moves center on backward integration into tanning and timber supply, plus architect-direct procurement relationship cultivation.
Among Italian heritage fabricators, Minotti S.p.A. and Natuzzi S.p.A. exemplify the manufacturing-specialist archetype through their positioning within Northern Italy's upholstery and leather processing corridors. Roche Bobois represents the showroom-network model with its decentralized maker relationships sustaining design agility across metropolitan European markets. These three entities anchor the competitive landscape without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Giorgio Armani |
| BoConcept |
| Roche Bobois |
| Casamilano |
| Porada |
| Minotti |
| Eichholtz |
| Capital |
| Natuzzi |
| Others |
Supply & Pricing Matrix
Parametric CNC routing absorption of hand-carving workflows simultaneously compresses prototype-to-production timelines and concentrates premium pricing power with Brianza manufacturers capable of rapid architect-specified iteration. This technology shift elevates cost efficiency for Italian workshops while embedding scarcity premiums for traditional upholstery craft labor across Puglia and Tuscany tanning partnerships.
Pricing Analysis
Input-cost pass-through from Italian tanneries and FSC-certified European timber suppliers drives pricing stratification across premium, standard, and economy tiers. Full-grain leather grading differentials and kiln-drying energy disclosure requirements separate certified sustainable seating from conventional alternatives. Pricing pressure stems from ECHA REACH compliance costs elevating water-based finish premiums. Hospitality developers show least price sensitivity given CSRD procurement scoring obligations, while Central European retail channels absorb most margin compression.
Supply Chain Analysis
Dual-sourcing requirements from hospitality developers and corporate fit-out managers mandate multi-supplier qualification across Italian, Romanian, and Polish manufacturing bases. Supply chains draw from Puglia tanning partnerships, Lombardy automated cutting systems, and Eastern European finishing capacity for standard-grade case goods. Single-source vulnerability concentrates in premium hide supply controlled by Tuscan tanneries. Distribution runs through architect-direct procurement consortiums, Paris and Milan showroom networks, and digital visualization platforms serving remote private clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
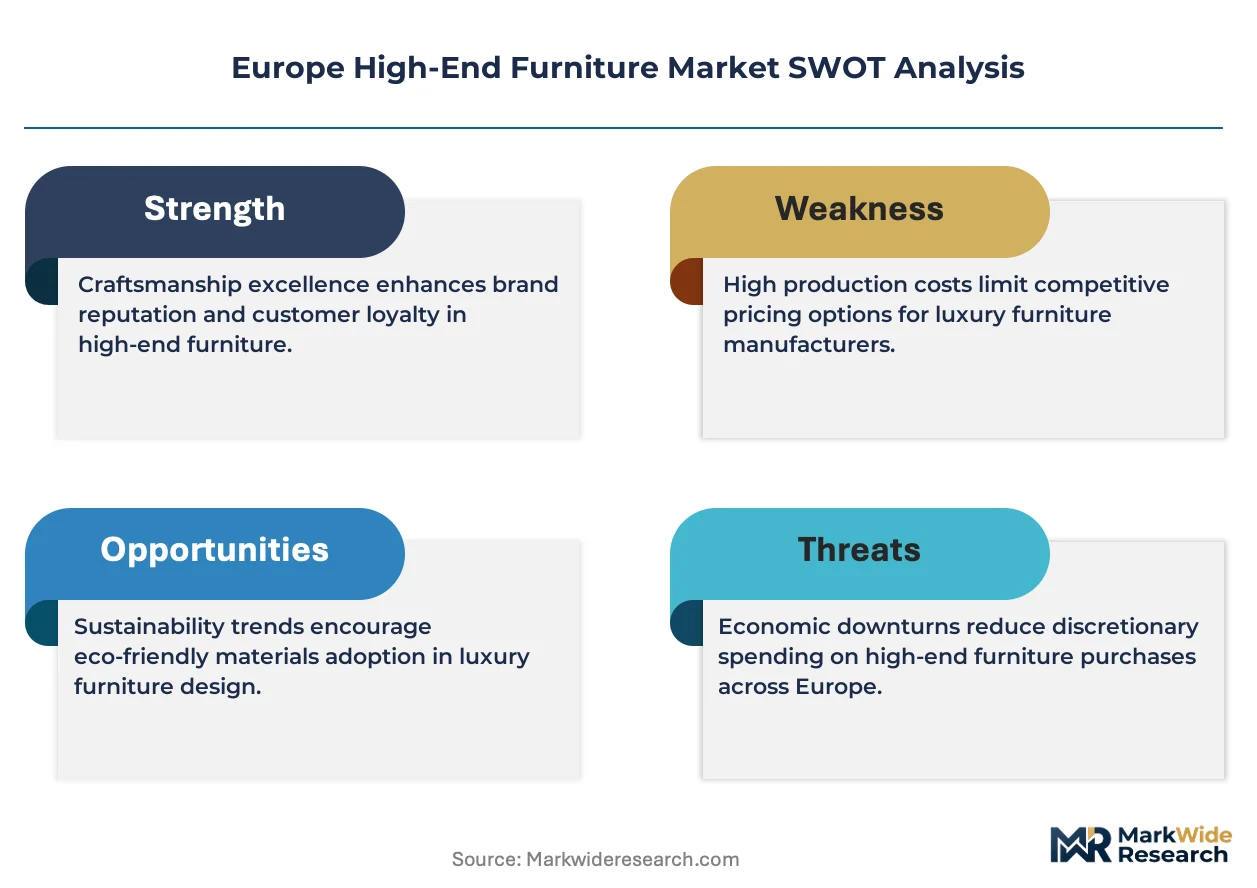
The Europe high-end furniture market functions as a stable compounder where hospitality refurbishment cycles and regulatory disclosure mandates generate predictable specification volume. EU Green Deal embodied-carbon tracking creates durable preference windows for compliant domestic suppliers.
For Market Incumbents: Acquire captive tanning partnerships in Italy's Puglia region to secure full-grain leather supply against input cost volatility from Tuscan tannery concentration. Invest in Brianza-based CNC routing capacity to absorb hand-carving workflows while preserving artisan upholstery craft differentiation threatened by labor scarcity across Italian and Portuguese workshops. For New Entrants and Emerging Players: Capture specification share in Polish and Romanian finishing capacity for standard-grade case goods serving Central European retail channels displaced by sustainability-driven procurement shifts in Western markets. Deploy digital visualization platforms targeting remote private clients in secondary European cities where architect relationships remain underdeveloped. For Investors and Strategic Acquirers: Roll-up economics work for Brianza-based manufacturing specialists with captive material partnerships because craft labor scarcity and regulatory compliance barriers protect margin structures from commoditization. Monitor CSRD supply-chain disclosure adoption rates across German hospitality developers as the inflection indicator for procurement scoring preference windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tanning | Secures Puglia hide supply against Tuscan tannery concentration volatility. |
| CNC Routing Capacity Expansion | Compresses Milan and Paris showroom prototype-to-production timelines for architect commissions. |
| Digital Visualization Platform Launch | Reduces specification friction for remote private clients in secondary European cities. |
| FSC Certification Investment | Qualifies for BREEAM and LEED procurement scoring in hospitality developer tenders. |
| Eastern European Manufacturing Footprint | Captures standard-grade case goods volume displaced by Western sustainability mandates. |
Research Methodology
Coverage spans Germany, Italy, France, the United Kingdom, and Poland, with primary inputs from each market combining interviews with hospitality procurement directors, architect consortium leads, Brianza manufacturer operations heads, leather tanning supply managers, and furniture showroom network directors. Secondary validation draws from EU construction product regulation filings, ECHA REACH substance databases, FSC chain-of-custody certification records, and hospitality sustainability certification registries. Bottom-up and top-down triangulation reconciles manufacturer shipment data with end-use specification tracking.
Rate-of-change decomposition across product type, material certification tier, styling segment, and distribution channel dimensions structures the analytical framework throughout the forecast period. CAGRs derive from segment-level volume and value build-ups incorporating hospitality refurbishment cycle timing, regulatory compliance cost trajectories, and digital channel adoption curves specific to high-end furniture specification behavior.
Regulatory enforcement delays, leather supply disruptions from Italian tannery consolidation, and hospitality development financing constraints are the dominant revision risks to the outlook. Deviation in EU Green Deal embodied-carbon disclosure implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America Furniture Market
Furniture
North America RTA Furniture Market
Furniture
Bar Stools Market
Furniture
India Luxury Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
Study Carrels Market
Furniture
Back Mount Frames Market
Furniture
Europe School Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
Mexico Home Furniture Market
Furniture
Wood Furniture Market
Furniture
Portering Chair Market
Furniture
US Secondary Wood Products Market
Furniture
High Density Fiberboard (HDF) Market