
 India Decorative Laminates Market | 2026-2036
India Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
India Decorative Laminates Market Insights
A capital-intensity divergence between integrated resin producers and trading-dependent converters is reorganizing competitive tiers in India's decorative laminates sector. Merino Laminates leverages captive kraft paper manufacturing to control raw material costs across its Gujarat and Punjab plants. Greenlam Industries sustains R&D spending on antimicrobial and fingerprint-resistant surfaces, differentiating its portfolio in premium residential projects. Stylam Industries anchors export volumes to the Middle East and Africa, occupying a niche that domestic-focused rivals navigate less aggressively.
Decorative laminates are multi-layered thermosetting resin-impregnated sheets, typically comprising kraft paper core layers topped with decorative printed paper and a transparent melamine overlay, cured under heat and pressure to form rigid, wear-resistant surfaces. These materials serve primarily as surfacing solutions for furniture, interior paneling, and flooring applications where abrasion resistance, hygiene, and aesthetic replication of wood or stone are required. High-Pressure Laminates dominate volume shipments due to their superior durability in commercial and institutional environments where replacement cycles must extend beyond fifteen years. Specialty Laminates, including electrostatic-dissipative and chemical-resistant grades, represent the fastest-expanding margin pool as pharmaceutical laboratories and electronics cleanrooms specify certified surfacing under BIS and ISO frameworks. The Furniture application segment absorbs the largest share of domestic output, though Interior Walls is gaining share as architects specify laminate cladding for hotel lobbies and corporate reception areas.
BIS mandates on formaldehyde emission limits and fire-retardant classifications are elevating compliance costs for smaller laminate presses while creating market access barriers for uncertified imports. The Bureau of Energy Efficiency and state-level pollution control boards are tightening effluent and emissions standards for phenol-formaldehyde resin production, concentrating supply among integrated manufacturers with captive chemical plants. Stakeholders must monitor BIS revision timelines for antimicrobial surface standards and assess backward integration into decorative paper printing to capture margin pools currently controlled by European and East Asian suppliers.
Market Dynamics
BIS certification mandates on fire-retardant grades and formaldehyde emission limits are compressing the supplier base, concentrating production among integrated manufacturers with captive resin and paper operations while marginalizing trading-dependent converters.
Growth Catalysts
- Residential Real Estate Expansion:Modular kitchen and wardrobe specifications in western India's construction pipeline are absorbing record laminate volumes from Gujarat and Maharashtra manufacturing clusters.
- Bureau of Energy Efficiency Standards:Tightening effluent controls on phenol-formaldehyde resin production favor integrated producers with captive chemical plants and pollution control infrastructure.
- Antimicrobial Surface Certification:BIS revision timelines for antimicrobial standards are creating first-mover advantages for domestic manufacturers investing in certified R&D lines.
Market Restraints
- Kraft Paper Import Dependency:Decorative paper printing and overlay supplies remain concentrated with European and East Asian suppliers, exposing converters to currency and shipping cost volatility.
- Substitution by Engineered Quartz:Premium residential kitchen surfaces increasingly specify engineered stone for countertop applications, compressing laminate share in high-value installations.
- Capital Intensity of Backward Integration:Captive kraft paper and resin production requires substantial fixed-asset deployment that trading-dependent converters cannot finance.
Strategic Opportunities
- Export Expansion to Middle East and Africa:Uncertified Indian laminate volumes face limited competition in price-sensitive African markets where BIS-grade certification holds less procurement weight.
- Electronics Cleanroom Surfacing:Electrostatic-dissipative laminates for pharmaceutical laboratories and semiconductor fabrication facilities command certified-premium positioning under ISO cleanroom frameworks.
- Hotel and Corporate Interior Cladding:Interior wall applications in hospitality and commercial reception areas are specifying laminate cladding as a cost-efficient alternative to stone or wood paneling.
Industry Challenges
- Skilled Press Operator Shortage:Heat-and-pressure calibration expertise for multi-layer thermosetting cure cycles remains scarce outside established Gujarat and Punjab manufacturing belts.
- BIS Certification Timeline Compression:Fire-retardant and antimicrobial testing protocols extend product launch cycles, delaying revenue recognition for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Decorative Laminates Market |
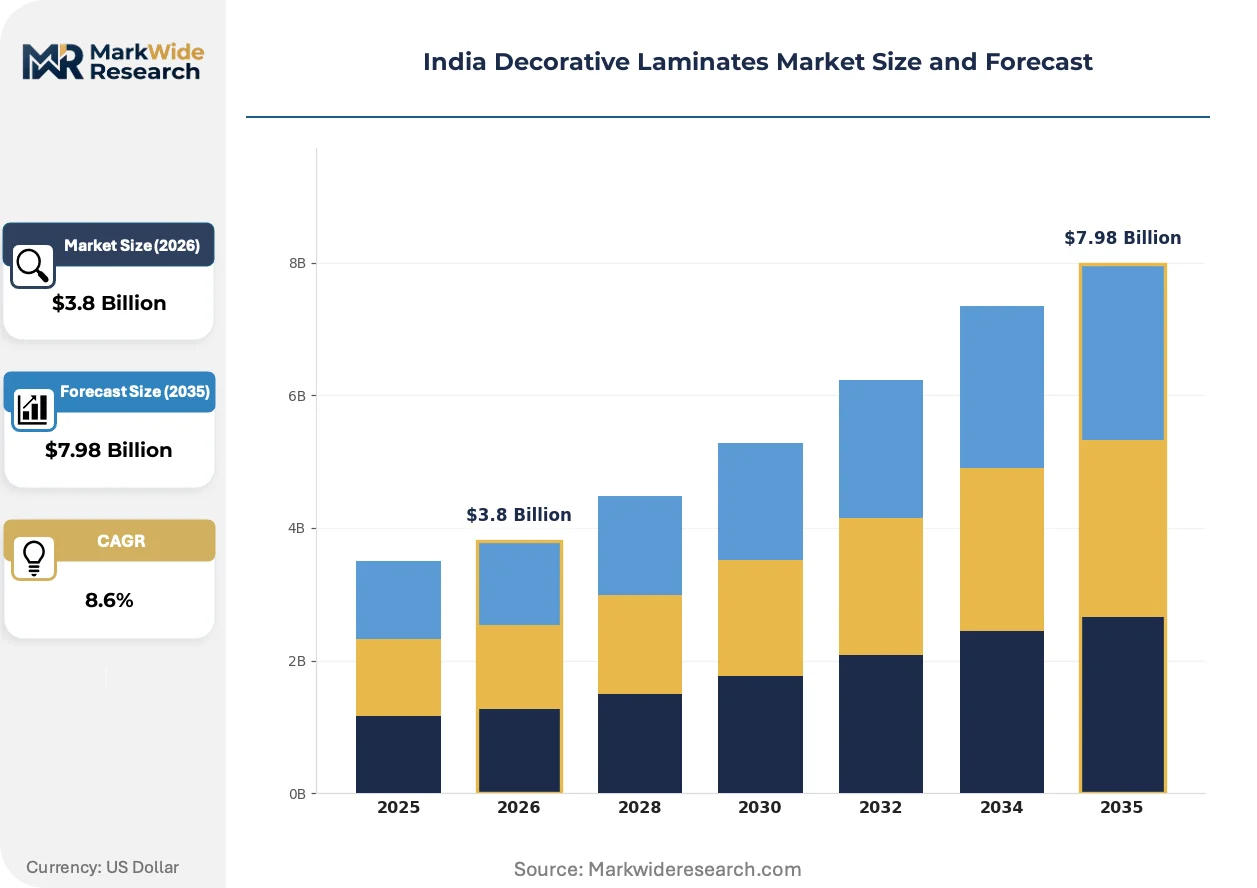
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminates, Low-Pressure Laminates, Backed Laminates, Specialty Laminates Material: Wood, Plastic, Metal, Glass End User: Residential, Commercial, Institutional, Hospitality Application: Furniture, Interior Walls, Flooring, Ceilings |
| Companies Covered | Stylam Industries, Formica India, Greenlam Industries, Durian Laminates, Rushil Decor, Merino Laminates, AICA Sunmica, Airo Lam, Century Laminates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Decorative Laminates Market Trends and Innovations
Digital printing technology and automated resin impregnation lines are compressing batch sizes and expanding design variety, while regulatory pressure on emissions and certification standards is accelerating capital deployment toward integrated manufacturing.
Digitally printed decorative paper is displacing gravure-printed overlays in mid-tier residential applications. Furniture manufacturers in Gujarat are adopting short-run digital presses to offer customized wood-grain and stone patterns without cylinder changeover costs. This technology is displacing traditional high-volume print runs and enabling made-to-order laminate production for modular kitchen OEMs.
BIS mandates on formaldehyde emission limits are elevating compliance costs for phenol-formaldehyde resin formulations. Manufacturers with captive resin plants are reformulating binder chemistry to meet E1 and E0 grade specifications. Smaller laminate presses without laboratory testing capabilities are exiting certified-grade production, consolidating market access among integrated producers.
Direct procurement relationships between real estate developers and laminate manufacturers are compressing distributor margins in western India. Large residential projects in Maharashtra are negotiating volume contracts with Gujarat-based integrated producers, bypassing traditional trading channels. This pattern concentrates procurement leverage with construction firms and erodes converter margins in Mumbai and Pune distribution networks.
India Decorative Laminates Market Segmentation
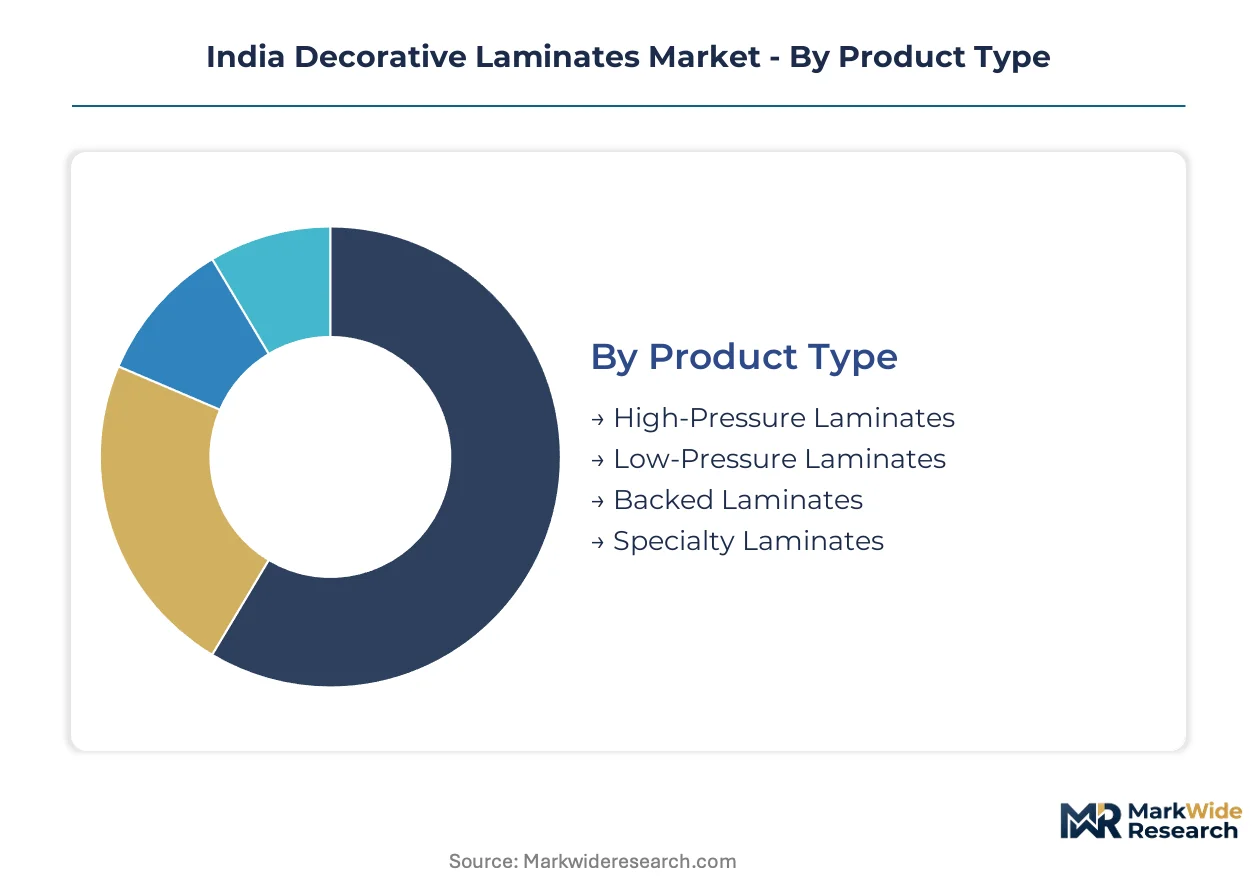
Segmentation in India's decorative laminates market reveals how BIS certification tiers and manufacturing integration levels partition procurement decisions across construction verticals. Each dimension exposes distinct margin structures and compliance burdens that reshape competitive positioning among Gujarat and Maharashtra producers.
Product Type:
BIS fire-retardant and formaldehyde emission standards create divergent compliance costs across laminate pressure classes, concentrating certified production among integrated manufacturers with captive resin operations.
- High-Pressure Laminates:Multi-layer thermosetting sheets cured under heat and pressure above 70 kg/cm², delivering superior abrasion resistance and dimensional stability. Maharashtra and Gujarat furniture manufacturers specify these grades for modular kitchens and institutional installations where BIS certification mandates extend replacement cycles beyond fifteen years.
- Specialty Laminates:Electrostatic-dissipative and chemical-resistant grades engineered for pharmaceutical cleanrooms and electronics fabrication facilities. ISO-certified semiconductor facilities in Bengaluru and Hyderabad are driving procurement of these premium grades under BIS antimicrobial surface revision timelines.
- Low-Pressure Laminates:Decorative surfaces bonded directly to substrates without separate pressing, serving cost-sensitive residential cabinetry in tier-2 and tier-3 cities.
- Backed Laminates:Pre-glued reverse surfaces for simplified field installation, penetrating the renovation and repair segment across western India.
High-Pressure Laminates handles the majority of throughput; Specialty Laminates is the fastest mover on share.
Material:
Raw material selection determines the resin chemistry and pressing parameters required for BIS-compliant finished surfaces, with wood-based substrates dominating volume economics.
- Wood:Kraft paper core layers impregnated with phenol-formaldehyde binders, topped with decorative melamine overlays. Gujarat integrated producers control this segment through captive paper manufacturing at plants in Morbi and Gandhidham, insulating against import volatility.
- Plastic:PVC and PET-based decorative films for moisture-resistant applications in coastal Maharashtra and Kerala residential projects.
- Metal:Aluminum and steel composite laminates for high-traffic commercial interiors and elevator cladding in Mumbai and Delhi NCR corporate towers.
- Glass:Tempered glass decorative laminates for premium hospitality reception areas and luxury residential feature walls.
Wood absorbs the dominant production volume; Metal is climbing the fastest as commercial interior specifications harden.
End User:
Procurement scale and certification requirements vary sharply across customer categories, with institutional buyers enforcing the most stringent BIS documentation protocols.
- Residential:Individual homeowners and apartment developers specifying laminates for kitchens, wardrobes, and interior paneling. Western India real estate developers in Pune and Ahmedabad are negotiating direct volume contracts with integrated Gujarat manufacturers, bypassing traditional distribution channels.
- Commercial:Office fit-outs, retail stores, and banking halls requiring fire-retardant grades under BIS IS 2046 standards. Mumbai and Bengaluru corporate reception areas are specifying laminate wall cladding as cost-efficient alternatives to stone.
- Institutional:Schools, hospitals, and government buildings with mandatory BIS certification for public safety compliance.
- Hospitality:Hotels and restaurants prioritizing antimicrobial surfaces and design flexibility for rapid renovation cycles.
Residential commands the largest share of domestic absorption; Hospitality is expanding most quickly on specification upgrades.
Application:
Surface performance requirements and replacement cycle expectations differ fundamentally across installation locations, driving grade selection and pricing stratification.
- Furniture:Cabinetry, tabletops, and storage systems requiring scratch-resistant and moisture-tolerant surfaces. Modular kitchen OEMs in Gujarat manufacturing clusters are absorbing record laminate volumes as residential real estate developers scale procurement for western India construction pipelines.
- Interior Walls:Vertical cladding for lobbies, corridors, and feature walls where aesthetic replication of wood or stone is prioritized. Hotel operators in Maharashtra and Goa are specifying these applications for cost-efficient renovation against engineered stone alternatives.
- Flooring:Wear-layer surfaces for commercial and institutional high-traffic zones with specific abrasion resistance ratings.
- Ceilings:Acoustic and decorative suspended panels for office and hospitality environments.
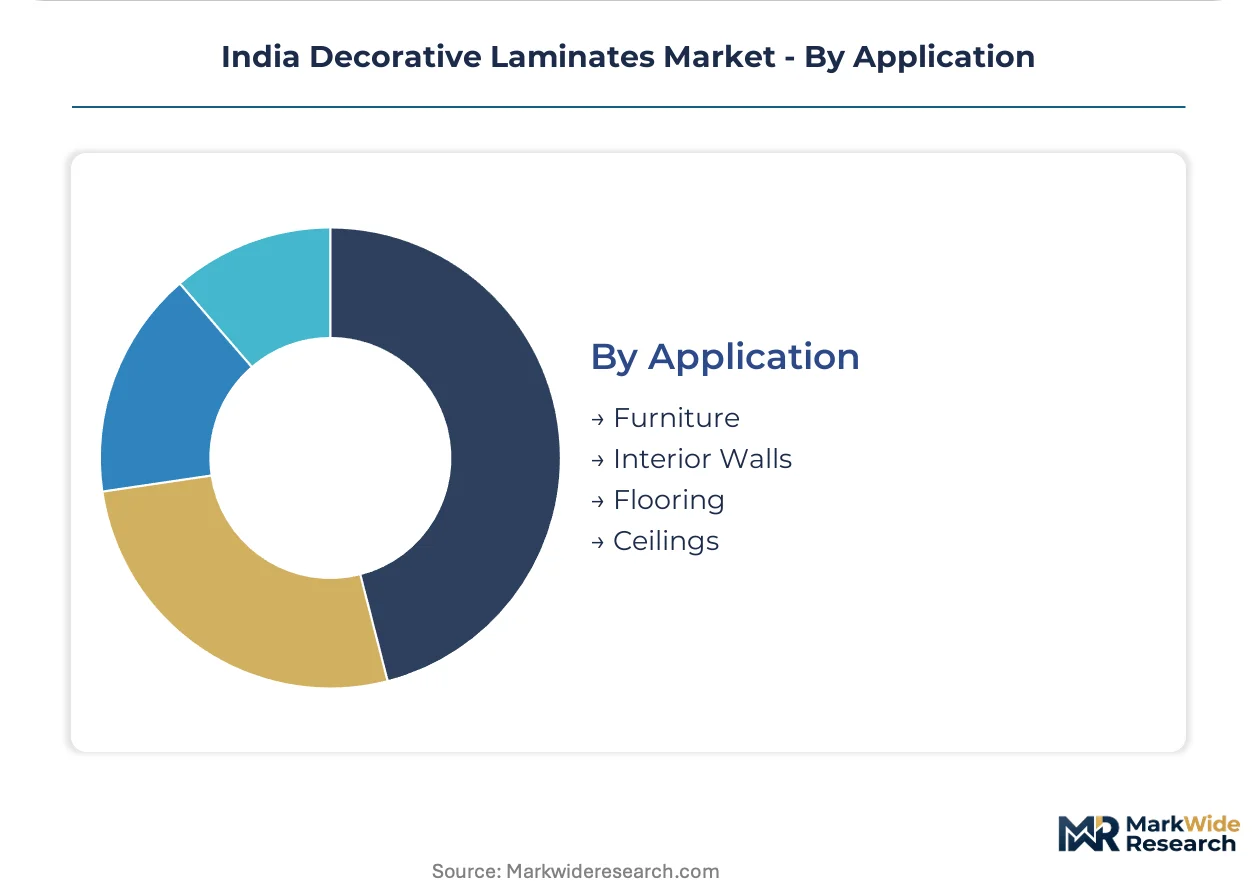
Furniture absorbs the dominant production volume; Interior Walls is gaining share fastest on architectural specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in tier-2 cities demonstrate acute price sensitivity to laminate grades, while Mumbai and Delhi NCR commercial developers absorb certified-premium products with limited elasticity. This demand bifurcation concentrates integrated production in cost-competitive western states and specification-grade supply in metropolitan construction corridors.
Maharashtra
Mumbai and Pune real estate developers are negotiating direct volume contracts for modular kitchen laminates, bypassing traditional distribution networks. BIS fire-retardant certification under IS 2046 is mandatory for commercial high-rises in Mumbai Metropolitan Region. Thane and Nashik furniture manufacturing clusters are absorbing record laminate shipments as residential construction scales.
Gujarat
Morbi and Gandhidham integrated producers control captive kraft paper and resin operations, insulating against import volatility. Bureau of Energy Efficiency effluent standards are concentrating phenol-formaldehyde production among integrated manufacturers with pollution control infrastructure. Ahmedabad furniture OEMs are scaling procurement for western India residential pipelines.
Karnataka
Bengaluru semiconductor fabrication facilities are driving procurement of electrostatic-dissipative laminates under ISO cleanroom frameworks. BIS antimicrobial surface revision timelines are creating first-mover advantages for domestic manufacturers with certified R&D lines. Electronics manufacturing clusters in Hosur and Mysuru are specifying specialty grades for pharmaceutical laboratories.
Tamil Nadu
Chennai hospitality developers are specifying laminate wall cladding for hotel renovation cycles as cost-efficient alternatives to engineered stone. Coastal moisture-resistant applications in Kochi-adjacent projects are penetrating PVC and PET-based decorative films. Coimbatore furniture manufacturing belts are absorbing mid-tier residential laminate volumes.
Delhi-NCR
Gurugram and Noida corporate reception areas are driving specification of fire-retardant laminate cladding under BIS IS 2046 standards. Institutional procurement from schools and hospitals enforces stringent BIS documentation protocols. Faridabad distribution networks are compressing margins as real estate developers negotiate direct manufacturer contracts.
India Decorative Laminates Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive resin and paper operations separating price-competitive volume players from specification-grade certified producers. Merino Laminates and Greenlam Industries anchor the integrated tier through backward control over kraft paper manufacturing, while trading-dependent converters occupy mid-market residential segments with thinner margin structures. Three archetypes define competitive positioning: integrated resin-to-laminate manufacturers, decorative paper specialists with regional printing operations, and import-dependent trading converters serving price-sensitive tier-2 markets. Dominant competitive moves include capacity expansion in Gujarat manufacturing belts and strategic partnerships with modular kitchen OEMs for direct procurement relationships.
Among integrated manufacturers, Merino Laminates exemplifies the captive supply archetype through its Gujarat and Punjab plant network, while Greenlam Industries occupies a position emphasizing certified R&D investment for antimicrobial and fingerprint-resistant surfaces. Stylam Industries represents the export-oriented specialist tier, anchoring Middle East and Africa volumes where BIS-grade certification holds less procurement weight than in domestic commercial projects.
| Leading Market Players |
|---|
| Stylam Industries |
| Formica India |
| Greenlam Industries |
| Durian Laminates |
| Rushil Decor |
| Merino Laminates |
| AICA Sunmica |
| Airo Lam |
| Century Laminates |
| Others |
Pricing and Supply Chain Analysis
Long-term volume contracts between Gujarat integrated producers and Maharashtra real estate developers lock in both kraft paper supply access and price visibility across multi-year residential construction pipelines. This contract structure insulates captive manufacturers from spot market volatility while compressing distributor margins in Mumbai and Pune trading networks.
Pricing Analysis
After-sales technical service and BIS certification renewal contracts drive lifetime value for premium-grade laminate suppliers. Three-tier pricing structure across BIS-certified premium, standard-grade domestic, and uncertified economy levels stratifies procurement decisions. Price differentiation hinges on fire-retardant certification tier under IS 2046 and captive resin production scale. Cost compression in economy-grade segments is intensifying as import-dependent converters absorb currency volatility. Tier-2 residential buyers in Ahmedabad and Nashik exhibit acute price sensitivity, while Mumbai commercial developers absorb certified-premium products with limited elasticity.
Supply Chain Analysis
Kraft paper import corridors through Mundra and Hazira ports constitute chokepoints that tether domestic laminate production to European and East Asian overlay suppliers. Manufacturing gravity centers on Gujarat and Maharashtra, with phenol-formaldehyde resin production anchored in Morbi and Gandhidham chemical belts. Raw material dependencies span kraft paper core layers, melamine decorative overlays, and phenol-formaldehyde binders. Single-source vulnerability in decorative paper printing exposes converters to shipping cost volatility. Distribution runs through direct manufacturer-developer contracts in western India and traditional trading channels in tier-2 markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS antimicrobial surface revision timelines and digital printing adoption are disrupting competitive positioning in India's decorative laminates sector. This regulatory-technological inflection concentrates advantage among integrated manufacturers with certified R&D infrastructure.
For Market Incumbents: Fortify captive kraft paper operations at Morbi and Gandhidham plants to insulate against import volatility. Deepen backward integration into decorative paper printing to capture margin pools currently controlled by European suppliers. Engineered quartz substitution in premium kitchen surfaces threatens laminate share; counter with certified fire-retardant grades for commercial high-rises under BIS IS 2046 mandates. For New Entrants and Emerging Players: Lead with electrostatic-dissipative specialty grades for Bengaluru semiconductor cleanrooms, where ISO certification barriers limit incumbent competition. Target price-sensitive African export markets where BIS-grade certification holds less procurement weight than in domestic commercial projects. Pursue digital printing partnerships with Gujarat furniture OEMs for made-to-order laminate production without cylinder changeover costs. For Investors and Strategic Acquirers: Trading-dependent converters with regional distribution networks in tier-2 cities represent consolidation targets as BIS compliance costs marginalize uncertified players. Long-term viability favors integrated resin-to-laminate manufacturers with pollution control infrastructure under Bureau of Energy Efficiency standards. Monitor BIS antimicrobial testing protocol finalization as inflection indicator for certified-premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Decorative Paper Printing | Captures margin pools from European overlay suppliers while insulating against currency volatility. |
| Capacity Expansion in Gujarat Manufacturing Belt | Consolidates cost-competitive production near Morbi resin plants and Mundra port access. |
| BIS Antimicrobial Certification Investment | Creates first-mover advantage as revision timelines finalize hospital and hospitality specifications. |
| Direct Procurement Partnerships with Real Estate Developers | Bypasses Mumbai and Pune distribution networks to secure volume contracts for modular kitchens. |
| Export Channel Development for Middle East and Africa | Penetrates price-sensitive markets where BIS-grade certification holds less procurement weight. |
Research Methodology
Initial hypotheses were tested against primary input from laminate plant managers, real estate developer procurement heads, furniture OEM technical directors, and BIS certification laboratory leads and refined through secondary validation. Sources included BIS notification records, Bureau of Energy Efficiency effluent compliance filings, Gujarat State Pollution Control Board permits, and residential construction pipeline databases. Bottom-up volume estimates from Gujarat and Maharashtra manufacturing clusters were triangulated against top-down construction spending forecasts.
Variance-decomposition across product type, material substrate, end-user category, application surface, and state-level regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated BIS revision timeline scenarios, phenol-formaldehyde resin capacity utilization rates, and modular kitchen OEM procurement scaling patterns.
Forecasts assume regulatory continuity in BIS certification mandates and Bureau of Energy Efficiency effluent standards; material policy shifts would require re-modeling of compliance cost structures and competitive tier boundaries. Practitioners should keep alternative scenarios live as antimicrobial testing protocol finalization and engineered quartz substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Bookends Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Window Covering Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Louvre Windows Market