
 Global Smart Furniture Market | 2026-2036
Global Smart Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Furniture Market Foresight
The premium-commodity split in smart furniture is restructuring around embedded technology depth rather than raw material quality alone. Steelcase Inc. leverages its enterprise channel control to dominate corporate deployment of sensor-integrated workstations. Herman Miller Inc. differentiates through sustained R&D intensity in ergonomic AI algorithms. Inter IKEA Systems B.V. anchors mass-market penetration with modular platforms that reduce per-unit smart component costs.
Smart furniture encompasses seating, surfaces, and storage systems embedded with sensors, actuators, and connectivity modules enabling automated adjustment, usage tracking, and environmental responsiveness. These products typically integrate microcontrollers, low-energy Bluetooth protocols, and pressure-sensitive fabrics to serve commercial and residential environments demanding space efficiency and health monitoring. Adjustable desks and sleep monitoring beds carry the deepest margin pools as buyers prioritize demonstrable wellness outcomes. Smart chairs lead volume through corporate standardization, while modular sofas represent the fastest-expanding category as urban density rises. IoT connectivity functions as the baseline technology layer, with AI integration emerging as the premium differentiator commanding price premiums.
FCC certification requirements govern wireless transmission standards for US-bound products, while REACH compliance in Europe restricts hazardous substances in embedded electronics and upholstery treatments. The EU AI Act introduces algorithmic transparency obligations for furniture systems making autonomous ergonomic adjustments, complicating product architecture decisions. Stakeholders must monitor how divergent regulatory timelines across the FDA's device classification deliberations and ECHA's expanding restricted substance lists reshape competitive entry barriers and R&D allocation priorities.
Market Dynamics
Hybrid work permanence is compressing corporate furniture replacement cycles while EU embodied carbon rules force material reselection across manufacturing footprints.
Growth Catalysts
- EU Green Deal embodied carbon rules:Manufacturers in Germany and Italy accelerate recyclable aluminum and bio-based polymer adoption to preempt compliance costs. Domestic supply chains for low-emission components expand capacity.
- Corporate wellness budgets:Human resources departments in the United States and United Kingdom allocate dedicated spend to sensor-integrated seating and adjustable surfaces. Ergonomic AI demonstrably reduces musculoskeletal claims.
- Bluetooth Low Energy mesh networks:Interoperability standards mature, enabling cross-brand furniture coordination in open-plan offices. Facility managers in Japan demand ecosystem-agnostic procurement.
Market Restraints
- Semiconductor supply concentration:Microcontroller and sensor module production concentrates in Taiwan and South Korea. Geopolitical friction elevates inventory carrying costs for European and North American assemblers.
- REACH substance restrictions:ECHA's expanding restricted substance lists complicate upholstery treatments and flame-retardant formulations. Reformulation cycles extend product development timelines by eight to fourteen months.
- Copper and rare earth price volatility:Wiring harnesses and permanent magnet actuators face input cost swings. Procurement teams struggle to hedge exposure through fixed-price contracts.
Strategic Opportunities
- India commercial real estate buildout:Bengaluru and Hyderabad technology campuses generate greenfield demand for sensor-integrated workstations. Domestic manufacturing incentives reduce landed cost versus imports.
- Ambient computing convergence:Furniture-embedded environmental sensors merge with building management systems. Integration partnerships with HVAC and lighting controls create new specification channels.
- EU AI Act algorithmic transparency:Early compliance with autonomous adjustment documentation requirements differentiates premium suppliers. First-movers capture specification roles in public sector tenders.
Industry Challenges
- FCC Part 15 certification timelines:Wireless transmission testing for US-bound products faces backlog at accredited laboratories. Launch delays compress selling seasons.
- Firmware-legacy system integration:Enterprise IT departments resist furniture-to-network connections without segmented security architectures. Pilot-to-scale conversion rates suffer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Furniture Market |
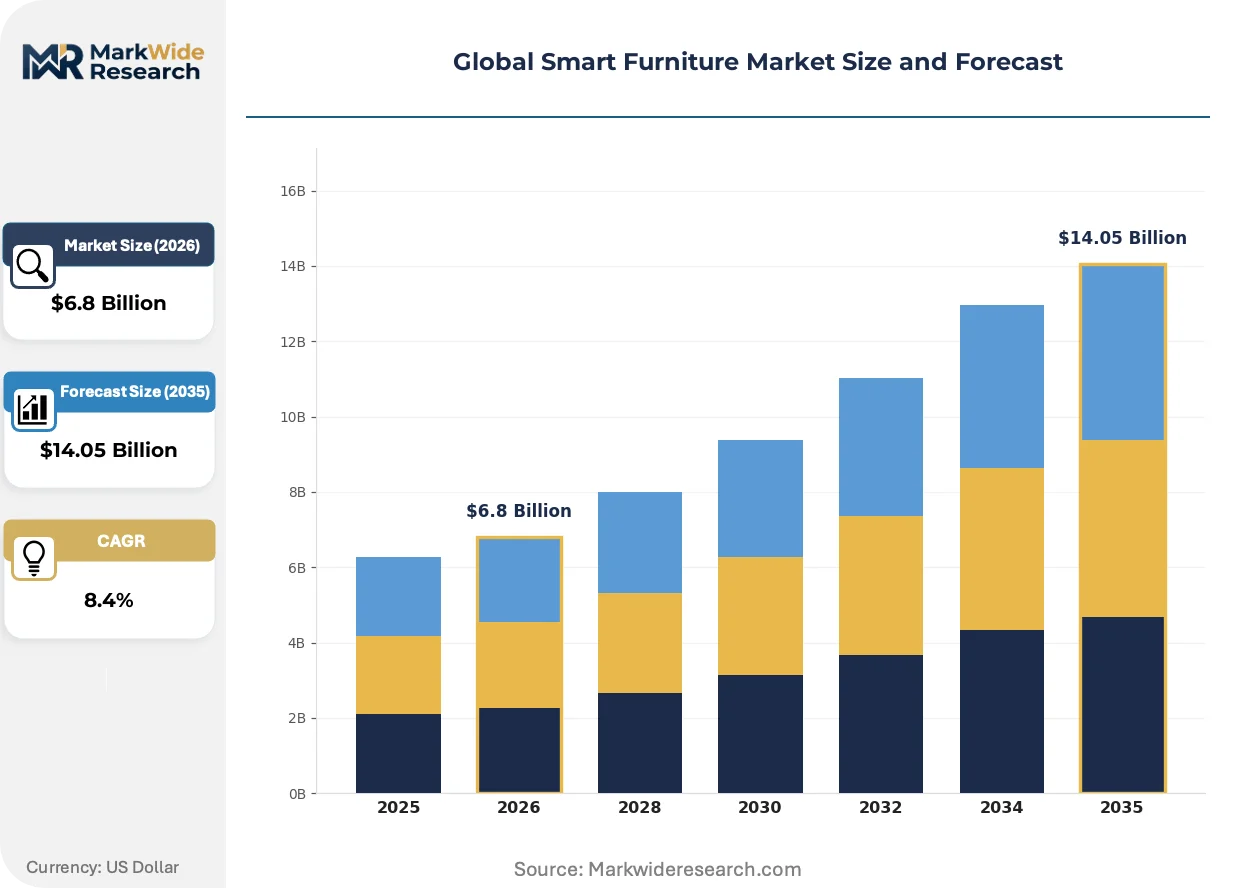
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Chairs, Adjustable Desks, Sleep Monitoring Beds, Interactive Tables, Modular Sofas Technology: IoT Connectivity, Voice Recognition, Touch Control, AI Integration, Wireless Charging Application: Residential Living, Corporate Offices, Educational Institutions, Hospitality Venues, Healthcare Facilities End User: Homeowners, Office Managers, Educational Administrators, Hotel Operators, Medical Practitioners |
| Companies Covered | HNI Corporation, Ashley Furniture Industries Inc., Inter IKEA Systems B.V., Haworth Inc., Desktronic, Steelcase Inc., Herman Miller Inc., Ori Living Inc., Sleep Number Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Furniture Market Shifts & Advancements
Embedded intelligence is migrating from standalone features to coordinated environmental systems, with regulatory pressure and procurement sophistication accelerating technical integration.
Pressure-sensitive fabric arrays with distributed capacitive sensing are automating posture recognition and micro-adjustment in task seating. Corporate facilities teams in the Netherlands and Sweden specify these systems for six-hour-plus workstation deployments. The technology is automating ergonomic intervention that previously required human resources case management.
ECHA's expanding SVHC candidate list is forcing reformulation of polyurethane foams and textile finishes used in upholstered smart furniture. German and Italian manufacturers establish captive chemical testing capabilities to accelerate compliance verification. Seating categories with extended skin contact face the most intensive substance scrutiny and supplier qualification requirements.
Building owners now unbundle furniture procurement from facilities management contracts, creating direct manufacturer relationships. Institutional buyers in Singapore and Australia negotiate performance-based specifications with embedded IoT telemetry. Asset-light operators favor rental and refresh models over capital purchase, compressing supplier cash conversion cycles.
Global Smart Furniture Market Segmentation
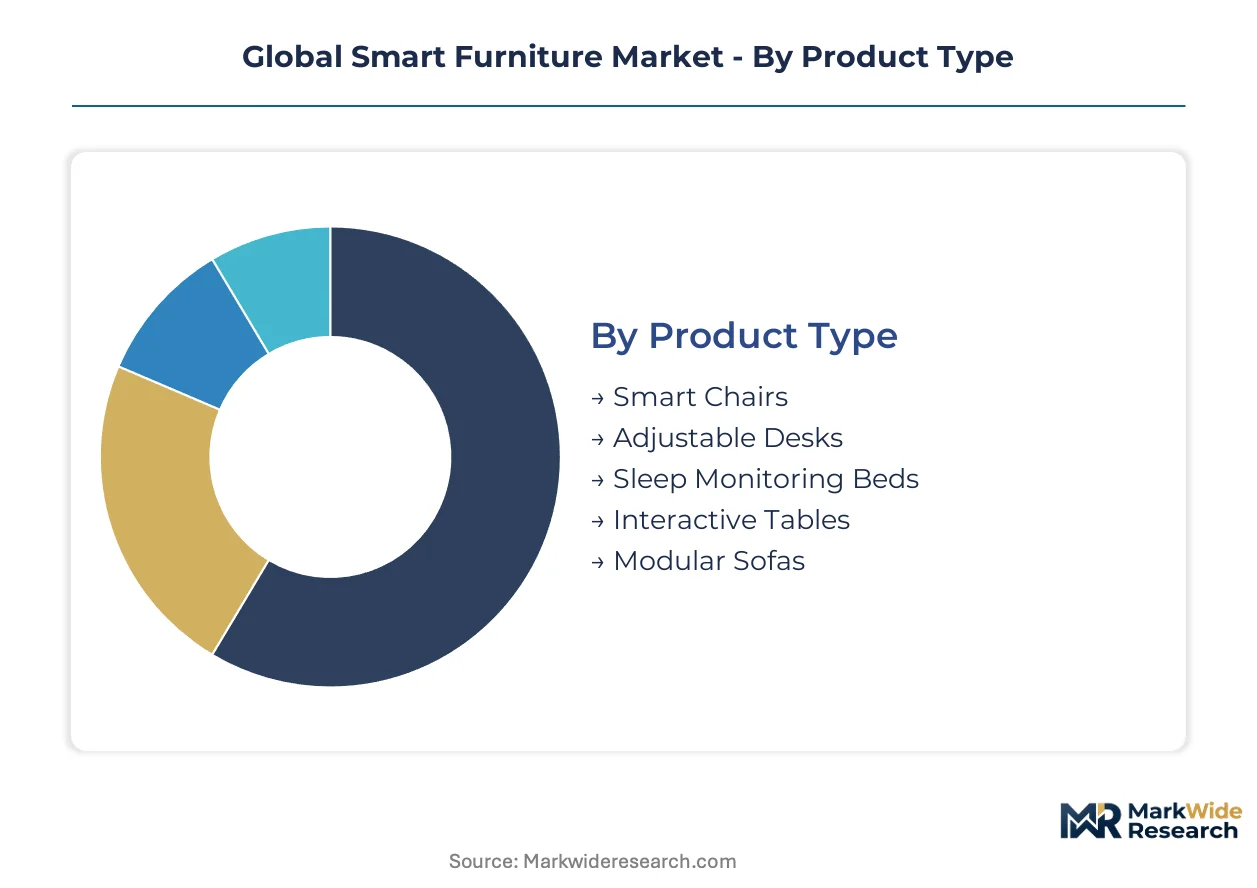
Smart furniture segmentation reveals how embedded intelligence migrates across physical form factors and procurement contexts. Technology depth and application environment together determine specification requirements and margin architecture.
Product Type:
Technology integration depth varies sharply across furniture categories, with sensor density and actuator complexity defining tier boundaries.
- Smart Chairs:Pressure-sensitive fabric arrays and micro-adjustment actuators enable automated posture correction. Corporate facilities in the United States and Germany standardize these for six-hour-plus workstation deployments, driven by measurable reductions in musculoskeletal claims.
- Adjustable Desks:Dual-motor lift systems with height memory and collision detection dominate premium specifications. Office managers in the United Kingdom and Japan prioritize these for hot-desking environments where ergonomic personalization must occur without IT intervention.
- Sleep Monitoring Beds:Biometric tracking mattresses with temperature regulation and sleep stage analysis. Homeowners in Australia and Canada demonstrate willingness to pay premium prices for demonstrable wellness outcomes.
- Interactive Tables:Touch-integrated surfaces with embedded displays and wireless connectivity modules. Educational administrators in Singapore specify these for collaborative learning spaces.
- Modular Sofas:Reconfigurable seating platforms with distributed sensor networks and plug-and-play connectivity. Urban residential buyers in South Korea and the Netherlands favor these as space-constrained living solutions.
Mature deployment sits with smart chairs. Newer deployment is concentrated in modular sofas.
Technology:
Cost-to-capability ratios stratify procurement decisions, with baseline interoperability commanding volume and advanced autonomy capturing premium positioning.
- IoT Connectivity:Low-energy Bluetooth mesh and Wi-Fi protocols enabling cross-device coordination. Facility managers in Japan demand ecosystem-agnostic procurement, forcing interoperability standards maturation.
- AI Integration:Algorithmic systems enabling autonomous ergonomic adjustment and predictive maintenance. The EU AI Act's transparency obligations complicate product architecture for European-bound systems.
- Voice Recognition:Natural language interfaces for hands-free furniture control. Hospitality venues in the United States deploy these for accessibility compliance and guest experience differentiation.
- Touch Control:Capacitive and resistive interfaces for manual override and preference setting. Educational institutions favor these for intuitive student interaction.
- Wireless Charging:Inductive power surfaces integrated into tabletops and armrests. Corporate offices in Germany embed these to reduce cable clutter in flexible workspaces.
Volume concentration rests with IoT connectivity. Value capture is climbing fastest through AI integration.
Application:
Procurement sophistication and budget scale diverge dramatically across built environment types, reshaping go-to-market requirements.
- Corporate Offices:Enterprise-scale deployments with standardized specifications and centralized fleet management. Hybrid work permanence in the United States and United Kingdom compresses replacement cycles.
- Residential Living:Fragmented individual purchases prioritizing aesthetic integration and wellness features. Homeowners in Germany and Sweden show strongest preference for sleep monitoring and ergonomic seating.
- Healthcare Facilities:Clinical-grade requirements for infection control and patient monitoring integration. Medical practitioners in Japan and Australia specify pressure-relief seating with telemetry.
- Educational Institutions:Durability-focused procurement with collaborative technology requirements. Administrators in Singapore and the Netherlands prioritize interactive surfaces.
- Hospitality Venues:Experience-driven specifications emphasizing guest control and aesthetic differentiation. Hotel operators in Dubai and Miami deploy voice-activated systems for luxury positioning.
Specification maturity concentrates in corporate offices. Healthcare facilities are gaining share fastest as clinical evidence accumulates.
End User:
Decision authority and evaluation criteria fragment across organizational roles and individual contexts.
- Office Managers:Centralized procurement with total cost of ownership analysis and wellness outcome metrics. United Kingdom facilities teams increasingly unbundle furniture from service contracts.
- Homeowners:Discretionary purchases driven by wellness trends and smart home ecosystem integration. German and Canadian buyers show highest propensity for premium sleep monitoring beds.
- Medical Practitioners:Evidence-based selection for patient outcomes and clinical workflow efficiency. Australian aged care operators specify sensor-integrated seating for fall prevention.
- Educational Administrators:Budget-constrained procurement prioritizing durability and multi-use flexibility. Singaporean universities negotiate performance-based specifications with embedded telemetry.
- Hotel Operators:Brand-differentiated selection emphasizing guest experience and operational efficiency. Dubai luxury properties deploy ambient computing convergence with building management systems.
Procurement sophistication peaks with office managers. Medical practitioners are expanding most quickly as reimbursement models evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru and Hyderabad technology campuses anchor greenfield demand for sensor-integrated workstations across India, while established manufacturing clusters in Germany and the United States retrofit corporate facilities for hybrid permanence.
United States
Corporate wellness budgets from human resources departments drive specification of sensor-integrated seating and adjustable surfaces. FCC Part 15 certification requirements govern wireless transmission standards for furniture-bound products. Dallas and Austin metropolitan areas concentrate technology campus buildouts with standardized ergonomic deployments.
Germany
Industry 4.0 integration into domestic furniture manufacturing accelerates smart product development with embedded automation. EU Green Deal embodied carbon rules pressure manufacturers toward recyclable aluminum and bio-based polymer adoption. Bavaria and North Rhine-Westphalia host expanding supply chains for low-emission components.
India
Bengaluru and Hyderabad technology campuses generate greenfield demand for sensor-integrated workstations with domestic manufacturing incentives. Production-linked incentive schemes reduce landed cost versus imports for campus-scale procurement. Tamil Nadu and Karnataka states concentrate contract manufacturing capacity for regional assembly.
United Kingdom
Office managers unbundle furniture procurement from facilities management contracts for direct manufacturer relationships. REACH compliance restricts hazardous substances in embedded electronics and upholstery treatments. London and Manchester metropolitan areas lead specification of hot-desking environments with ergonomic personalization.
Japan
Facility managers demand ecosystem-agnostic procurement with Bluetooth Low Energy mesh network interoperability. METI standards mature for cross-brand furniture coordination in open-plan offices. Tokyo and Osaka metropolitan areas concentrate pilot deployments of ambient computing convergence with building management systems.
Global Smart Furniture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology depth and enterprise channel control. The vendor base organizes into three tiers: enterprise-scale contract furniture specialists, mass-market modular platform operators, and venture-backed vertical specialists. Strategic archetypes include sensor-integrated workstation providers, AI-driven ergonomic algorithm developers, and space-transforming robotics fabricators. Dominant competitive moves encompass M&A for enterprise channel access and strategic partnerships with building management system integrators.
Within the enterprise-scale tier, Steelcase Inc., Herman Miller Inc., and Inter IKEA Systems B.V. exemplify divergent positioning strategies. Steelcase Inc. occupies a position emphasizing enterprise channel control for corporate deployment. Herman Miller Inc. sits within the premium tier through sustained intensity in algorithmic development. Inter IKEA Systems B.V. anchors mass-market penetration with modular platform architectures that reduce per-unit component costs.
| Leading Market Players |
|---|
| HNI Corporation |
| Ashley Furniture Industries Inc. |
| Inter IKEA Systems B.V. |
| Haworth Inc. |
| Desktronic |
| Steelcase Inc. |
| Herman Miller Inc. |
| Ori Living Inc. |
| Sleep Number Corporation |
| Others |
Supply & Pricing Matrix
Captive component manufacturing in Taiwan and South Korea anchors both supply security and premium pricing power for sensor-integrated furniture systems, with microcontroller fabrication concentration enabling tiered margin extraction across enterprise and residential channels.
Pricing Analysis
Outcome-linked pricing tied to musculoskeletal claim reduction anchors enterprise procurement decisions for sensor-integrated seating. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled autonomous adjustment systems from basic IoT connectivity modules from non-connected ergonomic furniture. Cost compression in the economy tier is intensifying because modular platform operators achieve scale efficiencies in sensor component sourcing. Corporate facilities teams demonstrate lowest price sensitivity due to wellness budget allocation, while residential buyers exhibit highest elasticity unless demonstrable sleep outcomes are guaranteed.
Supply Chain Analysis
Microcontroller and pressure-sensitive fabric supply rests on Taiwanese semiconductor foundries and South Korean sensor module producers, with German and Italian manufacturers maintaining final assembly and algorithm development capabilities. Critical input dependencies include rare earth permanent magnets for actuator motors, copper wiring harnesses, and bio-based polymer feedstocks for EU Green Deal compliance. Single-source vulnerability concentrates in advanced microcontroller fabrication, where geopolitical friction elevates inventory carrying costs. Distribution runs through enterprise contract furniture specialists and mass-market retail platforms, with direct manufacturer relationships emerging in institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with upstream control over sensor module sourcing and downstream capture of facilities management contracts representing the decisive levers for margin defense.
For Market Incumbents: Extend algorithmic development capabilities to preempt EU AI Act compliance differentiation, while consolidating enterprise channel control through integrated fleet management software. Sensor module supply concentration in Taiwan presents substitution risk from emerging mainland Chinese fabricators. Backward integration into pressure-sensitive fabric manufacturing reduces per-unit component cost exposure.
For New Entrants and Emerging Players: Building management system integrators represent the most accessible channel for ambient computing convergence partnerships, bypassing incumbent-controlled enterprise furniture procurement. India's Bengaluru and Hyderabad technology campuses offer the most penetrable geography for greenfield sensor-integrated workstation deployment. Specification through performance-based contracts with embedded IoT telemetry enables bypass of established vendor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise software or building automation conglomerates seeking furniture-embedded environmental sensor networks. Long-term viability favors suppliers with demonstrated clinical evidence for wellness outcomes and established compliance documentation for EU algorithmic transparency requirements. Watch for FDA device classification deliberations as the critical inflection signal for healthcare facility market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development Investment | EU AI Act compliance documentation differentiates premium suppliers in public sector tenders. |
| Building Management System Integration Partnership | Ambient computing convergence with HVAC controls creates new specification channels in Japan. |
| Recyclable Material Supply Chain Captive | EU Green Deal embodied carbon rules pressure aluminum and bio-polymer adoption in Germany. |
| Enterprise Channel Control Consolidation | Direct manufacturer relationships with unbundled procurement compress competitor access in the United Kingdom. |
| Clinical Evidence Generation Program | Musculoskeletal claim reduction documentation enables healthcare facility specification in Australia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facilities managers, biomedical engineers, enterprise procurement officers, and contract furniture specialists. ECHA substance restriction updates, FCC Part 15 certification databases, and EU Green Deal implementation guidance provided regulatory trajectory inputs. Bottom-up shipment modeling and top-down macroeconomic reconciliation validated volume estimates.
Reconciliation of production data from German and Italian manufacturing associations with import records from Indian technology campus buildouts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology depth, application environment, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating replacement cycle compression and greenfield demand emergence. Bluetooth Low Energy mesh interoperability maturation and REACH substance list expansion served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including specific FCC certification backlog durations, geopolitical disruption scenarios in Taiwan Strait shipping lanes, and rapid FDA device reclassification decisions. Forecasts reflect assumptions about hybrid work permanence and EU regulatory timeline adherence. A small set of named triggers warrants ongoing watch: semiconductor supply rationing, ECHA SVHC list acceleration, and enterprise IT security architecture standardization for furniture-network segmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Upholstered Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Furniture Laminate Market
Furniture
Global Organic Furniture Market
Furniture
Bar Stools Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
North America Furniture Market
Furniture
Italy Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Children Furniture Market
Furniture
India Luxury Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Bean Bag Chairs Market