
 Italy Furniture Market | 2026-2036
Italy Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Furniture Market Outlook
Digital manufacturing integration is narrowing the gap between bespoke craftsmanship and scalable production across Italian furniture workshops. Molteni & C leverages automated cutting and CNC routing to preserve design fidelity at volume. Natuzzi anchors its competitive stance through proprietary leather treatment facilities in Puglia. Scavolini dominates kitchen system manufacturing by controlling distribution through company-owned showrooms in every Italian region.
Italy furniture comprises movable objects for interior spaces, typically constructed from engineered wood panels, solid timber, metal frameworks, or upholstered substrates with density ratings from 25 to 45 kg per cubic meter for seating foams, designed to support residential, commercial, and hospitality functions. Wood material segments sustain premium positioning through FSC-certified supply chains and heritage finishing techniques that command margin pools in luxury residential projects. Fabric and leather upholstery categories compete on performance certifications for contract hospitality applications where fire resistance and abrasion thresholds determine specification outcomes.
Italy's Ministry of Enterprise and Made in Italy (MIMIT) enforces origin labeling under the "Made in Italy" decree, while EU REACH and ECHA chemical restrictions govern finishes and adhesives used in domestic production. The EU Green Deal's embodied carbon requirements for building materials are reshaping procurement specifications for office and hospitality fit-outs. Stakeholders must monitor how CSRD disclosure mandates will pressure mid-sized manufacturers to document supply chain emissions or risk exclusion from corporate furnishing contracts.
Market Dynamics
Italy's furniture sector is restructuring around the tension between heritage craftsmanship and digital manufacturing scale, with EU Green Deal embodied carbon mandates forcing material sourcing transparency across the Brianza production cluster.
Growth Catalysts
- PNRR sustainable manufacturing incentives:Italy's National Recovery and Resilience Plan channels capital toward FSC-certified wood supply chains, accelerating facility upgrades in Lombardy upholstery workshops.
- Hospitality sector renovation cycles:Hotel groups across Milan and Rome are procuring Italian-designed furnishings at elevated volumes, creating pull-through demand for contract-grade upholstery with fire resistance certifications.
- Digital manufacturing adoption:Automated cutting and CNC routing technologies are compressing production lead times while preserving design fidelity, enabling mid-sized workshops to serve corporate furnishing contracts previously captured by larger manufacturers.
Market Restraints
- Certified timber supply concentration:FSC-certified hardwood flows through a narrow corridor of Baltic and Alpine suppliers, exposing Brianza manufacturers to input cost volatility and extended procurement timelines.
- REACH chemical compliance friction:ECHA restrictions on finishes and adhesives force reformulation cycles that extend product development timelines and elevate R&D expenditure for coating suppliers.
- Skilled artisan labor scarcity:Heritage finishing techniques requiring decade-long training pipelines face generational attrition, constraining output expansion for premium residential projects demanding hand-applied veneer work.
Strategic Opportunities
- Southern Italy manufacturing expansion:Puglia's leather treatment infrastructure and lower facility costs offer anchor points for upholstery producers seeking geographic diversification beyond Lombardy concentration.
- CSRD disclosure tailwinds:Corporate Sustainability Reporting Directive mandates are pressuring mid-sized manufacturers to document supply chain emissions, creating first-mover advantage for those with certified traceability systems already operational.
- Direct-to-developer channel innovation:Bypassing traditional wholesale distribution through company-owned showrooms in secondary Italian cities captures margin pools and specification control previously ceded to intermediaries.
Industry Challenges
- Embodied carbon certification complexity:EU Green Deal building material requirements demand lifecycle assessment documentation that many family-owned workshops lack technical capacity to generate without external consultancy.
- Digital-physical integration friction:Legacy ERP systems in multi-generational furniture enterprises resist seamless connection to automated production equipment, delaying real-time inventory visibility.
- Made in Italy enforcement ambiguity:MIMIT origin labeling decree creates compliance uncertainty for manufacturers sourcing components across EU borders, elevating legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Furniture Market |
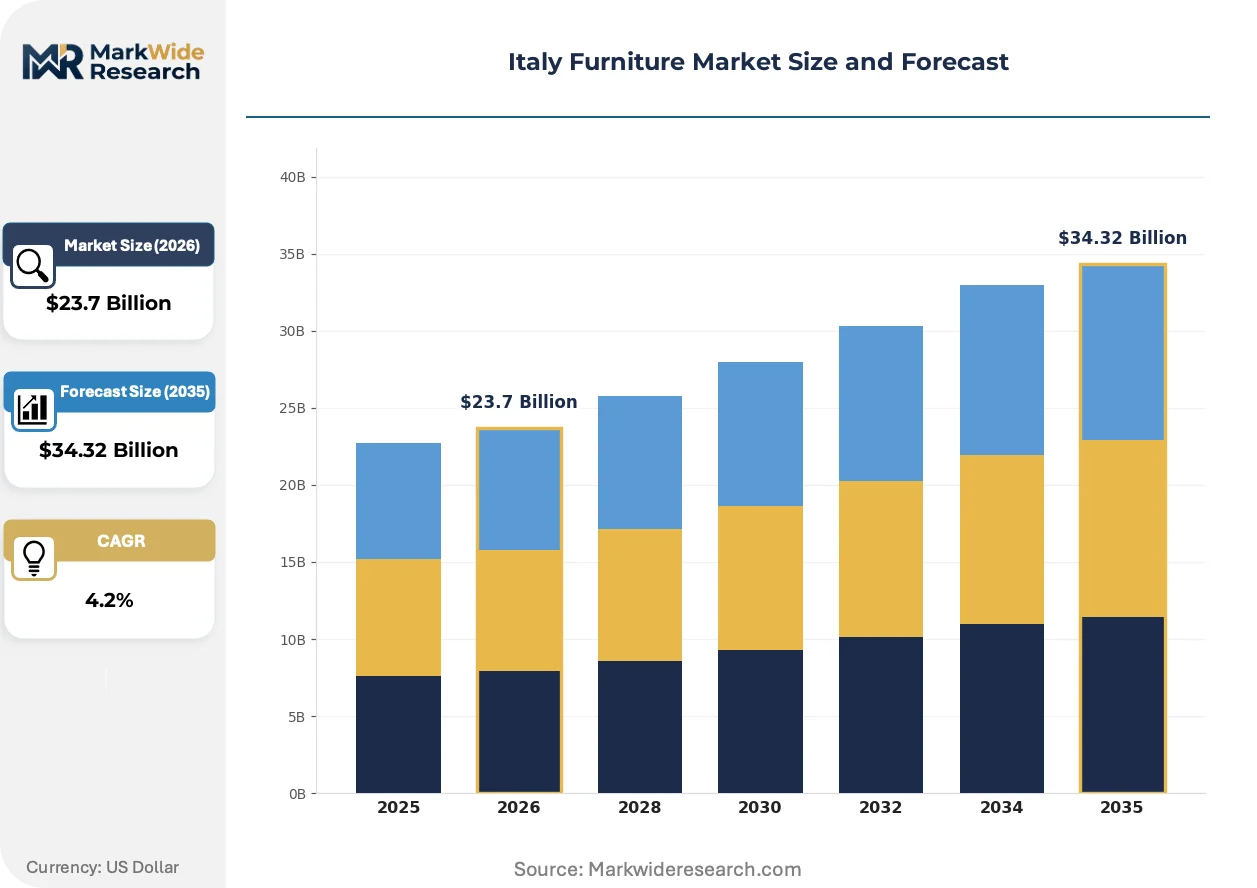
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $34.32 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Chairs, Tables Material: Wood, Metal, Fabric, Leather End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Retail, Wholesale, Showrooms |
| Companies Covered | Poltrona Frau, Natuzzi, Scavolini, Calligaris, B&B Italia, Molteni & C, Poliform, Cassina, Minotti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Furniture Market Strategic Shifts
Italian furniture production is converging on three vectors: computational design tools that compress prototyping cycles, regulatory pressure on material provenance, and procurement centralization among hospitality and corporate buyers.
Parametric design software paired with robotic fabrication is hybridizing the boundary between custom cabinetry and scalable production. High-end residential developers and boutique hotel operators are specifying digitally fabricated components at volumes previously reserved for mass-market manufacturers. This convergence compresses the price premium between bespoke and batch production, forcing traditional workshops to adopt CAD-CAM workflows or retreat to purely artisan positioning.
EU Green Deal embodied carbon thresholds for building materials are tightening procurement specifications across office and hospitality fit-outs. REACH and ECHA chemical restrictions on finishes and adhesives are elevating compliance costs for coating suppliers serving the furniture sector. Northern Italian manufacturers with early investments in water-based finishing systems and certified timber traceability are capturing specification share from laggards facing retrofit timelines.
Corporate furnishing buyers are consolidating vendor relationships and demanding outcome-based contracts that bundle installation, maintenance, and end-of-life recovery. Hospitality procurement teams in Milan and Rome are shifting from transactional purchasing to multi-year framework agreements with performance guarantees. This concentration favors manufacturers with captive service networks and circular logistics capabilities, marginalizing pure production players without downstream asset control.
Italy Furniture Market Segmentation
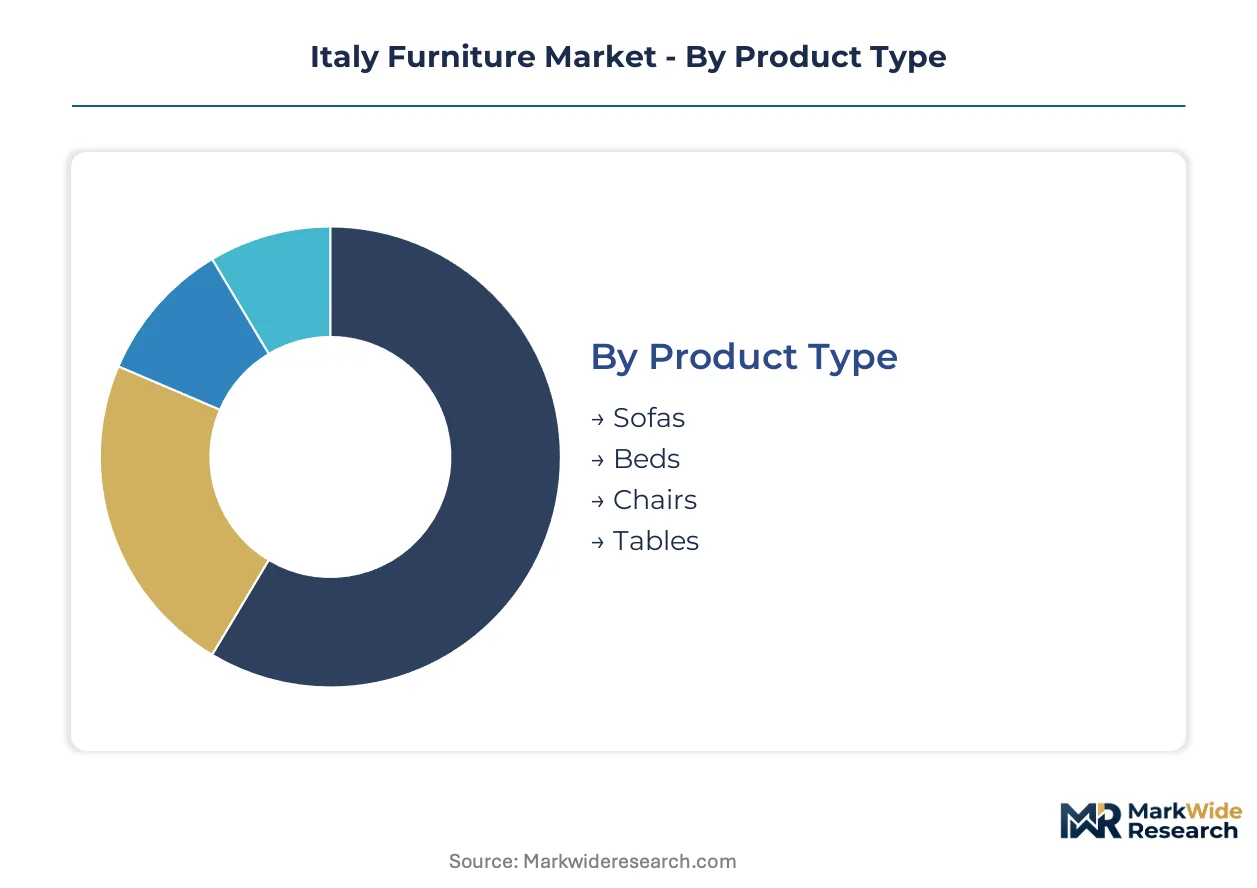
Italian furniture segmentation reveals how production capabilities align with distinct procurement channels and regulatory requirements. Each dimension exposes different margin structures and compliance burdens across the Lombardy-centered manufacturing base.
Product Type:
Mature categories dominate revenue concentration while emerging formats exploit digital fabrication to compress bespoke-to-batch cost gaps.
- Sofas:Upholstered seating systems rely on foam density ratings from 25 to 45 kg per cubic meter for structural integrity. Hospitality procurement in Milan and Rome drives specification toward fire-resistant contract-grade fabrics with elevated abrasion thresholds. Brianza workshops anchor production through automated cutting lines that preserve design fidelity at volume.
- Beds:Mattress platforms and headboard assemblies integrate slatted wood bases with metal reinforcement frameworks. Residential demand concentrates in Lombardy's luxury developments where FSC-certified timber supply chains command premium positioning through heritage finishing techniques.
- Chairs:Seating spans dining, accent, and task configurations with metal or wood structural substrates. Corporate furnishing buyers consolidate vendor relationships around multi-year framework agreements.
- Tables:Surface assemblies range from solid timber dining platforms to engineered panel conference systems. EU Green Deal embodied carbon thresholds reshape procurement specifications for office fit-outs.
Sofas retain volume leadership; beds hold the steepest expansion curve.
Material:
Cost tier stratification separates certified premium inputs from standardized commodity alternatives.
- Wood:Solid timber and engineered panels sustain premium positioning through FSC-certified supply chains. Baltic and Alpine suppliers channel certified hardwood through narrow procurement corridors, exposing Brianza manufacturers to input cost volatility.
- Leather:Full-grain and corrected hides undergo proprietary treatment at Puglia facilities. Natuzzi anchors competitive positioning through captive tanning infrastructure that controls quality consistency and margin capture.
- Metal:Steel and aluminum frameworks provide structural substrates for seating and table bases. REACH chemical restrictions on finishes force reformulation cycles that extend product development timelines.
- Fabric:Natural and synthetic textiles compete on performance certifications for contract applications. Fire resistance ratings determine specification outcomes in hospitality procurement.
Wood commands the highest margin tier; leather gains share fastest in contract segments.
End User:
Application-driven demand splits between cyclical residential replacement and sustained commercial renovation cycles.
- Residential:Individual consumers and luxury developers specify heritage finishing techniques requiring hand-applied veneer work. Generational attrition in artisan training pipelines constrains output expansion for premium projects.
- Hospitality:Hotel groups across Milan and Rome are procuring Italian-designed furnishings at elevated volumes. Renovation cycles create pull-through demand for contract-grade upholstery with certified traceability documentation.
- Commercial:Retail and public space operators prioritize durability specifications and rapid replacement logistics. CSRD disclosure mandates pressure mid-sized manufacturers to document supply chain emissions.
- Office:Corporate furnishing buyers demand outcome-based contracts bundling installation, maintenance, and end-of-life recovery. Concentration favors manufacturers with captive service networks.
Residential maintains volume dominance; hospitality climbs the fastest on renovation momentum.
Distribution Channel:
Geographic reach and margin capture trade off across physical and digital infrastructure investments.
- Showrooms:Company-owned display spaces in every Italian region enable specification control previously ceded to intermediaries. Scavolini dominates kitchen system manufacturing through this captive distribution model.
- Retail:Third-party furniture stores and department store concessions extend reach into secondary cities. Margin compression accompanies wholesale discount structures.
- Online:Digital platforms compress lead times for standardized configurations while struggling to convey tactile quality for premium upholstery. Automated cutting and CNC routing technologies enable mid-sized workshops to serve corporate contracts.
- Wholesale:Traditional distribution through independent dealers and contract furniture specialists retains relevance in hospitality procurement. Multi-year framework agreements shift power toward buyers with consolidated vendor relationships.
Showrooms retain margin leadership; online channels expand most quickly on digital manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French buyers absorb the majority of Italian furniture exports, channeling demand through Milan's trade corridors toward Northern European commercial fit-outs and luxury residential developments.
Lombardy
Milan's hospitality renovation cycles drive procurement of contract-grade upholstery with fire resistance certifications. MIMIT enforces origin labeling under the "Made in Italy" decree across Brianza manufacturing clusters. The dense concentration of automated cutting and CNC routing workshops in Monza and Como compresses production lead times for corporate furnishing contracts.
Veneto
Residential developers in Treviso and Padua specify heritage finishing techniques requiring FSC-certified timber supply chains. EU Green Deal embodied carbon requirements reshape procurement specifications for luxury housing projects. The Verona furniture district anchors engineered panel production for export-bound kitchen systems.
Piedmont
Turin's corporate headquarters sector demands outcome-based contracts bundling installation and end-of-life recovery services. REACH chemical restrictions from ECHA force reformulation cycles for coating suppliers serving the regional manufacturing base. The Biella textile corridor supplies performance-certified fabrics for contract hospitality applications.
Emilia-Romagna
Bologna's public space operators prioritize rapid replacement logistics and durability specifications for institutional seating. CSRD disclosure mandates pressure mid-sized manufacturers to document supply chain emissions or risk exclusion from municipal furnishing contracts. The Modena ceramic-furniture hybrid cluster experiments with digitally fabricated surface assemblies.
Italy Furniture Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure where captive showroom networks and wholesale distribution coexist. The vendor base stratifies between vertically integrated manufacturers with in-house tanning and finishing infrastructure and assembly-focused workshops sourcing components across EU borders. Three archetypes dominate: heritage luxury houses preserving artisan positioning, scale-driven kitchen system manufacturers, and digitally enabled mid-cap specialists. Competitive moves concentrate on geographic diversification beyond Lombardy concentration and backward integration into certified timber supply chains.
Among heritage-positioned manufacturers, Poltrona Frau and Cassina exemplify the artisan-luxury archetype through decades-long brand equity in hand-finished leather and wood craftsmanship. Natuzzi occupies a distinct position anchoring competitive stance through proprietary leather treatment infrastructure in Southern Italy. Scavolini represents the scale-driven kitchen system vector through company-owned showroom penetration across every Italian region. These three sit within different strategic tiers yet face converging pressure from EU Green Deal embodied carbon documentation requirements and hospitality procurement consolidation.
| Leading Market Players |
|---|
| Poltrona Frau |
| Natuzzi |
| Scavolini |
| Calligaris |
| B&B Italia |
| Molteni & C |
| Poliform |
| Cassina |
| Minotti |
| Others |
Value Chain & Pricing Dynamics
Baltic and Alpine hardwood corridors channel FSC-certified timber through narrow procurement windows, compressing margin capture for Brianza manufacturers while concentrating pricing power with certified suppliers serving luxury residential developers.
Pricing Analysis
Heritage finishing techniques versus automated production lines versus digitally fabricated components create a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FSC certification grade and after-sales service bundling, with cost compression in contract hospitality tiers intensifying because of procurement consolidation among Milan and Rome hotel groups. Corporate furnishing buyers exhibit lowest price sensitivity; mid-sized workshops without captive showroom networks face highest pressure.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Lombardy upholstery specialists, Veneto engineered panel producers, and Puglia leather treatment facilities. Raw material dependencies span Baltic hardwood, Alpine softwood, and corrected hides from EU tanneries. Single-source vulnerability runs through FSC-certified timber corridors. Distribution feeds from company-owned showrooms in primary cities, wholesale networks in secondary markets, and digital platforms for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's furniture sector sits in early-cycle expansion as EU Green Deal embodied carbon mandates force procurement specification upgrades across hospitality and commercial fit-outs, creating pull-through demand for certified traceability systems.
For Market Incumbents: Entrench position through backward integration into certified timber supply chains and captive service network expansion. Molteni-style automated production investments defend against digitally enabled mid-cap specialists. CSRD disclosure mandates threaten exclusion from corporate contracts for laggards without emissions documentation systems.
For New Entrants and Emerging Players: Southern Italy manufacturing zones offer underpenetrated production capacity at lower facility costs than Lombardy concentration. Puglia leather infrastructure and Emilia-Romagna ceramic-furniture hybrid clusters represent most penetrable anchor points. Direct-to-developer showroom models in secondary cities bypass wholesale margin compression.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed kitchen system manufacturers and digitally enabled upholstery specialists. Five-to-ten year viability favors those with certified traceability operational before CSRD enforcement waves. Monitor hospitality procurement framework agreement volumes as inflection indicator for contract-grade specification share shifts.
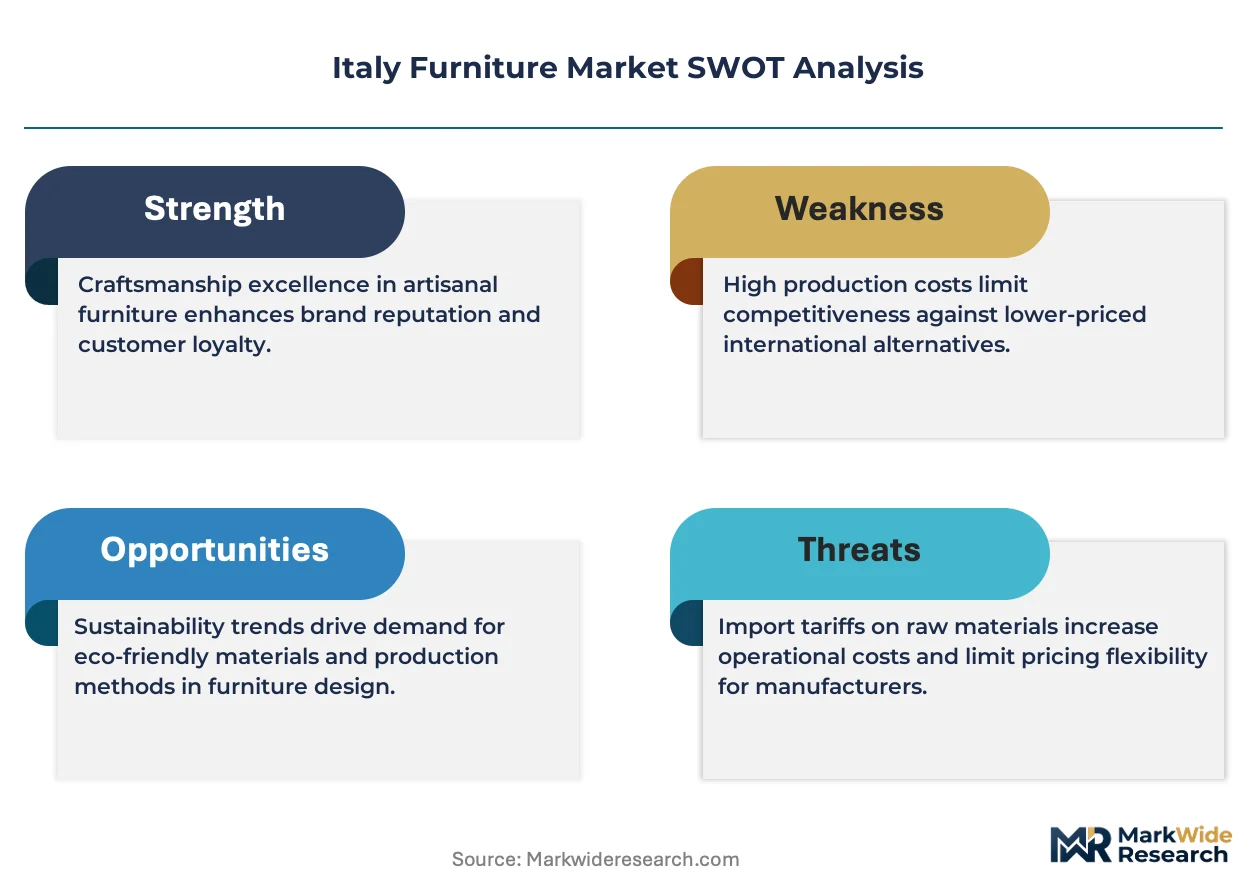
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Timber Backward Integration | FSC supply chain control insulates Brianza manufacturers from Baltic input volatility. |
| Automated Production Scale-Up | CNC routing investments compress bespoke-to-batch cost gaps for corporate contracts. |
| Direct-to-Developer Showroom Expansion | Company-owned display spaces in secondary cities capture margin pools from wholesalers. |
| CSRD-Ready Traceability Systems | Emissions documentation capabilities secure hospitality framework agreement eligibility. |
| Southern Italy Manufacturing Footprint | Puglia and Emilia-Romagna facilities diversify geographic risk beyond Lombardy concentration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU trade statistics, MIMIT regulatory filings, and hospitality procurement databases. Primary interviews engaged furniture manufacturing executives, hospitality procurement directors, certified timber suppliers, and coating formulation specialists. Secondary validation drew from ECHA chemical restriction updates, FSC supply chain disclosures, and corporate sustainability reports. Bottom-up production capacity estimates triangulated against top-down demand segmentation across residential, hospitality, commercial, and office end uses.
Forecast inputs span product type evolution, material substitution patterns, end-user procurement consolidation, and distribution channel migration. Segmentation dimensions modeled include product category, material grade tier, end-use application, and geographic production cluster. CAGRs derived from trend extrapolation anchored in PNRR incentive disbursement schedules and hospitality renovation cycle timing. Industry-specific inputs incorporate EU Green Deal embodied carbon threshold implementation pace and CSRD disclosure mandate compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally enabled mid-cap specialists or PE-backed consolidation platforms would shift outcomes. Quarterly review of hospitality framework agreement awards and FSC-certified timber spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
RTA Furniture Market
Furniture
France Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Vietnam Home Furniture Market
Furniture
Children Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
School Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Japan Furniture Market
Furniture
Germany Home Furniture Market
Furniture
High End Furnitures Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market