
 Outdoor Furniture Market | 2026-2036
Outdoor Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Furniture Market Analysis
Multi-source material procurement is restructuring supply economics across the outdoor furniture sector. IKEA leverages its captive textile and flat-pack logistics network to compress landed costs on seating systems. Kettal Group anchors its position through in-house aluminum extrusion and European weaving ateliers. Royal Botania competes on teak and ceramic composite specialization for luxury terrace installations.
Outdoor furniture comprises weather-engineered seating, surface, and shade systems built from treated hardwoods, powder-coated aluminum, high-density polyethylene, or synthetic wicker, typically rated for UV stability, moisture resistance, and load-bearing performance in exterior conditions. Metal and wicker segments command widening share as consumers prioritize longevity and low maintenance over traditional wood refinishing cycles. The hospitality end-user channel represents the fastest-expanding demand pool, driven by hotel rooftop concepts and al fresco dining mandates that specify commercial-grade durability certifications.
EPA oversees volatile organic compound limits on paints and coatings applied to metal frames, while California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation enforces TB 117-2013 flammability standards that reshape foam sourcing decisions. The EU REACH regulation restricts chromated copper arsenate in preserved timber, redirecting European manufacturers toward heat-treated or acetylated wood alternatives. Stakeholders must monitor evolving chemical compliance thresholds and certification reciprocity between jurisdictions to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
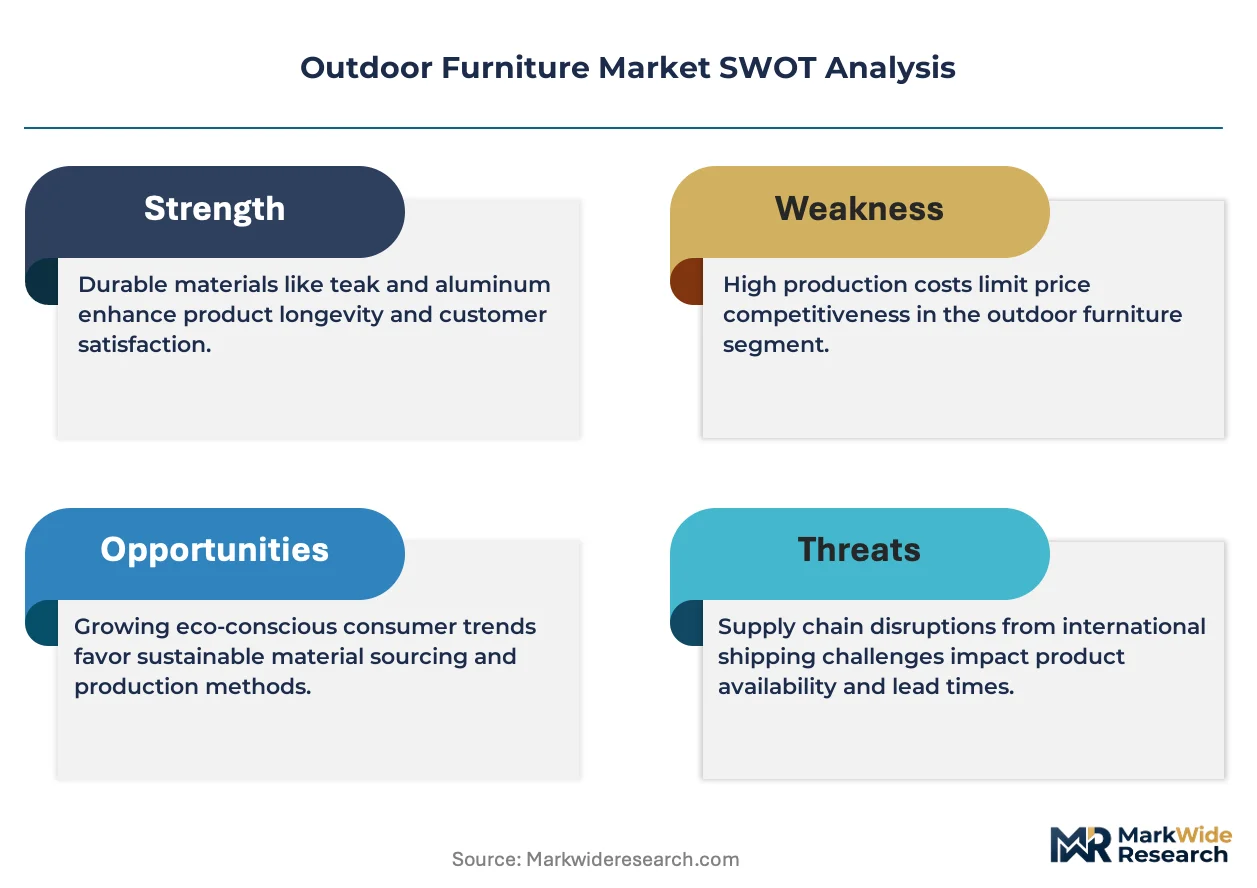
Hospitality procurement mandates for commercial-grade durability certifications are restructuring supplier qualification requirements across the outdoor furniture sector, compressing lead times and elevating testing protocols.
Growth Catalysts
- TB 117-2013 Compliance:California's updated flammability standards are compelling foam and fabric reformulation across supply chains, creating premium positioning for certified suppliers.
- Resort Rooftop Concepts:Hotel chains are expanding al fresco dining mandates that specify weather-resistant seating ensembles, pulling volume toward commercial-grade manufacturers.
- Suburban Backyard Renovation:United States homeowners are redirecting discretionary spending toward outdoor living spaces, sustaining demand for residential-grade shade and surface systems.
Market Restraints
- Teak Supply Concentration:Burmese and Indonesian plantation capacity constraints are elevating hardwood input costs and elongating procurement timelines for luxury terrace manufacturers.
- REACH Chemical Restrictions:ECHA's prohibition on chromated copper arsenate in preserved timber is forcing European producers toward higher-cost acetylated wood alternatives.
- HDPE Resin Volatility:Petroleum-derived synthetic wicker feedstock prices fluctuate with crude benchmarks, compressing margins on mid-market seating collections.
Strategic Opportunities
- Heat-Treated Timber Innovation:Finnish and Swedish producers are commercializing thermally modified ash and pine as CCA-free alternatives, opening premium positioning in EU contract markets.
- Direct-to-Contractor Channels:Digital platforms are bypassing traditional distributor markups for landscape architecture firms specifying large-scale hospitality installations.
- EPA VOC Compliance Services:Third-party certification providers are capturing value by guiding metal frame coaters through volatile organic compound limit documentation.
Industry Challenges
- Weaving Artisan Scarcity:European synthetic wicker ateliers face recruitment gaps for skilled hand-weaving technicians, constraining output scaling for luxury collections.
- Multi-Jurisdiction Certification:Manufacturers distributing across US, EU, and Asia-Pacific must maintain parallel testing documentation for TB 117-2013, REACH, and varying national fire codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Furniture Market |
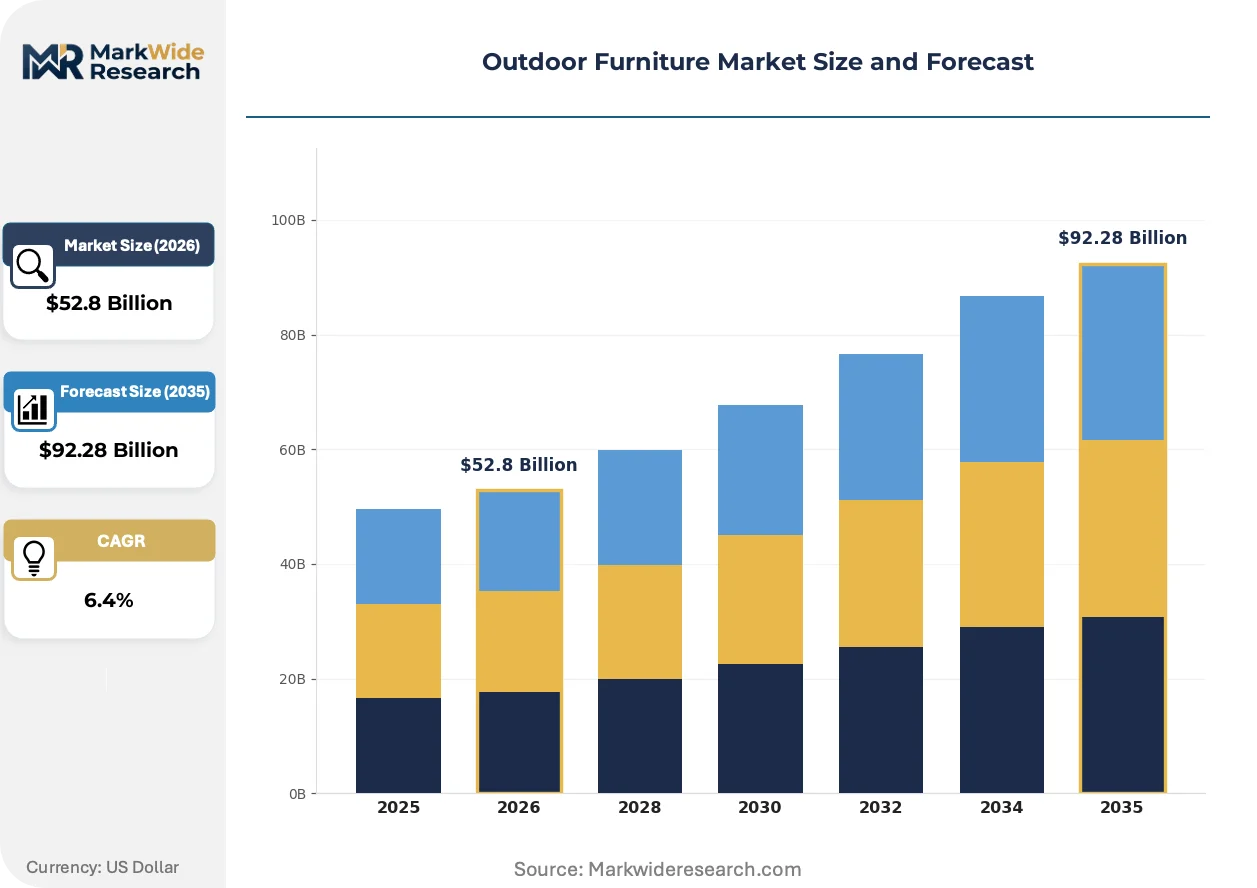
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Sofas, Umbrellas Material: Wood, Metal, Plastic, Wicker End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Retail Stores, Direct Sales, Wholesale |
| Companies Covered | Gloster Furniture, Royal Botania, IKEA, Woodard Furniture, Landscape Forms, Inc., Ashley Furniture Industries, Inc., Kettal Group, Aura Global Furniture, Brown Jordan Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Furniture Market Emerging Trajectories
Powder-coating chemistry advances and digital specification tools are compressing product development cycles while elevating performance benchmarks for exterior-rated metal systems.
Ceramic composite tabletops are expanding into luxury terrace installations by delivering granite-equivalent scratch resistance at reduced weight. High-end hotel operators in Miami and Dubai are specifying these surfaces for rooftop pool deck dining. The technology is expanding into mid-market hospitality chains as production scale drives unit cost compression.
REACH restrictions on preserved timber are redirecting European supply chains toward heat-treated and acetylated wood alternatives. German and Italian manufacturers are reformulating product lines to maintain EU market access. Outdoor furniture producers serving northern European markets are accelerating supplier qualification for thermally modified ash from Nordic sawmills.
Landscape architecture firms are consolidating vendor relationships around single-source responsibility for seating, surface, and shade systems. This specification behavior favors full-line manufacturers capable of unified warranty coverage. Procurement consolidation is most visible in United States coastal resort developments where project timelines compress vendor onboarding windows.
Outdoor Furniture Market Segmentation
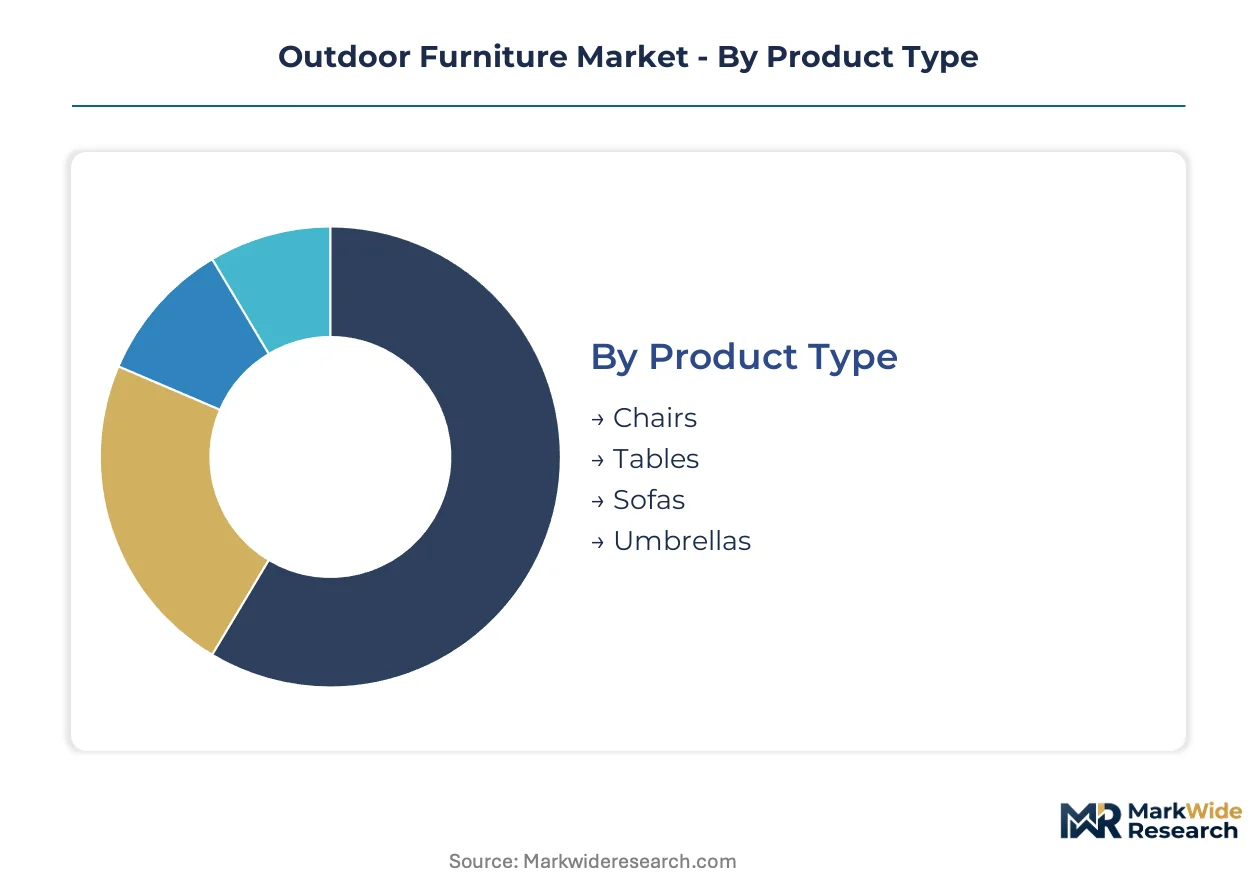
Outdoor furniture purchasing behavior splits sharply between volume-driven residential refresh cycles and specification-heavy hospitality contracts. Material and distribution channel choices diverge across these endpoints, with durability certifications commanding premium positioning in commercial installations while cost compression dominates suburban backyard procurement.
Product Type:
Volume concentrates in seating systems, yet margin expansion tracks toward integrated shade and surface combinations.
- Chairs:Stackable aluminum and synthetic wicker designs dominate hospitality procurement for rooftop dining venues. Hotel operators in Miami and Dubai specify commercial-grade frames with powder-coated finishes rated for salt-air exposure.
- Tables:Ceramic composite tabletops are displacing granite in luxury terrace installations by delivering equivalent scratch resistance at reduced weight. Mid-market hospitality chains are adopting these surfaces as production scale compresses unit costs.
- Sofas:Deep-seating modular systems command premium positioning in residential outdoor living spaces.
- Umbrellas:Cantilever and center-pole shade systems complete specification bundles for landscape architecture firms.
Mature deployment sits with Chairs. Newer deployment is concentrated in Tables.
Material:
Cost tier stratification runs from petroleum-derived synthetics through plantation hardwoods to specialized metal alloys.
- Wood:Teak from Burmese and Indonesian plantations faces supply constraints elevating input costs for luxury manufacturers. REACH restrictions on chromated copper arsenate are redirecting European producers toward heat-treated ash from Nordic sawmills.
- Metal:Powder-coated aluminum extrusions anchor commercial-grade durability certifications. EPA volatile organic compound limits on frame coatings reshape supplier qualification requirements across US distribution channels.
- Plastic:High-density polyethylene synthetic wicker feedstock fluctuates with crude benchmarks, compressing margins on mid-market collections.
- Wicker:European hand-weaving ateliers face technician recruitment gaps constraining output scaling for luxury collections.
Established specification patterns favor Metal. Emerging substitution dynamics center on Wood alternatives.
End User:
Application context determines performance certification requirements and procurement timeline compression.
- Residential:Suburban backyard renovation spending in the United States sustains demand for shade and surface systems prioritizing aesthetics over commercial durability ratings.
- Commercial:Corporate campus and municipal park installations specify mid-tier longevity with standardized maintenance protocols.
- Hospitality:Hotel rooftop concepts and al fresco dining mandates represent the steepest expansion trajectory, pulling volume toward weather-resistant seating ensembles with unified warranty coverage.
- Retail:Showroom display and seasonal merchandising drive shorter replacement cycles with lower per-unit durability thresholds.
Volume leadership remains with Residential. Margin expansion concentrates in Hospitality.
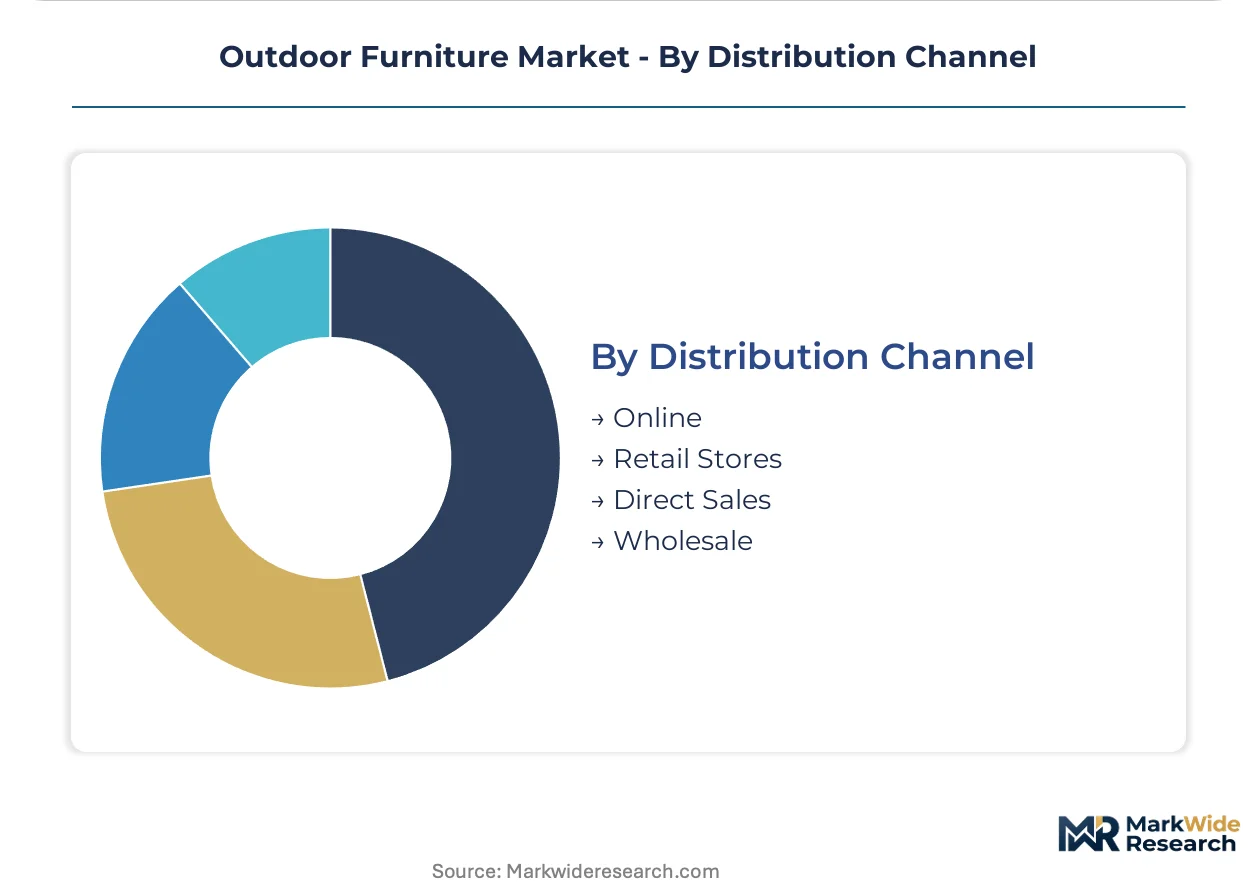
Distribution Channel:
Customer type and project scale dictate channel selection, with digital platforms eroding traditional distributor markups in contract segments.
- Online:Direct-to-consumer platforms capture residential refresh spending through augmented reality visualization tools and compressed delivery timelines.
- Retail Stores:Big-box and specialty showroom footprints dominate suburban homeowner procurement with immediate availability and tactile material evaluation.
- Direct Sales:Landscape architecture firms and hospitality developers consolidate vendor relationships around single-source responsibility for large-scale installations.
- Wholesale:Regional distributors maintain inventory positions for contractor-grade metal and synthetic collections serving commercial maintenance programs.
Traditional volume flows through Retail Stores. Channel shift momentum favors Direct Sales in contract segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Teak plantations in Indonesia and Myanmar anchor hardwood supply chains for luxury terrace manufacturers. Aluminum extrusion clusters in China and Germany feed powder-coating operations serving commercial-grade durability mandates. Synthetic wicker weaving ateliers concentrate in Belgium and the Netherlands.
United States
Suburban backyard renovation spending and hotel rooftop dining expansions pull volume toward weather-resistant seating systems. EPA volatile organic compound limits on metal frame coatings reshape supplier qualification requirements across distribution channels. Miami and Dubai hospitality developers specify salt-air-rated powder-coated finishes for pool deck installations.
Germany
Heat-treated ash from Nordic sawmills substitutes for chromated copper arsenate-treated timber under REACH restrictions. ECHA chemical compliance mandates redirect manufacturers toward acetylated wood alternatives. Bavarian and North Rhine-Westphalian fabricators reformulate product lines to maintain EU market access.
China
Aluminum extrusion capacity and synthetic wicker resin processing dominate mid-market supply economics. MIIT industrial standards guide powder-coating chemistry for export-rated metal systems. Guangdong and Zhejiang manufacturing clusters serve hospitality procurement timelines for international hotel chains.
Belgium
European synthetic wicker weaving ateliers face technician recruitment gaps constraining luxury collection output. REACH timber preservation rules accelerate supplier qualification for thermally modified alternatives. Flemish producers commercialize CCA-free wood treatments for contract market positioning.
Indonesia
Plantation teak supply constraints elevate input costs and elongate procurement timelines for hardwood-dependent manufacturers. National forestry regulations govern harvest quotas and export licensing for premium timber grades. Javanese sawmills concentrate processing capacity serving terrace furniture specialists.
Outdoor Furniture Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from single-material specialization into full-line seating, surface, and shade systems. The vendor base stratifies across three tiers: mass-market flat-pack distributors, mid-market metal and synthetic specialists, and luxury hardwood and ceramic composite fabricators. Consolidation pressure concentrates among hospitality-grade suppliers seeking unified warranty coverage capabilities. Geographic expansion and backward integration into captive aluminum extrusion represent the dominant competitive moves.
Among European luxury fabricators, Royal Botania and Kettal Group exemplify the premium-tier archetype through material specialization and in-house production control. IKEA anchors the mass-market vector with flat-pack logistics networks compressing landed costs on residential collections. These three occupy positions spanning the cost-tier spectrum from economy-scale distribution through bespoke terrace installations.
| Leading Market Players |
|---|
| Gloster Furniture |
| Royal Botania |
| IKEA |
| Woodard Furniture |
| Landscape Forms, Inc. |
| Ashley Furniture Industries, Inc. |
| Kettal Group |
| Aura Global Furniture |
| Brown Jordan Co. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between commercial durability mandates and residential refresh cycles shapes both margin structures and supplier qualification economics across outdoor furniture procurement. Hospitality buyers absorbing unified warranty bundles face 40-60% unit premiums over unbundled residential equivalents, while supply chains split between captive aluminum extrusion networks and spot-market resin sourcing.
Pricing Analysis
Warranty bundling separates hospitality procurement from residential transactions, with commercial-grade seating systems commanding premium positioning through unified coverage terms. Three-tier pricing structure across premium, standard, and economy levels tracks material certification ladders—thermally modified ash and ceramic composite tabletops anchor premium tiers, while petroleum-derived synthetic wicker collections face cost compression. Pricing pressure stems from HDPE resin volatility tethered to crude benchmarks, squeezing mid-market margins. Residential suburban buyers exhibit highest price sensitivity, prioritizing immediate availability over longevity ratings.
Supply Chain Analysis
Dual-sourcing mandates from hospitality developers require parallel qualification of aluminum extruders across China and Germany alongside Nordic sawmills for heat-treated timber alternatives. Raw material dependencies center on Burmese and Indonesian plantation teak, Guangdong resin processing, and Flemish weaving atelier capacity. Single-source vulnerability concentrates in European hand-weaving technician pools, where recruitment gaps constrain luxury collection scaling. Distribution runs through landscape architecture direct channels for contract segments and big-box retail footprints for residential refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic composite tabletop technology is displacing granite in luxury terrace installations, compressing development timelines and resetting performance benchmarks across hospitality specification.
For Market Incumbents: Extend captive aluminum extrusion capacity into powder-coating operations to defend margin position against resin volatility. Secure thermally modified ash supply agreements with Nordic sawmills ahead of REACH-driven CCA substitution. Certification investment in TB 117-2013 foam compliance creates switching costs against mid-market entrants lacking testing infrastructure. For New Entrants and Emerging Players: Enter via direct-to-contractor digital platforms bypassing traditional distributor markups in United States coastal resort developments. Target hospitality rooftop dining segments where project timelines compress vendor onboarding windows and unified warranty requirements favor new qualification. White-space exists in EPA VOC compliance documentation services for metal frame coaters lacking regulatory expertise. For Investors and Strategic Acquirers: Re-rating potential sits with full-line manufacturers capable of single-source responsibility for seating, surface, and shade systems given procurement consolidation by landscape architecture firms. Long-term viability favors backward-integrated fabricators controlling aluminum extrusion and weaving atelier capacity. Watch thermally modified timber adoption rates in German and Italian reformulation cycles as inflection signal for CCA-free supply chain winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of powder-coated frames secures commercial-grade certification timelines for hospitality procurement. |
| Heat-Treated Timber Supplier Qualification | Nordic sawmill partnerships maintain EU market access under ECHA REACH restrictions on preserved timber. |
| Direct-to-Contractor Platform Launch | Digital specification tools compress distributor markups for landscape architecture firms consolidating vendor relationships. |
| Ceramic Composite Tabletop Scale-Up | Production volume expansion drives unit cost compression into mid-market hospitality chains. |
| EPA VOC Compliance Certification | Third-party documentation services capture value from metal coaters navigating volatile organic compound limits. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this outdoor furniture market analysis. Primary interviews with hospitality procurement directors, landscape architecture specification leads, aluminum extrusion plant managers, and Nordic sawmill commercial officers combined with secondary validation from EPA enforcement databases, ECHA REACH substance restrictions, and MIIT industrial standards. Bottom-up shipment analysis across material grades and end-use channels triangulated against top-down spending estimates from residential renovation and hospitality capex disclosures.
Reconciliation of production capacity data, import-export flows, and end-user procurement surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material certification tier, end-use application context, distribution channel structure, and regional regulatory cluster. CAGRs derived from trend extrapolation of hospitality rooftop expansion rates, suburban backyard renovation spending patterns, and substitution dynamics between timber preservation technologies. Forecast inputs incorporated REACH chemical restriction timelines and California TB 117-2013 compliance adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petroleum price volatility or Indonesian teak harvest quota disruptions. Deviation in European weaving atelier technician recruitment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Patio Furniture Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Middle-East Christmas Tree Market