
 Italy Home Furniture Market | 2026-2036
Italy Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Home Furniture Market Outlook
Market Context
Modular sofa configurations is broadening buyer choice across Italian living spaces. Natuzzi leverages vertical integration from leather tanning to finished seating to control cost and delivery timelines. Molteni&C anchors its position through deep manufacturing scale in the Brianza furniture district. Giorgetti differentiates via artisanal woodcraft specialization that commands premium positioning.
Technical Definition and Segment Structure
Italy home furniture encompasses movable domestic fixtures engineered from solid timber, engineered panels, metal hardware, and upholstery textiles, produced through CNC milling, hand-finishing, and modular assembly for residential interior functionality. Wood material dominates structural value, though fabric upholstery captures expanding margin pools in the sofa segment. Modern style leads volume, while rustic applications sustain niche premiums among renovators seeking heritage aesthetics.
Regulatory Environment
Italy's national implementation of EU Ecodesign standards and REACH chemical compliance shapes material certification requirements for manufacturers. The country's environmental ministry enforces timber traceability rules that filter market access for uncertified suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and their cost pass-through implications for pricing architecture.
Market Dynamics
Residential renovators across Lombardy and Veneto are accelerating modular living system purchases, pressuring manufacturers to compress delivery timelines while maintaining artisanal quality standards. This demand surge is restructuring supplier relationships around the Brianza furniture cluster.
Growth Catalysts
- EU Ecodesign alignment:Italy's environmental ministry enforces timber traceability rules that filter market access, advantaging certified domestic manufacturers over uncertified imports.
- Modular sofa demand:Urban apartment dwellers in Milan and Turin drive configuration flexibility requirements, expanding addressable buyer segments beyond traditional single-family homes.
- Lombard manufacturing concentration:The Brianza district's dense supplier ecosystem enables rapid prototyping and short-run customization that northern Italian renovators prioritize.
Market Restraints
- Certified leather supply scarcity:REACH-compliant tanning capacity concentrates among a handful of Veneto suppliers, creating input bottlenecks for premium upholstery lines.
- Artisan skill attrition:Traditional hand-finishing expertise retires faster than vocational programs in Piedmont and Tuscany can replenish, constraining heritage-product output.
- Energy cost volatility:Natural gas price swings disproportionately impact kiln-drying operations in Friuli-Venezia Giulia, compressing margin stability for solid-wood specialists.
Strategic Opportunities
- Sicily and Apulia underpenetration:Southern Italian markets show lower modular furniture penetration rates, creating whitespace for regional distribution partnerships.
- Extended producer responsibility frameworks:Pending national implementation of EU-mandated take-back schemes positions early movers to capture circular economy service revenue.
- Digital configuration platforms:Web-based 3D visualization tools enable direct-to-consumer channels that bypass traditional retail markups in metropolitan markets.
Industry Challenges
- CNC programming talent scarcity:Advanced milling operations require specialized operators that technical institutes in Emilia-Romagna struggle to graduate at sufficient scale.
- REACH certification timelines:Chemical compliance documentation for imported fabric treatments creates 8-12 week procurement delays that disrupt just-in-sequence manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Home Furniture Market |
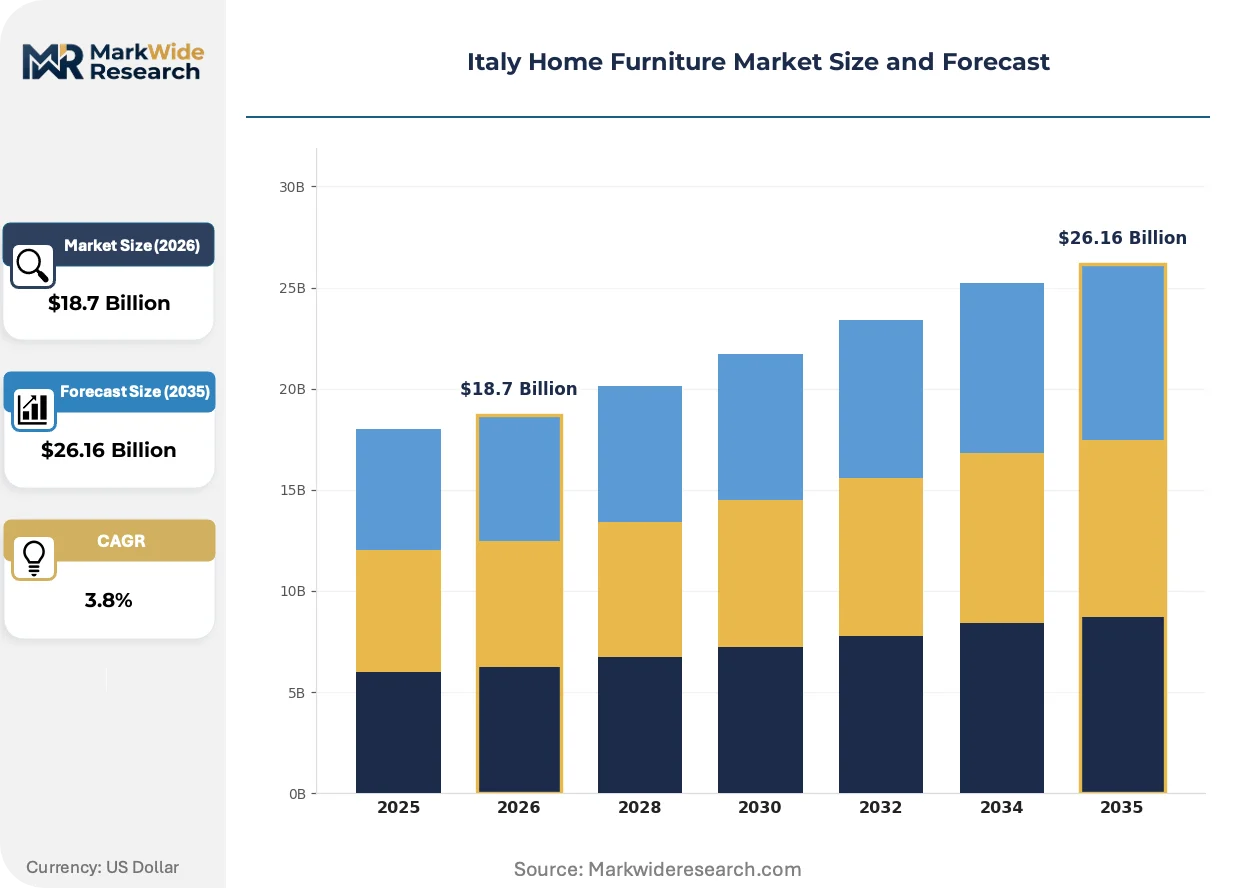
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Dining Tables, Wardrobes Material: Wood, Metal, Glass, Fabric Style: Modern, Traditional, Rustic, Minimalist End User: Residential, Commercial, Rental Properties, Renovators |
| Companies Covered | Natuzzi, Giorgetti, Minotti, Molteni&C, Cassina, B&B Italia, Flexform, Arper, Poltrona Frau, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Home Furniture Market Strategic Shifts
Italian home furniture production is pivoting toward digitally enabled customization and material transparency, with manufacturers investing in traceability infrastructure to preempt regulatory enforcement and capture premium positioning among design-conscious buyers.
Mass-customization software is consolidating control over specification workflows. Mid-market manufacturers in the Brianza corridor deploy parametric design tools that let buyers adjust sofa dimensions and upholstery combinations without engineering intervention. This capability compresses the traditional showroom-to-factory information loop, enabling made-to-order production at near-stock lead times.
REACH chemical compliance is tightening material sourcing requirements. Italy's national environmental regulator enforces documentation standards for imported textiles and engineered panels that previously entered with minimal scrutiny. Upholstery suppliers serving the Milan design corridor now face mandatory substance testing that adds cost but creates competitive separation for domestic-certified producers.
Renovator buying patterns are fragmenting across project types. Residential investors in Rome and Florence increasingly purchase furniture packages through property development channels rather than traditional retail, while end-consumers in Bologna and Genoa favor direct brand relationships. This bifurcation forces manufacturers to maintain parallel go-to-market capabilities without economies of scale consolidation.
Italy Home Furniture Market Segmentation
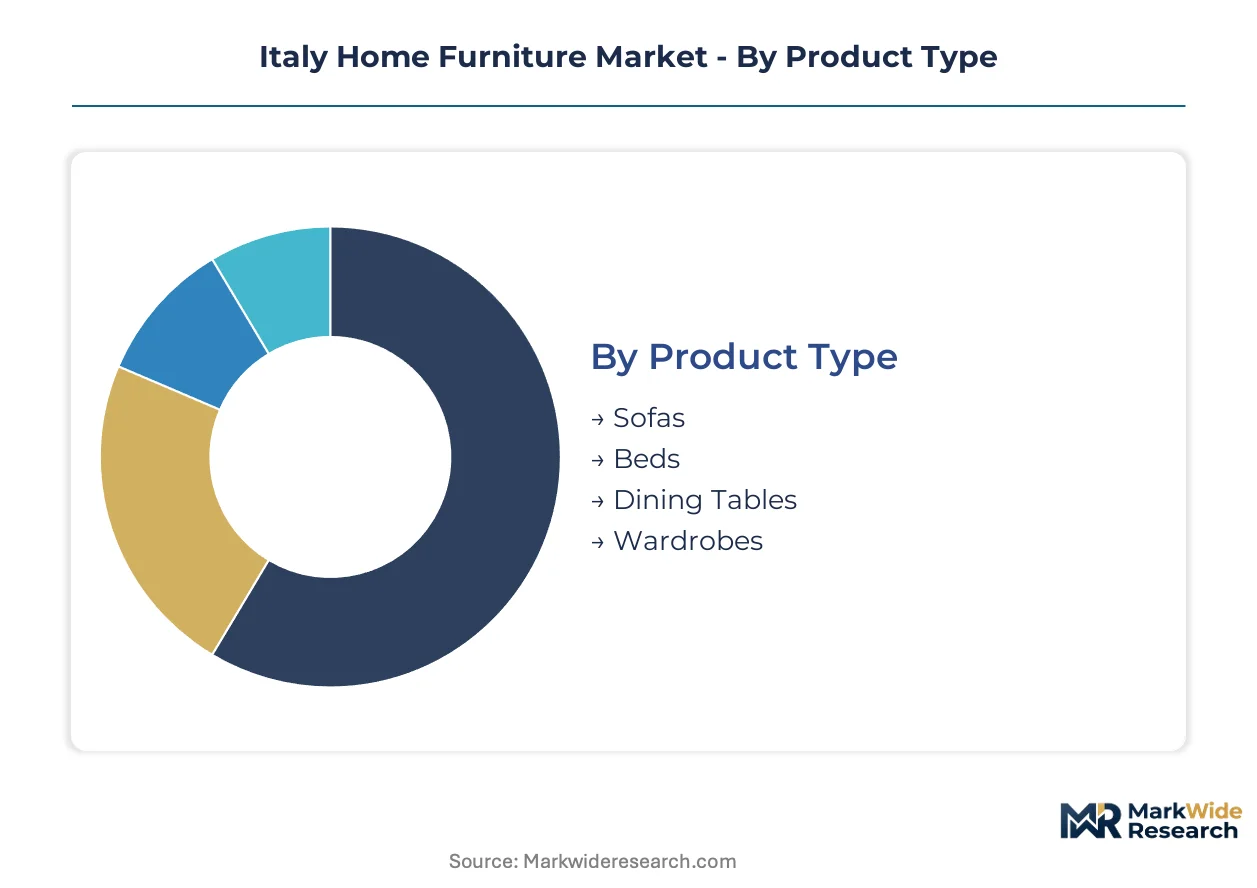
Italian home furniture manufacturers configure production lines around distinct material and style specifications that determine tooling investments and supplier relationships. Segmentation clarity enables producers to match capital deployment against buyer willingness to pay for customization and certification.
Product Type:
Sofas and beds demand the heaviest upfront investment in upholstery workshops and mattress assembly infrastructure, while dining tables and wardrobes rely more heavily on CNC milling capacity that spreads across multiple product lines.
- Sofas:Modular frame systems combine engineered hardwood cores with fabric or leather upholstery. Demand concentrates among Milan and Turin apartment dwellers seeking reconfigurable seating for compact living spaces, pressured by EU Ecodesign material traceability requirements.
- Beds:Slatted base mechanisms and upholstered headboards require dedicated spring-coil and foam-cutting equipment. Lombardy renovators drive specification upgrades toward ergonomic adjustability and certified low-VOC finishes.
- Dining Tables:Solid timber and veneered surfaces dominate, with extendable mechanisms adding engineering complexity. Brianza manufacturers leverage existing woodworking infrastructure for this segment.
- Wardrobes:Built-in and freestanding closet systems integrate sliding hardware and interior fittings. Production scales efficiently through panel-processing lines shared with kitchen cabinetry.
Sofas absorb the bulk of installed upholstery capacity; beds are expanding most quickly among health-conscious residential buyers.
Material:
Wood commands the widest supplier network and longest heritage expertise, while fabric and metal require more specialized certification pathways that filter competitive entry.
- Wood:Solid timber and engineered panels form structural frames and visible surfaces. REACH-compliant adhesive and finish sourcing from domestic suppliers advantages Brianza producers over import-dependent competitors.
- Metal:Powder-coated steel and aluminum appear in table bases, bed frames, and hardware. Demand clusters in minimalist and industrial-style applications among Genoa and Bologna design buyers.
- Glass:Tempered and laminated surfaces serve tabletops and display cabinetry. Processing requires specialized tempering furnaces concentrated among a handful of Veneto suppliers.
- Fabric:Natural and synthetic textiles cover seating and bedding surfaces. Certified chemical compliance documentation creates procurement delays that constrain just-in-sequence manufacturing.
Wood retains the deepest supplier ecosystem; fabric is climbing the fastest as upholstery customization becomes a primary purchase differentiator.
Style:
Modern and minimalist styles favor standardized components that amortize tooling costs across high volumes, while traditional and rustic approaches require artisan labor that resists capital substitution.
- Modern:Clean lines, neutral palettes, and modular dimensions define this segment. Milan design corridor buyers prioritize rapid delivery of certified sustainable configurations.
- Traditional:Ornate carving, rich wood tones, and classical proportions characterize heritage Italian craftsmanship. Tuscany and Piedmont workshops face skill attrition that limits output expansion.
- Rustic:Distressed finishes, reclaimed timber aesthetics, and farmhouse proportions appeal to secondary residence owners in Umbria and Marche. Production scales through semi-automated distressing techniques.
- Minimalist:Extreme simplicity, hidden hardware, and monochromatic surfaces target urban professionals. Metal and glass integration raises material costs but commands premium positioning.
Modern styling dominates production volume; minimalist configurations are gaining share fastest among metropolitan apartment renovations.
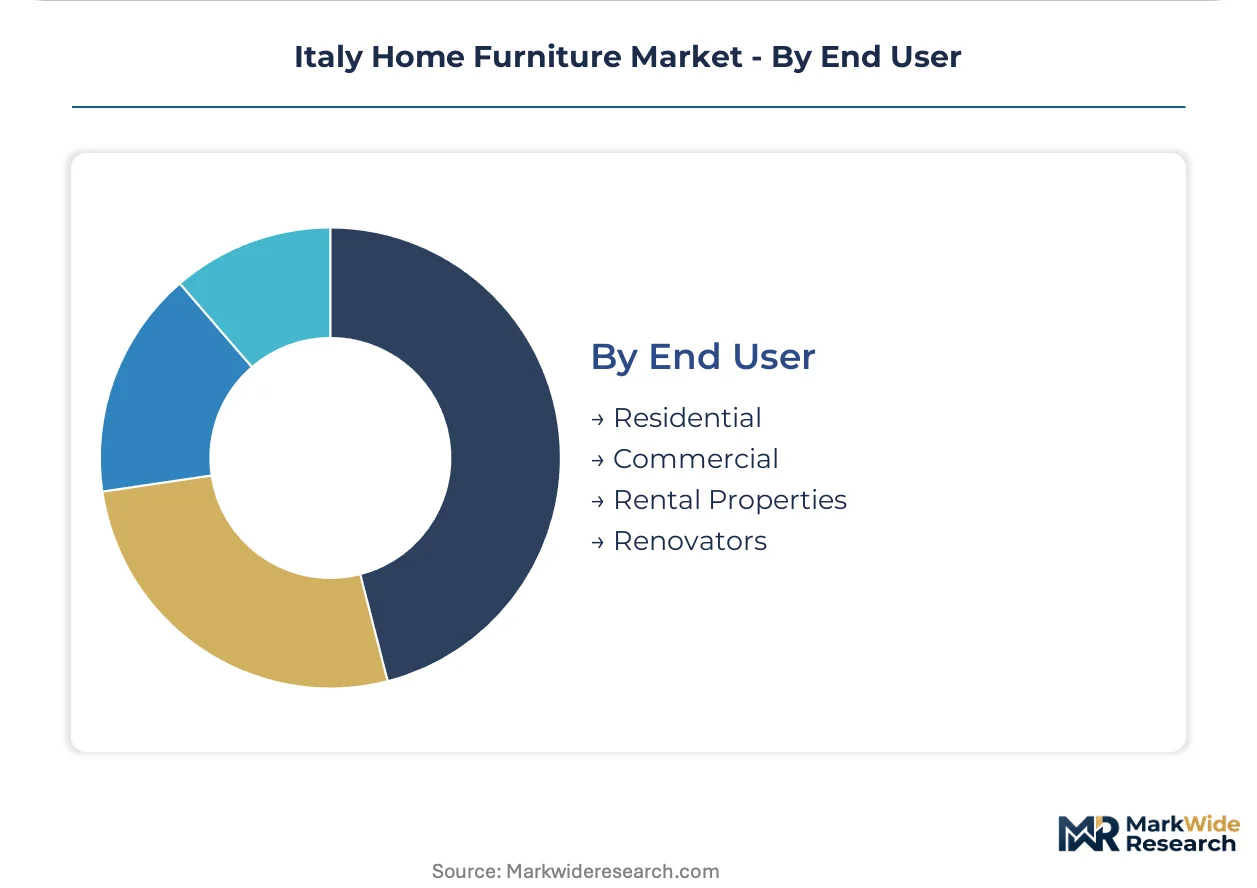
End User:
Residential buyers and renovators drive the most fragmented demand patterns, requiring flexible manufacturing, while commercial and rental channels favor standardized specifications that reward scale.
- Residential:Individual homeowners purchasing for primary residences. Lombardy and Veneto households lead specification complexity and sustainability certification requirements.
- Commercial:Hotels, offices, and hospitality venues purchasing in bulk. Procurement runs through design firms and facility managers prioritizing durability warranties and fire-safety compliance.
- Rental Properties:Landlords and property investors furnishing units for lease. Cost discipline dominates, with preference for rapid-replacement stock items over custom configurations.
- Renovators:Residential remodeling contractors and design-build firms. This segment accelerates modular system adoption and compresses delivery timeline expectations across all product categories.
Residential buyers command the broadest SKU variety; renovators are expanding their share of manufacturer attention fastest as project-based purchasing consolidates volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian furniture production concentrates in northern manufacturing clusters while consumption spreads across wealthier metropolitan areas and secondary residence markets. This geographic split shapes logistics architecture and regional pricing variation.
Lombardy
Milan apartment renovations drive modular sofa demand among design-conscious urban professionals. The region's environmental agency enforces EU Ecodesign timber traceability protocols that filter supplier access. The Brianza furniture district hosts dense networks of CNC milling shops and upholstery workshops serving rapid-turnaround custom orders.
Piedmont
Turin households prioritize ergonomic bed systems with certified low-VOC finishes. REACH chemical compliance documentation requirements from Italy's national environmental regulator constrain imported fabric procurement timelines. Traditional woodworking ateliers in the Alpine foothills face accelerating artisan retirements that limit heritage-style output expansion.
Veneto
Padua and Verona renovators accelerate purchases of extendable dining tables and fitted wardrobes. The region's tanning industry clusters supply REACH-compliant leather to premium upholstery lines, though capacity constraints create input bottlenecks. Glass tempering furnaces concentrated outside Venice serve display cabinetry demand from design firms.
Tuscany
Florence and Siena secondary residence owners sustain demand for rustic distressed-finish furniture. Italy's vocational training shortfalls hit hardest here, with hand-finishing expertise retiring faster than regional institutes replenish skilled labor. Semi-automated distressing techniques in Arezzo province partially offset craft labor scarcity.
Lazio
Rome property investors increasingly purchase furniture packages through development channels rather than retail showrooms. The capital's environmental enforcement of extended producer responsibility frameworks pressures manufacturers toward circular economy service models. Distribution partnerships targeting this channel consolidate around logistics hubs in the metropolitan periphery.
Italy Home Furniture Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct buyer segments. The vendor base organizes into three recognizable tiers: heritage luxury houses commanding artisan premiums, mid-market scale operators optimizing Brianza manufacturing density, and emerging digital-native brands bypassing traditional retail markups. Consolidation pressure runs highest among mid-market producers seeking volume defense against private-label imports. Strategic moves center on backward integration into certified material sourcing and parametric design platform deployment.
Among heritage-positioned specialists, Natuzzi exemplifies captive supply chain control through in-house leather tanning operations. Molteni&C anchors the scale-driven tier through deep manufacturing infrastructure in the Brianza district. Giorgetti occupies a position exemplifying artisanal woodcraft specialization that commands premium positioning among design buyers.
| Leading Market Players |
|---|
| Natuzzi |
| Giorgetti |
| Minotti |
| Molteni&C |
| Cassina |
| B&B Italia |
| Flexform |
| Arper |
| Poltrona Frau |
| Others |
Value Chain & Pricing Dynamics
Parametric design software deployment across the Brianza manufacturing corridor compresses specification-to-production cycles while simultaneously concentrating cost advantages among capitalized mid-market producers. This technological shift rewards firms with existing CNC milling density, filtering price-competitive entry for smaller workshops lacking digital configuration platforms.
Pricing Analysis
Margin tightening in the mid-market tier reflects certified material cost pass-throughs from EU Ecodesign compliance documentation. Three-tier pricing structure across premium, standard, and economy levels separates heritage artisan positioning from Brianza scale operators and import-dependent value lines. Price differentiation hinges on REACH certification grade and customization depth. Renovators show lowest price sensitivity; rental property investors exhibit highest.
Supply Chain Analysis
Reverse-logistics infrastructure for take-back schemes remains embryonic, constraining circular economy service revenue capture pending national extended producer responsibility implementation. Raw material sourcing draws from Italian timber forests, Veneto tanning operations, and German engineered panel suppliers. Supply chain risk centers on REACH-compliant leather capacity bottlenecks. Distribution runs through Milan design corridor showrooms, regional retail partnerships, and emerging direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy home furniture market is becoming a vertical-integration race as manufacturers pursue captive control over certified material supply to defend margin architecture against compliance cost volatility.
For Market Incumbents: To counter private-label import encroachment, Molteni&C-scale operators should consolidate Brianza supplier networks through selective acquisition of distressed CNC milling capacity. Natuzzi-model backward integration into tanning operations insulates against REACH certification delays. Channel control through owned flagship expansion in Rome and Florence property development channels captures renovator volume consolidation. For New Entrants and Emerging Players: EU Ecodesign alignment in Italy opens a window for digital-native brands to bypass traditional retail markups via web-based 3D configuration platforms. Sicily and Apulia underpenetration offers the most penetrable whitespace for regional distribution partnerships. Direct-to-consumer positioning with rapid-turnaround modular sofa customization captures Milan apartment dweller segments underserved by heritage showroom models. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified European furniture conglomerates seeking Italian design heritage positioning. Long-term viability favors targets with installed parametric design infrastructure and established REACH certification documentation workflows. Watch Brianza district CNC programming talent pipeline expansion as inflection indicator for sustainable manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Tanning | Captive REACH-compliant leather supply insulates Natuzzi-model upholstery lines against Veneto supplier bottlenecks. |
| Parametric Design Platform Deployment | Mass-customization software enables Brianza manufacturers to compress made-to-order lead times toward stock-item parity. |
| Extended Producer Responsibility Pre-positioning | Early circular economy service infrastructure captures renovator preference ahead of national take-back mandate implementation. |
| Regional Distribution Partnership Expansion | Southern Italian channel development in Sicily and Apulia accesses whitespace markets with lower modular penetration. |
| Artisan Skill Pipeline Investment | Vocational program partnerships in Piedmont and Tuscany workshops address heritage-product output constraints from retirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with furniture manufacturing executives, upholstery workshop owners, design firm procurement leads, and regional distribution channel managers. FederlegnoArredo industry statistics, Italy's Ministry of Environment Ecodesign enforcement documentation, and EU REACH compliance registries provided demand-side validation. Bottom-up production capacity estimates triangulated against top-down consumption surveys across Lombardy, Veneto, and Tuscany metropolitan markets.
Reconciliation of shipment data, import-export flows, and channel inventory levels informed volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, material composition, style category, and end-user archetype dimensions. CAGRs derived from regression analysis of historical production trends against renovator spending pattern shifts and regulatory compliance cost trajectories. Forecast inputs included Brianza district capacity utilization rates and certified leather supply availability indices.
The model assumes a particular technology adoption path; alternative pathways for parametric design platform penetration would alter the outlook if vocational training shortfalls constrain CNC programming talent supply faster than anticipated. Forecasts reflect documented assumptions regarding EU Ecodesign enforcement intensity and extended producer responsibility timeline implementation. Practitioners should monitor REACH certification documentation backlogs and natural gas price volatility for Friuli-Venezia Giulia kiln operations as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Multifunctional Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Russia Home Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Contract Furniture and Furnishing Market
Furniture
Luxury Furniture Market
Furniture
Saudi Arabia Furniture Market
Furniture
France Furniture Market
Furniture
Europe School Furniture Market
Furniture
Recliner Chair Market
Furniture
Massive Wood Slabs Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Kids and Nursery Furniture Market