
 Japan Home Furniture Market | 2026-2036
Japan Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Home Furniture Market Foresight
The capability gap between mass-market fabricators and precision wood specialists is collapsing as automated CNC joinery becomes accessible at mid-scale investment levels. Nitori Holdings Co., Ltd. leverages its vertically controlled supply chain to dominate price-sensitive segments across suburban retail chains. Karimoku Furniture Inc. anchors its position through captive lumber sourcing and artisan-certified production in Aichi Prefecture. Hida Sangyo Co., Ltd. differentiates via deep specialization in traditional joinery techniques adapted for contemporary interiors.
Japan home furniture comprises movable domestic fixtures—seating, sleeping surfaces, tables, and storage—typically fabricated from solid timber, engineered boards, metal frames, or upholstered composites, with dimensions optimized for tatami-module spatial planning and load-rated for seismic anchoring. Its primary purpose is to maximize functional utility within constrained floor areas while conforming to JIS durability and formaldehyde-emission thresholds. Sofas and beds command the largest revenue pools as urban households prioritize comfort in shrinking living spaces, while Scandinavian and minimalist styles outpace traditional forms among younger buyers seeking visual lightness. Wood remains the dominant material by value, though metal and upholstery gain share in rental-oriented and pet-resistant product lines.
METI enforces energy-efficiency labeling and circular-economy disclosure rules that reshape procurement criteria for large retailers, while JIS standards govern structural safety and chemical emissions in residential settings. The Consumer Affairs Agency monitors misleading claims about domestic origin and sustainable sourcing, tightening compliance costs for imported components. Stakeholders must track how evolving building-code seismic requirements and municipal fire-safety ordinances will redefine furniture anchoring specifications and material flame-resistance thresholds.
Market Dynamics
Automated CNC joinery is collapsing the capability gap between mass-market fabricators and precision wood specialists, redistributing competitive advantage toward mid-scale producers who can now achieve artisan-grade tolerances without captive craft labor.
Growth Catalysts
- METI Circular-Economy Disclosure Rules:Large retailers now face mandatory supply-chain transparency requirements, accelerating procurement shifts toward certified low-emission finishes and domestic component sourcing.
- Seismic Anchoring Mandates:Revised municipal building codes in Tokyo and Osaka drive replacement cycles for load-rated storage and sleeping systems, creating sustained demand for JIS-certified structural furniture.
- Tatami-Module Spatial Planning:Compact urban apartments standardize on 910mm grid dimensions, pulling demand for multifunctional pieces that integrate seating, storage, and sleeping surfaces within fixed footprints.
Market Restraints
- Solid Timber Input Volatility:Captive lumber sourcing in Aichi Prefecture and Hida regions concentrates supply risk, exposing fabricators to weather-driven harvest disruptions and yen-denominated import competition.
- JIS Certification Timeline Friction:Formaldehyde-emission testing and structural load verification create 8-14 month product approval windows, compressing margin recovery for seasonal collections.
- Metal Frame Substitution:Rental-oriented landlords increasingly specify steel shelving and aluminum bed frames for pet-resistant durability, displacing wood value share in investor-class housing.
Strategic Opportunities
- Kyushu and Tohoku Underpenetration:Prefectures outside the Kanto corridor show renovation cycle gaps of 4-7 years versus Tokyo, offering first-mover expansion for compact furniture formats adapted to aging rural stock.
- AI-Assisted Custom Joinery:Convergence of parametric design software and robotic sanding enables mass-customization of traditional kumiki joints at mid-market price points.
- Direct-to-Renovator Digital Channels:Municipal renovation subsidy portals in Saitama and Chiba now integrate furniture specification tools, creating bypass opportunities around suburban retail gatekeepers.
Industry Challenges
- Certified Kumiki Craft Labor Scarcity:Master joiners with Ministry of Economy, Trade and Industry artisan credentials average 58 years of age, with apprenticeship pipelines failing to replace retirement-driven attrition.
- Legacy ERP Integration Friction:Mid-scale fabricators struggle to synchronize CNC production data with Showa-era inventory systems, delaying real-time yield optimization and defect tracing.
- Cross-Prefecture Fire-Safety Variance:Osaka and Yokohama maintain divergent flame-resistance thresholds for upholstered composites, forcing SKU fragmentation and testing cost duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Home Furniture Market |
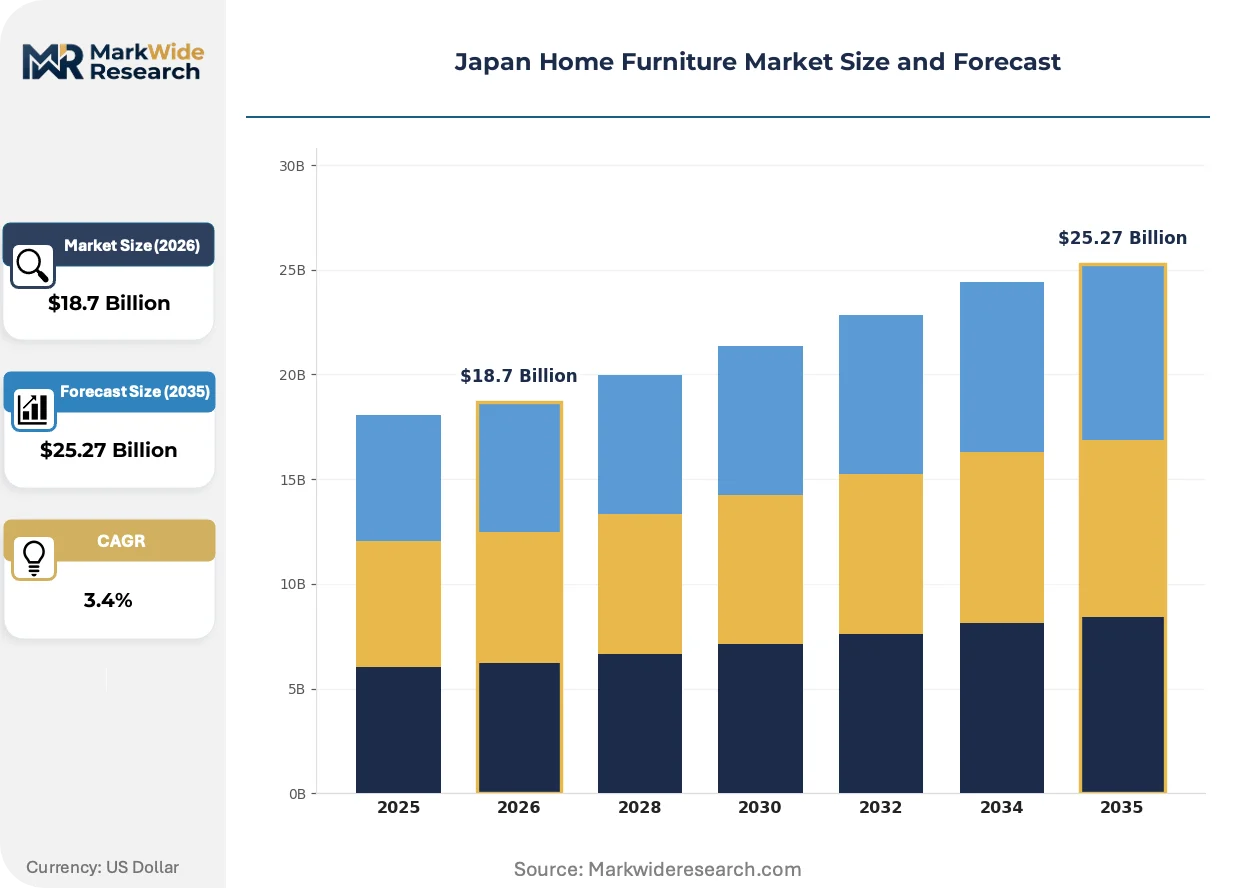
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $25.27 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Furniture Type: Sofas, Beds, Dining Tables, Chairs Material: Wood, Metal, Upholstery, Plastic Style: Modern, Traditional, Scandinavian, Minimalist Distribution Channel: Online, Specialty Stores, Retail Chains, Showrooms |
| Companies Covered | Okamura Corporation, Itoki Corporation, Nitori Holdings Co., Ltd., Maruni Wood Industry Inc., Karimoku Furniture Inc., Ryohin Keikaku Co., Ltd., Kokuyo Co., Ltd., Hida Sangyo Co., Ltd., IKEA Japan K.K., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Home Furniture Market Shifts & Advancements
Digital fabrication and regulatory disclosure requirements are splitting the competitive landscape between precision-automated mid-tier producers and heritage craft houses, while demand-side preferences rotate toward lighter visual profiles and service-integrated purchase models.
Parametric CNC routing is bifurcating the market for storage-integrated seating. Younger buyers in Tokyo's 25-35 square meter apartments specify algorithmically optimized wall-bed systems that compress 40% more function per tatami module. This technology is bifurcating competitive positioning: automated fabricators capture volume in standardized configurations, while manual specialists retreat to bespoke heritage commissions.
METI's 2023 indoor air quality disclosure amendments now require retail chains to publish formaldehyde emission grades at point-of-sale. Manufacturers must reconfigure finishing lines to water-based UV coatings or risk exclusion from JREIT-linked housing procurement. Prefabricated bathroom and kitchen suppliers extending into adjacent furniture categories face the steepest compliance cost escalation.
Rental management platforms now bundle furniture lifecycle services into tenant onboarding packages. Institutional landlords in central Osaka specify 36-month replacement guarantees for upholstered pieces, displacing traditional retail ownership models. This service integration concentrates demand among three national lessors who can underwrite residual value risk at portfolio scale.
Japan Home Furniture Market Segmentation
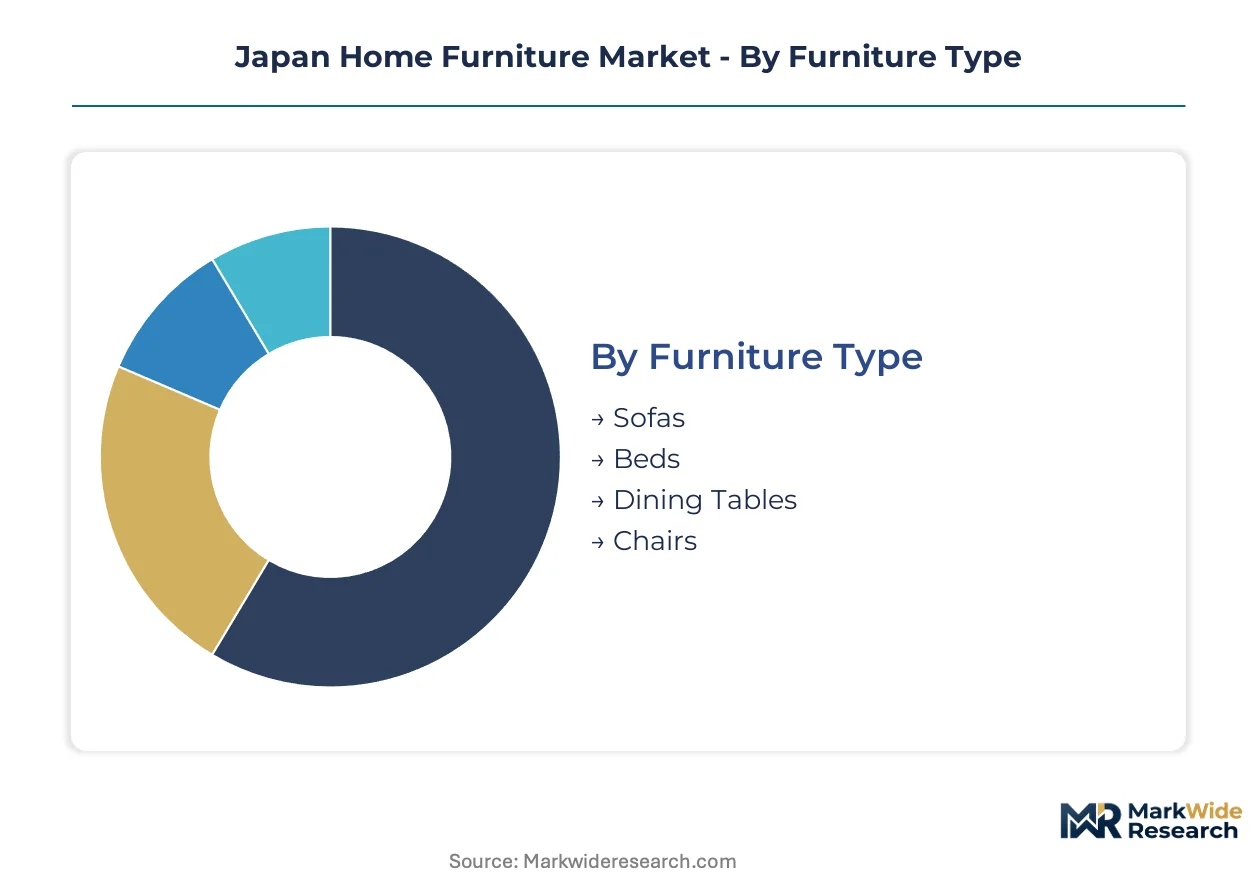
Segmentation in the Japan home furniture market reveals how substitution pressures and regulatory constraints reshape competitive boundaries. Understanding these divisions exposes where automated fabricators displace traditional suppliers and where JIS certification creates defensible moats.
Furniture Type:
Metal frame substitution and multifunctional design imperatives exert uneven pressure across living-space categories, compressing margins in commoditized segments while protecting premium niches.
- Sofas:Upholstered seating systems with high-density foam cores and fabric or leather coverings, dimensioned for 910mm tatami-grid compatibility. Demand concentrates in Tokyo's micro-apartments where wall-hugging profiles maximize floor utility, though rental-platform lifecycle services displace traditional retail ownership.
- Beds:Platform and storage-integrated sleeping surfaces engineered for seismic anchoring compliance, spanning solid timber frames to steel-reinforced hybrids. Osaka's institutional landlords specify 36-month replacement guarantees, pulling procurement toward national lessors with residual-value underwriting capacity.
- Dining Tables:Extendable and foldable configurations dominate Kanto corridor renovations, with parametric CNC routing enabling compact storage-integrated designs.
- Chairs:Stacking and nesting variants gain share in Chiba and Saitama municipal subsidy programs, displacing fixed seating in aging rural stock renovations.
Beds anchor the volume base while sofas gain share at the steepest rate.
Material:
Cost-tier stratification separates certified domestic suppliers from import-dependent fabricators, with METI disclosure rules amplifying differentiation at the premium end.
- Wood:Solid timber and engineered board constructions, spanning hinoki and sugi domestic species to imported oak and walnut. Aichi Prefecture's captive lumber sourcing and Hida's artisan-certified production anchor premium positioning, though weather-driven harvest disruptions concentrate supply risk.
- Metal:Steel shelving and aluminum bed frames specified for pet-resistant durability in investor-class housing. Yokohama and Osaka landlords increasingly mandate metal for rental inventory, displacing wood value share in multi-unit properties.
- Upholstery:Fabric and leather composites face divergent flame-resistance thresholds across prefectures, forcing SKU fragmentation and testing cost duplication.
- Plastic:Polypropylene and polycarbonate variants penetrate budget renovation segments in Kyushu, where shorter replacement cycles tolerate lower durability.
Wood retains the dominant value position while metal climbs the fastest among rental-oriented specifications.
Style:
Customer-type divergence splits demand between heritage-preserving rural renovations and space-optimizing urban conversions.
- Modern:Clean-lined configurations with concealed hardware and modular adaptability, optimized for seismic anchoring integration. Tokyo's 25-35 square meter apartments standardize on algorithmically optimized wall-bed systems that compress multiple functions per tatami module.
- Minimalist:Visual lightness through reduced material mass and neutral palettes, gaining share among younger buyers seeking psychological spaciousness in constrained floor areas.
- Scandinavian:Pale wood tones and ergonomic simplicity resonate in Saitama and Chiba suburban developments, bridging traditional Japanese spatial sensibilities with Nordic functionalism.
- Traditional:Kumiki joinery and tatami-compatible proportions, preserved through METI artisan credentials but threatened by master joiner demographic collapse averaging 58 years of age.
Modern styling anchors the volume base while minimalist designs expand most quickly among urban millennials.
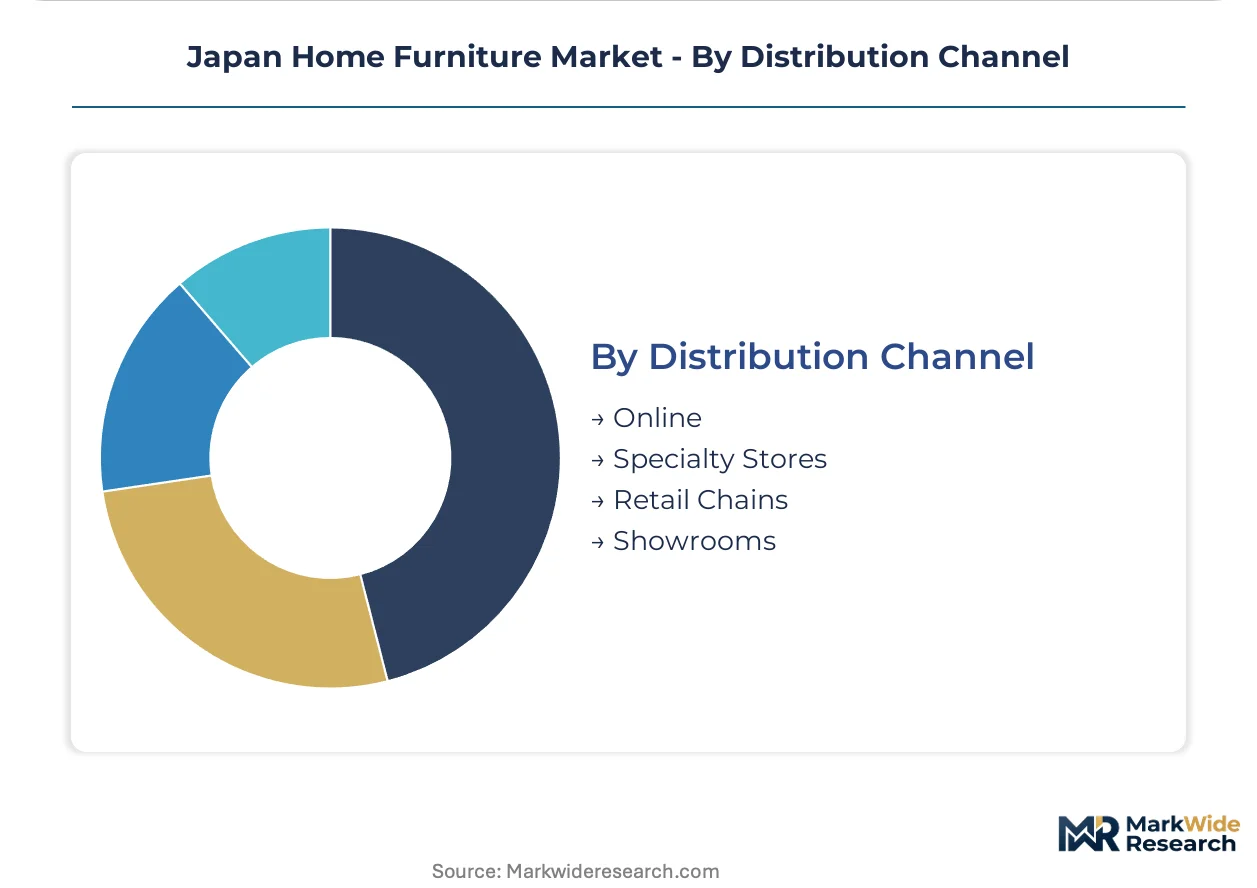
Distribution Channel:
Geographic penetration gaps between Kanto corridor density and underdeveloped prefectures reshape channel economics, with digital integration creating bypass opportunities around established retail gatekeepers.
- Retail Chains:Vertically controlled suburban networks dominate price-sensitive segments through centralized procurement and standardized JIS-certified SKUs. Nitori Holdings leverages this channel to capture volume in Chiba and Saitama renovation cycles.
- Online:Direct-to-renovator platforms integrated with municipal subsidy portals in Saitama and Chiba enable specification tools that circumvent traditional retail markups.
- Specialty Stores:Curated presentations of artisan-certified and heritage joinery, concentrated in Aichi and Hida regions where captive lumber sourcing supports premium positioning.
- Showrooms:Experiential display environments for mass-customization services, enabling parametric design visualization before CNC production commitment.
Retail chains anchor the volume base while online channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's home furniture trade balance tilts toward domestic fabrication, with import penetration concentrated in budget-oriented metal frames and mass-market upholstery while precision wood exports from Aichi and Gifu prefectures sustain a modest surplus with Asian markets.
Kanto/Tokyo
Micro-apartment densification and renovation subsidy programs drive demand for wall-bed systems and tatami-grid storage. METI's circular-economy disclosure rules force retail chains to publish formaldehyde emission grades at point-of-sale. Chiba and Saitama municipal portals now integrate furniture specification tools that bypass traditional suburban retail gatekeepers.
Kansai/Osaka
Institutional landlords specify 36-month replacement guarantees for upholstered pieces, concentrating procurement among national lessors with residual-value underwriting capacity. Revised municipal building codes mandate seismic anchoring for load-rated storage systems. The Osaka Bay manufacturing cluster hosts steel-reinforced bed frame fabricators serving investor-class housing.
Chubu/Nagoya
Captive lumber sourcing in Aichi Prefecture anchors premium solid timber production, though weather-driven harvest disruptions concentrate supply risk. JIS certification timelines for formaldehyde-emission testing compress margin recovery for seasonal collections. Artisan-certified production facilities in the region preserve kumiki joinery techniques adapted for contemporary interiors.
Kyushu
Renovation cycle gaps of 4-7 years versus Tokyo create first-mover expansion opportunities for compact furniture formats. Shorter replacement cycles in aging rural stock tolerate lower-durability polypropylene variants. Prefecture-level fire-safety ordinances maintain divergent flame-resistance thresholds from Kanto, forcing SKU fragmentation.
Tohoku
Post-disaster reconstruction programs and municipal housing stock renewal generate episodic demand spikes for JIS-certified structural furniture. Demographic contraction limits sustained volume growth outside Sendai metropolitan core. Regional fabricators struggle to synchronize CNC production data with legacy inventory systems.
Japan Home Furniture Market Competitive Landscape
Concentration sits with vertically integrated retail chains and captive-sourcing wood specialists who control procurement and finishing lines end-to-end. Automated CNC joinery has redistributed advantage toward mid-scale producers achieving artisan-grade tolerances without captive craft labor. Two strategic archetypes dominate: mass-market fabricators leveraging centralized supply chains for price-sensitive suburban segments, and heritage houses defending premium positioning through artisan credentials and traditional joinery specialization. Competitive moves center on municipal subsidy portal integration and parametric design service deployment.
Among vertically controlled retailers, Nitori Holdings Co., Ltd. exemplifies the mass-market archetype through suburban chain dominance. Karimoku Furniture Inc. and Hida Sangyo Co., Ltd. occupy positions within the precision wood specialist tier, the former through Aichi-based captive lumber sourcing and the latter via deep specialization in traditional joinery adapted for contemporary applications. These three anchors illustrate how automated fabrication and heritage craft credentials now split competitive positioning across price tiers.
| Leading Market Players |
|---|
| Okamura Corporation |
| Itoki Corporation |
| Nitori Holdings Co., Ltd. |
| Maruni Wood Industry Inc. |
| Karimoku Furniture Inc. |
| Ryohin Keikaku Co., Ltd. |
| Kokuyo Co., Ltd. |
| Hida Sangyo Co., Ltd. |
| IKEA Japan K.K. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Aichi Prefecture sawmills and Tokyo retail chains lock in both hinoki supply access and price visibility across 24-36 month windows, insulating fabricators from yen-denominated import volatility while compressing margin recovery timelines for seasonal collections.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on JIS certification grade and volume scale, with artisan-certified kumiki pieces commanding substantial premiums over CNC-fabricated alternatives. Cost compression in the metal frame tier is intensifying because Yokohama and Osaka landlords increasingly mandate steel-reinforced specifications for rental inventory. Municipal renovation contractors show highest price sensitivity, while heritage preservation architects demonstrate lowest sensitivity to certification-linked premiums.
Supply Chain Analysis
Weather-driven harvest disruptions in Aichi and Gifu prefectures concentrate supply risk for solid timber inputs. Domestic hinoki and sugi sourcing draws from captive forestry partnerships, while engineered board production feeds from imported oak and walnut shipments. Single-source vulnerability sits with master joiner demographics, where METI artisan credential holders average 58 years of age with inadequate apprenticeship pipelines. Distribution runs through vertically controlled suburban retail chains and direct-to-renovator digital portals integrated with municipal subsidy systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture lifecycle service bundling now expands faster than hardware sales, as Osaka institutional landlords specify 36-month replacement guarantees and residual-value underwriting becomes a separable revenue layer.
For Market Incumbents: Compound defensive positioning through captive lumber sourcing deepening in Aichi Prefecture and parametric CNC service deployment against kumiki craft labor scarcity. METI circular-economy disclosure rules threaten import-dependent fabricators with compliance cost escalation. Certification investment in water-based UV finishing lines secures JREIT-linked housing procurement access. For New Entrants and Emerging Players: Anchor in Kyushu and Tohoku renovation cycle gaps, where 4-7 year lags versus Tokyo create first-mover expansion opportunities for compact furniture formats adapted to aging rural stock. Municipal subsidy portal integration in Saitama and Chiba offers a direct-to-renovator go-to-market angle that circumvents established suburban retail gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among national lessors with residual-value underwriting capacity at portfolio scale. Long-term viability across the projection horizon favors automated mid-scale fabricators achieving artisan-grade tolerances without captive craft labor. Watch for AI-assisted custom joinery adoption rates as the inflection signal distinguishing scalable precision producers from heritage craft houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Forestry | Aichi Prefecture hinoki sourcing secures supply continuity against weather-driven harvest disruptions. |
| Parametric CNC Service Deployment | Algorithmic wall-bed customization captures Tokyo micro-apartment demand at mid-market price points. |
| Municipal Subsidy Portal Integration | Direct-to-renovator digital channels in Saitama and Chiba bypass suburban retail markups. |
| JIS Certification Investment | Water-based UV finishing lines secure access to JREIT-linked housing procurement pools. |
| Furniture Lifecycle Service Bundling | 36-month replacement guarantees align with Osaka institutional landlord procurement specifications. |
Research Methodology
The analysis maps solid timber fabrication, engineered board production, metal frame assembly, and upholstery finishing, each validated through production directors at Aichi and Gifu fabricators, procurement leads at Tokyo retail chains, municipal housing subsidy administrators in Saitama and Chiba, and METI regulatory affairs specialists. Secondary validation draws from JIS standard filings, METI circular-economy disclosure registries, customs trade records for lumber imports, and municipal renovation program databases. Bottom-up unit economics triangulate against top-down market sizing across furniture type, material, style, and distribution channel dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models demand by furniture type, material grade, stylistic category, and regional prefecture cluster, with CAGRs derived from historical trajectory analysis and structural driver elasticity. Key inputs include tatami-module spatial planning adoption rates, seismic anchoring mandate implementation timelines, and rental-platform lifecycle service penetration curves.
Decision-makers should treat outputs as directional under assumptions of sustained urban densification and METI disclosure rule enforcement; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as master joiner retirement rates and cross-prefecture fire-safety harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Massive Wood Slabs Market
Furniture
Ergonomic Chair Market
Furniture
Global Folding Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Bar Stools Market
Furniture
Bean Bag Chairs Market
Furniture
North America School Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Kids and Nursery Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Laminated Door Market
Furniture
UK Multifunctional Furniture Market
Furniture
Europe Furniture Market