
 Metal Furniture Market | 2026-2036
Metal Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Furniture Market Intelligence
Asset-light leasing models for commercial interiors is reconfiguring competitive entry barriers, allowing mid-scale operators to bid against capital-heavy incumbents. Steelcase Inc. leverages its North American manufacturing footprint to sustain institutional contract flow. Herman Miller Inc. anchors its position through design-forward ergonomic seating systems. KOKUYO Co. Ltd. dominates Japanese corporate fit-out channels with integrated workspace planning.
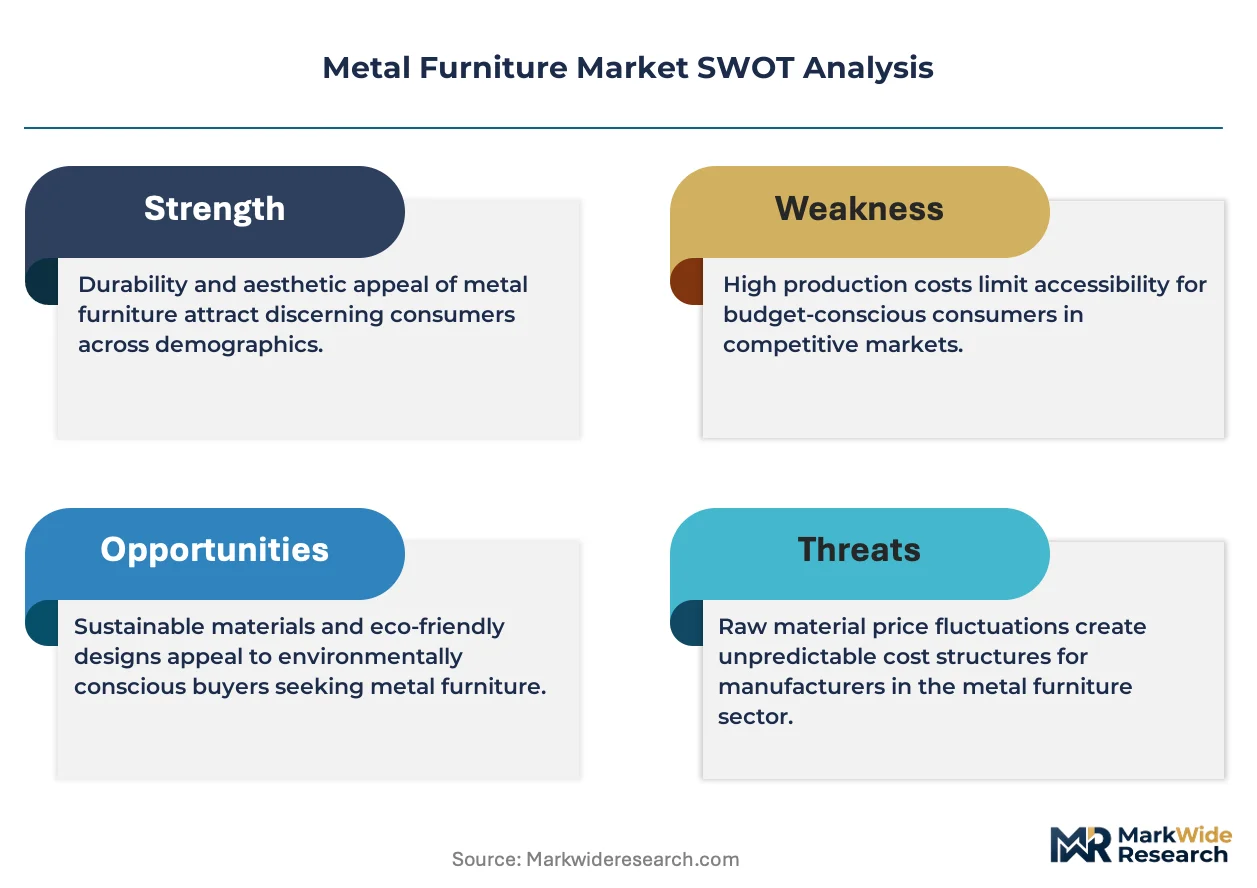
Metal furniture encompasses seating, storage, and surface products fabricated from steel, aluminum, or iron alloys, typically welded or stamped and finished through powder coating or anodizing to achieve durability ratings exceeding 50,000 cycle tests for commercial use. The product serves high-traffic environments requiring fire resistance, load-bearing stability, and standardized dimensions for facility management. Chairs and tables occupy the largest revenue pool across the residential and commercial end-user segments, while cabinets and racks capture expanding share in educational and hospitality settings where secure storage and space optimization drive specification. Modern and industrial design styles are pulling ahead of vintage and minimalist alternatives as urban commercial renovations favor exposed structural aesthetics.
EPA emission standards for surface coating operations and REACH substance restrictions on hexavalent chromium directly shape supplier compliance costs and finishing technology choices across the United States and European Union. China's GB standards for indoor air quality and metal content disclosure further condition export eligibility for manufacturers serving multinational procurement chains. BIS certification requirements in India add another compliance layer for seating and storage products entering institutional tenders. Stakeholders must weigh regulatory divergence against regional manufacturing scale when locating finishing and final assembly capacity.
Market Dynamics
Modular workstation leasing is compressing capital deployment cycles for commercial fit-out buyers, forcing manufacturers to reconfigure revenue models around service subscriptions rather than unit sales.
Growth Catalysts
- REACH substance restrictions:European hexavalent chromium bans are accelerating powder-coating line upgrades across export-oriented finishing facilities.
- Co-working space expansion:Flexible office operators in India and Vietnam are procuring reconfigurable metal workstations at volumes exceeding traditional corporate contracts.
- Aluminum extrusion advances:High-strength alloy stamping is enabling thinner-walled storage products without load-bearing penalties.
Market Restraints
- Steel price volatility:Hot-rolled coil fluctuations in China directly compress margin buffers for mid-scale fabricators.
- Concentrated powder supply:Three specialty chemical producers in Germany control global epoxy-polyester hybrid formulations.
- Substitution pressure:Engineered wood laminates with metal-look finishes are capturing budget-tier hospitality seating specifications.
Strategic Opportunities
- Vietnamese manufacturing zones:Industrial park incentives in Binh Duong province are attracting welded-frame assembly capacity from Guangdong suppliers.
- Circular design mandates:EU Green Deal product passport requirements favor disassemblable metal furniture with documented recyclability pathways.
- Direct-to-facility distribution:E-procurement platforms are bypassing traditional dealer networks for institutional bulk orders.
Industry Challenges
- Welding automation skills gap:Robotic seam programming expertise remains scarce across Indian and Vietnamese production hubs.
- BIS certification timelines:Seating safety testing queues in Mumbai laboratories extend tender participation windows by 90-120 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Furniture Market |
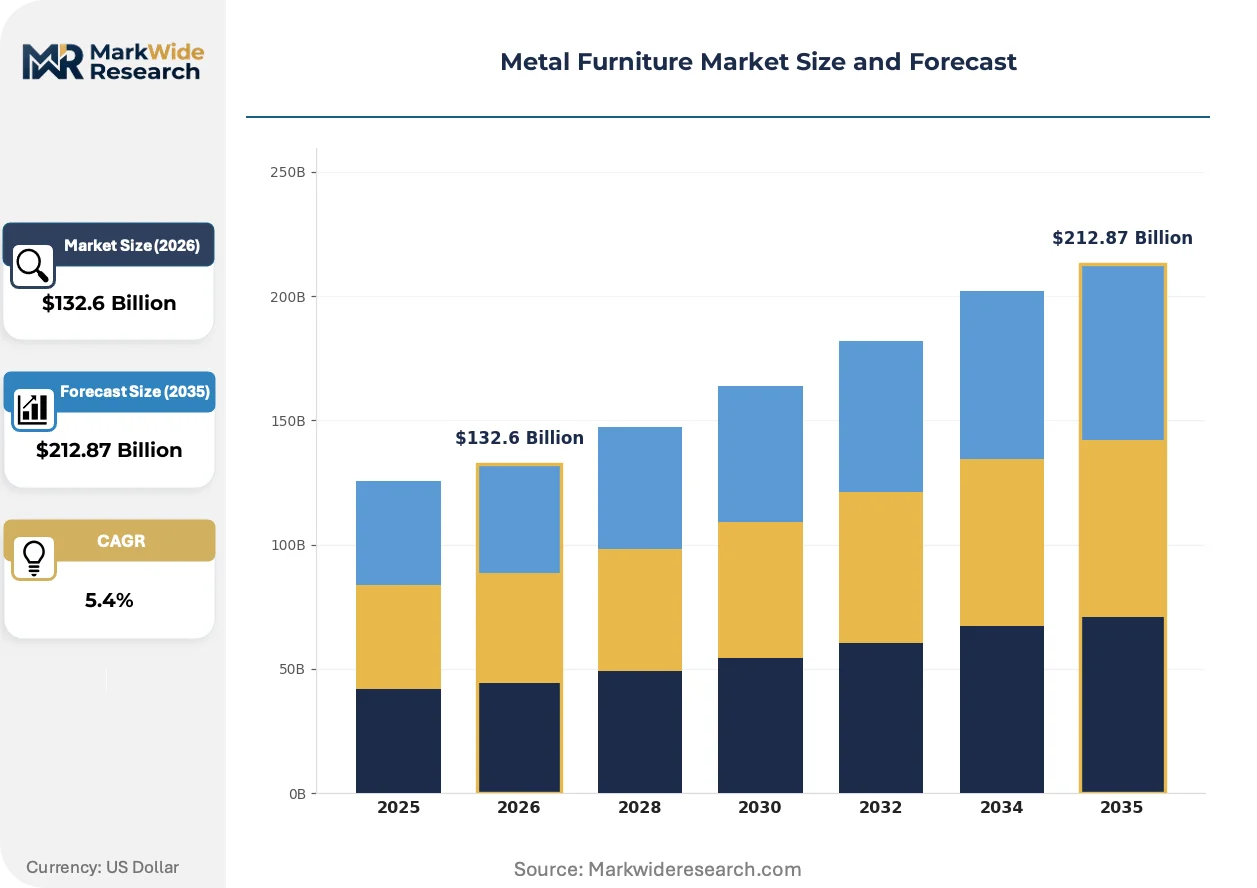
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $212.87 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Cabinets, Racks End User: Residential, Commercial, Educational, Hospitality Design Style: Modern, Vintage, Industrial, Minimalist Finishing Type: Powder Coated, Painted, Anodized, Polished |
| Companies Covered | Inter IKEA Systems B.V., Teknion Corporation, Steelcase Inc., Zinus Inc., Allsteel Inc., Herman Miller Inc., KOKUYO Co. Ltd., Meco Corporation, HNI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Furniture Market Strategic Shifts & Innovations
Finishing technology convergence and procurement platform digitization are compressing specification-to-delivery timelines while fragmenting traditional channel control.
Laser-cut tube bending combined with automated TIG welding is rendering obsolete stamped-and-welded frame construction for mid-volume commercial seating. Hospitality and healthcare buyers in the United States are specifying these structures for 500-plus unit orders. The shift is rendering obsolete legacy fixture investments at second-tier metalworking shops.
China's GB standards for indoor air quality disclosure are forcing export manufacturers to reformulate powder-coat curing processes and document volatile organic compound emissions. Finishing facilities in Zhejiang and Guangdong provinces are retrofitting thermal oxidizers to maintain multinational procurement eligibility. Educational furniture bound for European markets faces the tightest compliance verification.
Asset-light interior service contracts are displacing permanent furniture ownership among corporate real estate managers. WeWork-style operators in Singapore and Sydney are contracting workstation refresh cycles under 36-month terms. Facility management departments are unbundling furniture from landlord provision responsibilities.
Metal Furniture Market Segmentation
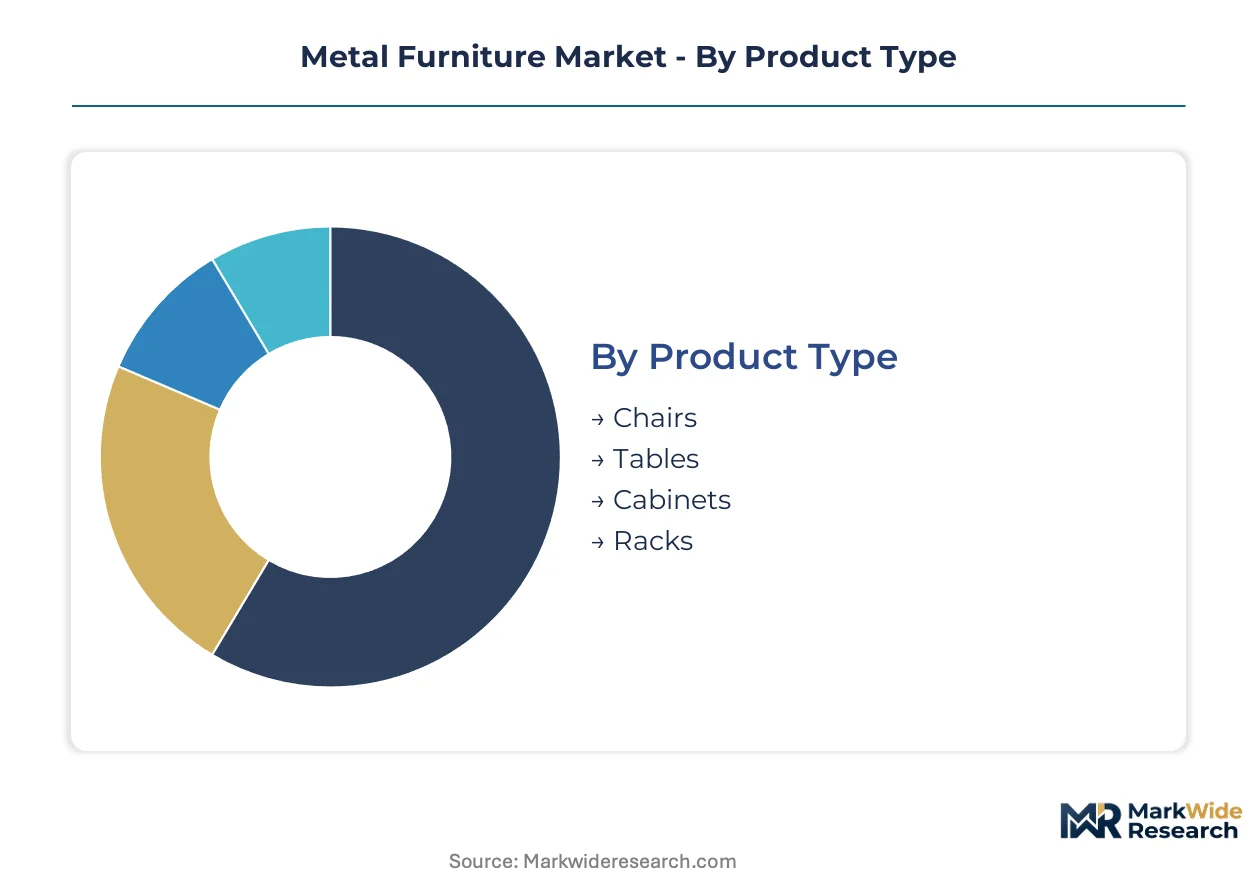
Metal furniture segmentation reveals how specification requirements diverge across procurement contexts. Product durability ratings, aesthetic mandates, and compliance obligations reshape competitive positioning within each slice.
Product Type:
Volume concentration across seating, storage, and surface categories determines where fabrication capacity achieves scale economies.
- Chairs:Welded steel or aluminum frames with ergonomic shell construction dominate commercial and educational tenders. Demand concentrates in co-working fit-outs across India and Vietnam where 500-plus unit orders specify powder-coated finishes for high-cycle durability.
- Tables:Stamped leg assemblies with laminate or solid surface tops serve modular workstation configurations. Corporate real estate managers in Singapore specify reconfigurable metal tables under 36-month refresh contracts, compressing capital deployment cycles.
- Cabinets:Lockable storage units with reinforced shelving address secure document and equipment needs.
- Racks:Open-frame shelving systems optimize vertical space in hospitality back-of-house and retail inventory rooms.
Chairs command the established base. The steepest expansion runs through tables.
End User:
Procurement authority structures diverge sharply between owner-occupiers, institutional buyers, and flexible-space operators.
- Residential:Direct consumer purchases through retail channels emphasize design aesthetics and flat-pack delivery. Urban apartment renovations in Japan favor exposed structural metal frames matching industrial interior themes.
- Commercial:Facility management departments and asset-light leasing companies drive bulk workstation procurement. WeWork-style operators in Sydney contract furniture-as-a-service, unbundling ownership from landlord provision.
- Educational:Institutional tenders require BIS certification in India, extending testing queues by 90-120 days.
- Hospitality:Hotel procurement chains specify fire-rated metal seating for high-traffic lobby and dining areas.
Commercial buyers command the established base. The steepest expansion runs through hospitality.
Design Style:
Aesthetic preference cycles reshape finishing technology investments and fabrication methods.
- Modern:Clean lines with minimal ornamentation specify laser-cut tube bending and automated TIG welding. US healthcare buyers source these structures for 500-plus unit orders, displacing stamped-and-welded legacy construction.
- Industrial:Exposed welds, raw steel, and visible fasteners dominate urban commercial renovations. Co-working spaces across Germany and the Netherlands favor this aesthetic for brand differentiation.
- Vintage:Distressed finishes and ornamental detailing require specialized patina processes.
- Minimalist:Ultra-thin profiles and hidden hardware demand high-strength aluminum extrusion advances.
Industrial commands the established base. The steepest expansion runs through modern.
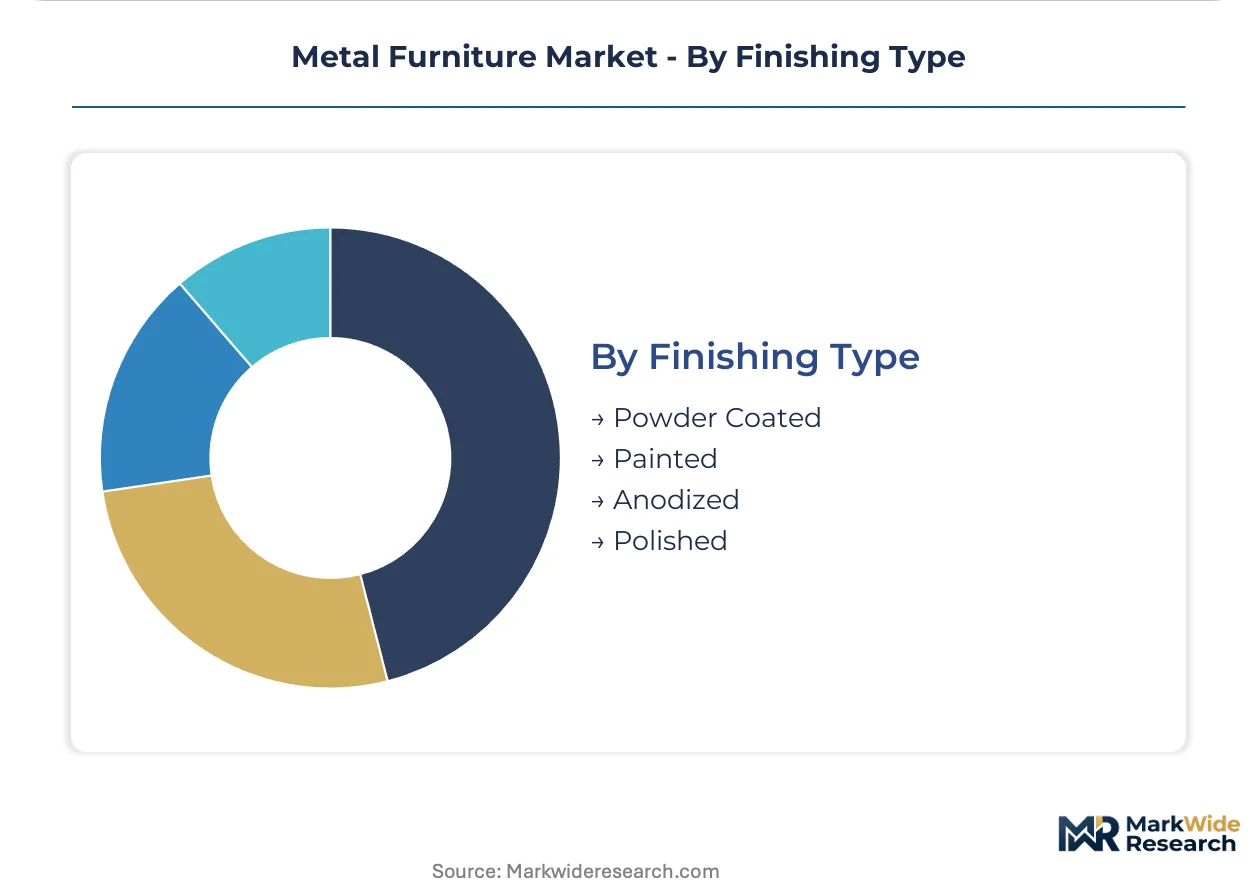
Finishing Type:
Regulatory compliance costs and emission disclosure requirements fragment supplier capabilities across coating technologies.
- Powder Coated:Electrostatically applied thermoset polymer finishes achieve 50,000-plus cycle durability for commercial use. REACH hexavalent chromium bans across Europe accelerate line upgrades at export-oriented facilities in Zhejiang and Guangdong.
- Anodized:Electrochemical oxide layer formation on aluminum creates corrosion-resistant, dye-absorptive surfaces. Japanese corporate fit-outs specify anodized finishes for premium workstation programs.
- Painted:Liquid coating systems serve budget-tier specifications and color-matching requirements.
- Polished:Mechanical buffing to mirror finish addresses hospitality and decorative residential applications.
Powder coated commands the established base. The steepest expansion runs through anodized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial co-working operators and institutional facility managers concentrate procurement authority across distinct national markets, each shaped by divergent compliance regimes and manufacturing ecosystems.
United States
Healthcare systems and hospitality chains drive specification for laser-cut tube seating structures in 500-plus unit orders. EPA emission standards for surface coating operations mandate thermal oxidizer retrofits at finishing facilities serving federal contracts. Grand Rapids, Michigan anchors welded-frame production clusters supplying institutional buyers.
Germany
Co-working space operators across Berlin and Hamburg favor exposed structural industrial aesthetics for brand differentiation. REACH substance restrictions on hexavalent chromium accelerate powder-coating line upgrades at export-oriented fabricators. The Ruhr industrial corridor concentrates robotic welding capacity for commercial workstation programs.
China
Multinational procurement chains source reconfigurable metal workstations from Guangdong and Zhejiang finishing facilities. GB standards for indoor air quality disclosure force reformulation of powder-coat curing processes and VOC emission documentation. Binh Duong province in neighboring Vietnam draws welded-frame assembly capacity from Guangdong suppliers relocating to escape rising labor costs.
India
Institutional tenders for educational and government seating require BIS certification, extending testing queues at Mumbai laboratories by 90-120 days. The PLI scheme for furniture manufacturing attracts welded-frame investment to Gujarat and Tamil Nadu industrial corridors. Pune and Chennai clusters specialize in powder-coated commercial storage for domestic fit-out channels.
Japan
Corporate real estate managers in Tokyo and Osaka specify anodized aluminum finishes for premium workstation programs. METI industrial standards condition procurement eligibility for domestic facility management contracts. The Kanto region around Tokyo concentrates integrated workspace planning capabilities serving keiretsu-affiliated fit-out channels.
Metal Furniture Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base splits between capital-heavy incumbents sustaining institutional contract flow and mid-scale operators exploiting asset-light leasing models. Three archetypes dominate: North American manufacturing-anchored full-line suppliers, Asia-Pacific integrated workspace planners, and European design-forward ergonomic specialists. Competitive moves concentrate on geographic capacity relocation and finishing technology compliance upgrades.
Among North American-based fabricators, Steelcase Inc., Herman Miller Inc., and HNI Corporation exemplify distinct strategic positions within the commercial contract channel. Steelcase Inc. represents the manufacturing-anchored archetype with institutional contract flow. Herman Miller Inc. occupies a position emphasizing design-forward ergonomic seating systems. HNI Corporation sits within the diversified portfolio segment serving multiple end-use verticals. Japanese integrated workspace planning is anchored by KOKUYO Co. Ltd., which exemplifies the Asia-Pacific channel control model through corporate fit-out dominance.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Teknion Corporation |
| Steelcase Inc. |
| Zinus Inc. |
| Allsteel Inc. |
| Herman Miller Inc. |
| KOKUYO Co. Ltd. |
| Meco Corporation |
| HNI Corporation |
| Others |
Cost & Logistics Intelligence
Guangdong province's welded-frame assembly clusters command downstream pricing power through captive access to powder-coating chemical supply chains concentrated in Zhejiang. Hot-rolled coil indexation in procurement contracts ties finished goods pricing to Shanghai Futures Exchange movements, compressing margin buffers for fabricators lacking backward integration into steel service centers.
Pricing Analysis
Cost-plus contracts with Shanghai Futures Exchange indexation dominate institutional procurement, with powder-grade tier and REACH compliance certification driving price spreads between export-qualified and domestic-only suppliers. Pricing pressure stems from engineered wood laminate substitutes capturing budget-tier hospitality seating specifications. Asset-light co-working operators exhibit highest price sensitivity through 36-month refresh contracting, while healthcare systems tolerate premium positioning for laser-cut tube durability ratings.
Supply Chain Analysis
Export-control scrutiny on robotic welding equipment from Germany and Japan constrains capacity expansion timelines across Vietnamese and Indian assembly zones. Supply concentrates in China, Vietnam, and India, with epoxy-polyester hybrid formulations drawing from three German specialty chemical producers. Single-source vulnerability runs through powder-coating chemical supply. Distribution runs through e-procurement platforms bypassing traditional dealer networks for institutional bulk orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal furniture sits in early-cycle expansion as co-working space proliferation across India and Vietnam accelerates modular workstation procurement beyond traditional corporate contract volumes.
For Market Incumbents: Insulate institutional contract flow by deepening backward integration into steel service centers near Grand Rapids and Ruhr corridor production clusters. Accelerate powder-coating line upgrades ahead of REACH hexavalent chromium enforcement timelines. Counter engineered wood substitution threats through design-forward ergonomic positioning in healthcare specification channels.
For New Entrants and Emerging Players: Establish a beachhead in hospitality back-of-house rack systems where fire-rated metal specifications resist laminate substitution. Target Binh Duong province manufacturing incentives for welded-frame assembly capacity serving export markets. Leverage direct-to-facility e-procurement platform relationships to bypass entrenched dealer networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming furniture divisions lacking REACH-compliant finishing infrastructure. Five-to-ten year viability hinges on regulatory compliance technology rather than pure scale economics. Monitor BIS certification queue lengths at Mumbai laboratories as inflection signal for Indian institutional tender participation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Finishing Upgrade | Powder-coating line retrofits at Zhejiang and Guangdong facilities preserve multinational procurement eligibility under ECHA substance restrictions. |
| Vietnamese Manufacturing Relocation | Binh Duong industrial park incentives attract welded-frame assembly capacity escaping Guangdong labor cost inflation. |
| Robotic Welding Automation | Automated TIG programming addresses skills scarcity across Indian and Vietnamese production hubs for mid-volume commercial orders. |
| Circular Design Certification | EU Green Deal product passport documentation of disassemblable metal pathways secures premium positioning in European institutional tenders. |
| Direct E-Procurement Platform Integration | Bypassing traditional dealer networks captures institutional bulk order flows from facility management departments unbundling furniture ownership. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with co-working space procurement directors, institutional facility managers, powder-coating chemical formulators, and robotic welding systems integrators. Secondary validation drew from EPA emission standard filings, ECHA REACH substance restriction updates, BIS certification queue records, and Shanghai Futures Exchange steel price data. Bottom-up fabrication capacity estimates triangulated against top-down end-use procurement surveys across the analysis window.
Calibration anchored volume projections to historical co-working space expansion rates and institutional tender award patterns across segmented end-use categories. Modeled dimensions spanned product type, design style, finishing technology, and regional regulatory cluster. CAGRs derived from fitted trend lines through documented procurement cycle data and capacity utilization rates at named production zones.
Sensitivities concentrate around steel price volatility, REACH enforcement timing, and co-working operator consolidation trajectories. Forecasts reflect documented assumptions on regulatory compliance cost pass-through rates and substitution elasticity between metal and engineered wood specifications. Material shifts in EU Green Deal product passport implementation schedules or BIS certification processing capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
China Furniture Market
Furniture
Salon Chairs Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Portering Chair Market
Furniture
Bar Stools Market
Furniture
GCC Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
North America Home Furniture Market
Furniture
India Home Furniture Market
Furniture
North America School Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Saudi Arabia Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
North America RTA Furniture Market