
 Freestanding Retractable Awnings Market | 2026-2036
Freestanding Retractable Awnings Market Size, Share, and Industry Trends Forecast 2026-2036
Freestanding Retractable Awnings Market Insights
REACH compliance is consolidating the cost-of-entry calculus for European fabric suppliers and frame manufacturers alike. MARKILUX GmbH + CO. KG leverages its German engineering heritage to dominate premium motorized installations across Central Europe. Sunesta sustains a defensible position in North American residential channels through extensive dealer networks. Mitjavila anchors Mediterranean commercial projects with specialized wind-resistant engineering.
Freestanding retractable awnings are self-supporting shade structures with cantilevered or post-supported frames, typically fabricated from powder-coated aluminum extrusions and solution-dyed acrylic fabrics rated for UV resistance and water repellency; they deploy via manual crank, electric motor, or solar-charged drive systems to modulate solar heat gain and extend usable outdoor floor area. Motorized units command the widest margin pools as hospitality operators prioritize remote-control integration and wind sensor automation, while solar-powered variants represent the fastest-growing product type amid off-grid recreational area expansion. Aluminum framing leads material selection for its strength-to-weight ratio, though PVC-coated fabric competes aggressively in budget-sensitive event space deployments.
EPA Energy Star guidelines and EU F-Gas Regulation jointly shape product efficiency benchmarks and refrigerant-adjacent thermal performance claims for integrated cooling accessories. OSHA fall-protection standards govern commercial installation labor costs across US states, while CE marking mandates structural load testing for European wind and snow zones. Stakeholders must monitor evolving building code harmonization between national fire-retardant fabric standards and emerging smart-city infrastructure integration requirements.
Market Dynamics
Motorized drive systems with wind-sensor automation are compressing replacement cycles and expanding specification requirements across hospitality procurement channels.
Growth Catalysts
- EU F-Gas Regulation:Thermal performance mandates for integrated cooling accessories are accelerating specification of high-efficiency fabric assemblies in Mediterranean commercial retrofits.
- Aluminum extrusion advances:Powder-coating durability improvements are extending warranty terms and reducing lifecycle cost calculations for German café operators.
- US hospitality expansion:OSHA fall-protection compliance costs are being absorbed by national restaurant chains prioritizing outdoor seating capacity additions under shade structures.
Market Restraints
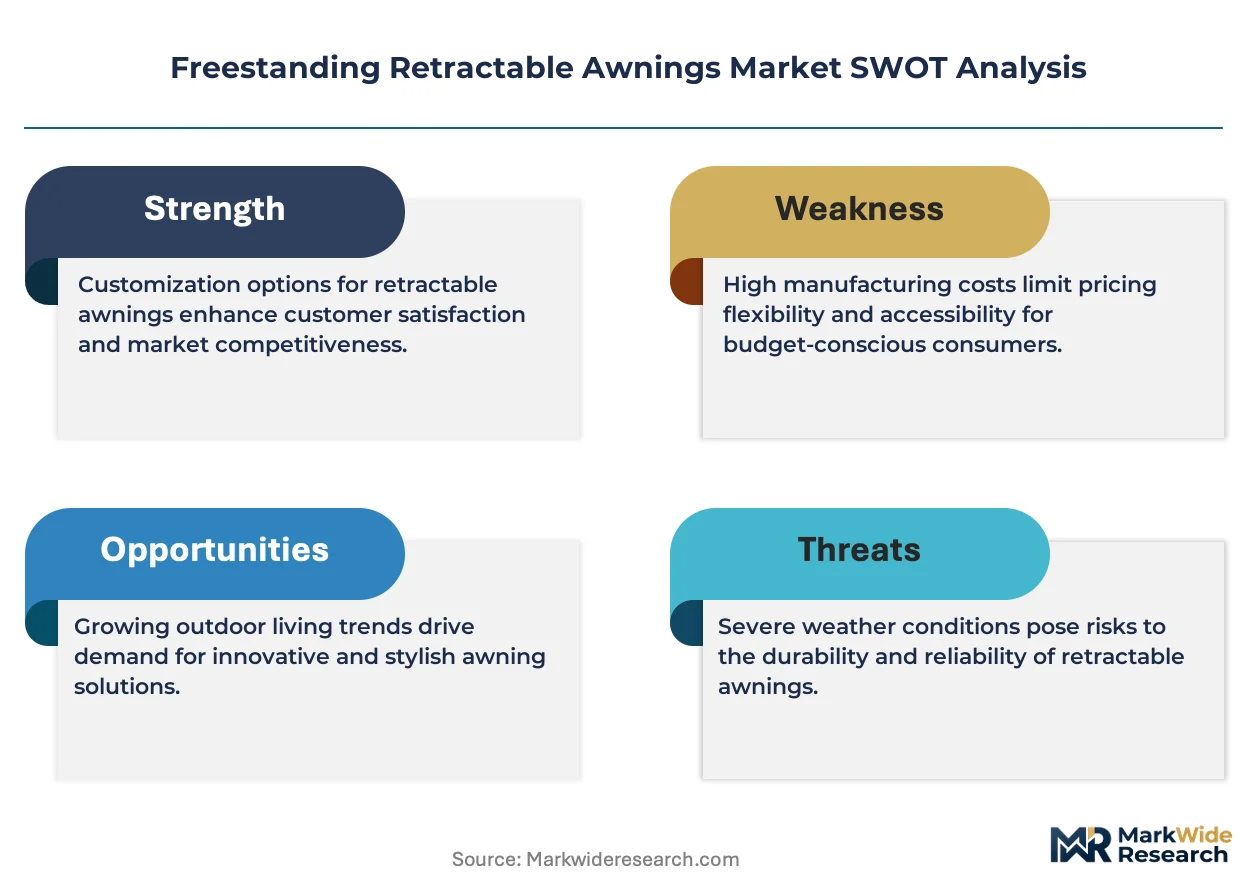
- Solution-dyed acrylic supply concentration:European fabric mills face REACH compliance cost escalation that compresses margin pools for mid-tier frame assemblers.
- Wind-load engineering limitations:Cantilevered designs above 6-meter projection require specialized structural certification that extends quoting timelines.
- PVC-coated polyester substitution:Budget event-space operators are trading UV resistance for upfront cost savings in temporary deployment scenarios.
Strategic Opportunities
- Solar-charged drive systems:Off-grid recreational area expansion in Australia and South Africa is creating specification pull for battery-integrated motorization.
- Smart-city infrastructure convergence:Municipal IoT integration requirements in Dubai and Singapore are opening specification channels for sensor-networked shade assets.
- CE marking harmonization:Unified structural load testing protocols are reducing country-specific certification burdens for Central European exporters.
Industry Challenges
- Installation technician certification:Commercial wind-load anchoring expertise remains concentrated among specialized rigging contractors, constraining deployment velocity.
- Fabric-to-frame integration complexity:Tensioning system compatibility across supplier ecosystems creates field-adjustment delays and warranty dispute exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freestanding Retractable Awnings Market |
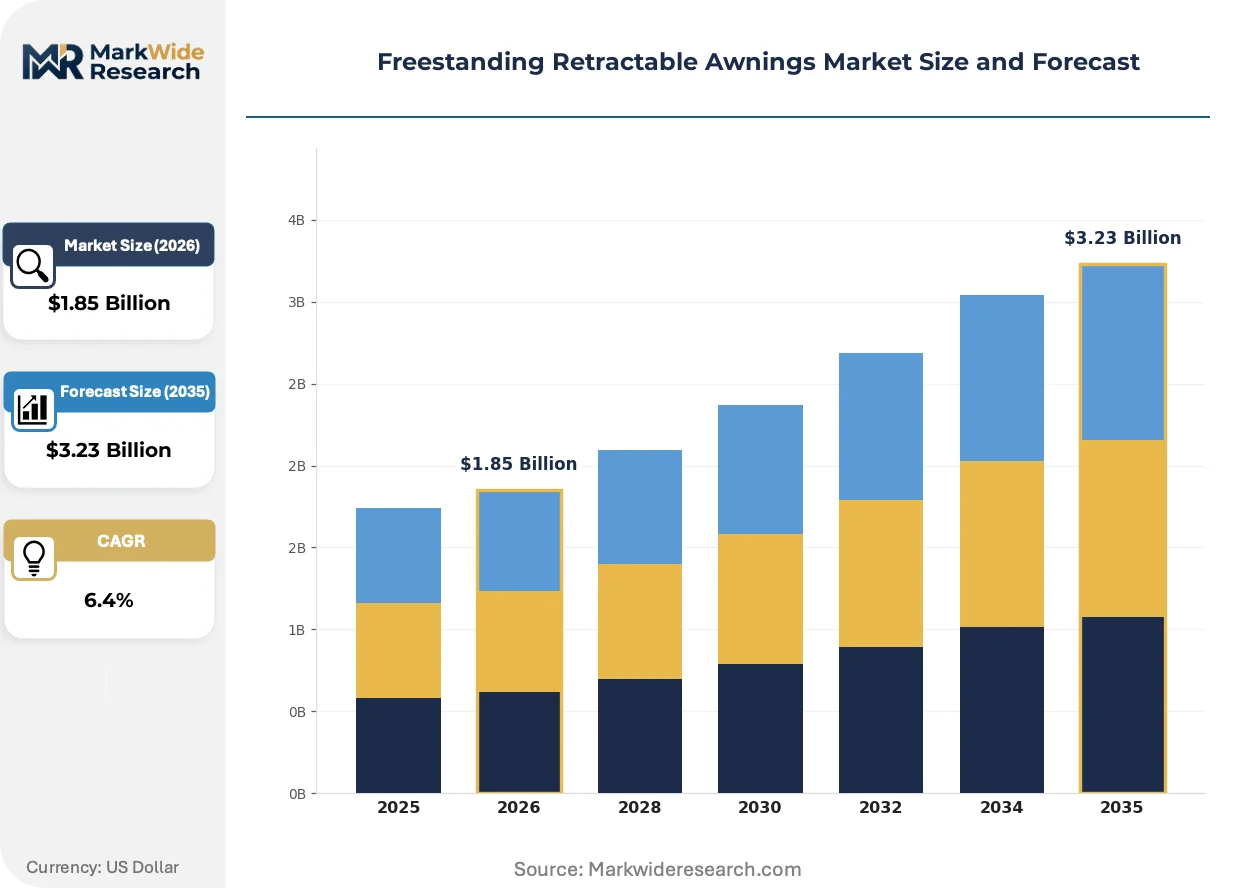
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized, Manual, Semi-Automatic, Solar-Powered Material: Aluminum, Steel, Polyester Fabric, Acrylic Fabric, PVC Coated Fabric Application: Residential Patios, Outdoor Cafés, Commercial Storefronts, Event Spaces, Recreational Areas End User: Private Homeowners, Hospitality Establishments, Retail Outlets, Sports Facilities |
| Companies Covered | Marygrove Awnings, Mitjavila, Advanced Design Awnings & Signs, Shades Awnings, NuImagePro & NuImage Awnings, Commercial Awnings Ltd, MARKILUX GmbH + CO. KG, Sunesta, Eide Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freestanding Retractable Awnings Market Trends and Innovations
Automation hardware and connected infrastructure are redefining performance benchmarks and procurement specifications across commercial and residential deployment channels.
Photovoltaic-integrated motorization is integrating solar cell arrays into cantilever arms to eliminate grid dependency for off-grid hospitality and recreational deployments. Safari lodge operators in Kenya and Botswana are specifying these units for remote poolside and dining installations. This architecture is integrating battery storage and Bluetooth control modules that compress installation scope and reduce ongoing electrical contracting requirements.
REACH substance restrictions are forcing reformulation of powder-coat chemistries and fabric dye processes across European supply chains. ECHA enforcement of SVHC candidate list expansions is triggering raw material qualification cycles that extend 18-24 months. German and Italian frame manufacturers are responding with captive coating facilities and vertically controlled fabric sourcing to maintain CE marking continuity.
Specification authority is migrating from general contractors to facilities management platforms with standardized asset tracking requirements. US university and corporate campus procurement teams are unbundling after-sales service from initial supply contracts and mandating API-accessible maintenance scheduling. This shift is most pronounced in California and Texas where portfolio-scale outdoor amenity standardization drives centralized purchasing authority.
Freestanding Retractable Awnings Market Segmentation
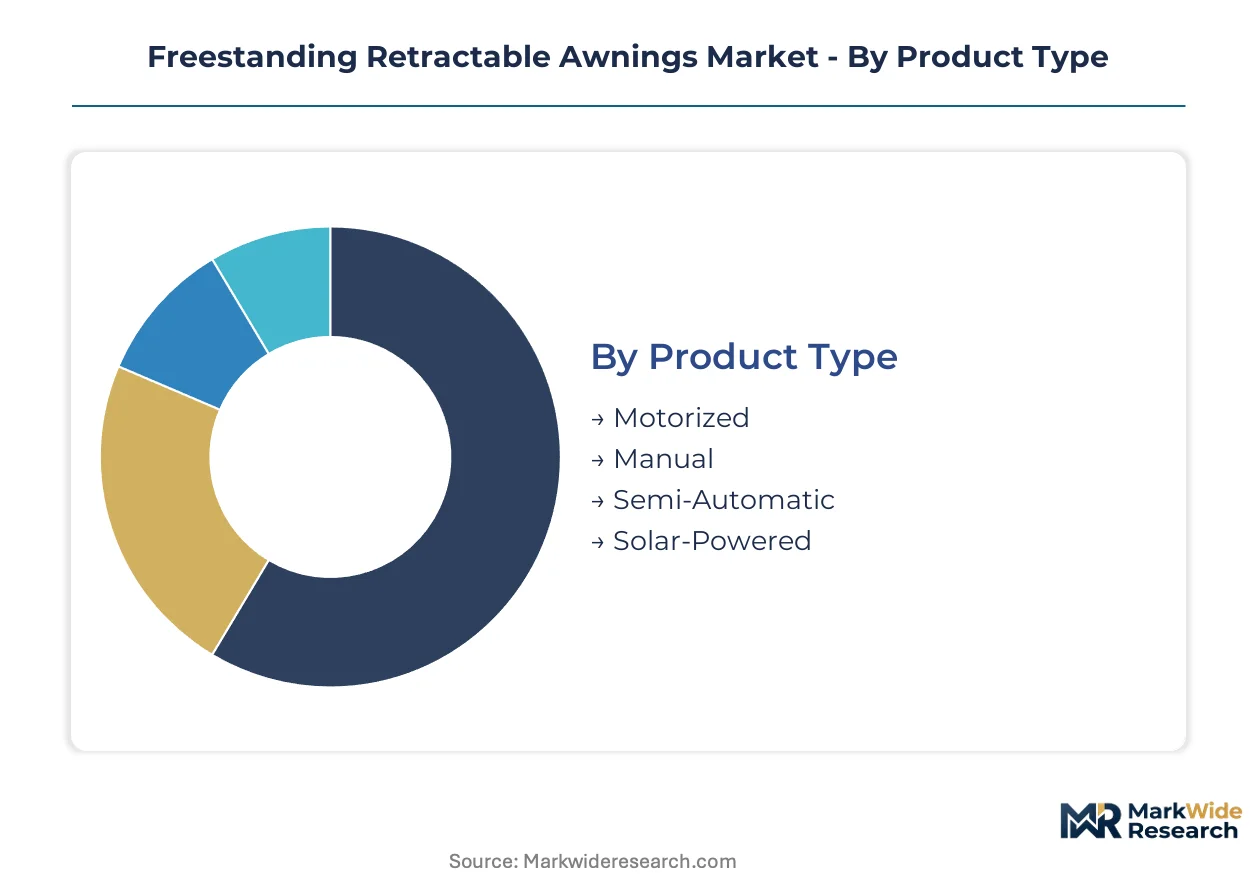
Segmentation in the freestanding retractable awnings market reveals divergent specification logics across procurement channels. Hospitality buyers prioritize automation integration and wind-sensor compatibility, while residential purchasers emphasize manual simplicity and upfront cost containment. Material selection and application context further stratify vendor positioning and margin capture.
Product Type:
Purchase authority and operational complexity separate buyers across automation tiers, with hospitality procurement teams favoring integrated control systems and residential owners accepting trade-offs for simplicity.
- Motorized:Electric drive systems with remote control and wind-sensor automation dominate hospitality specification in Germany and California. Restaurant chains absorb higher capital costs to reduce manual labor and warranty exposure from operator error. Motorized leads volumes today; solar-powered is gaining share fastest.
- Manual:Hand-crank mechanisms serve budget-conscious residential installations and temporary event deployments where electrical infrastructure is absent. German café operators in heritage districts select manual units to satisfy historic preservation restrictions on visible automation hardware.
- Semi-Automatic:Hybrid cranks with motorized assist reduce physical effort while preserving grid independence for rural recreational areas in Australia.
- Solar-Powered:Photovoltaic-integrated cantilever arms with battery storage eliminate electrical contracting for safari lodges in Kenya and Botswana.
Specification authority concentrates in motorized systems for commercial portfolios; solar-powered variants expand most quickly in off-grid recreational development.
Material:
Performance certification and lifecycle cost calculations drive material selection divergence between permanent commercial installations and temporary event deployments.
- Aluminum:Powder-coated extrusions deliver strength-to-weight optimization for cantilever spans exceeding six meters. REACH-compliant coating facilities in Germany and Italy anchor supply for EU commercial retrofits under Green Deal thermal performance mandates. Aluminum leads volumes today; acrylic fabric is gaining share fastest.
- Steel:Galvanized framing supports high wind-load zones in coastal Mediterranean markets where structural certification exceeds aluminum limits. Italian frame manufacturers maintain captive steel fabrication for CE-marked snow-load assemblies.
- Polyester Fabric:Uncoated woven substrates serve single-season event deployments in Texas and Florida where UV degradation timelines align with temporary use cycles.
- Acrylic Fabric:Solution-dyed synthetic fibers with fluoropolymer finishes achieve ten-year colorfastness warranties for German hospitality operators.
- PVC Coated Fabric:Vinyl-laminated polyester competes aggressively on upfront cost for budget event-space operators trading durability for capital conservation.
Aluminum extrusions dominate permanent commercial specification; acrylic fabric assemblies command expanding share in premium hospitality retrofits.
Application:
Regulatory exposure and revenue-per-square-foot economics differentiate deployment contexts, with food-service operators facing stricter enclosure codes than residential owners.
- Residential Patios:Suburban homeowners in Texas and California prioritize manual simplicity and dealer network proximity over automation integration. Warranty terms and local installation labor availability drive vendor selection more than technical specification.
- Outdoor Cafés:German café operators under EnEV energy codes specify motorized assemblies with integrated cooling accessories to satisfy thermal envelope retrofit requirements. OSHA fall-protection compliance costs for US restaurant chains prioritize national vendor relationships over regional price competition.
- Commercial Storefronts:Retail outlets in Dubai and Singapore specify sensor-networked shade assets for smart-city infrastructure integration.
- Event Spaces:Temporary deployment economics favor PVC-coated fabric on steel frames for budget-sensitive operators in seasonal markets.
- Recreational Areas:Off-grid safari lodges in Botswana and Kenya drive solar-powered motorization specification for remote poolside installations.
Outdoor café applications anchor commercial revenue concentration; recreational area deployments demonstrate steepest expansion trajectory amid off-grid hospitality development.
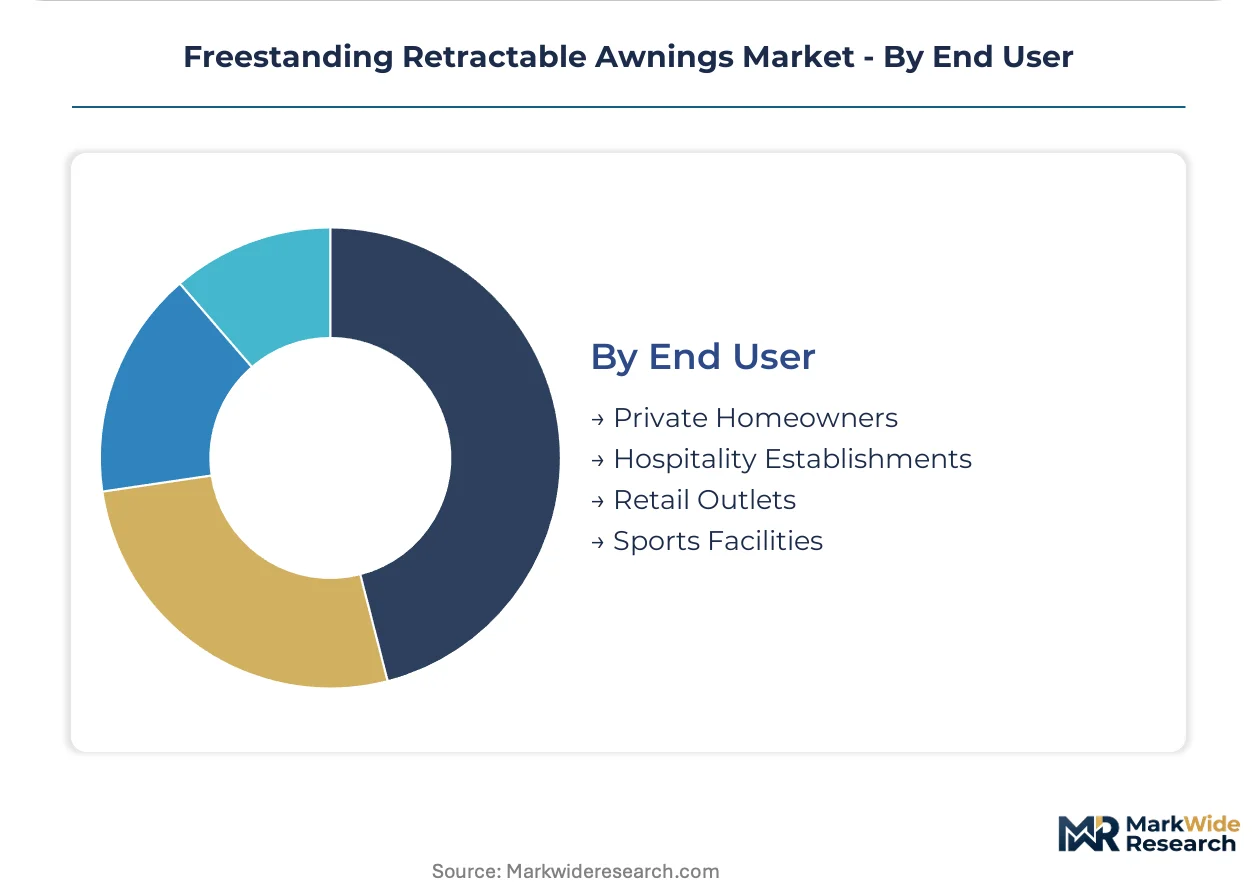
End User:
Procurement centralization and specification authority separate institutional buyers from dispersed residential decision-makers, with portfolio-scale operators unbundling service contracts from initial supply.
- Private Homeowners:Fragmented purchase authority and dealer network dependence characterize residential channels across North America. Sunesta's extensive dealer infrastructure captures this dispersed demand through localized installation and warranty service.
- Hospitality Establishments:National restaurant chains and hotel operators centralize procurement for outdoor seating expansions under shade structures. US university and corporate campus facilities management platforms mandate API-accessible maintenance scheduling, unbundling after-sales service from initial supply contracts.
- Retail Outlets:Commercial storefront operators in Mediterranean markets prioritize wind-resistant engineering and CE marking continuity for high-traffic pedestrian zones.
- Sports Facilities:Municipal and private athletic complexes in Australia and South Africa specify solar-charged drive systems for grandstand shade and spectator comfort.
Hospitality establishments dominate commercial specification volume; sports facilities demonstrate fastest-growing procurement activity amid recreational infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metalworking labor pools in Germany's Ruhr Valley and Italy's Veneto region anchor European fabrication capacity for precision aluminum extrusion and powder-coating operations.
United States
Hospitality operators in California and Texas are expanding outdoor seating capacity under shade structures to capture extended dining seasons. OSHA fall-protection standards govern commercial installation labor costs across these states. National restaurant chains in Florida prioritize centralized procurement relationships over regional price competition.
Germany
Café culture in Berlin and Munich intersects with strict EnEV energy codes to drive motorized awning specification for thermal envelope retrofits. REACH compliance is consolidating cost-of-entry calculus for domestic fabric suppliers. MARKILUX GmbH + CO. KG leverages German engineering heritage to dominate premium motorized installations across Central Europe.
Italy
Wind-resistant engineering requirements in coastal Mediterranean markets sustain demand for galvanized steel framing beyond aluminum limits. CE marking mandates structural load testing for snow-load assemblies in Alpine-adjacent regions. Frame manufacturers in Veneto maintain captive steel fabrication facilities to maintain certification continuity.
Australia
Off-grid recreational area expansion in Queensland and Western Australia creates specification pull for solar-charged drive systems. Municipal sports facilities specify battery-integrated motorization for grandstand shade installations. Safari lodge operators source remote poolside units through specialized procurement channels.
United Arab Emirates
Smart-city infrastructure convergence in Dubai and Singapore opens specification channels for sensor-networked shade assets. Retail outlets prioritize wind-resistant engineering for high-traffic pedestrian zones. Facilities management platforms mandate API-accessible maintenance scheduling for portfolio-scale outdoor amenity standardization.
Freestanding Retractable Awnings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across motorized, manual, and solar-powered product tiers. The vendor base stratifies between premium engineering-led German manufacturers, North American residential channel specialists, and Mediterranean wind-resistance experts. Three archetypes dominate: heritage engineering houses with captive coating facilities, dealer-network-dependent residential distributors, and project-specific commercial rigging contractors. Competitive moves concentrate on backward integration into fabric sourcing and geographic expansion through acquisition of regional installation service providers.
Among German heritage engineering houses, MARKILUX GmbH + CO. KG exemplifies the premium motorized tier through its vertically controlled supply chain. Sunesta occupies a position within North American residential channels characterized by extensive dealer infrastructure. Mitjavila anchors Mediterranean commercial project execution through specialized engineering credentials. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Marygrove Awnings |
| Mitjavila |
| Advanced Design Awnings & Signs |
| Shades Awnings |
| NuImagePro & NuImage Awnings |
| Commercial Awnings Ltd |
| MARKILUX GmbH + CO. KG |
| Sunesta |
| Eide Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Hospitality procurement teams with portfolio-scale outdoor amenity mandates are consolidating purchase authority around bundled service contracts that unbundle after-sales maintenance from initial capital expenditure. This buyer concentration is compressing margin pools for mid-tier frame assemblers while rewarding vendors with captive coating facilities and vertically controlled fabric sourcing.
Pricing Analysis
Bundled service contracts dominate premium hospitality procurement while unbundled transactional pricing persists in residential channels. Three-tier pricing structure across premium motorized, standard manual, and economy event-space tiers separates vendors by automation integration and wind-sensor certification. Pricing pressure stems from REACH compliance cost escalation in European fabric mills. Residential homeowners in Texas and Florida exhibit highest price sensitivity; German café operators under EnEV codes demonstrate lowest sensitivity due to thermal retrofit mandates.
Supply Chain Analysis
Direct-to-hospitality channels handle national restaurant chain demand while dealer networks serve fragmented residential buyers. Powder-coated aluminum extrusions draw from German Ruhr Valley and Italian Veneto fabrication clusters; solution-dyed acrylic fabric sources from REACH-compliant European mills. Single-source vulnerability concentrates in specialized wind-load anchoring expertise among rigging contractors. Distribution runs through project-specific commercial contractors for institutional buyers and localized dealer infrastructure for homeowners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hospitality operators shift specification authority toward sensor-networked assets with API-accessible maintenance scheduling rather than commodity shade structures.
For Market Incumbents: Extend backward integration into captive coating facilities and vertically controlled fabric sourcing to defend against REACH compliance cost escalation compressing mid-tier margins. Prioritize certification investment for CE-marked wind-load assemblies above six-meter projection to maintain specification access in German and Italian commercial retrofits. For New Entrants and Emerging Players: Launch via solar-powered motorization specialization targeting off-grid recreational development in Australia and safari lodge procurement channels in Botswana and Kenya. Bypass saturated North American residential dealer networks by direct specification to facilities management platforms with standardized asset tracking requirements. For Investors and Strategic Acquirers: Building envelope retrofit contractors pursuing EU Green Deal thermal performance mandates are the most active acquirer in this space. Target mid-tier frame assemblers with established CE marking continuity and German engineering credentials. Watch for inflection in municipal IoT integration requirements across Dubai and Singapore smart-city infrastructure programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabric Sourcing | REACH compliance cost escalation in European mills rewards captive supply control for CE marking continuity. |
| Geographic Expansion through Installation Service Acquisition | OSHA fall-protection compliance costs in US hospitality channels favor owned rigging capabilities over subcontractor dependence. |
| Solar-Powered Product Line Extension | Off-grid recreational development in Australia and safari lodge procurement in Kenya creates specification pull for battery-integrated motorization. |
| Smart-City Infrastructure Partnership | Municipal IoT integration requirements in Dubai and Singapore open channels for sensor-networked shade assets with API accessibility. |
| Premium Motorized Tier Certification Investment | Wind-sensor automation and remote-control integration command widest margin pools in German hospitality retrofit procurement. |
Research Methodology
Bottom-up hospitality procurement modeling reconciled against top-down aluminum extrusion and fabric supply tracking forms the analytical core. Primary interviews with facilities management platform directors, commercial awning installation contractors, powder-coating facility operators, and hospitality procurement executives combined with secondary validation against EU F-Gas Regulation filings, OSHA enforcement databases, ECHA SVHC candidate list updates, and national building code harmonization records.
Historical trendline analysis across motorized, manual, semi-automatic, and solar-powered product types calibrated against application context segmentation and end-user procurement centralization patterns shaped the projection framework. CAGRs derived from installation volume trajectories in hospitality expansion zones and thermal envelope retrofit mandates throughout the forecast period. Industry-specific inputs include REACH compliance cost curves and smart-city infrastructure deployment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal enforcement acceleration or sudden aluminum extrusion supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Middle-East Christmas Tree Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Luxury Outdoor Furniture Market