
 Polyethylene Wax Market | 2026-2036
Polyethylene Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Wax Market Analysis
Paraffin wax is decoupling from premium coating formulations as polyethylene wax offers superior thermal stability and lower volatile organic compound profiles. Mitsui Chemicals leverages its integrated ethylene feedstock position to sustain cost leadership across Asian supply chains. BASF SE anchors European demand through specialized oxidized grades for water-based coatings. Honeywell International Inc. competes in high-performance micronized powders targeting precision ink applications.
Polyethylene wax comprises low molecular weight polyethylene polymers typically ranging from 500 to 10,000 g/mol molecular weight, manufactured via high-pressure polymerization, thermal degradation, or Fischer-Tropsch byproduct recovery, functioning primarily as lubricants, dispersants, and surface modifiers in processing thermoplastics and coatings. Powder grades dominate volume throughput in masterbatch production where melt flow enhancement commands consistent procurement, while emulsion formats represent the fastest-growing category as waterborne coating conversions accelerate in architectural and industrial finishes. Pellet forms retain margin strength in automated compounding operations serving automotive and food packaging end use industries.
REACH registration requirements in Europe and China's GB 4806 food-contact material standards collectively elevate analytical certification burdens for cross-border suppliers. The EPA's Toxic Substances Control Act oversight in the United States further shapes product stewardship obligations for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms deliver superior compliance economics.
Market Dynamics
Automotive OEMs are consolidating adhesive specifications toward hot-melt systems that eliminate solvent-based curing, directly amplifying polyethylene wax consumption in viscosity-modified formulations. This specification shift is compressing procurement cycles for traditional paraffin alternatives.
Growth Catalysts
- China's GB 4806 food-contact mandates:Domestic packaging converters are upgrading to high-purity PE wax grades to satisfy migration limits on heavy metals and aromatic content, creating certified-grade demand premiums.
- Masterbatch compounding cluster expansion:East Asian thermoplastics processors are scaling color and additive concentrate output, where PE wax functions as the primary dispersion medium for pigment loading efficiency.
- Thermal degradation process refinements:Advanced cracking control technologies are yielding narrower molecular weight distributions, enabling finer segmentation between coating-grade and plastics-processing-grade wax specifications.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracking economics and shale-gas pricing differentials inject margin instability into polymerization-based wax production, particularly affecting non-integrated manufacturers.
- Fischer-Tropsch byproduct supply concentration:Gas-to-liquid output from South African and Middle Eastern facilities dominates one synthesis pathway, creating geographic chokepoints for specific wax grade availability.
- Paraffin wax price arbitrage:Refined slack wax from lubricant base oil production retains cost advantage in non-critical coating applications, limiting PE wax penetration in price-sensitive industrial segments.
Strategic Opportunities
- India's packaging sector formalization:BIS certification requirements for food-contact plastics are accelerating organized sector conversion from unrefined mineral waxes to certified PE wax alternatives in flexible packaging.
- Waterborne architectural coating conversion:Emulsified oxidized PE wax grades are capturing share from solvent-based surface modifiers as VOC regulations tighten across municipal building codes.
- 3D printing filament lubrication:Micronized PE wax powders are emerging as processing aids for engineering polymer filaments, reducing nozzle wear and layer adhesion defects in industrial additive manufacturing.
Industry Challenges
- Analytical certification bottlenecks:REACH registration dossiers and GB standard test reports require specialized toxicology and migration study documentation, extending supplier qualification timelines by 8-14 months.
- Legacy compounding equipment incompatibility:Automated masterbatch lines engineered for pellet-fed systems cannot accommodate powder-grade wax without pneumatic conveying retrofits, constraining format flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Wax Market |
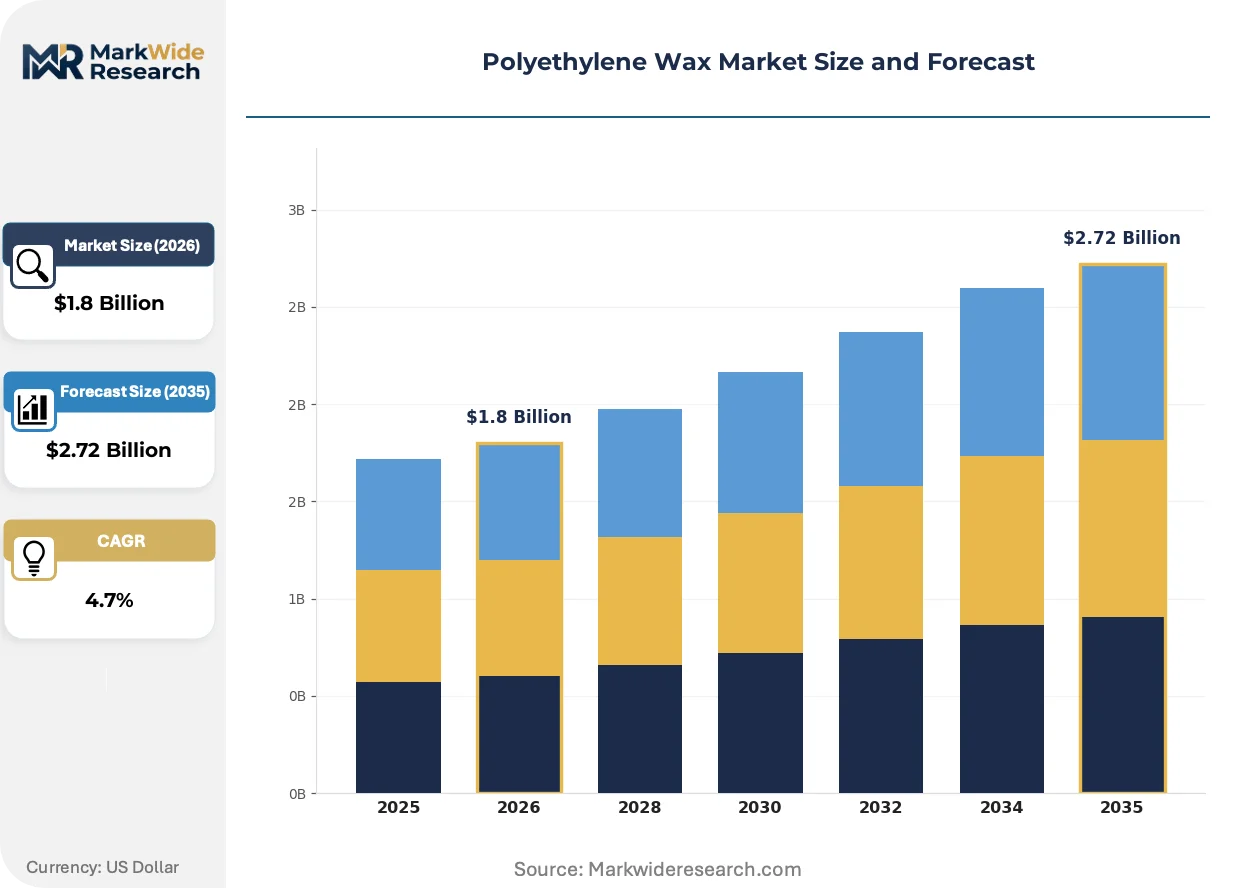
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Powders, Pellets, Pastes Application: Candles, Coatings, Plastics, Inks End Use Industry: Cosmetics, Food Packaging, Automotive, Textiles Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Mitsui Chemicals, Westlake Chemical Corporation, BASF SE, The Lubrizol Corporation, Trecora Resources, Clariant, DEUREX, Innospec Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Wax Market Emerging Trajectories
Formulation science is converging with regulatory toxicology, pushing suppliers to document chain-of-custody purity rather than simply meeting technical specifications. This documentation burden is reshaping competitive advantage toward integrated producers with captive feedstock control.
Micronized PE wax with controlled particle size distributions below 20 microns is integrating into precision inkjet ink formulations, where surface tension modification and rub resistance are critical performance parameters. Specialty ink manufacturers in Germany and Japan are qualifying these grades for high-speed commercial printing applications. The technology is integrating pigment stabilization and substrate adhesion functions previously requiring multi-additive packages, compressing formulation complexity for ink compounders.
REACH authorization requirements for substances of very high concern are tightening impurity thresholds for oxidized PE wax imports into EU member states. ECHA dossier updates are mandating additional analytical testing for polycyclic aromatic hydrocarbon traces in thermal degradation-derived grades. Waterborne coating formulators in France and Italy are responding by dual-sourcing from Fischer-Tropsch and polymerization routes to mitigate authorization risk.
Automotive tier suppliers are compressing adhesive qualification cycles from 24 months to 12 months, forcing PE wax vendors to pre-certify viscosity-modified grades against multiple OEM hot-melt specifications simultaneously. Direct procurement relationships are displacing distributor-mediated supply for high-volume masterbatch compounders serving German and South Korean automotive clusters. This pattern is most visible in Bavaria and Gyeonggi-do province, where just-in-time adhesive delivery contracts now specify wax-derived viscosity stability under thermal aging protocols.
Polyethylene Wax Market Segmentation
Polyethylene wax procurement patterns diverge sharply across product formats and end-use specifications. Masterbatch compounders, coating formulators, and automotive tier suppliers each impose distinct technical requirements that reshape supplier priorities and margin structures.
Product Type:
Equipment upgrade cycles and formulation conversions are redistributing volume across physical formats as processors modernize handling infrastructure.
- Powders:Fine particulate grades with controlled particle size distributions below 200 microns dominate masterbatch compounding operations. East Asian thermoplastics processors in Zhejiang and Guangdong provinces absorb consistent throughput where melt flow enhancement commands premium positioning.
- Emulsions:Water-dispersed oxidized grades serve architectural coating formulators eliminating solvent-based systems. French and Italian waterborne coating specialists are qualifying these grades for VOC-compliant building finishes under tightening municipal codes.
- Pellets:Dense, low-dust formats retain margin strength in automated feeding systems serving automotive adhesive compounders.
- Pastes:Pre-dispersed concentrates address small-batch cosmetics formulators lacking in-house dispersion equipment.
Volume placements concentrate in powders; the faster expansion belongs to emulsions.
Application:
Cost tier stratification separates commodity-grade consumption from performance-critical specifications where certification premiums apply.
- Plastics:Masterbatch dispersion and processing lubrication for polyethylene and polypropylene compounding. German automotive color concentrate suppliers specify narrow molecular weight distributions for pigment loading efficiency in bumper and interior trim applications.
- Coatings:Surface modification and rub resistance for industrial and architectural finishes. Waterborne conversions in France and Italy are displacing paraffin-based modifiers.
- Inks:Micronized grades below 20 microns modify surface tension for inkjet formulations. Japanese precision ink manufacturers qualify these for high-speed commercial printing.
- Candles:Fragrance carrier and burn rate control in decorative and utility candle manufacturing.
Plastics applications anchor procurement volume; coatings are climbing the fastest as regulatory pressure intensifies.
End Use Industry:
Customer type maturity determines whether procurement emphasizes price stability or technical partnership depth.
- Automotive:Hot-melt adhesive viscosity modification for assembly bonding. Bavarian and Gyeonggi-do province tier suppliers compress qualification cycles from 24 months to 12 months under just-in-time delivery contracts.
- Food Packaging:High-purity grades satisfying China's GB 4806 migration limits and EU REACH food-contact requirements. Domestic Chinese converters upgrade from mineral waxes to certified PE wax alternatives.
- Cosmetics:Emollient and thickening functions in personal care formulations. BIS certification requirements in India accelerate organized sector conversion from unrefined inputs.
- Textiles:Yarn lubrication and finishing agent applications in synthetic fiber processing.
Automotive specifications dominate value capture; food packaging is gaining share fastest on regulatory tailwinds.
Distribution Channel:
Supply concentration shapes whether procurement flows through intermediaries or direct relationships.
- Direct Sales:High-volume masterbatch compounders serving German and South Korean automotive clusters bypass distributors for technical partnership depth. Annual contract structures specify thermal aging stability protocols.
- Wholesale:Regional distributors aggregate fragmented demand from mid-tier coating formulators and plastics processors.
- Online:E-procurement platforms capture spot purchases from small-batch cosmetics and candle manufacturers.
- Retail:Limited presence in specialty chemical supply stores serving artisan formulators.
Direct sales concentrate contract value; wholesale channels handle the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate polyethylene wax demand through masterbatch compounding clusters serving automotive and packaging converters. German chemical parks in Bavaria and North Rhine-Westphalia anchor European supply chains for high-purity oxidized grades. India's Gujarat and Maharashtra industrial corridors are formalizing BIS-certified food-contact wax procurement.
China
Masterbatch compounders in Zhejiang and Guangdong provinces drive consistent powder-grade consumption for pigment dispersion in automotive plastics. GB 4806 food-contact material standards enforce migration limits on heavy metals and aromatic content, forcing domestic packaging converters to upgrade from mineral waxes. The Yangtze River Delta cluster around Shanghai absorbs premium certified-grade volumes for export-oriented flexible packaging.
Germany
Automotive tier suppliers in Bavaria specify narrow molecular weight distribution waxes for hot-melt adhesive viscosity modification in bumper and interior trim bonding. REACH registration dossiers mandate polycyclic aromatic hydrocarbon testing for thermal degradation-derived imports, compressing supplier qualification timelines. The North Rhine-Westphalia chemical corridor hosts specialized oxidized grade production for waterborne architectural coatings.
United States
Hot-melt adhesive compounders serving Detroit automotive clusters procure pelletized viscosity modifiers under EPA Toxic Substances Control Act stewardship protocols. Shale-gas ethylene feedstock economics sustain cost positioning for polymerization-based wax production against imports. Gulf Coast petrochemical integration supports backward integration into captive polyethylene wax supply for integrated adhesive manufacturers.
India
Flexible packaging converters in Gujarat and Maharashtra are transitioning from unrefined mineral waxes to BIS-certified polyethylene wax alternatives under formalized food-contact regulations. Organized sector expansion in Mumbai-Pune and Ahmedabad-Vadodara corridors creates certified-grade demand premiums. Cosmetics formulators in Delhi-NCR specify emulsion-grade waxes for personal care thickening applications.
South Korea
Automotive adhesive suppliers in Gyeonggi-do province operate under compressed 12-month qualification cycles for viscosity-modified wax grades against multiple OEM specifications. Just-in-time delivery contracts now specify thermal aging stability protocols for hot-melt systems eliminating solvent-based curing. Busan-Ulsan petrochemical complexes leverage integrated ethylene positions to serve export masterbatch demand.
Polyethylene Wax Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical groups commanding polymerization-based supply and independent refiners dominating thermal degradation niches. Three archetypes define competitive positioning: integrated ethylene producers with captive feedstock control, specialized wax refiners with narrow specification expertise, and diversified chemical conglomerates with oxidized grade portfolios. Capacity expansion in Fischer-Tropsch byproduct recovery and strategic partnerships for emulsion technology licensing represent the dominant competitive moves reshaping supply availability.
Among integrated petrochemical groups, Mitsui Chemicals exemplifies the captive feedstock archetype through its Asian ethylene position, while BASF SE anchors European oxidized grade specialization. Honeywell International Inc. occupies the diversified technology tier with micronized powder capabilities. Westlake Chemical Corporation represents North American scale-driven positioning. These named entities illustrate how geographic feedstock access and regulatory compliance depth determine competitive segmentation rather than product substitution alone.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Westlake Chemical Corporation |
| BASF SE |
| The Lubrizol Corporation |
| Trecora Resources |
| Clariant |
| DEUREX |
| Innospec Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Naphtha price differentials between Asian and Gulf Coast benchmarks cascade through polyethylene wax supply chains, compressing margins for non-integrated thermal degradation producers while rewarding ethylene crackers with captive feedstock positions. This raw-material arbitrage stratifies procurement economics across polymerization-derived, Fischer-Tropsch byproduct, and thermal cracking synthesis routes.
Pricing Analysis
Lead-time compression commands premium positioning in polyethylene wax procurement, with just-in-time automotive adhesive contracts in Bavaria and Gyeonggi-do province pricing above spot inventory held by regional distributors. Three-tier pricing structure across certified food-contact, industrial-grade, and unrefined mineral wax alternatives separates migration-tested GB 4806 grades from commodity coating inputs. Price erosion runs through powder-grade masterbatch volumes as Zhejiang compounders consolidate procurement scale. Small-batch cosmetics formulators exhibit highest price sensitivity; automotive tier suppliers prioritize thermal aging stability over unit cost.
Supply Chain Analysis
REACH registration dossiers and GB 4806 migration test reports function as certification gates that extend supplier qualification timelines by 8-14 months, concentrating supply relationships among integrated producers with analytical infrastructure. Manufacturing concentrates in China, Germany, and the United States, with South Korean petrochemical complexes serving export masterbatch demand. Ethylene feedstock, slack wax byproduct, and specialized oxidation catalysts constitute critical input dependencies. Single-source vulnerability permeates Fischer-Tropsch byproduct supply from South African and Middle Eastern gas-to-liquid facilities. Distribution runs through direct sales contracts for high-volume automotive compounders and wholesale channels for fragmented coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyethylene wax supply is tightening around analytical certification bottlenecks, with REACH dossier requirements and GB 4806 migration studies constraining qualified supplier pools and sustaining pricing power for integrated producers with captive testing infrastructure.
For Market Incumbents: Lock in long-term ethylene supply agreements and expand in-house oxidation capacity to defend against Fischer-Tropsch byproduct supply concentration. Pre-certify viscosity-modified grades against multiple OEM hot-melt specifications simultaneously to compress automotive qualification cycles from 24 months toward 12-month benchmarks. For New Entrants and Emerging Players: Small-batch cosmetics formulators lacking in-house dispersion equipment represent an underserved buyer archetype accessible through pre-dispersed paste formats and emulsion-grade wax offerings. India's Gujarat and Maharashtra flexible packaging corridors offer penetrable white-space as BIS certification requirements accelerate organized sector conversion from unrefined mineral waxes. A technical partnership with established emulsion technology licensors enables rapid formulation qualification without proprietary R&D investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal degradation specialists with narrow molecular weight distribution capabilities in European chemical parks, where REACH authorization burdens have compressed valuations for non-integrated refiners. The 5-10 year viability window favors acquisition targets with backward integration into ethylene feedstock or Fischer-Tropsch offtake agreements. Watch for ECHA dossier updates on polycyclic aromatic hydrocarbon thresholds as the inflection signal for authorization risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Mitsui Chemicals leverages Asian naphtha cracking economics to sustain cost leadership against import-dependent competitors. |
| Emulsion Technology Licensing Partnership | French and Italian waterborne coating specialists qualify oxidized grades under tightening municipal VOC codes. |
| Micronized Powder Capacity Expansion | Honeywell International Inc. targets precision inkjet ink formulations below 20 microns for Japanese commercial printing applications. |
| GB 4806 Certification Infrastructure Investment | Domestic Chinese packaging converters capture certified-grade demand premiums in Yangtze River Delta export corridors. |
| Long-term Automotive Adhesive Supply Agreement | Bavarian tier suppliers specify thermal aging stability protocols under compressed 12-month qualification cycles. |
Methodological Framework
Independent corroboration across customs trade data, SEC 10-K filings, and ACC/Cefic industry reports underwrites the qualitative findings in this study. Primary interviews with polyethylene wax plant managers, procurement leads at German and South Korean automotive tier suppliers, masterbatch compounders in Zhejiang and Guangdong provinces, and distribution channel partners in European chemical parks were combined with secondary validation from ECHA registration dossiers, FDA food-contact notifications, and BIS certification records. Bottom-up volume estimates from end-use industry consumption patterns and top-down supply-side capacity assessments were triangulated to establish market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects and currency translation impacts. Segmentation dimensions modeled include product format, synthesis route, application, end-use industry, and regional production hub. CAGRs were derived from regression analysis against ethylene feedstock cost trajectories, regulatory compliance cost escalations, and end-use industry production indices. Industry-specific forecast inputs encompass automotive adhesive specification shifts toward hot-melt systems and waterborne coating conversion rates in European architectural markets.
Revisions become necessary when ethylene feedstock volatility exceeds historical bands, REACH authorization requirements expand substance scope, or automotive OEM qualification cycles compress further. Forecasts reflect documented assumptions on capacity expansion timelines, regulatory enforcement intensity, and substitution elasticity between polyethylene and paraffin wax grades. A model refresh is warranted upon material change in ECHA dossier requirements for thermal degradation-derived grades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
EVA Foam Market