
 Polyglycerol Polyricinoleate Market | 2026-2036
Polyglycerol Polyricinoleate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycerol Polyricinoleate Market Analytics
Modular emulsion-delivery formats are gaining traction as buyers seek application-specific PGPR grades rather than universal formulations, and this unbundling of product lines is realigning procurement patterns across food manufacturing. BASF SE leverages its integrated oleochemicals platform to sustain supply security for high-volume confectionery customers. Palsgaard A/S anchors its position through specialized emulsifier blends that combine PGPR with complementary stabilizers. KLK Oleo competes on backward integration into palm oil derivatives, controlling raw material costs across Southeast Asian production bases.
Polyglycerol polyricinoleate is a complex ester synthesized from polymerized glycerol and castor oil fatty acids, typically exhibiting a viscosity range of 300-800 mPa·s at 25°C and a hydroxyl value below 50 mg KOH/g, functioning primarily as a water-in-oil emulsifier and viscosity reducer in lipid-based food systems. The liquid product type dominates current volume shipments due to its ease of incorporation into continuous chocolate tempering processes, while powder formats are gaining share in dry-mix bakery applications where storage stability and dust-free handling matter. Among applications, confectionery represents the most mature revenue pool with established formulation protocols, whereas dairy alternatives present faster growth trajectories as plant-based beverage makers adopt PGPR to mimic mouthfeel previously delivered by dairy lipids.
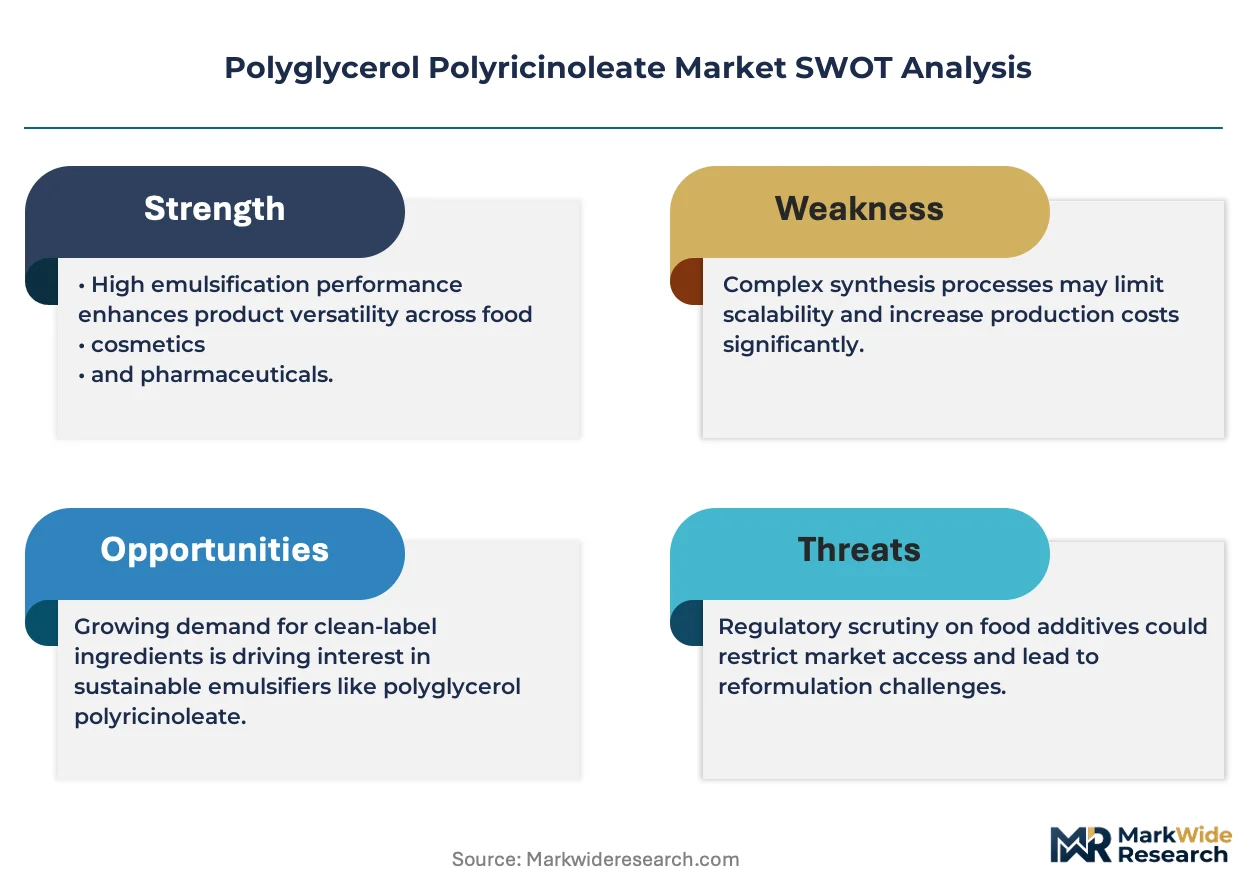
EFSA maintains stringent specifications for polyglycerol ester additives under Regulation (EC) No 1333/2008, while the FDA governs PGPR use in chocolate and cocoa products through 21 CFR 172.854, with both frameworks directly shaping acceptable purity thresholds and labeling requirements. BIS in India enforces additive quality standards through IS specifications that affect import clearance and domestic manufacturing compliance for suppliers targeting processed food exporters. Stakeholders must monitor evolving maximum-residue limits for 3-MCPD and glycidyl esters across jurisdictions, as tightening thresholds will force process investments or raw material sourcing shifts well before regulatory deadlines crystallize.
Market Dynamics
Chocolate manufacturers are systematically reducing cocoa butter content in formulations, forcing emulsifier suppliers to engineer PGPR grades that maintain flow properties at lower lipid concentrations. This technical pivot is compressing margins for commodity-grade producers while rewarding specialists with application-specific capabilities.
Growth Catalysts
- EFSA Re-evaluation Mandates:Tightening purity specifications under Regulation (EC) No 1333/2008 are disqualifying marginal suppliers and consolidating volume with certified producers capable of meeting sub-50 ppm 3-MCPD thresholds.
- Castor Oil Derivative Chemistry:Advances in controlled polymerization of glycerol are yielding PGPR variants with narrower viscosity bands, enabling precision dosing in automated tempering lines.
- German Processing Clusters:Industrial chocolate manufacturing concentration around Hamburg and Cologne generates contract-manufacturing demand that flows through to emulsifier procurement at scale.
Market Restraints
- Castor Bean Supply Concentration:Over 85% of global castor oil originates from Indian and Brazilian agricultural zones, exposing PGPR producers to monsoon variability and port logistics disruptions.
- Lecithin Price Volatility:Soy and sunflower lecithin substitutes create pricing ceilings that constrain PGPR premium positioning in cost-sensitive confectionery segments.
- EFSA 3-MCPD Threshold Compression:Anticipated reductions in maximum residue limits for glycidyl esters will force process revalidation investments before regulatory deadlines formalize.
Strategic Opportunities
- Plant-Based Dairy Formulation:Oat and almond beverage manufacturers are adopting PGPR to replicate dairy lipid mouthfeel, opening volume channels outside traditional confectionery.
- Dry-Mix Bakery Penetration:Powder-grade PGPR formats address dust-free handling requirements in industrial bakery premix operations currently dependent on liquid emulsifier workarounds.
- BIS IS Standard Alignment:Indian processed food exporters are demanding additive compliance documentation that creates certification-service revenue for testing laboratories and qualified suppliers.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Testing laboratories face recruitment gaps for chromatography specialists capable of validating sub-ppm contaminant detection methods required by EFSA protocols.
- Legacy Tempering System Retrofit Costs:Chocolate manufacturers operating pre-2015 continuous tempering lines require mechanical modifications to handle next-generation low-viscosity PGPR grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycerol Polyricinoleate Market |
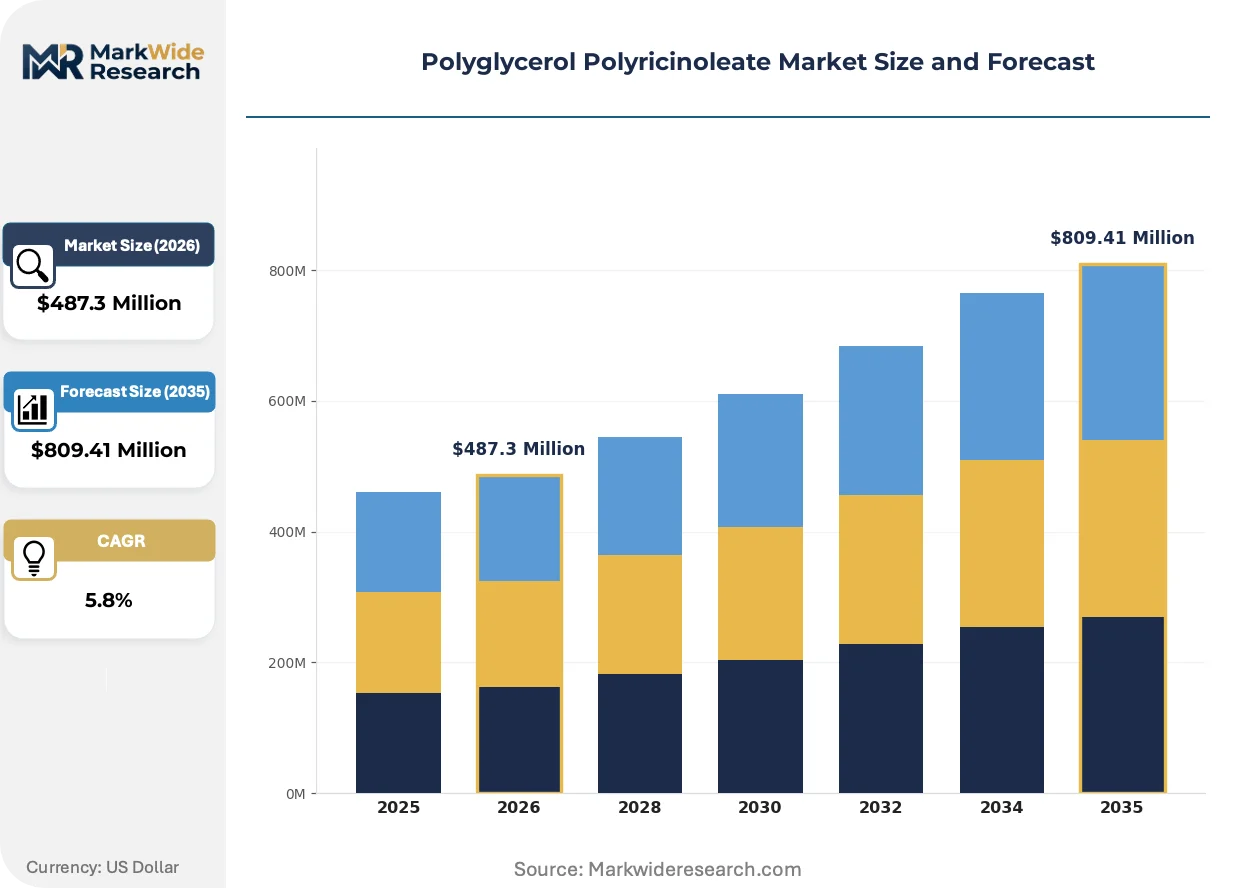
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Gel Application: Baking, Confectionery, Dairy, Sauces End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Nutraceutical Brands Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | BASF SE, Estelle Chemicals Pvt. Ltd., Cargill, KLK Oleo, DuPont, Palsgaard A/S, Croda International Plc, Wilmar International Limited, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycerol Polyricinoleate Market Evolving Landscape
Modular emulsion-delivery formats are fragmenting procurement patterns as buyers reject universal PGPR formulations in favor of application-tuned grades with specified hydroxyl values and viscosity profiles. This specification unbundling is forcing suppliers to maintain parallel product lines and technical service capabilities.
Enzymatic interesterification is integrating into PGPR production workflows, enabling manufacturers to achieve precise esterification degrees without thermal degradation of polyglycerol backbones. Mid-tier confectionery houses in Belgium and Switzerland are adopting these grades to reduce tempering energy inputs. The technology is integrating process control capabilities that commodity producers cannot replicate without capital-intensive reactor upgrades.
REACH Annex XIV authorization requirements for castor oil derivatives are compelling EU-based formulators to document supply chain substance volumes and exposure scenarios. Industrial chocolate processors in Germany and the Netherlands are responding by demanding full mass-balance certification from emulsifier suppliers. This regulatory friction is accelerating supplier consolidation as smaller blenders lack compliance infrastructure.
Buyers are unbundling technical service from product supply, negotiating separate contracts for formulation support, regulatory documentation, and volume commitments. Large confectionery groups in France and Italy are centralizing emulsifier procurement through specialized purchasing cooperatives that aggregate demand across multiple manufacturing sites. This purchasing model is compressing distributor margins and favoring direct manufacturer relationships with dedicated technical account management.
Polyglycerol Polyricinoleate Market Segmentation
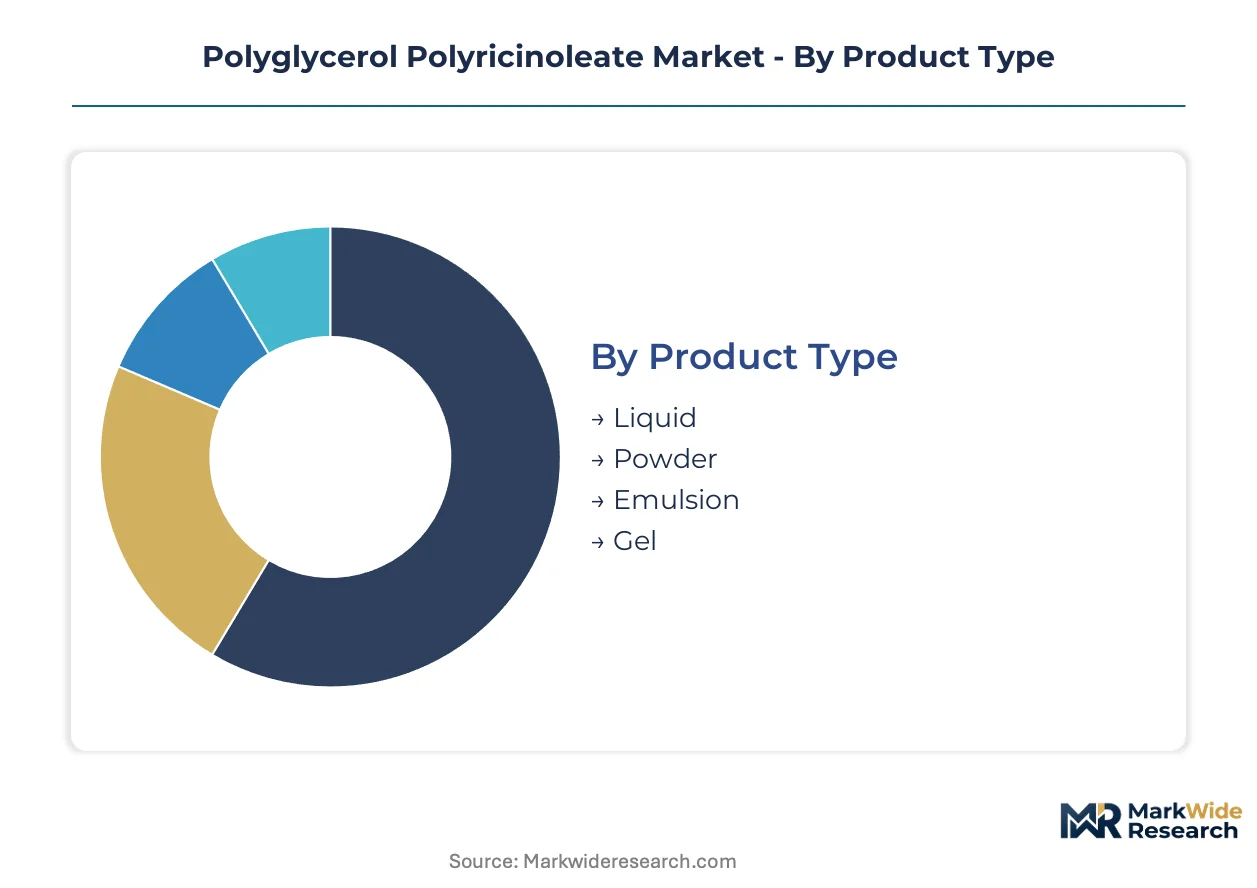
PGPR procurement patterns diverge sharply between integrated chocolate processors seeking bulk liquid supply and specialty formulators requiring precision-grade powders. Understanding these segment boundaries clarifies where technical service investments yield pricing power versus where volume commoditization dominates.
Product Type:
Integration depth separates continuous-process users embedding PGPR directly into tempering lines from batch operators blending emulsifiers offline.
- Liquid:Dominates continuous chocolate tempering with viscosity specifications of 300-800 mPa·s at 25°C, enabling automated dosing without pre-heating. German industrial processors around Hamburg and Cologne anchor procurement volumes for this grade. Liquid leads volumes today; powder is gaining share fastest.
- Powder:Addresses dust-free handling requirements in industrial bakery premix operations and dry-mix applications where storage stability matters. Spray-dried formats from Southeast Asian producers serve Indian processed food exporters seeking BIS IS standard compliance documentation.
- Emulsion:Pre-dispersed water-in-oil systems reduce energy inputs for small-batch confectionery houses lacking high-shear mixing infrastructure.
- Gel:Concentrated semi-solid formats target artisan chocolate makers requiring precise manual incorporation without flow measurement systems.
Liquid formats command the installed base; powder grades are climbing the fastest as dry-mix bakery applications expand.
Application:
Cost tier stratification places premium confectionery formulations against commodity baking segments with divergent purity tolerance thresholds.
- Confectionery:Mature revenue pool with established EFSA Regulation (EC) No 1333/2008 compliance protocols for 3-MCPD thresholds below 50 ppm. Belgian and Swiss mid-tier houses drive enzymatic interesterification grade adoption to reduce tempering energy inputs.
- Baking:Industrial premix operations in Germany and the Netherlands favor powder-grade PGPR for dust-free handling, with REACH Annex XIV documentation requirements forcing mass-balance certification from suppliers.
- Dairy:Plant-based beverage manufacturers adopt PGPR to replicate dairy lipid mouthfeel in oat and almond formulations, opening volume channels outside traditional chocolate applications.
- Sauces:Marginal segment serving emulsified dressing producers where PGPR competes with lecithin on price-performance positioning.
Confectionery retains the largest revenue footprint; dairy alternatives show the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through specialized purchasing cooperatives or direct manufacturer relationships with embedded technical service.
- Food Manufacturers:Industrial chocolate processors in Germany and Italy centralize emulsifier procurement through purchasing cooperatives aggregating demand across multiple manufacturing sites.
- Cosmetic Companies:Formulators leverage PGPR for water-in-oil emulsion stability in lipid-based personal care, with REACH compliance documentation driving supplier consolidation.
- Pharmaceutical Firms:Excipient-grade requirements for oral lipid formulations impose purity specifications exceeding food-grade thresholds.
- Nutraceutical Brands:Softgel and lipid-based supplement manufacturers represent emerging demand as delivery format diversification accelerates.
Food manufacturers dominate current offtake; nutraceutical brands are expanding most quickly as supplement format innovation accelerates.
Distribution Channel:
Supply concentration patterns distinguish direct relationships with integrated oleochemicals platforms from fragmented distributor networks serving smaller accounts.
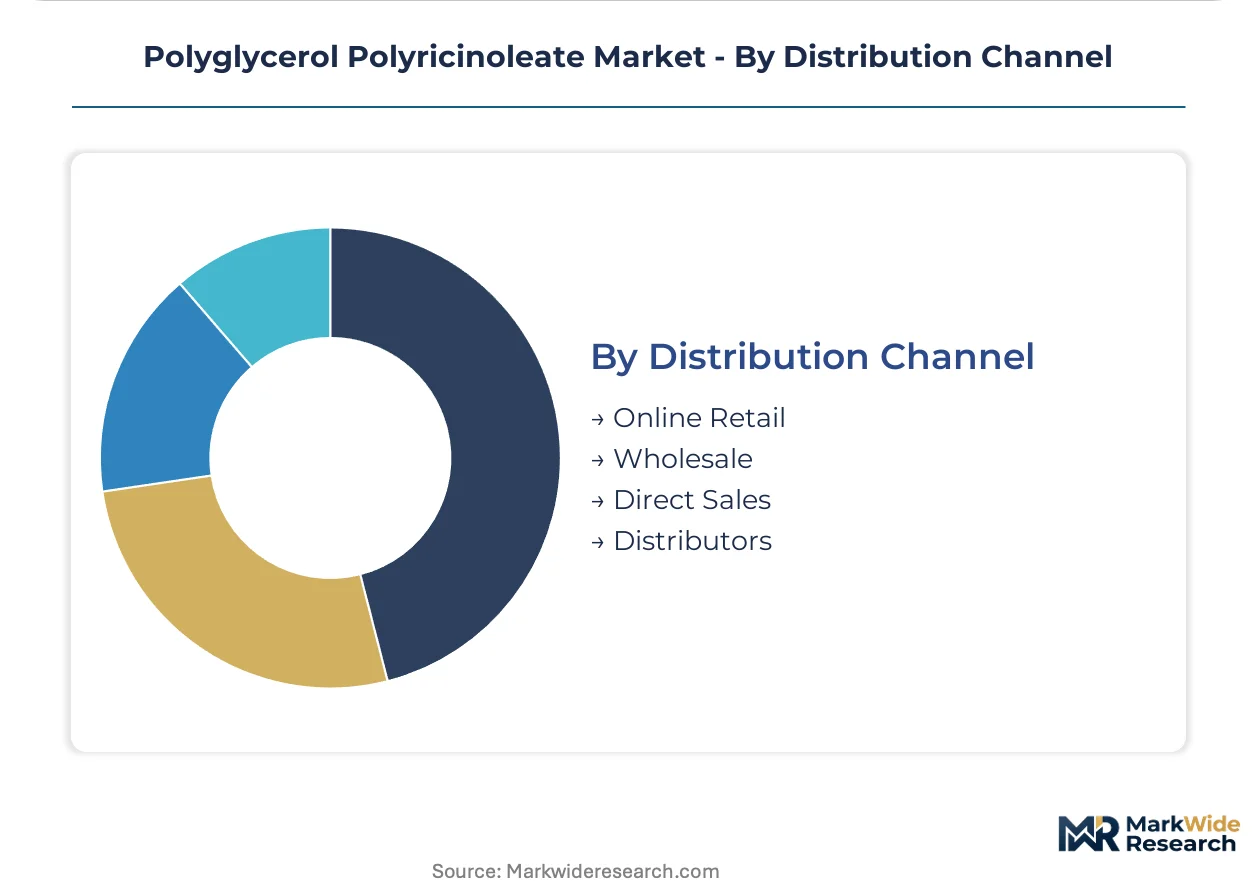
- Direct Sales:Large confectionery groups in France negotiate separate contracts for formulation support, regulatory documentation, and volume commitments outside distributor markups.
- Distributors:Regional blenders lacking REACH compliance infrastructure rely on distributor technical service for documentation support.
- Wholesale:Bulk liquid shipments to industrial chocolate processing clusters flow through established chemical distribution networks with dedicated food-grade handling capabilities.
- Online Retail:Artisan and small-batch producers source gel and powder formats through specialized ingredient marketplaces with certificate-of-analysis transparency.
Direct sales capture the highest volume concentration; online retail is gaining share fastest among artisan segment entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial chocolate processing first scaled in European manufacturing clusters during the mid-20th century, establishing formulation protocols that now govern emulsifier procurement worldwide. Today, PGPR demand concentrates in specific national markets where confectionery production, regulatory stringency, and supply chain infrastructure intersect.
Germany
Industrial chocolate processing clusters around Hamburg and Cologne generate contract-manufacturing demand that anchors European PGPR procurement volumes. EFSA's Regulation (EC) No 1333/2008 compliance mandates drive qualification requirements for suppliers serving German confectionery exporters. The North Rhine-Westphalia region houses automated tempering lines that specify narrow-viscosity PGPR grades for continuous-process integration.
United States
FDA governance under 21 CFR 172.854 shapes acceptable purity thresholds for chocolate and cocoa product applications, with major confectionery groups centralizing emulsifier procurement through specialized purchasing cooperatives. The Midwest industrial corridor, particularly Illinois and Pennsylvania manufacturing zones, processes bulk liquid PGPR shipments through established food-grade chemical distribution networks. Domestic formulators face competitive pressure from soy and sunflower lecithin substitutes that create pricing ceilings in cost-sensitive segments.
India
BIS enforces additive quality standards through IS specifications that affect import clearance and domestic manufacturing compliance for suppliers targeting processed food exporters. Over 85% of global castor oil originates from Indian agricultural zones, exposing PGPR producers to monsoon variability and port logistics disruptions. Gujarat and Maharashtra processing facilities supply raw material derivatives to both domestic emulsifier manufacturers and Southeast Asian production bases.
Belgium
Mid-tier confectionery houses in Belgian manufacturing zones drive adoption of enzymatic interesterification grades to reduce tempering energy inputs. REACH Annex XIV authorization requirements for castor oil derivatives compel formulators to document supply chain substance volumes and exposure scenarios. The Flanders region maintains specialized emulsifier blending capabilities that combine PGPR with complementary stabilizers for premium chocolate applications.
Switzerland
Swissmedic and federal food safety frameworks impose excipient-grade purity specifications that exceed standard food-grade thresholds for pharmaceutical and nutraceutical applications. Lake Geneva and Zurich manufacturing corridors serve as formulation development centers where precision-grade PGPR variants with specified hydroxyl values undergo application testing. Artisan chocolate makers in Swiss alpine regions source concentrated semi-solid gel formats requiring precise manual incorporation.
Polyglycerol Polyricinoleate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and technical service capabilities, with EFSA-qualified suppliers capturing volume consolidation benefits as marginal producers face disqualification. The vendor base stratifies into three tiers: integrated oleochemicals platforms with captive raw material supply, specialized emulsifier blenders with application-specific formulation expertise, and regional distributors lacking compliance documentation infrastructure. Dominant competitive moves include backward integration into palm oil and castor oil derivatives to control input costs, and strategic partnerships with industrial chocolate processors for co-development of low-viscosity grades compatible with legacy tempering equipment.
Within the integrated platform tier, BASF SE leverages its Ludwigshafen oleochemicals complex to sustain supply security for high-volume confectionery customers, while KLK Oleo occupies a position anchored in Southeast Asian palm oil derivative production. Palsgaard A/S exemplifies the specialized blender archetype, with Danish technical service capabilities supporting emulsifier blends that combine PGPR with complementary stabilizers for precision formulation requirements.
| Leading Market Players |
|---|
| BASF SE |
| Estelle Chemicals Pvt. Ltd. |
| Cargill |
| KLK Oleo |
| DuPont |
| Palsgaard A/S |
| Croda International Plc |
| Wilmar International Limited |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Chromatography specialists concentrated in German industrial zones widen pricing-tier spreads as EFSA-mandated sub-50 ppm 3-MCPD validation requirements inflate labor costs for premium-grade certification against commodity-grade alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-qualified grades with full mass-balance documentation from regional blenders lacking REACH Annex XIV infrastructure. Price differentiation rests on certification depth and volume scale, with automated tempering line compatibility commanding premiums. Cost compression in economy tiers intensifies because soy and sunflower lecithin substitutes establish pricing ceilings. Industrial chocolate processors in Germany exhibit lowest price sensitivity due to formulation lock-in, while Indian processed food exporters face acute cost pressure.
Supply Chain Analysis
EFSA qualification gates consolidate supply relationships with certified producers capable of sub-50 ppm 3-MCPD validation, marginalizing regional blenders. Geographic concentration centers on India, Brazil, and Germany, with castor bean cultivation anchored in Indian and Brazilian agricultural zones and processing clusters around Hamburg and Cologne. Raw material dependencies draw from polymerized glycerol, castor oil fatty acids, and palm oil derivatives. Single-source vulnerability in Indian castor bean supply exposes producers to monsoon variability. Distribution runs through direct manufacturer relationships for large confectionery groups and specialized chemical distribution networks for bulk liquid shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity as EFSA's ongoing re-evaluation of 3-MCPD thresholds under Regulation (EC) No 1333/2008 forces process investments that favor certified incumbents over marginal suppliers.
For Market Incumbents: To counter enzymatic interesterification technology displacement, BASF SE and Palsgaard A/S should deepen captive supply of castor oil derivatives through backward integration into Indian agricultural processing zones. Certification investment in REACH Annex XIV documentation infrastructure remains essential to defend volume relationships with German industrial chocolate processors. For New Entrants and Emerging Players: Launch via online retail channels serving artisan chocolate makers in Swiss alpine regions and Belgian mid-tier houses seeking gel-format precision grades. Plant-based dairy alternatives present the most penetrable white-space, with oat and almond beverage manufacturers adopting PGPR to replicate dairy lipid mouthfeel without established supplier relationships. For Investors and Strategic Acquirers: Integrated oleochemicals platforms are the most active acquirer in this space, seeking specialized emulsifier blenders with EFSA-qualified production infrastructure. Targets exhibiting backward integration into castor oil derivatives and enzymatic interesterification capabilities demonstrate superior long-term viability across the projection horizon. Monitor EFSA's anticipated glycidyl ester threshold reductions as the critical inflection signal for forced process revalidation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Derivatives | KLK Oleo's palm oil derivative control demonstrates upstream cost management across Southeast Asian production bases. |
| EFSA Certification Investment | Sub-50 ppm 3-MCPD validation infrastructure disqualifies marginal suppliers and consolidates volume with qualified producers. |
| Enzymatic Interesterification Adoption | Belgian and Swiss mid-tier houses reduce tempering energy inputs through precision esterification grades. |
| Plant-Based Dairy Formulation Partnerships | Oat and almond beverage manufacturers open volume channels outside traditional confectionery applications. |
| Direct Sales Channel Expansion | French and Italian confectionery groups centralize procurement through cooperatives that compress distributor margins. |
Research Methodology
Multiple input streams — technical interviews with emulsifier R&D directors, procurement leads at industrial chocolate processors, regulatory affairs specialists, and distribution channel partners — were reconciled against secondary validation from EFSA additive safety evaluations, FDA 21 CFR 172.854 filings, BIS IS specifications, customs trade data, and SEC disclosures from listed oleochemicals platforms. Bottom-up volume modeling across liquid, powder, emulsion, and gel product types was triangulated with top-down value aggregation.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation dimensions spanning product format, application category, end-user type, and distribution channel. CAGRs were derived through iterative convergence of demand-side uptake curves and supply-side capacity expansion timelines. Castor oil price volatility indices and EFSA regulatory milestone schedules served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including force majeure disruptions to Indian monsoon-dependent castor bean harvests and unilateral regulatory acceleration beyond published EFSA consultation timelines. Forecasts reflect documented assumptions regarding enzymatic interesterification adoption rates and tempering line retrofit completion schedules. A model refresh is warranted upon material change in EFSA's final glycidyl ester threshold determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market