
 Trimellitic Anhydride Market | 2026-2036
Trimellitic Anhydride Market Size, Share, and Industry Trends Forecast 2026-2036
Trimellitic Anhydride Market Intelligence
A shift from single-source to multi-source procurement for trimellitic anhydride is expanding among downstream converters seeking supply chain resilience. Polynt SpA leverages its specialized production capabilities to serve niche, high-purity applications. In contrast, BASF SE competes on a global scale with a broad portfolio of chemical intermediates. Jiangsu Zhengdan Chemical anchors a significant portion of Asia's production capacity, influencing regional supply dynamics.
Trimellitic anhydride is a solid aromatic anhydride chemical intermediate. It is primarily manufactured through the liquid-phase air oxidation of pseudocumene and serves as a critical building block for high-performance polymers. The plasticizers application segment constitutes the largest share of consumption, driven by its use in heat-resistant PVC insulation. Within product types, high-purity grades are gaining traction for demanding coatings and electronics applications, offering higher margins than industrial grade material.
Market access is governed by stringent chemical control regulations, including the European Union's REACH and the US EPA's Toxic Substances Control Act (TSCA). These frameworks, along with China's GB standards, mandate comprehensive substance registration and define acceptable impurity profiles for commercial use. Producers must now decide between expanding capacity for commoditized industrial grades or investing in purification technology to capture value in specialized segments.
Market Dynamics
The market's central dynamic is the regulatory-driven displacement of traditional phthalate plasticizers. This substitution, mandated by frameworks like the EU's REACH, creates dedicated demand for trimellitic anhydride in high-performance applications, particularly for heat-resistant wire and cable insulation.
Growth Catalysts
- Phthalate Substitution Mandates:Regulations such as the EU's REACH restrict the use of certain phthalates in consumer and industrial goods, directly compelling converters to adopt trimellitate-based plasticizers for compliance, especially in PVC applications.
- Automotive Electrification:The transition to electric vehicles requires high-temperature resistant wiring and cable insulation to handle increased thermal loads, boosting consumption of trimellitic anhydride as a key precursor for suitable plasticizers.
- High-Purity Grade Development:The creation of higher purity grades of trimellitic anhydride opens new, high-margin opportunities in demanding applications like powder coatings, insulation enamels, and specialized polymers for the electronics industry.
Market Restraints
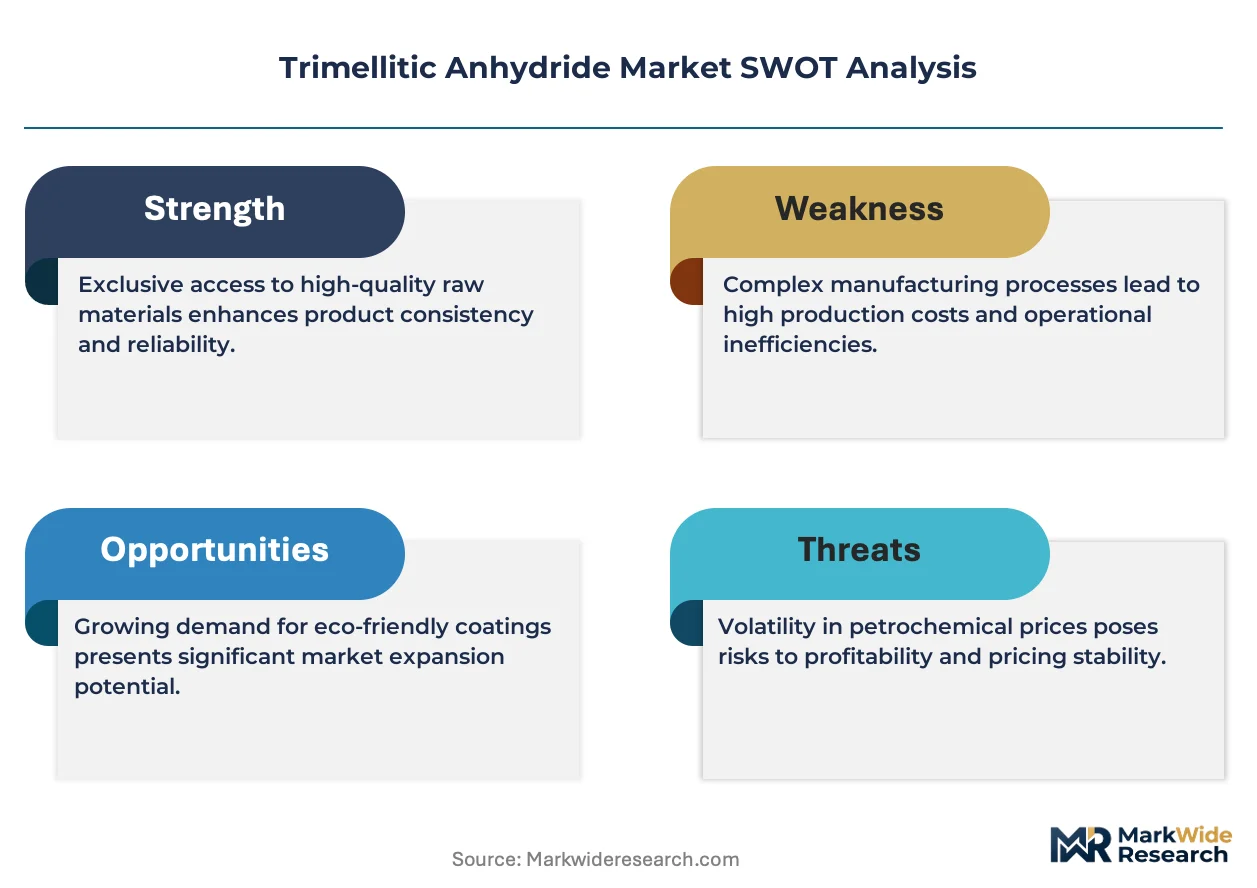
- Feedstock Price Volatility:The market is sensitive to price fluctuations of its primary raw material, pseudocumene, a petroleum derivative. Unpredictable feedstock costs can compress producer margins and create price instability for downstream customers.
- Geographic Production Concentration:A significant portion of global production capacity is centered in China. This concentration exposes the global supply chain to risks associated with regional policy shifts, logistical disruptions, or trade tensions.
- Substitution by Alternative Chemistries:In some non-PVC polymer systems, other high-performance materials, such as certain aliphatic polyesters or other aromatic anhydrides, can compete on a performance-cost basis, limiting market penetration in those niches.
Strategic Opportunities
- Bio-Based Feedstock Development:Research into producing trimellitic acid and its anhydride from renewable, bio-based sources presents a long-term opportunity to reduce dependence on fossil fuels and appeal to customers with sustainability mandates.
- Expansion in Southeast Asia:As electronics and automotive manufacturing expands in countries like Vietnam and Thailand, establishing supply channels and local partnerships can capture new demand outside of established Chinese and South Korean markets.
- Advanced Composite Formulations:There is an opportunity to incorporate trimellitic anhydride derivatives as curing agents or modifiers in epoxy resins and other composites for lightweighting applications in the aerospace and defense sectors.
Industry Challenges
- Capital-Intensive Capacity Expansion:Building new liquid-phase oxidation and purification facilities requires significant capital investment and long lead times, making it difficult for producers to respond quickly to sudden demand surges.
- Complex Regulatory Compliance:Producers selling into multiple regions face the challenge of managing and maintaining separate, costly substance registrations and compliance data for diverse chemical control laws like REACH, TSCA, and others.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimellitic Anhydride Market |
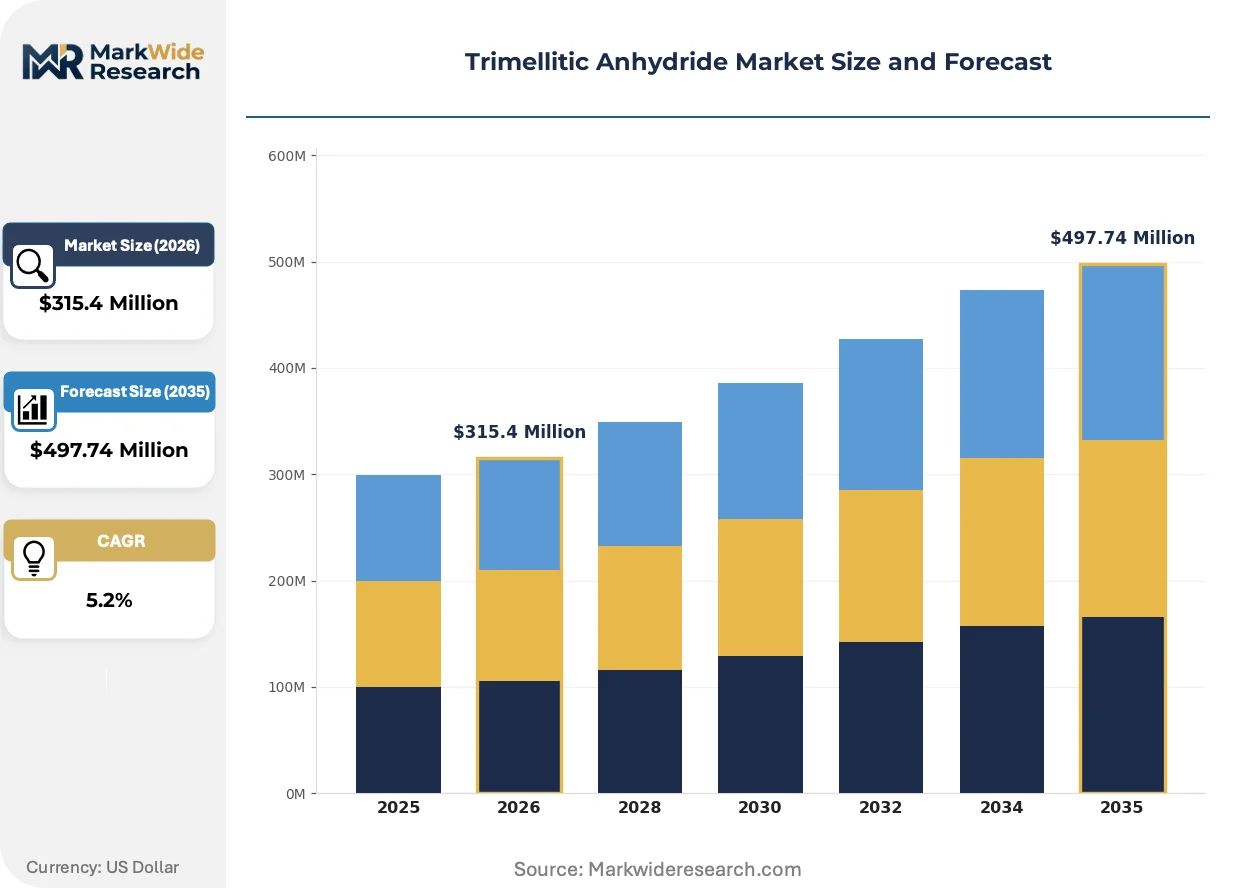
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $497.74 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Commercial Grade, High Purity, Crude Application: Plasticizers, Coatings, Adhesives, Sealants End Use Industry: Automotive, Construction, Electronics, Textiles Packaging Type: Drums, Totes, Bulk Containers, Bags |
| Companies Covered | Polynt SpA, BASF SE, Jiangsu Zhengdan Chemical, The Dow Chemical Company, Anhui Taida New Materials Co., Ltd, Wuxi Baichuan Chemical, Mitsubishi Gas Chemical Company Inc, Lonza Group Ltd., Ineos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimellitic Anhydride Market Strategic Shifts & Innovations
Innovation is focused on two fronts: enhancing process efficiency to manage costs and developing higher-purity grades to access more valuable end markets. This bifurcated approach reflects the material's dual role as both a specialty intermediate and a high-volume performance chemical.
Advanced process control software is a key technology being adopted in production. These systems use real-time sensor data from oxidation reactors to maintain optimal reaction conditions. Producers of high-purity trimellitic anhydride are the primary adopters to ensure consistent quality. This technology is automating the continuous monitoring of impurity profiles, thereby reducing batch-to-batch variability and the need for extensive post-production testing.
China's "dual carbon goals" policy is a significant regulatory force impacting the chemical industry. The policy pressures energy-intensive manufacturing processes, including the air oxidation of pseudocumene, to improve efficiency and lower their carbon footprint. Producers in major chemical hubs like the Jiangsu province are now required to invest in greener process technologies or risk facing government-mandated production limitations.
A notable behavioral change is the move by converters away from single-supplier contracts for critical intermediates. This diversification of the supplier base is disrupting traditional, long-term relationships in favor of a more resilient, multi-vendor portfolio management strategy. This trend is most pronounced among European and North American wire and cable manufacturers seeking to mitigate supply chain risks associated with geographic concentration.
Trimellitic Anhydride Market Segmentation
The segmentation analysis for trimellitic anhydride delineates how this chemical intermediate serves a spectrum of industrial needs, from high-volume commodity applications to highly specialized, performance-driven formulations. Understanding these distinct segments allows producers to tailor product offerings and navigate the complex regulatory and technological requirements of various end markets.
Product Type:
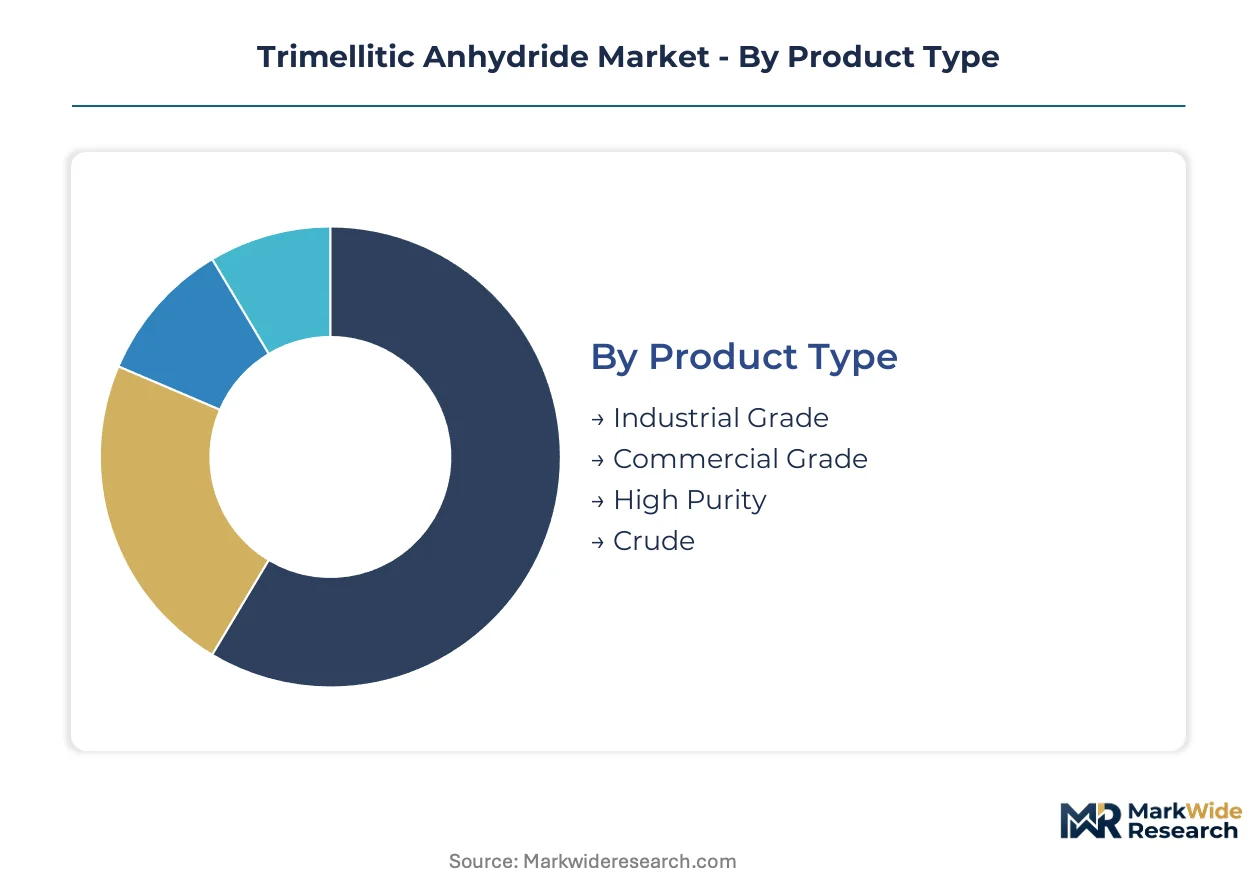
The product type segmentation reveals how trimellitic anhydride grades integrate into diverse chemical formulations, from basic intermediates to highly specialized performance materials.
- High Purity:This grade of trimellitic anhydride contains minimal impurities, making it suitable for demanding applications in electronics and high-performance coatings where consistent quality is paramount. Demand concentrates in regions with advanced manufacturing capabilities, driven by the need for superior electrical insulation and thermal stability.
- Industrial Grade:Industrial grade trimellitic anhydride serves as a foundational building block for high-volume plasticizer production, particularly for PVC compounds used in general-purpose wire and cable insulation. Consumption is widespread, influenced by the global construction and automotive sectors' ongoing need for cost-effective material solutions.
- Commercial Grade:Commercial grade trimellitic anhydride offers a balance of purity and cost-effectiveness, finding use in various intermediate applications beyond the most stringent requirements.
- Crude:Crude trimellitic anhydride represents the least refined form, typically requiring further processing before it can be incorporated into most commercial products.
Volume placements concentrate in Industrial Grade material; the faster expansion belongs to High Purity grades.
Application:
Application segments delineate the primary end-uses for trimellitic anhydride, reflecting varied consumption volumes and performance requirements across industries.
- Plasticizers:Trimellitic anhydride is a critical precursor for non-phthalate plasticizers, especially trimellitates, which impart heat resistance and flexibility to PVC, vital for wire and cable insulation. The largest share of consumption for plasticizers occurs in industrial and automotive applications, propelled by stringent regulatory mandates against traditional phthalates.
- Coatings:In coatings, trimellitic anhydride acts as a curing agent or intermediate for high-performance resins, particularly in powder coatings and insulation enamels, offering enhanced durability and chemical resistance. Demand for advanced coatings is concentrating in the electronics and automotive sectors, driven by the need for protective layers in complex systems.
- Adhesives:Trimellitic anhydride derivatives contribute to the formulation of specialty adhesives, improving their thermal stability and bonding strength in demanding environments.
- Sealants:The chemical is utilized in certain sealant formulations to enhance their performance characteristics, including adhesion and resistance to elevated temperatures.
Plasticizers lead in consumption volume, while specialized coatings applications exhibit significant growth potential.
End Use Industry:
End-use industry segmentation highlights the diverse sectors leveraging trimellitic anhydride's properties, each with distinct material specifications and regulatory landscapes.
- Automotive:The automotive sector uses trimellitic anhydride in plasticizers for high-temperature resistant wiring and cable insulation, essential for electric vehicles and modern engine compartments. Regulatory shifts towards non-phthalate plasticizers under frameworks like REACH directly influence material selection in vehicle manufacturing across Europe and Asia.
- Electronics:In electronics, trimellitic anhydride is crucial for high-purity coatings and insulation enamels, protecting sensitive components and ensuring reliable performance in consumer devices and industrial equipment. The miniaturization and increased power demands of electronic devices drive the need for superior insulating materials.
- Construction:The construction industry incorporates trimellitic anhydride derivatives into PVC products for wiring, flooring, and piping, benefiting from improved durability and heat resistance.
- Textiles:Trimellitic anhydride finds niche applications in textile treatments and coatings, contributing to the performance characteristics of specialized fabrics.
The automotive sector drives substantial demand for high-performance plasticizers, and electronics manufacturing represents a rapidly expanding consumption area.
Packaging Type:
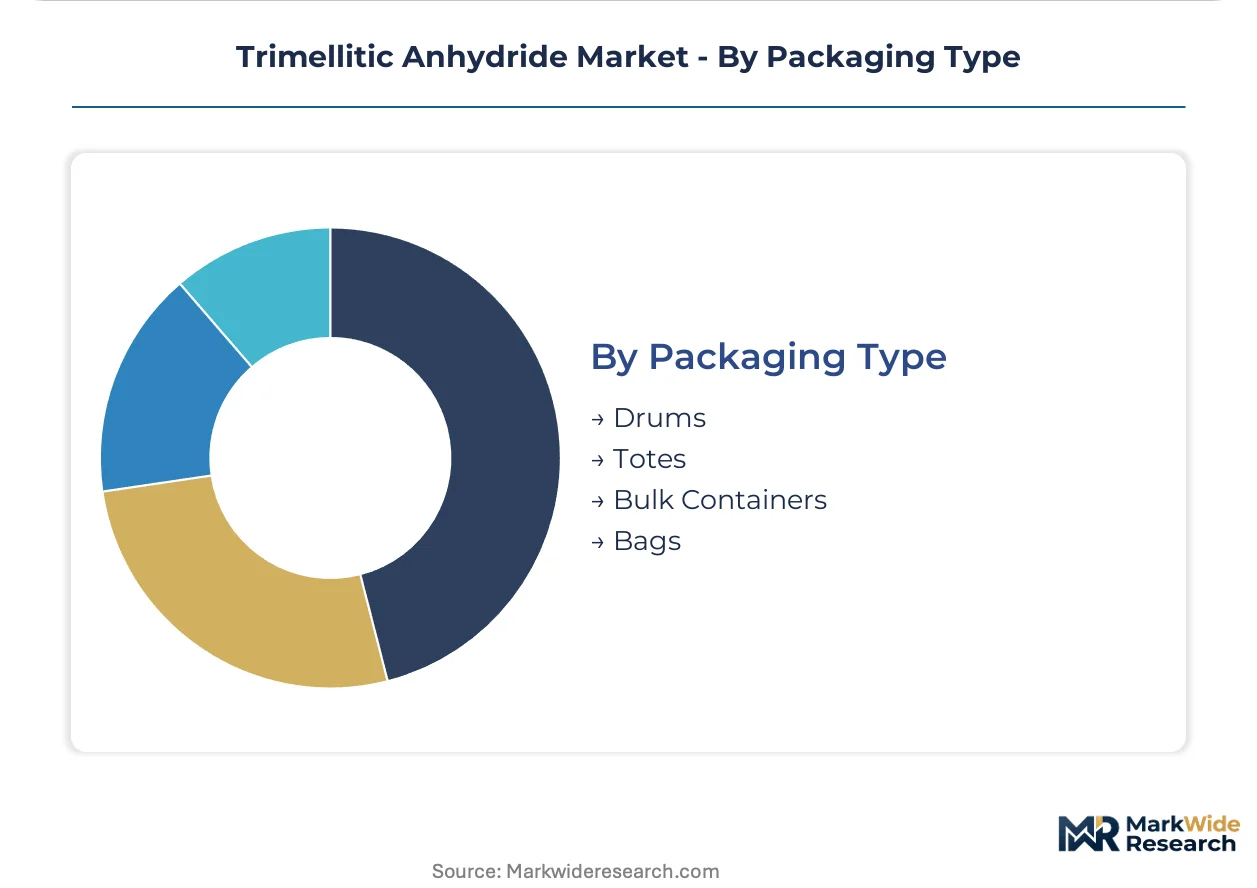
Packaging type segmentation reflects the logistical requirements for trimellitic anhydride, influenced by shipment volume, material handling, and transport efficiency.
- Bulk Containers:Bulk containers, such as ISO tanks or large industrial containers, are employed for high-volume shipments to large-scale industrial users and chemical manufacturers. This packaging type optimizes transport costs for major consumers across China and Europe.
- Drums:Drums provide a versatile packaging solution for trimellitic anhydride, accommodating medium-volume orders for diverse manufacturers and distributors globally. Drums are common for chemical intermediates due to their robust construction and ease of handling.
- Totes:Intermediate bulk containers (IBCs), often referred to as totes, offer an efficient solution for quantities larger than drums but smaller than bulk containers.
- Bags:Bags are typically used for smaller quantities or specific grades of powdered trimellitic anhydride, suitable for specialized applications or laboratory use.
Bulk containers facilitate high-volume industrial deliveries, while drums offer versatile transport for medium-scale requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market's production gravity centers on specialized chemical hubs, driving regional consumption patterns. Pseudocumene, a key petroleum derivative, underpins trimellitic anhydride synthesis. These production zones dictate supply dynamics for critical downstream industries, particularly in Asia.
China
China's robust electronics manufacturing fuels significant demand for high-purity trimellitic anhydride in insulation enamels. The country's GB standards mandate specific impurity profiles for chemical intermediates. Major chemical clusters in Jiangsu province are investing in advanced purification technologies to meet these requirements.
South Korea
South Korea's automotive electrification initiatives boost consumption of trimellitate-based plasticizers for high-temperature wiring. The Ministry of Environment manages chemical substance registrations, influencing market access for new materials. Ulsan's industrial complex concentrates specialized chemical production for regional electronics and automotive sectors.
Germany
German automotive manufacturers increasingly adopt non-phthalate plasticizers for vehicle interiors and wire insulation. The European Union's REACH regulation rigorously controls chemical substance use, impacting product formulations across the continent. Chemical parks like Ludwigshafen are centers for advanced polymer development and material innovation.
United States
Demand in the United States stems from high-performance coatings for infrastructure and electronics applications. The US EPA's Toxic Substances Control Act (TSCA) governs chemical commercialization and substance reviews, shaping market entry. Gulf Coast chemical producers are expanding capacity for specialized intermediates to serve diverse industries.
India
India's expanding construction sector drives consumption of industrial-grade trimellitic anhydride for PVC applications in wiring and piping. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical products, ensuring material consistency. Gujarat's chemical manufacturing belt is a growing hub for plasticizer production and related intermediates.
Trimellitic Anhydride Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the need to meet rising demand for non-phthalate plasticizers in critical applications like wire and cable insulation. The market exhibits a tiered structure, with a few large integrated chemical producers alongside numerous specialized intermediate manufacturers serving specific end-use industries. Strategic archetypes include global chemical conglomerates offering a wide range of products, and regional specialists focusing on niche, high-purity applications. Portfolio diversification into higher-purity grades and geographic expansion into emerging Asian markets are primary competitive moves observed.
Within the global chemical conglomerate archetype, BASF SE exemplifies a broad portfolio strategy, leveraging extensive research and development alongside global distribution networks for diverse chemical intermediates. Polynt SpA, a European specialist, occupies a position focused on high-purity applications, particularly for demanding coatings and electronics segments across Europe and North America. Meanwhile, Jiangsu Zhengdan Chemical, a key Asian producer, anchors a significant portion of regional trimellitic anhydride capacity, serving the electronics and automotive sectors across China and South Korea, often at a larger industrial grade scale.
| Leading Market Players |
|---|
| Polynt SpA |
| BASF SE |
| Jiangsu Zhengdan Chemical |
| The Dow Chemical Company |
| Anhui Taida New Materials Co., Ltd |
| Wuxi Baichuan Chemical |
| Mitsubishi Gas Chemical Company Inc |
| Lonza Group Ltd. |
| Ineos Group |
| Others |
Cost & Logistics Intelligence
Pseudocumene price volatility, a key petroleum derivative, directly impacts trimellitic anhydride producer margins and subsequently influences pricing for downstream plasticizers used in wire and cable insulation. Unpredictable feedstock costs create instability across the entire value chain.
Pricing Analysis
Service-level agreements bundled with high-purity trimellitic anhydride ensure consistent quality and technical support for demanding electronics applications. The dominant pricing model is contract-based long-term offtake for strategic buyers, complemented by commodity spot pricing for industrial grades. Price differentiation arises from quality grade, with high-purity material commanding a premium, and volume scale. Pricing softness stems from overcapacity in industrial grades, particularly from Chinese producers. Construction sector buyers are highly price-sensitive for industrial-grade PVC applications, while electronics manufacturers prioritize consistent quality for high-purity material.
Supply Chain Analysis
Regional distribution centers in Europe and Asia facilitate the timely delivery of trimellitic anhydride to downstream converters. Geographic supply concentration primarily centers in China and South Korea, with some specialized production in Germany. The industry draws from pseudocumene, a petroleum derivative, as its primary raw material. Geographic concentration in China exposes the global supply chain to risks associated with regional policy shifts or logistical disruptions. Distribution runs through direct sales to large industrial converters and via specialized chemical distributors for smaller, niche requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trimellitic anhydride market is a consolidation play, driven by stringent regulatory compliance requirements under frameworks like REACH and TSCA, which disproportionately burden smaller producers. This pressure forces weaker players out or into acquisition by larger entities.
For Market Incumbents: Hedge against feedstock price volatility by securing long-term pseudocumene supply contracts with integrated petrochemical producers. Incumbents should invest in advanced purification technology to capture value in high-purity segments, mitigating margin pressure from commoditized industrial grades. This strategy addresses the threat of regulatory shifts favoring higher-grade materials and competition from lower-cost industrial producers. Expanding capacity in specialized segments like electronics insulation offers a defensive play.
For New Entrants and Emerging Players: The EU's REACH regulation in Europe opens a window for new entrants offering non-phthalate compliant solutions and bio-based trimellitic anhydride alternatives. Emerging players can target specialized coatings for electric vehicle components, leveraging sustainability mandates and performance needs. The most penetrable segment lies in niche high-purity applications with a strong sustainability story. A strong go-to-market angle involves partnering with downstream formulators for co-development of advanced materials.
For Investors and Strategic Acquirers: Increased M&A activity among mid-sized specialty chemical manufacturers is the leading indicator that consolidation is accelerating in the trimellitic anhydride market. This market offers stable, essential chemical intermediate demand over a five-to-ten-year window, driven by regulatory tailwinds and electrification trends. Acquisition targets should be regional specialists with advanced purification technology or proprietary bio-based feedstock capabilities. A specific signal to watch is significant investment announcements in pseudocumene production outside traditional Asian hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Meets demand from electronics and automotive sectors requiring superior insulation properties. |
| Bio-Based Feedstock Research & Development | Reduces reliance on petroleum derivatives and appeals to customers with sustainability mandates. |
| Geographic Expansion into Southeast Asia | Captures new demand from expanding electronics and automotive manufacturing bases in the region. |
| Long-Term Pseudocumene Supply Contracts | Mitigates feedstock price volatility and ensures supply stability for production operations. |
| Advanced Process Control Software Adoption | Enhances production efficiency and ensures consistent quality for high-purity material output. |
Research Approach
Independent corroboration across industry association reports, customs trade data, and company financial filings underwrites the qualitative findings. Primary interviews with plant managers, procurement leads at downstream OEMs, and R&D directors provided critical insights. Secondary validation incorporated EU REACH registration data, US EPA TSCA filings, and China GB standards. This approach ensured a robust bottom-up and top-down triangulation of market intelligence.
Rate-of-change decomposition isolated the independent contributions of key market drivers and restraints across the analysis window. Segmentation dimensions modeled included grade tier, end-use industry, packaging format, and regional production hub. Compound Annual Growth Rates were projected by analyzing historical consumption trends and anticipated technological shifts. Pseudocumene supply forecasts and electric vehicle production targets served as critical industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for bio-based feedstock development would alter the outlook. Forecasts reflect assumptions concerning future regulatory landscapes and macroeconomic conditions. Geopolitical events impacting feedstock supply or unforeseen regulatory changes present key risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Global Fermentation Chemicals Market