
 Colored Hard PU Foam Market | 2026-2036
Colored Hard PU Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Colored Hard PU Foam Market Insights
Germany is tilting toward expanded polyurethane compounding capacity as OEMs localize interior material supply. BASF SE leverages its Ludwigshafen integrated site to sustain captive isocyanate and polyol flows into colored rigid foam grades. Huntsman Corporation anchors North American demand through specialized MDI formulations tailored to automotive hard foam specifications. Covestro AG differentiates via high-colorfastness pigment dispersion technology for exterior-exposed PU components.
Colored hard PU foam denotes rigid polyurethane systems with integrated pigment packages, typically formulated with densities between 35 and 200 kg/m³ through reaction injection molding or pour-in-place processing, serving structural insulation, impact absorption, and aesthetic surface functions in manufactured goods. Rigid foam dominates current value flows due to its entrenched role in automotive interior substrates and appliance insulation, while specialty foam captures expanding margin pools as medical device and aerospace buyers specify certified color-stable grades. The furniture application segment competes primarily on cost-engineered formulations, whereas sports equipment represents the fastest-growing demand channel as ski and bicycle manufacturers adopt pigmented structural cores.
REACH and RoHS frameworks in Europe restrict phthalate-based colorants and heavy-metal pigments in PU foam articles, compelling reformulation toward compliant inorganic and organic pigment systems. EPA oversight in the United States governs methylene chloride and flame-retardant loading in rigid foam production, shaping plant-level chemical handling investments. Stakeholders must monitor pending F-Gas Regulation amendments in Europe and corresponding state-level hydrofluorocarbon phase-downs in California, as these determine blowing-agent selection and the cost structure of next-generation colored hard PU foam output.
Market Dynamics
REACH and EPA volatile organic compound limits are forcing polyurethane formulators to rebuild pigment and blowing-agent packages from molecular level upward, compressing legacy product cycles while opening certified-grade premiums.
Growth Catalysts
- Automotive Interior Specification:Dashboard core and door panel designers now mandate pigmented rigid foam for aesthetic integration and structural performance in passenger vehicle programs.
- F-Gas Regulation Amendment Trajectory:Pending European hydrofluorocarbon phase-downs are accelerating next-generation low-GWP blowing-agent adoption across rigid foam production lines.
- Sports Equipment Structural Core Migration:Ski and bicycle manufacturers specify certified color-stable grades for impact-absorbing structural components in high-performance gear.
Market Restraints
- Isocyanate Input Volatility:MDI and TDI price swings compress margin predictability for colored foam compounders serving cost-sensitive furniture segments.
- German Supply Corridor Concentration:Tier-1 seating and trim supplier clustering in Baden-Württemberg and Bavaria creates geographic single-point vulnerability for just-in-time interior assembly.
- Phthalate Colorant Obsolescence:REACH Annex XVII restrictions on legacy pigment systems force complete formulation rebuilds with compliant inorganic and organic alternatives.
Strategic Opportunities
- Medical Device Certification Gap:Color-stable PU grades meeting ISO 10993 biocompatibility standards command scarcity premiums in surgical positioning and patient support equipment.
- California HFC Phase-Down Acceleration:State-level hydrofluorocarbon restrictions ahead of federal timelines create early-mover advantage for low-GWP foam systems in West Coast appliance manufacturing.
- Aerospace Interior Panel Specification:FAR 25.853 fire-smoke-toxicity compliant pigmented foam grades penetrate aircraft cabin sidewall and overhead bin substrate programs.
Industry Challenges
- Pigment Dispersion Engineering Talent Scarcity:Formulators with expertise in high-colorfastness particle stabilization for exterior-exposed PU components command premium compensation and extended recruitment cycles.
- Multi-Certification Timeline Compression:Simultaneous REACH, RoHS, and FAA fire-safety approvals extend product qualification periods for aerospace and medical device market entry.
- Legacy Pour-In-Place Equipment Retrofit:Existing reaction injection molding installations require capital-intensive modification to handle next-generation low-viscosity pigment packages and alternative blowing agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colored Hard PU Foam Market |
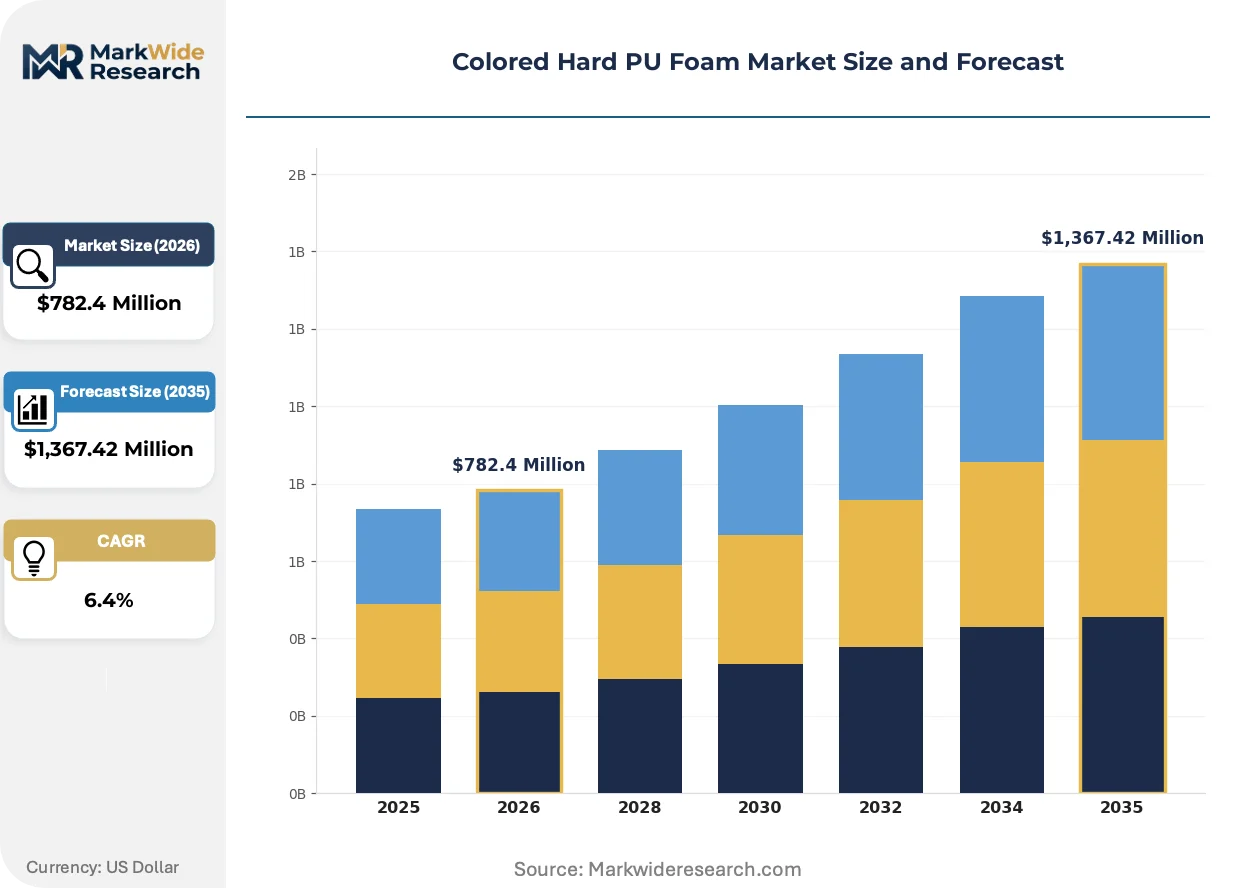
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,367.42 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Semi-Rigid Foam, Specialty Foam Application: Furniture, Automotive Interiors, Packaging, Sports Equipment End User: Manufacturers, Retailers, Wholesalers, Distributors Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Covestro AG, BASF SE, Huntsman Corporation, Carpenter Company, Saint-Gobain Performance Plastics, INOAC Corporation, Rogers Corporation, Stepan Company, Recticel NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colored Hard PU Foam Market Trends and Innovations
Digital formulation platforms and closed-loop color-matching systems are compressing development cycles while regulatory chemistry constraints are rewiring raw-material procurement priorities across the value chain.
Water-blown and liquid CO2 blowing technologies are virtualizing conventional hydrofluorocarbon-dependent rigid foam production. Appliance insulation manufacturers in Germany and automotive suppliers in Michigan adopt these systems at pilot scale now, with full-line conversion timelines compressing from five-year horizons to eighteen-month execution windows. The technology is virtualizing legacy capital equipment depreciation schedules and forcing premature asset retirement decisions across European production networks.
The F-Gas Regulation amendment pathway through 2030 tightens hydrofluorocarbon quotas for polyurethane blowing agents in structural insulation applications. European foam producers face step-function cost increases for conventional HFC-245fa and HFC-365mfc systems, redirecting R&D spend toward hydrocarbon and hydrofluoroolefin alternatives. Germany's automotive supply corridor responds fastest, with Ludwigshafen and Leverkusen integrated sites already certifying next-generation low-GWP grades for 2027 model-year interior programs.
Specification-driven procurement now dominates automotive and medical device channels, displacing spot-market volume purchasing for colored rigid foam. Tier-1 suppliers in Stuttgart and Munich mandate lot-level color consistency certification and REACH-compliant pigment documentation before contract award, compressing qualified vendor pools to integrated compounders with captive analytical laboratories. This pattern concentrates most visibly in German OEM supply agreements, where just-in-time interior assembly tolerates zero color-lot deviation.
Colored Hard PU Foam Market Segmentation
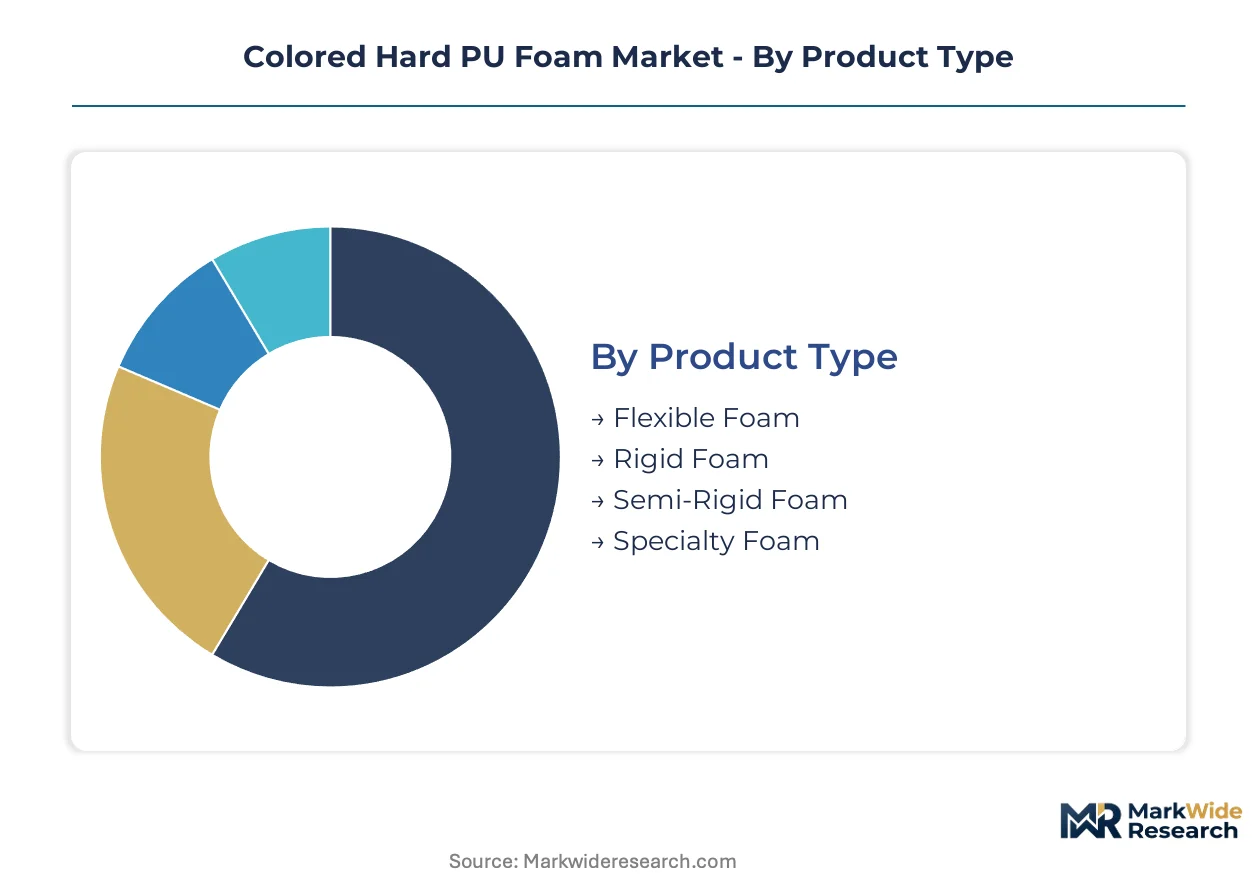
Segmentation in colored hard PU foam reveals how formulation chemistry, application requirements, and channel economics split value capture across the value chain. Each dimension exposes distinct margin profiles and service intensity needs that reshape supplier priorities.
Product Type:
After-sales service intensity varies sharply across foam rigidity grades, with specialty formulations demanding technical support and rigid systems requiring application engineering.
- Rigid Foam:High-density cellular structures between 35 and 200 kg/m³ formulated through reaction injection molding or pour-in-place processing. Demand concentrates in German automotive supply corridors where Tier-1 seating and trim suppliers specify pigmented grades for dashboard cores and door panels, constrained by REACH volatile organic compound limits on polyurethane formulations.
- Specialty Foam:Certified color-stable grades engineered for biocompatibility or fire-smoke-toxicity compliance. Medical device manufacturers in surgical positioning equipment and aerospace cabin interior programs specify these grades, with ISO 10993 and FAR 25.853 certifications extending qualification timelines and compressing qualified vendor pools.
- Flexible Foam:Lower-density cellular systems with elastic recovery properties for cushioning applications.
- Semi-Rigid Foam:Intermediate stiffness grades bridging structural support and impact absorption functions.
By volume, rigid foam leads. By growth pace, specialty foam is ahead.
Application:
Cost tier stratification separates premium specification-driven procurement from spot-market volume purchasing across end-use channels.
- Automotive Interiors:Dashboard core, door panel, and trim substrate applications where OEM designers mandate pigmented rigid foam for aesthetic integration. German supply corridors in Baden-Württemberg and Bavaria concentrate Tier-1 procurement, with just-in-time assembly tolerating zero color-lot deviation and demanding captive analytical laboratory capabilities.
- Sports Equipment:Structural cores for skis, bicycles, and high-performance gear requiring certified color-stable grades with impact absorption specifications. Ski manufacturers in Alpine regions and bicycle producers specify these grades fastest, climbing the fastest as equipment makers migrate from traditional core materials.
- Furniture:Cost-engineered formulations competing primarily on price with compressed margin predictability.
- Packaging:Protective cushioning and display applications with standardized color requirements.
Automotive interiors command highest unit values. Sports equipment shows steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through specification-driven contracts or spot-market volume arrangements.
- Manufacturers:Direct formulation buyers including automotive Tier-1 suppliers, appliance insulation producers, and medical device OEMs. These entities mandate lot-level color consistency certification and REACH-compliant pigment documentation, concentrating supply relationships on integrated compounders with captive isocyanate and polyol flows.
- Distributors:Intermediaries serving fragmented furniture and packaging accounts with lower service intensity and higher price sensitivity.
- Retailers:End-product sellers with limited direct foam procurement involvement.
- Wholesalers:Volume aggregators for standardized grades with minimal technical support requirements.
Manufacturers dominate value capture. Distributors handle greatest transaction volume.
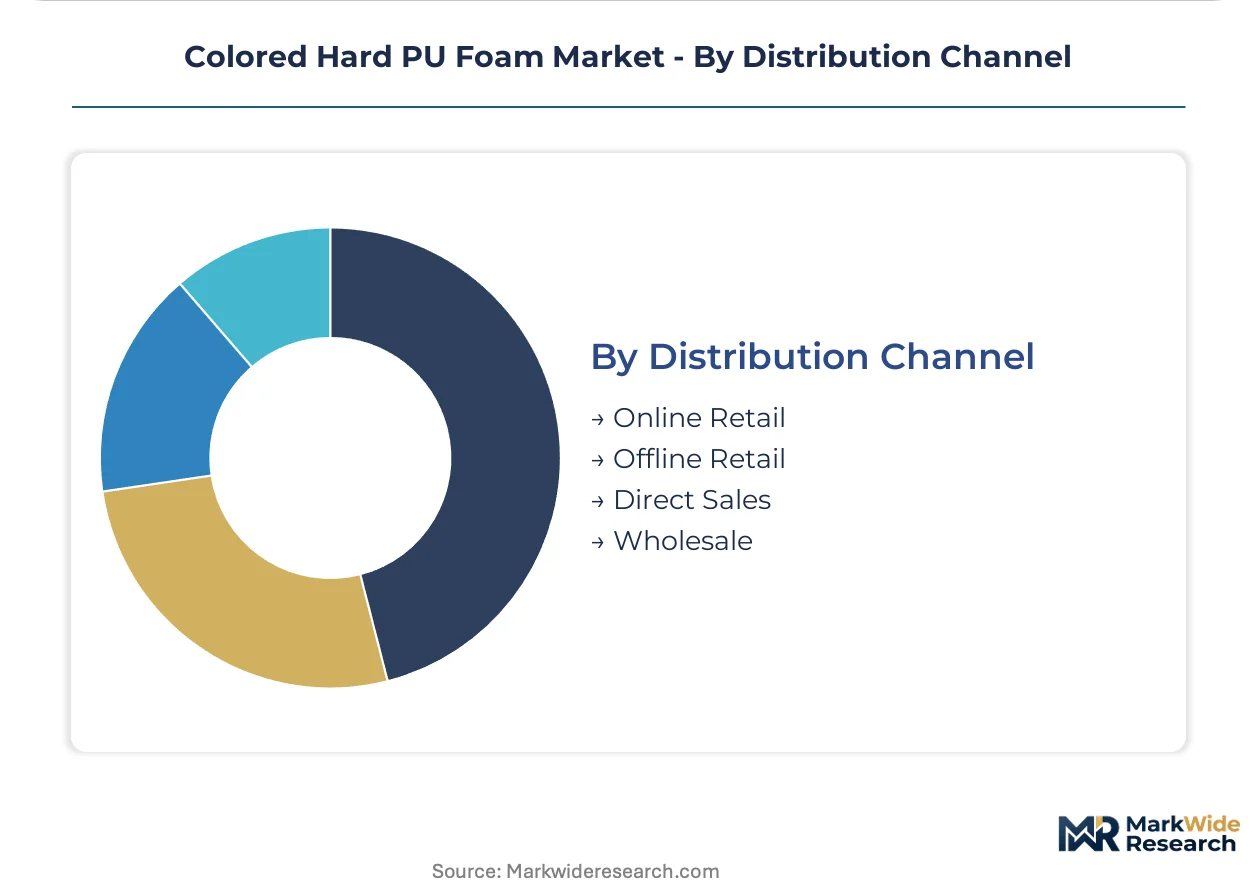
Distribution Channel:
Channel selection reflects the tension between specification complexity and procurement efficiency across customer segments.
- Direct Sales:Technical sales forces embedding with automotive and medical device accounts to manage formulation customization, color-matching protocols, and regulatory documentation. This channel captures premium margins where REACH, RoHS, and FAA approvals require dedicated account engineering.
- Online Retail:Emerging channel for standardized grades and small-batch custom colors with compressed lead times.
- Offline Retail:Traditional branch-based distribution for furniture and packaging segments.
- Wholesale:Volume aggregation for commodity grades with price-driven procurement.
Direct sales delivers highest margins per transaction. Online retail is gaining share fastest among non-specification grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance anchors European demand, with Germany's automotive supply corridor setting the pace for pigmented rigid foam specification across dashboard and interior programs.
Germany
Automotive Tier-1 seating and trim suppliers in Baden-Württemberg and Bavaria specify colored hard PU foam for just-in-time interior assembly. ECHA oversight tightens volatile organic compound limits on polyurethane formulations, compelling reformulation toward compliant pigment systems. Ludwigshafen and Leverkusen integrated chemical sites already certify next-generation low-GWP grades for 2027 model-year programs.
United States
EPA standards govern methylene chloride and flame-retardant loading in rigid foam production, shaping plant-level chemical handling investments. Appliance insulation manufacturers in Michigan adopt water-blown and liquid CO2 blowing technologies at pilot scale. California's state-level hydrofluorocarbon phase-down runs ahead of federal timelines, creating early-mover positioning for low-GWP foam systems in West Coast manufacturing.
China
MIIT oversight of industrial chemical production shapes polyurethane formulation standards for domestic appliance and automotive channels. Dual carbon goals accelerate hydrocarbon and hydrofluoroolefin blowing-agent adoption across rigid foam production lines. Yangtze River Delta chemical clusters concentrate pigmented foam compounding capacity for export-oriented appliance manufacturers.
Japan
METI guidance on fluorinated gas management influences blowing-agent selection in structural insulation applications. Automotive interior designers in Nagoya and Tokyo metropolitan areas specify certified color-stable grades for premium vehicle programs. Kansai region chemical producers develop high-colorfastness pigment dispersion technology for exterior-exposed PU components.
South Korea
MFDS and national chemical safety frameworks restrict heavy-metal pigments in consumer-facing foam articles. Seoul Capital Area appliance manufacturers source REACH-compliant pigmented rigid foam for export-oriented production. Busan-Ulsan industrial corridor hosts specialized MDI formulation capacity tailored to automotive hard foam specifications.
Colored Hard PU Foam Market Competitive Landscape
Capability concentration sits with integrated chemical majors possessing captive isocyanate and polyol flows; scale advantage sits with regional compounders serving cost-sensitive furniture and packaging segments. The vendor base stratifies into three archetypes: integrated chemical majors with backward control over raw material streams, specialized foam compounders with certified-grade portfolios, and regional processors competing on price-engineered formulations. Dominant competitive moves include capacity expansion in low-GWP blowing-agent systems and strategic partnerships bridging pigment dispersion expertise with automotive specification channels.
Among integrated chemical majors, BASF SE and Covestro AG exemplify the capability-driven tier with European headquarters and AG corporate structures anchoring premium-grade supply relationships. Huntsman Corporation occupies a position within the specialized formulation segment, with its corporate designation suggesting North American origins and focused MDI expertise for automotive specifications. These three entities represent distinct competitive archetypes: the integrated chemical major with captive raw material flows, the technology-differentiated compounder with colorfastness specialization, and the application-focused formulator with automotive channel penetration.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Huntsman Corporation |
| Carpenter Company |
| Saint-Gobain Performance Plastics |
| INOAC Corporation |
| Rogers Corporation |
| Stepan Company |
| Recticel NV |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta foam compounding corridor is compressing spot-market margins for commodity-grade rigid foam while simultaneously elevating pricing power for REACH-certified specialty grades in Germany's automotive supply corridor. This utilization divergence rewards integrated compounders with captive isocyanate flows and punishes regional processors dependent on merchant MDI purchases.
Pricing Analysis
Geographic price spreads between German automotive-grade pigmented foam and Asian commodity insulation foam reflect certification premiums and regulatory compliance burdens. Three-tier pricing structure across REACH-certified specialty, automotive specification rigid, and furniture commodity grades separates buyers by documentation requirements and color-consistency tolerances. Pricing pressure stems from isocyanate input volatility compressing margins for non-integrated compounders serving cost-sensitive furniture segments. Furniture distributors exhibit highest price sensitivity while aerospace and medical device OEMs accept substantial premiums for ISO 10993 and FAR 25.853 certified grades.
Supply Chain Analysis
Export control regimes on advanced pigment dispersion technology limit technology transfer to non-integrated foam compounders outside Europe and Japan. Supply concentrates in Germany, China, and the United States, with Ludwigshafen integrated sites, Yangtze River Delta chemical clusters, and Michigan appliance insulation corridors anchoring global capacity. Raw material flows draw from merchant MDI and TDI isocyanate markets, polyol feedstocks, and REACH-compliant inorganic pigment systems. Single-source vulnerability concentrates in Baden-Württemberg and Bavaria Tier-1 supplier clustering for just-in-time automotive interior assembly. Distribution runs through direct technical sales forces for specification-driven automotive and medical device accounts, with wholesale channels handling standardized furniture and packaging grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as specification-driven procurement in automotive and medical device channels displaces spot-market volume purchasing, creating niche positions for certified-grade compounders with captive analytical capabilities.
For Market Incumbents: Insulate margin position by accelerating backward integration into low-GWP blowing-agent systems and securing captive pigment dispersion capacity ahead of REACH Annex XVII enforcement waves. Capacity addition in Ludwigshafen and Leverkusen integrated sites defends automotive specification relationships against emerging Asian compounders with hydrocarbon blowing-agent advantages. For New Entrants and Emerging Players: Establish a beachhead in sports equipment structural cores where certified color-stable grade demand climbs fastest and qualified vendor pools remain thin. Alpine ski and premium bicycle manufacturers present penetrable entry points with less entrenched supply relationships than automotive Tier-1 corridors. A go-to-market angle emphasizing rapid color-matching turnaround and small-batch flexibility differentiates against integrated majors with longer qualification cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized foam compounders with ISO 10993 and FAR 25.853 certification portfolios serving medical device and aerospace OEMs through multi-year specification contracts. Long-term viability over the next decade rests on low-GWP blowing-agent transition execution and pigment dispersion engineering talent retention. The signal to watch is California HFC phase-down acceleration creating early-mover valuation premiums for West Coast low-GWP capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-GWP Blowing Agents | Covestro and BASF integrated sites in Germany already certify next-generation grades for 2027 automotive programs. |
| Medical Device Certification Investment | ISO 10993 biocompatibility compliance opens scarcity-premium positioning in surgical positioning equipment. |
| Joint Venture for Pigment Dispersion Technology | High-colorfastness particle stabilization partnerships penetrate exterior-exposed PU component specifications. |
| Long-term Supply Agreement with Tier-1 Automotive | Baden-Württemberg seating suppliers mandate lot-level color consistency certification before contract award. |
| Capacity Expansion in California Low-GWP Corridor | State-level hydrofluorocarbon restrictions ahead of federal timelines reward early-mover West Coast positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polyurethane formulators, automotive Tier-1 procurement leads, medical device OEM material scientists, and pigment dispersion engineering specialists. Secondary validation drew from ECHA REACH registration databases, EPA chemical handling filings, SEC 10-K disclosures from integrated chemical majors, and customs trade flow records for isocyanate and polyol feedstocks. Bottom-up volume modeling across rigid, specialty, and flexible foam grades triangulated against top-down value estimates from automotive interior and appliance insulation end-use channels.
Calibration against historical capacity utilization rates at Ludwigshafen, Leverkusen, and Yangtze River Delta integrated sites anchored the projection framework across the analysis window. Segmentation dimensions modeled include foam rigidity grade, application channel, certification tier, and regional regulatory cluster. CAGRs were derived from regression analysis of specification-driven procurement growth versus commodity spot-market expansion. Industry-specific forecast inputs incorporated F-Gas Regulation amendment trajectories and California HFC phase-down acceleration schedules.
Stress conditions across isocyanate price volatility bands, REACH enforcement intensity scenarios, and low-GWP blowing-agent conversion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about automotive interior specification persistence and medical device biocompatibility certification adoption curves. Material shifts in EPA methylene chloride restrictions or ECHA pigment authorization withdrawals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Static Mixer Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Catalyst Bins Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Industrial Wax Market