
 Calendering Resins Market | 2026-2036
Calendering Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Calendering Resins Market Analysis
Buyer consolidation among automotive OEMs is recalibrating volume allocation across the calendering resins supply base. Eastman Chemical Company leverages its Eastman Texas operations to sustain captive plasticizer supply for flexible PVC calendering. Shin-Etsu Chemical Co., Ltd. anchors its position through integrated silicone and vinyl resin production in Japan and the Netherlands.
Calendering resins are thermoplastic or thermosetting polymer systems formulated for multi-roll calender processing, typically achieving gauge tolerances within 0.025 millimeters for film and sheet applications. These resins must exhibit precise melt viscosity profiles and thermal stability across 150–200°C processing windows to prevent degradation during high-speed rolling. Polyurethane grades command margin premiums in automotive interior films where abrasion resistance and low-temperature flexibility prove critical. Epoxy-based calendering systems are gaining application share in industrial coatings requiring chemical resistance, though heat curing technology remains the dominant processing method due to established equipment infrastructure.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based calendering operations in the United States, while REACH registration requirements in Europe mandate comprehensive substance dossiers for phenolic and polyamide resin imports. The EU F-Gas Regulation indirectly pressures manufacturers toward UV curing alternatives by restricting fluorinated greenhouse gases used in certain thermal processes. Stakeholders must monitor regulatory divergence between North American and European emission frameworks when configuring regional production assets and technology portfolios.
Market Dynamics
Automotive OEM procurement consolidation is compressing supplier margins while simultaneously demanding higher-performance resin grades with tighter gauge tolerances and extended thermal stability windows.
Growth Catalysts
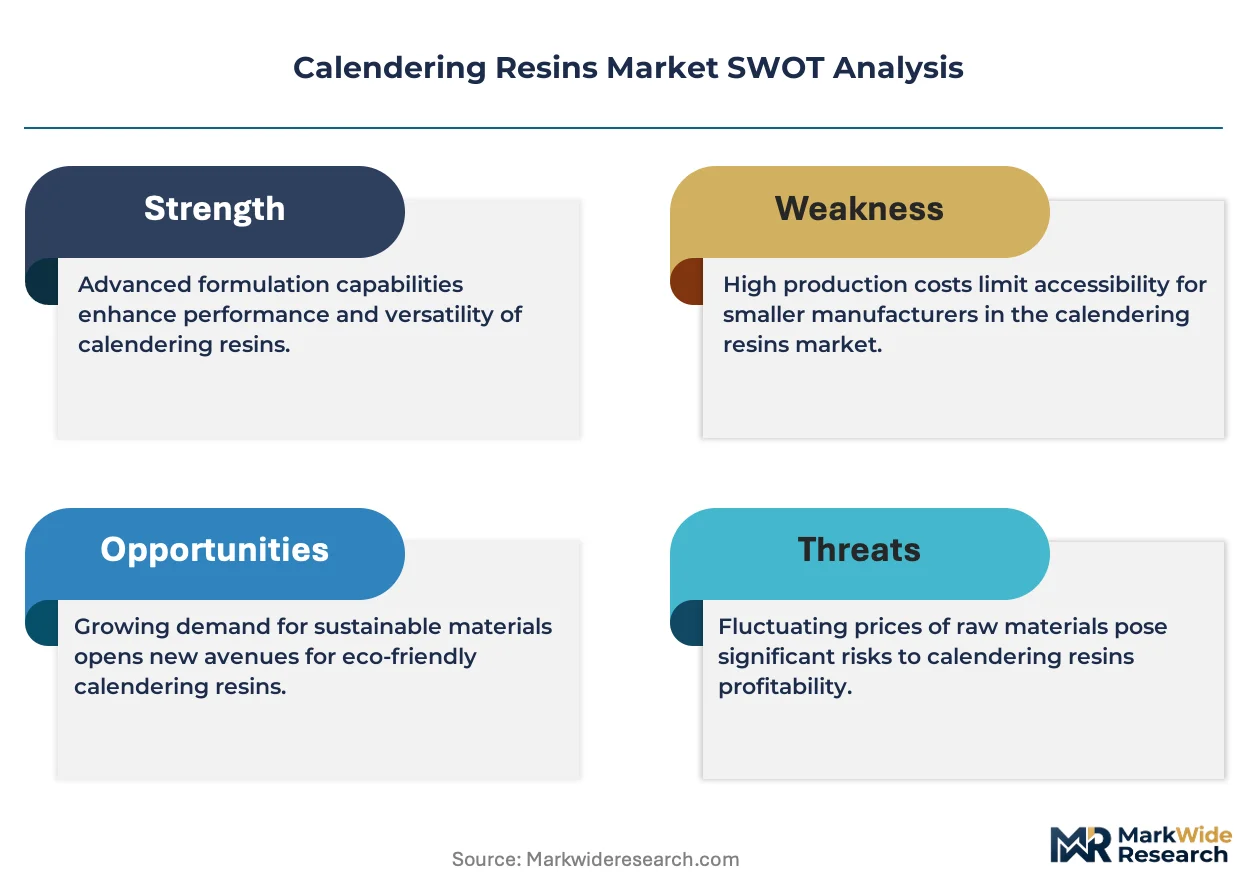
- REACH substance registration:European ECHA mandates are accelerating replacement of legacy phenolic systems with compliant polyurethane and epoxy alternatives in precision film manufacturing.
- Flexible PVC film demand:Interior surface applications in electric vehicle platforms require calendering resins with enhanced low-temperature flexibility and abrasion resistance profiles.
- Germany's industrial corridor concentration:Precision sheet manufacturers in Baden-Württemberg and Bavaria anchor specialized high-margin resin consumption for medical and optical film grades.
Market Restraints
- Plasticizer input volatility:Captive supply advantages at integrated producers disadvantage merchant resin compounders exposed to spot phthalate and bio-based plasticizer markets.
- Silicone resin supply concentration:Shin-Etsu's integrated production in Japan and the Netherlands creates bottleneck risk for specialty vinyl-silicone hybrid grades.
- Heat curing infrastructure lock-in:Established multi-roll calender equipment depreciated over decades resists capital replacement for UV curing adoption despite emission advantages.
Strategic Opportunities
- UV curing technology convergence:Hybrid epoxy-acrylate formulations combining thermal stability with instant cure response open industrial coating segments currently served by solvent systems.
- EPA NESHAP compliance services:Resin suppliers bundling formulation redesign with emission monitoring integration capture value from processors facing enforcement escalation.
- Medical film certification pathway:US FDA 21 CFR compliant resin grades for sterile barrier packaging command price premiums in an underpenetrated segment.
Industry Challenges
- Polymer rheology expertise scarcity:Formulation chemists capable of optimizing melt viscosity profiles across 150–200°C processing windows command compensation premiums that erode R&D budgets.
- Dual certification timeline compression:Simultaneous EPA TSCA pre-manufacture notification and REACH dossier preparation extends new product launch cycles by 18–24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calendering Resins Market |
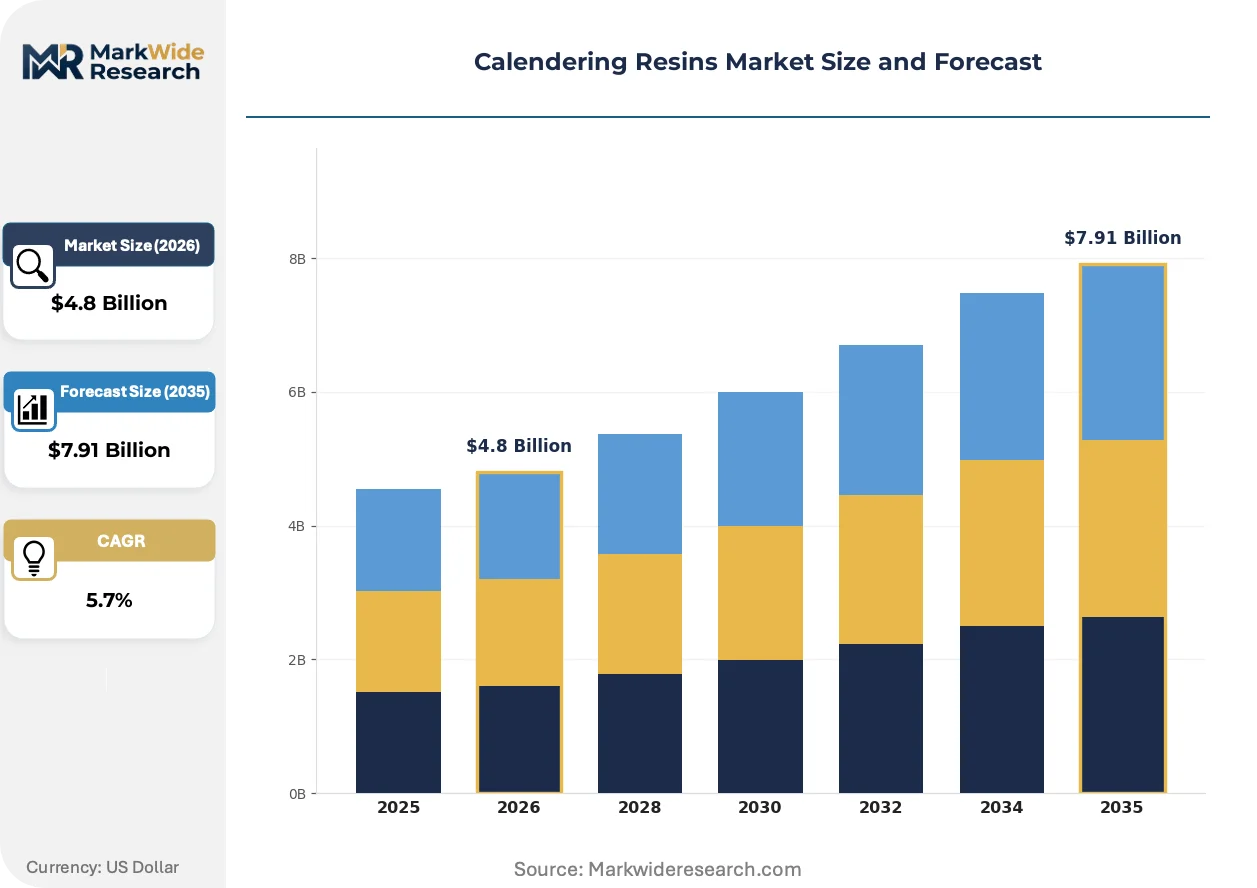
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Phenolic, Polyamide Application: Automotive Parts, Industrial Coatings, Adhesives, Textiles End User: Manufacturers, Automotive OEMs, Textile Producers, Construction Firms Technology: Heat Curing, Chemical Curing, UV Curing, Solvent-Based |
| Companies Covered | Formosa Plastics Corporation, Westlake Corporation, Eastman Chemical Company, Shin-Etsu Chemical Co., Ltd., Covestro AG, Avery Dennison Corporation, SK Chemicals, LG Chem, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calendering Resins Market Emerging Trajectories
Processing technology evolution and regulatory stringency are jointly compressing the viable technology set while opening premium niches for compliant advanced formulations.
Waterborne polyurethane dispersion technology is consolidating position in automotive interior film applications as Tier 1 suppliers abandon solvent-based systems ahead of EPA enforcement deadlines. BMW and Mercedes-Benz interior programs now specify aqueous polyurethane calendering resins exclusively, forcing compounders to retire legacy phthalate-plasticized PVC lines. This transition is consolidating procurement volumes among suppliers with proven aqueous dispersion scale-up capabilities.
The EU F-Gas Regulation is restricting hydrofluorocarbon use in thermal process equipment, indirectly pressuring calendering operations toward UV curing alternatives or infrared drying retrofits. German and Dutch film processors face accelerated equipment replacement timelines as maintenance parts for HFC-dependent chillers become unavailable. Industrial coating segments in Belgium and northern France are responding fastest, with several processors completing UV line conversions during scheduled maintenance windows.
Automotive OEM direct sourcing contracts are displacing distributor-mediated procurement for high-volume resin grades, compressing channel margins while securing supply priority. Tier 2 compounders in Michigan and Ohio report volume allocation pressure as Ford and GM procurement teams consolidate approved supplier lists to single-digit counts. This concentration is most visible in flexible PVC programs for seating and dashboard applications, where annual contract values now exceed individual distributor revenue thresholds.
Calendering Resins Market Segmentation
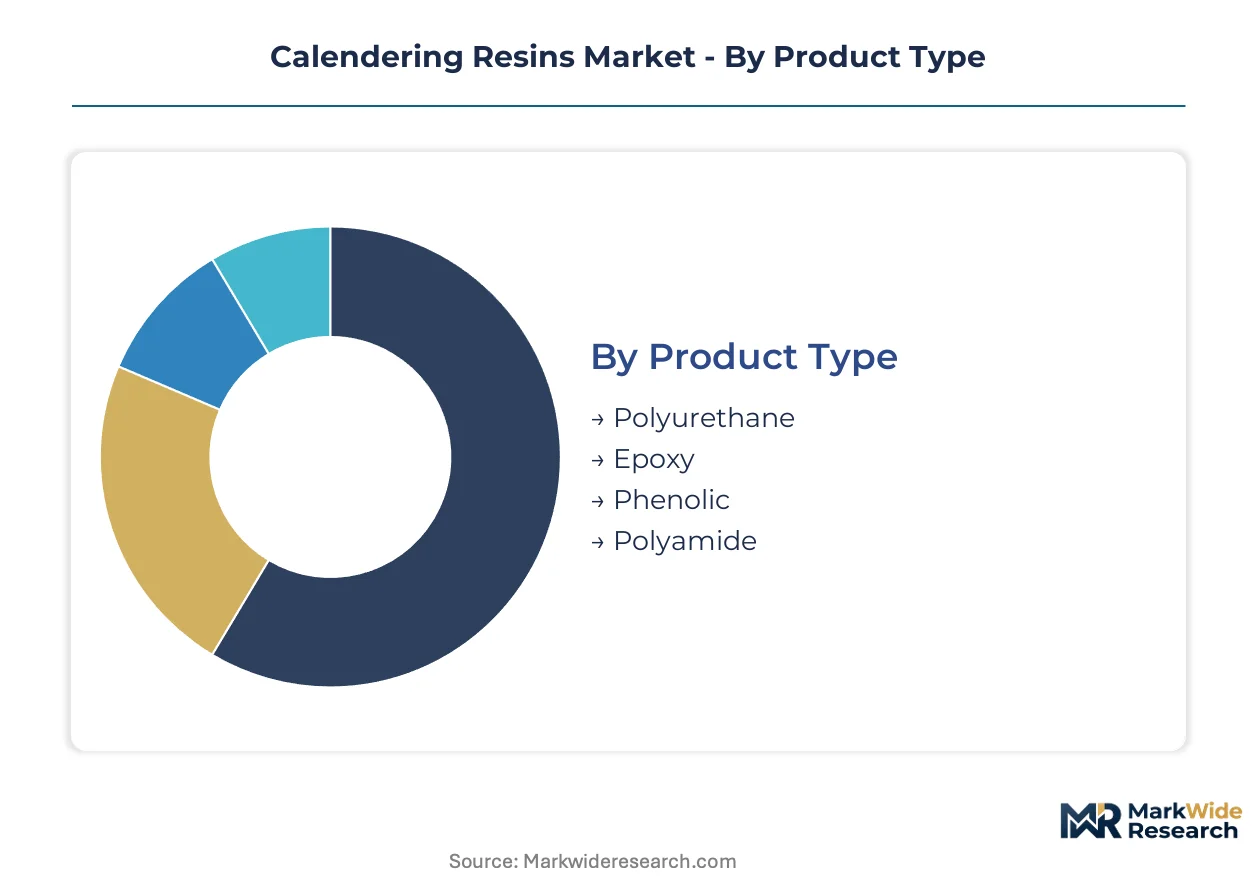
Calendering resin formulations diverge sharply across processing temperatures, curing chemistry, and end-use performance thresholds. Procurement patterns track these technical boundaries, with automotive interior specifications driving premium polyurethane grades while industrial maintenance coatings sustain epoxy and phenolic volumes.
Product Type:
Polyurethane formulations command the widest specification range across Shore hardness and abrasion resistance tiers.
- Polyurethane:These thermoplastic elastomers achieve Shore A 70-95 hardness ranges with exceptional low-temperature flexibility down to -40°C. BMW and Mercedes-Benz interior programs in Germany specify aqueous polyurethane dispersions exclusively, forcing compounders to abandon legacy plasticized PVC lines.
- Epoxy:Bisphenol-A and novolac-based systems deliver chemical resistance ratings exceeding ASTM D543 standards for industrial coating applications. Belgian and northern French processors are converting heat-curing epoxy lines to UV-acrylate hybrids during scheduled maintenance windows to meet EU F-Gas Regulation timelines.
- Phenolic:Thermosetting resole and novolac grades retain cost advantages in abrasive-facing and friction-material applications where thermal stability exceeds 200°C requirements.
- Polyamide:Nylon 6 and nylon 66-based calendering compounds serve specialized textile lamination and high-temperature release film segments with melting points above 220°C.
Mature deployment sits with Phenolic in industrial abrasive substrates. Newer deployment is concentrated in Polyurethane aqueous dispersions for automotive interior compliance.
Application:
End-use performance specifications create tiered margin structures across mobility, industrial, and consumer segments.
- Automotive Parts:Interior surface films for seating, dashboards, and door panels require gauge tolerances within 0.025 millimeters and abrasion resistance per ASTM D4060. Ford and GM procurement teams in Michigan and Ohio have consolidated approved supplier lists to single-digit counts for flexible PVC and polyurethane programs.
- Industrial Coatings:Chemical-resistant finishes for tanks, pipelines, and processing equipment sustain solvent-based epoxy volumes despite EPA NESHAP enforcement escalation. Heat curing infrastructure depreciation over decades resists capital replacement for UV alternatives.
- Adhesives:Pressure-sensitive and structural bonding films for industrial assembly operate at lower specification intensity than automotive grades, with price pressure from merchant compounders lacking captive plasticizer supply.
- Textiles:Synthetic leather and technical fabric coatings in Baden-Württemberg manufacturing clusters demand specialized resin-plasticizer compatibility for multi-layer lamination processes.
Volume concentration centers on Automotive Parts OEM direct contracts. Margin expansion is climbing the fastest in Industrial Coatings UV-curing conversions.
End User:
Procurement scale and technical capability separate integrated compounders from specification-driven formulators.
- Manufacturers:Precision film and sheet producers in Germany's industrial corridor anchor specialized high-margin resin consumption for medical and optical film grades requiring FDA 21 CFR compliance pathways.
- Automotive OEMs:Direct sourcing contracts now exceed individual distributor revenue thresholds for flexible PVC seating and dashboard programs, compressing channel margins while securing supply priority.
- Textile Producers:Synthetic leather manufacturers face formulation redesign costs as REACH substance registration mandates accelerate replacement of legacy phthalate systems.
- Construction Firms:Waterproofing membrane and flooring applications sustain commodity-grade phenolic and polyamide volumes with limited specification differentiation.
Procurement sophistication is highest among Automotive OEMs. Technical specification intensity peaks with Manufacturers serving medical certification pathways.
Technology:
Curing chemistry determines capital intensity, emission profiles, and regulatory compliance burden.
- Heat Curing:Multi-roll calender equipment with infrared and convection drying dominates installed capacity, achieving 150-200°C processing windows with established rheology control. Depreciated asset bases resist replacement despite EU F-Gas Regulation restrictions on hydrofluorocarbon-dependent chillers.
- UV Curing:Instant cure response eliminates thermal dwell time and reduces work-in-process inventory. German and Dutch film processors face accelerated equipment replacement timelines as HFC maintenance parts become unavailable.
- Chemical Curing:Two-part epoxy and polyurethane systems retain application in thick-film coatings where UV penetration limits cure depth.
- Solvent-Based:Declining share under EPA NESHAP and REACH volatile organic compound thresholds, with remaining volumes concentrated in industrial maintenance coatings requiring ambient temperature application.
Installed capacity dominance rests with Heat Curing infrastructure. Steepest expansion trajectory belongs to UV Curing hybrid formulations combining thermal stability with emission compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision film manufacturers in Germany's industrial corridor anchor specialized high-margin resin consumption. Automotive OEM procurement consolidation in the United States and Japan is recalibrating volume allocation across regional supply bases.
Germany
Precision sheet manufacturers in Baden-Württemberg and Bavaria drive demand for medical and optical film grades requiring REACH-compliant polyurethane formulations. ECHA substance registration mandates accelerate replacement of legacy phenolic systems in these manufacturing clusters. Stuttgart-area processors now specify aqueous polyurethane dispersions exclusively for interior surface applications.
United States
Automotive OEM direct sourcing contracts in Michigan and Ohio exceed individual distributor revenue thresholds for flexible PVC programs. EPA NESHAP enforcement under the National Emission Standards for Hazardous Air Pollutants constrains solvent-based calendering operations. Ford and GM procurement teams have consolidated approved supplier lists to single-digit counts in the Midwest manufacturing belt.
Japan
Integrated silicone and vinyl resin production anchors specialty vinyl-silicone hybrid grade supply for precision electronics films. METI industrial standards guide formulation requirements for high-performance resin grades. Nagoya-area chemical processors maintain captive plasticizer supply chains for automotive interior specifications.
Netherlands
German and Dutch film processors face accelerated equipment replacement timelines as EU F-Gas Regulation restricts hydrofluorocarbon-dependent chillers. ECHA REACH dossier requirements mandate comprehensive substance documentation for phenolic and polyamide resin imports. Rotterdam-area processors are completing UV line conversions during scheduled maintenance windows.
Belgium
Industrial coating segments in northern France and Belgium respond fastest to emission compliance pressures with UV-acrylate hybrid adoption. EU F-Gas Regulation indirectly pressures operations toward UV curing alternatives as HFC maintenance parts become unavailable. Antwerp-area processors serve chemical-resistant tank and pipeline coating applications with converted heat-curing epoxy lines.
Calendering Resins Market Vendor Landscape
United States producers anchor one tier; Japanese and German specialists hold differentiated positions in high-performance grades. The vendor base separates into integrated chemical conglomerates with captive feedstock supply and merchant compounders exposed to spot plasticizer markets. Three strategic archetypes dominate: scale-driven resin manufacturers, specialty formulation houses, and vertically integrated automotive suppliers. Competitive moves center on aqueous dispersion scale-up capabilities and UV curing technology licensing.
Among United States-based chemical producers, Eastman Chemical Company and Westlake Corporation exemplify the scale-driven archetype with established positions in flexible PVC and thermoplastic formulations. Japanese specialists Shin-Etsu Chemical Co., Ltd. and LG Chem occupy positions within the specialty tier, with the former representing integrated silicone-vinyl hybrid production capabilities. Covestro AG anchors the European polyurethane formulation segment. These named entities represent strategic positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Westlake Corporation |
| Eastman Chemical Company |
| Shin-Etsu Chemical Co., Ltd. |
| Covestro AG |
| Avery Dennison Corporation |
| SK Chemicals |
| LG Chem |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Captive plasticizer production at integrated resin manufacturers anchors both supply security and margin defense against merchant compounders exposed to spot phthalate markets. Eastman Chemical Company's Texas operations and Shin-Etsu's integrated silicone-vinyl production in Japan and the Netherlands demonstrate how backward integration into critical inputs determines pricing power across polyurethane and specialty hybrid grades.
Pricing Analysis
Volume concentration in automotive OEM direct contracts compresses margins, while specialized aqueous polyurethane dispersions for medical and optical films sustain premium tiers. Price differentiation separates REACH-compliant grades from legacy phenolic systems, with FDA 21 CFR certification commanding additional premiums. Cost compression in standard flexible PVC runs through plasticizer input volatility, as merchant compounders lack captive supply. Tier 2 processors in Michigan and Ohio show highest price sensitivity, whereas German precision film manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Scrap calendering resin recovery and reprocessing flows remain underdeveloped, though Belgian and Dutch processors are piloting closed-loop systems for UV-curable epoxy-acrylate hybrids. Primary production concentrates in Germany, the United States, and Japan, with specialty vinyl-silicone hybrids tethered to Shin-Etsu's integrated facilities in Japan and the Netherlands. Raw material dependencies center on bisphenol-A, polyol feedstocks, and specialty plasticizers. Single-source vulnerability persists for silicone resin intermediates. Distribution runs through direct OEM contracts displacing traditional distributor channels in high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calendering resins market is executing a technology-transition phase as aqueous polyurethane dispersions and UV curing systems displace solvent-based heat curing infrastructure. This substitution wave compresses legacy equipment valuations while opening premium positioning for compliant formulation houses.
For Market Incumbents: Extend aqueous dispersion scale-up capabilities to capture BMW and Mercedes-Benz interior program specifications before enforcement deadlines harden. Deepen captive plasticizer supply through backward integration into bio-based alternatives, defending margin position against merchant compounders exposed to phthalate spot markets. Prioritize UV curing technology licensing partnerships to monetize stranded heat-curing assets at Tier 2 processors.
For New Entrants and Emerging Players: Begin with FDA 21 CFR compliant resin grades for sterile barrier packaging, an underpenetrated segment where established suppliers lack dedicated medical certification pathways. Target German precision film manufacturers in Baden-Württemberg requiring REACH-compliant polyurethane formulations with specialized rheology profiles. Lead with formulation redesign services bundled with emission monitoring integration to capture EPA NESHAP compliance value.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty formulation houses with proven aqueous dispersion scale-up and medical certification capabilities. Long-term viability favors integrated producers with captive feedstock supply and UV curing technology portfolios. Watch for EU F-Gas Regulation enforcement escalation as the inflection signal accelerating equipment replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Plasticizers | Captive supply secures margin defense against phthalate spot market volatility for polyurethane grades. |
| UV Curing Technology Licensing | Belgian and Dutch processors convert heat-curing lines during maintenance windows to meet EU F-Gas timelines. |
| FDA 21 CFR Certification Investment | Medical film grades command price premiums in sterile barrier packaging with limited qualified suppliers. |
| Long-term Supply Agreement with Automotive OEMs | Ford and GM procurement consolidation favors compounders with direct contract relationships over distributors. |
| Joint Venture for Aqueous Dispersion Scale-up | BMW and Mercedes-Benz interior programs now specify aqueous polyurethane exclusively, forcing capacity alignment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at calendering operations, procurement leads at automotive OEMs, technical R&D directors at resin compounders, and distribution channel partners. Bottom-up volume modeling triangulated against top-down industry value estimates derived from ACC and Cefic chemical industry reports, EPA NESHAP enforcement disclosures, and ECHA REACH registration databases.
Granularity-level modeling operated at resin grade tier, end-use industry, curing technology, and regional production hub dimensions across the projection horizon. CAGRs were synthesized from segment-level volume trajectories and value-per-unit assumptions. Forecast inputs incorporated automotive OEM platform electrification schedules, EU F-Gas Regulation equipment replacement timelines, and REACH substance registration compliance deadlines.
Automotive OEM procurement consolidation, EPA enforcement escalation, and EU F-Gas Regulation chillers parts availability are the dominant revision risks to modeled outcomes. Practitioners should monitor these triggers for early signals of demand acceleration or supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Global Encapsulation Resins Market