
 North America Polypropylene Copolymer Market | 2026-2036
North America Polypropylene Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polypropylene Copolymer Market Intelligence
Capital-intensity divergence between integrated refinery-petrochemical operators and standalone compounders is bifurcating competitive returns in the North America polypropylene copolymer market. LyondellBasell Industries leverages its Channelview, Texas, complex to sustain feedstock cost advantages across random and impact copolymer grades. ExxonMobil Chemical Company anchors its position through proprietary metallocene catalyst technology, while Dow Chemical Company differentiates via specialized medical-grade and automotive compounding capabilities.
North America polypropylene copolymer denotes a thermoplastic polymer synthesized through copolymerization of propylene with ethylene or other alpha-olefins, yielding materials with tunable impact resistance from -20°C to 120°C service temperatures and melt flow indices spanning 2 to 70 g/10min for injection molding and extrusion processes. Impact copolymer dominates automotive bumper and interior panel applications where low-temperature ductility is specified, while random copolymer leads clarity-driven packaging and medical device segments. High-temperature copolymer represents the fastest-expanding grade category as under-hood automotive specifications tighten thermal deflection requirements.
FDA 21 CFR 177.1520 compliance governs food-contact and medical-device applications, compelling compounders to maintain extractables testing protocols, while EPA Clean Air Act stationary source rules shape emissions profiles at production facilities across Texas and Louisiana. NHTSA fuel economy standards indirectly drive copolymer substitution for heavier engineering plastics in vehicle weight reduction programs. Stakeholders must monitor proposed EPA ethylene oxide emission regulations and their cascading effects on sterilization-grade medical copolymer availability.
Market Dynamics
Automotive lightweighting mandates and medical-grade certification requirements are compressing product development cycles across the North America polypropylene copolymer value chain, forcing compounders to reconcile thermal performance specifications with FDA extractables protocols simultaneously.
Growth Catalysts
- NHTSA fuel economy standards:Vehicle weight reduction programs accelerate copolymer substitution for ABS and polycarbonate in bumper systems and interior panels.
- US Gulf Coast petrochemical expansion:Ethane feedstock availability from shale gas production sustains cost-competitive propylene supply for integrated producers.
- Medical device sterilization demand:Gamma and ethylene oxide sterilization compatibility drives random copolymer adoption in syringe and IV component manufacturing.
Market Restraints
- Propylene monomer volatility:Crude oil and natural gas liquid price swings transmit directly to copolymer raw material costs, compressing compounder margins.
- Texas-Louisiana production concentration:Hurricane exposure and Gulf Coast weather disruption risk concentrate supply vulnerability in a narrow geographic corridor.
- Engineering polymer substitution:Polyamide and PBT blends retain performance advantages in high-temperature under-hood applications above 150°C.
Strategic Opportunities
- Canada medical device manufacturing:Health Canada regulatory alignment with FDA standards creates nearshoring opportunities for US compounders seeking supply chain redundancy.
- Metallocene catalyst advances:Narrow molecular weight distribution technologies enable clarity and stiffness combinations previously unattainable in random copolymer grades.
- Mexico automotive assembly growth:OEM transplant expansion in Querétaro and Guanajuato generates localized demand for impact copolymer in injection-molded components.
Industry Challenges
- Extractables testing capacity:FDA 21 CFR 177.1520 compliance requires specialized analytical chemistry expertise that outstrips current laboratory availability.
- Multi-grade production switching:Random-to-impact copolymer transition downtime erodes asset utilization at standalone compounding facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polypropylene Copolymer Market |
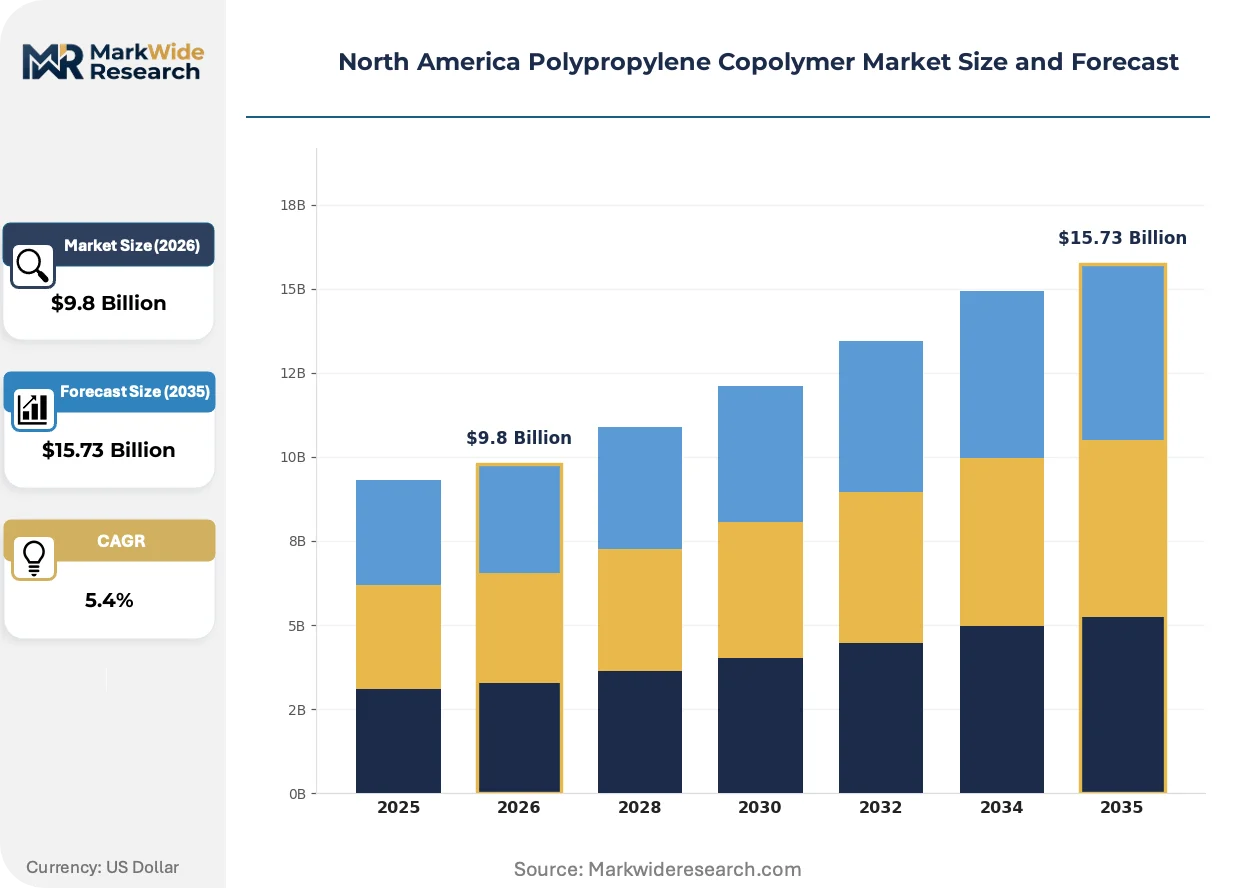
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Copolymer, Random Copolymer, Block Copolymer, High-Temperature Copolymer Application: Automotive Parts, Packaging, Consumer Goods, Medical Devices End User: Manufacturers, Distributors, Retailers, Exporters Grade: General Purpose, High Flow, Fiber Grade, Film Grade |
| Companies Covered | LyondellBasell Industries, ExxonMobil Chemical Company, Dow Chemical Company, Chevron Phillips Chemical Company, BASF, SABIC, Borealis AG, Formosa Plastics Corporation, Westlake Chemical Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polypropylene Copolymer Market Strategic Shifts & Innovations
Advanced catalyst systems and regulatory harmonization pressures are redefining product differentiation boundaries across medical, automotive, and packaging end-uses in North America.
Metallocene single-site catalyst technology is fragmenting traditional Ziegler-Natta product hierarchies by enabling precise control over ethylene incorporation and molecular weight distribution. Tier-one automotive suppliers now specify metallocene grades for Class A surface applications where weld-line aesthetics and dimensional stability are critical. The technology is fragmenting established supply relationships as compounders with catalyst licensing gain specification influence previously held by resin producers.
EPA proposed ethylene oxide emission regulations are tightening sterilization facility operating permits across Texas and Louisiana medical corridors. Medical device manufacturers face prospective supply constraints for sterilization-grade random copolymer as sterilizers reduce throughput or relocate capacity. The regulatory pressure is accelerating investment in alternative sterilization validation for gamma-compatible copolymer grades.
Automotive OEMs now mandate recycled content certificates in supplier scorecards, forcing compounders to develop post-industrial regrind protocols for impact copolymer. Tier-one suppliers in Michigan and Ohio are consolidating purchasing around compounders with verified mechanical recycling streams and mass-balance certification. The specification shift is most visible in bumper beam and fascia contracts where closed-loop material traceability is becoming a bid qualification threshold.
North America Polypropylene Copolymer Market Segmentation
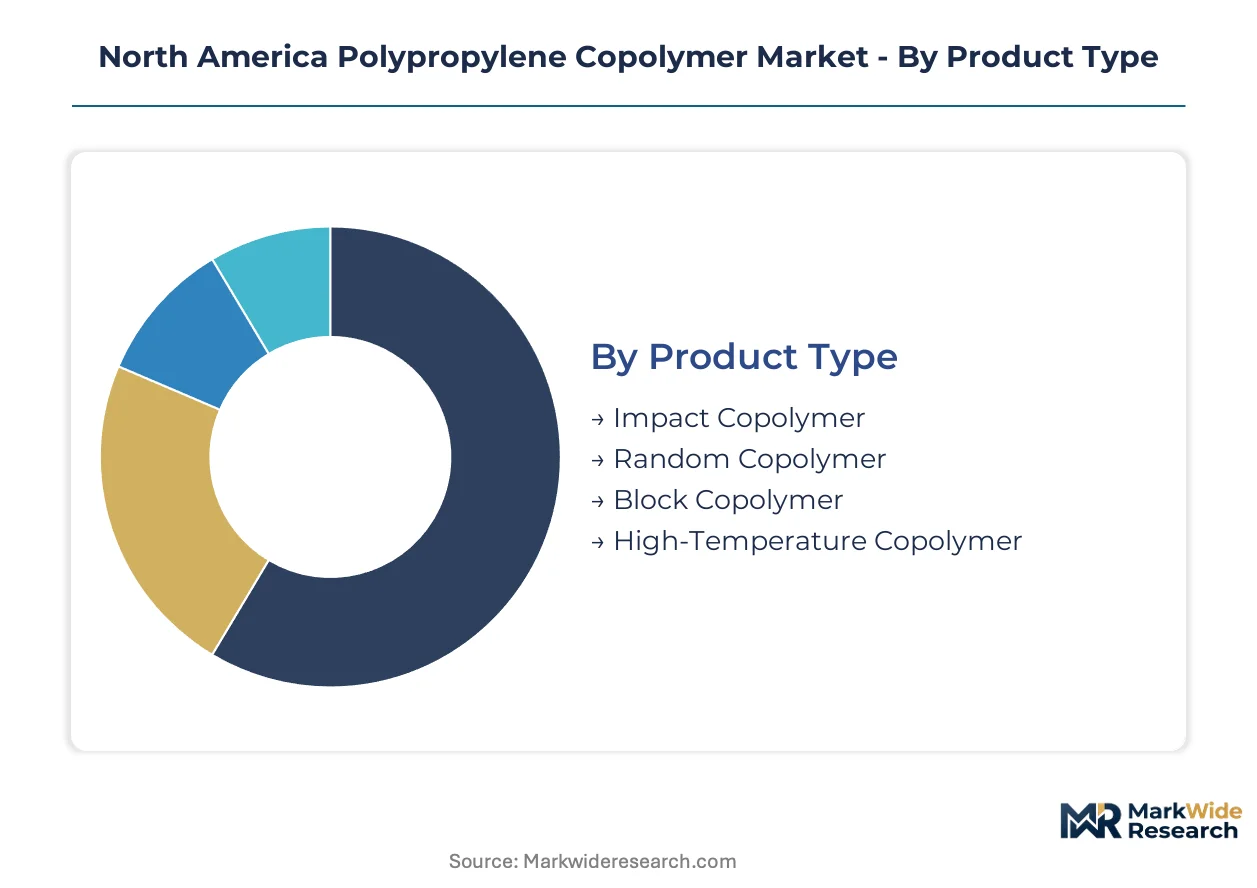
Polypropylene copolymer segmentation in North America reflects divergent certification burdens across FDA medical compliance, EPA emissions protocols, and NHTSA automotive specifications. Each segment category carries distinct regulatory gatekeepers that reshape formulation priorities and customer qualification timelines.
Product Type:
FDA 21 CFR 177.1520 extractables thresholds and NHTSA impact resistance specifications create divergent technical requirements across copolymer architectures.
- Impact Copolymer:Ethylene-propylene rubber phase dispersed within polypropylene matrix delivers low-temperature ductility down to -20°C. Demand concentrates in Michigan and Ohio automotive corridors where bumper beam and interior panel specifications mandate cold-impact resistance under NHTSA crashworthiness protocols.
- Random Copolymer:Statistical ethylene incorporation disrupts crystalline regularity to yield optical clarity exceeding 85% haze-free transmission. Medical device manufacturers in Minnesota and Massachusetts specify random copolymer for syringe barrels and IV connectors requiring gamma sterilization compatibility under FDA validation protocols.
- Block Copolymer:Segmented architecture combines rigid and elastomeric blocks for balanced stiffness and flexibility. Packaging converters in Wisconsin and Illinois utilize block grades for hinge-fatigue applications in living-hinge closures.
- High-Temperature Copolymer:Elevated crystallinity through controlled tacticity achieves heat deflection temperatures above 120°C. Under-hood automotive applications in Kentucky and Tennessee specify these grades for thermal management components.
Impact Copolymer handles the majority of throughput; High-Temperature Copolymer is the fastest mover on share.
Application:
Cost tier stratification separates specification-grade medical and automotive applications from commodity packaging volumes.
- Automotive Parts:Bumper systems, instrument panels, and door modules specify impact copolymer grades with melt flow indices of 10-35 g/10min for injection molding efficiency. OEM weight reduction programs across Detroit Three suppliers sustain specification growth despite engineering polymer competition above 150°C.
- Packaging:Clarity-driven food containers and thermoformed trays demand random copolymer with nucleating agent packages for dimensional stability. California and Florida packaging hubs drive volume concentration for retail-ready formats.
- Consumer Goods:Housewares, furniture, and recreational equipment utilize general-purpose grades where cost minimization dominates supplier selection. Big-box retailer private-label programs in Texas and Georgia consolidate purchasing around compounders with mass-balance certification.
- Medical Devices:Syringes, IV components, and diagnostic cassettes require FDA-validated extractables profiles and ethylene oxide sterilization compatibility. Health Canada regulatory alignment enables cross-border supply redundancy for Minnesota and Massachusetts manufacturers.
Automotive Parts commands the largest volume position; Medical Devices is climbing the fastest on specification premiums.
End User:
Customer type determines technical service intensity and margin capture across the value chain.
- Manufacturers:Tier-one automotive suppliers and medical device OEMs demand lot traceability, certificate of analysis documentation, and dedicated technical service support. Direct relationships with Channelview and Baytown resin producers secure feedstock priority during supply disruptions.
- Distributors:Warehousing and just-in-time delivery networks serve mid-size processors lacking rail siding or bulk storage infrastructure. Regional distributors in Chicago, Atlanta, and Dallas-Fort Worth consolidate fragmented compounder supply for custom color and additive packages.
- Retailers:Private-label housewares and consumer goods programs specify general-purpose grades with minimal technical service overhead. Walmart and Target supplier scorecards increasingly mandate recycled content verification.
- Exporters:Cross-border shipments to Mexico automotive assembly plants in Querétaro and Guanajuato require Spanish-language documentation and NAFTA-origin certification. Export volumes track peso-dollar exchange rate volatility.
Manufacturers absorb the dominant share of premium-grade volume; Exporters are gaining share fastest on nearshoring momentum.
Grade:
Volume-maturity segmentation separates established general-purpose grades from specialized flow and fiber variants.
- General Purpose:Balanced melt flow and mechanical properties serve undifferentiated injection molding and extrusion applications. Commodity converters in Ohio and Pennsylvania prioritize price stability over performance optimization.
- High Flow:Melt flow indices exceeding 50 g/10min enable thin-wall packaging and complex automotive geometries with reduced cycle times. Metallocene catalyst licensing distinguishes suppliers capable of narrow molecular weight distribution at elevated flow rates.
- Fiber Grade:Controlled rheology and additive packages optimize spinnability for nonwoven fabrics and industrial textiles. Personal protective equipment demand sustained elevated fiber grade consumption through recent supply disruptions.
- Film Grade:Low gel content and seal initiation temperature control suit cast and blown film applications for food packaging. Cast film lines in California and South Carolina specify film grades for clarity and heat-seal performance.
General Purpose maintains the broadest installed base; High Flow is expanding most quickly on thin-wall specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Gulf Coast petrochemical corridor while Canadian compounders leverage regulatory alignment to capture medical-grade premiums. This asymmetry shapes cross-border supply strategies across North American polypropylene copolymer markets.
United States
Texas and Louisiana host integrated refinery-petrochemical complexes that convert ethane feedstock into propylene monomer at scale. EPA Clean Air Act stationary source rules govern emissions profiles at production facilities across the Gulf Coast. Houston and Baytown industrial clusters anchor North American capacity for impact and random copolymer grades serving automotive and medical end-uses.
Canada
Health Canada regulatory alignment with FDA standards enables nearshoring opportunities for US medical device manufacturers seeking supply chain redundancy. The country's national environmental regulator maintains protocols compatible with US extractables testing requirements. Ontario-based compounders serve Minnesota and Massachusetts medical device corridors with sterilization-grade random copolymer.
Mexico
OEM transplant expansion in Querétaro and Guanajuato generates localized demand for impact copolymer in injection-molded automotive components. NAFTA-origin certification requirements shape cross-border shipment documentation for US resin producers. Mexico City Metro and Bajío Region automotive assembly plants specify grades with melt flow indices optimized for thin-wall geometries.
North America Polypropylene Copolymer Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North America polypropylene copolymer market. Integrated petrochemical operators command feedstock economics while specialized compounders capture specification premiums through FDA-validated protocols. The vendor base separates into three strategic archetypes: Gulf Coast integrated producers with captive propylene supply, regional compounders with medical-grade certification capabilities, and distributors consolidating fragmented processor demand. Dominant competitive moves include backward integration into catalyst licensing and geographic expansion toward Mexico automotive assembly corridors.
Among integrated petrochemical operators, LyondellBasell Industries, ExxonMobil Chemical Company, and Dow Chemical Company occupy positions exemplifying divergent strategic approaches. LyondellBasell represents the scale-driven archetype anchored to Channelview complex economics. ExxonMobil Chemical Company exemplifies technology-differentiated positioning through proprietary catalyst capabilities. Dow Chemical Company sits within the specialized compounding tier, capturing premiums via medical-grade and automotive formulation expertise.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| ExxonMobil Chemical Company |
| Dow Chemical Company |
| Chevron Phillips Chemical Company |
| BASF |
| SABIC |
| Borealis AG |
| Formosa Plastics Corporation |
| Westlake Chemical Corp. |
| Others |
Cost & Logistics Intelligence
Channelview-scale ethane crackers running above 90% utilization anchor North American polypropylene copolymer economics, compressing unit costs for integrated operators while forcing standalone compounders into specification-grade niches to escape price floors. This scale asymmetry concentrates margin capture among Gulf Coast petrochemical complexes and fragments downstream pricing power across medical-certified compounders and commodity distributors.
Pricing Analysis
The customization-premium spread separates configured-to-order medical-grade copolymer from standard impact and random grades sold on spot indices. Three-tier pricing structure across FDA-validated premium, automotive-certified standard, and general-purpose economy levels reflects certification burden and lot-traceability requirements. Pricing pressure stems from propylene monomer volatility transmitting directly from crude oil and natural gas liquid swings, eroding compounder margins during feedstock spikes. Tier-one automotive suppliers and medical device OEMs exhibit lowest price sensitivity due to specification lock-in, while commodity packaging converters in Ohio and Pennsylvania prioritize cost stability over performance optimization.
Supply Chain Analysis
The United States and Canada anchor North American polypropylene copolymer production, with Texas and Louisiana hosting integrated refinery-petrochemical complexes and Ontario-based compounders serving medical-grade demand. Feedstock supply draws from shale-derived ethane and refinery-grade propylene, with catalyst systems and nucleating agent packages representing critical input dependencies. Single-source vulnerability concentrates in the Gulf Coast corridor where hurricane exposure threatens production continuity at Channelview and Baytown facilities. Distribution runs through rail-served bulk terminals to compounders, with regional distributors in Chicago, Atlanta, and Dallas-Fort Worth consolidating fragmented processor demand for custom color and additive packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized analytical chemistry capacity for FDA 21 CFR 177.1520 extractables testing represents the critical skill gap constraining medical-grade copolymer supply expansion, creating asymmetric returns for compounders with validated laboratory infrastructure.
For Market Incumbents: Secure backward integration into metallocene catalyst licensing to defend specification influence against technology-disrupting compounders. Prioritize capacity hardening at Gulf Coast complexes against hurricane disruption risk, while consolidating medical-grade certification capabilities through laboratory acquisition or partnership with Minnesota and Massachusetts device manufacturers facing sterilization-grade supply constraints. For New Entrants and Emerging Players: Lead with Health Canada regulatory alignment to capture nearshoring demand from US medical device OEMs seeking supply chain redundancy against EPA ethylene oxide sterilization facility constraints. Target Ontario-based compounding capacity serving Minnesota syringe and IV component manufacturers, leveraging cross-border regulatory equivalence to bypass incumbent FDA validation backlogs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical-grade compounders with locked-in FDA validation protocols and multi-year supply agreements with device OEMs. Long-term viability favors acquisition targets with dual automotive-medical certification capabilities and verified post-industrial recycling streams meeting OEM recycled content mandates. Watch EPA ethylene oxide emission rule implementation as inflection indicator for sterilization-grade random copolymer availability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Licensing | Metallocene technology access enables specification capture in Class A automotive surface applications. |
| Medical-Grade Laboratory Certification | FDA 21 CFR 177.1520 extractables testing capacity unlocks premium pricing in syringe and IV component supply. |
| Gulf Coast Capacity Hardening | Hurricane-resilient infrastructure protects against supply disruption concentrated in Texas-Louisiana corridor. |
| Cross-Border Canadian Expansion | Health Canada regulatory alignment creates nearshoring arbitrage for US device manufacturers. |
| Post-Industrial Recycling Protocol Development | Mass-balance certification meets Detroit Three supplier scorecard recycled content mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including plant managers at Channelview and Baytown petrochemical complexes, procurement leads at Michigan and Ohio Tier-one automotive suppliers, regulatory affairs directors at Minnesota and Massachusetts medical device manufacturers, and distribution channel partners in Chicago, Atlanta, and Dallas-Fort Worth. Secondary validation drew from EPA Clean Air Act stationary source filings, FDA 21 CFR 177.1520 compliance databases, customs and trade data tracking cross-border shipments to Querétaro and Guanajuato automotive assembly plants, and SEC 10-K disclosures from integrated petrochemical operators. Bottom-up volume modeling across grade tiers and end-use segments was triangulated against top-down capacity assessments from Gulf Coast production complexes.
Across the analysis window, forecasts were constructed through segmented demand modeling by product architecture, application certification burden, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating NHTSA fuel economy standard trajectories, EPA emission rule implementation timelines, and automotive lightweighting program specifications. Industry-specific inputs included propylene monomer cost curves tied to ethane feedstock pricing, metallocene catalyst adoption rates in Class A surface applications, and sterilization-grade random copolymer demand elasticity relative to gamma-compatible alternative validation.
The analysis sits within stated boundaries; outcomes outside sustained shale gas economics, stable FDA-Health Canada regulatory alignment, and continued NHTSA fuel economy standard enforcement would require recalibration. Forecasts reflect documented assumptions regarding ethane feedstock availability, catalyst technology licensing diffusion, and medical device sterilization modality mix. Recalibration cycles align with material shifts in EPA ethylene oxide emission regulations, hurricane frequency affecting Gulf Coast production continuity, and automotive OEM recycled content mandate escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Global Linear Low Density Polyethylene Market