
 Middle East and Africa Non-Phthalate Plasticizers Market | 2026-2036
Middle East and Africa Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Non-Phthalate Plasticizers Market Foresight
Food-contact-grade and medical-specification tiers is collapsing into the mainstream as Gulf petrochemical producers upgrade reactor and compounding capabilities. BASF SE leverages its Ludwigshafen technical base to supply high-purity adipate grades into Saudi converter networks. Eastman Chemical Company anchors its regional position through dedicated plasticizer distribution hubs in Jebel Ali. Evonik Industries AG specializes in sebacate chemistry for heat-stable cable compounds serving North African infrastructure projects.
Non-phthalate plasticizers are ester-based compounds—adipates, citrates, and sebacates—that replace ortho-phthalates in flexible polymer systems, typically exhibiting volatility below 0.5% at 105°C and compatibility with suspension-grade PVC resins. Their primary purpose is to reduce glass transition temperature while maintaining tensile elongation above 300% in finished compounds. Adipates currently lead volume in flexible PVC sheathing for Gulf construction cables, though citrates are gaining fastest in food-contact films as Gulf Standards Organization (GSO) migration limits tighten. Sealants and adhesives applications concentrate margin pools in specialty sebacate formulations where hydrolytic stability commands premium positioning over standard adipate offerings.
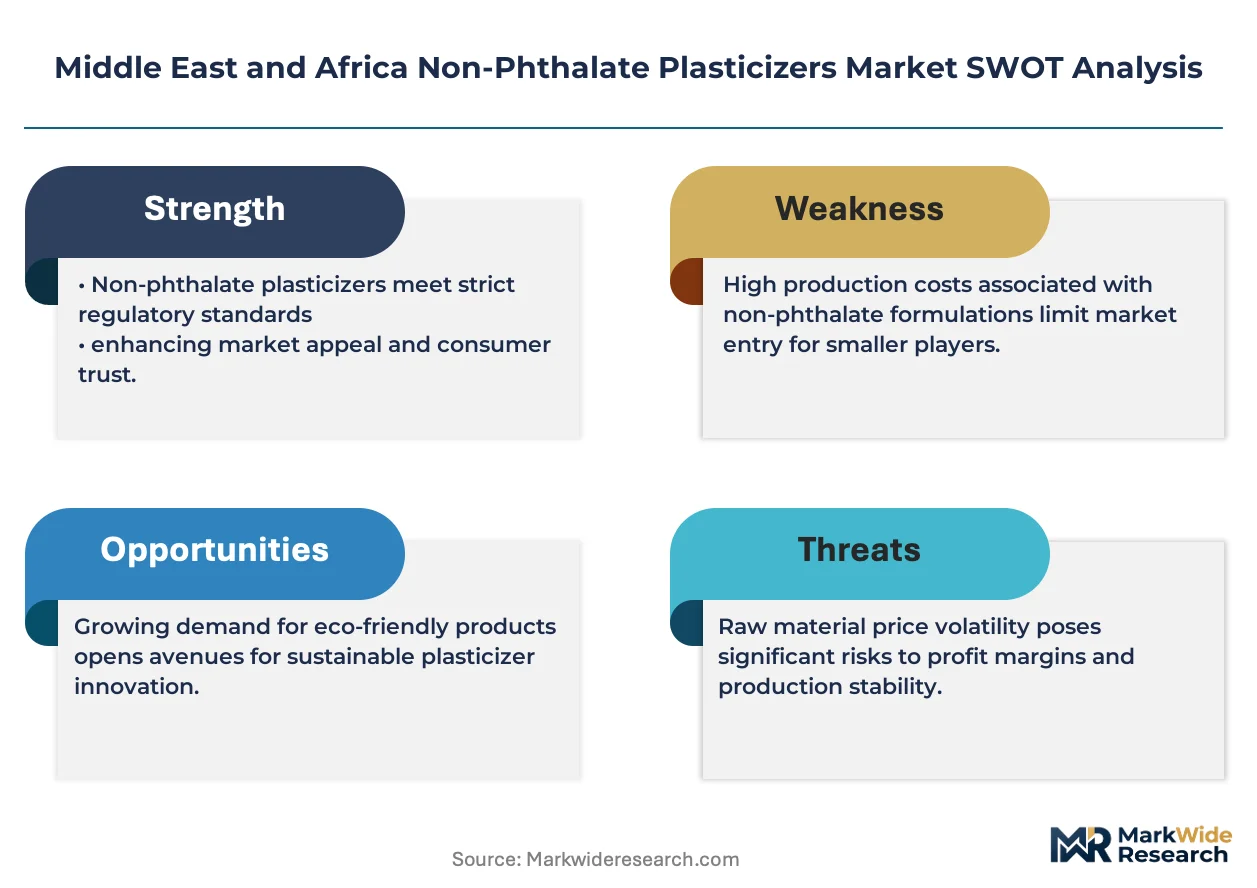
South Africa's National Regulator for Compulsory Specifications enforces phthalate restrictions aligned with EU REACH Annex XVII thresholds, while Saudi Standards, Metrology and Quality Organization (SASO) technical regulations mandate child-product safety assessments that exclude conventional DEHP. These frameworks compound reformulation costs but create qualified-supplier barriers that favor producers with pre-certified product portfolios. Stakeholders must monitor divergence between Gulf harmonization and national South African enforcement timelines when allocating technical service resources.
Market Dynamics
Gulf petrochemical downstream investments are redirecting formulation supply chains toward adipate and sebacate chemistry as REACH-aligned frameworks in Saudi Arabia and the United Arab Emirates tighten phthalate migration thresholds for flexible PVC applications.
Growth Catalysts
- SASO Technical Regulations:Saudi Standards, Metrology and Quality Organization mandates exclude conventional DEHP from child-product assessments, forcing compounders toward certified non-phthalate alternatives.
- Cable Sheathing Demand:Gulf construction megaprojects require heat-stable flexible PVC for infrastructure power distribution, concentrating volume pull in adipate-grade formulations.
- GSO Migration Limits:Gulf Standards Organization tightening of food-contact film specifications accelerates citrate plasticizer adoption across regional packaging converters.
Market Restraints
- Sebacic Acid Supply Concentration:Sebacate production depends on castor oil derivatives concentrated in Indian and Brazilian agricultural processing, exposing North African cable compounders to raw material volatility.
- Reformulation Cost Burden:REACH-aligned compliance in South Africa and Gulf states requires technical service investment that disadvantages smaller compounders without pre-certified portfolios.
- Adipate Performance Ceiling:Standard adipate plasticizers exhibit volatility above 0.3% at elevated temperatures, limiting penetration into automotive underhood applications where phthalate alternatives retain specification lock-in.
Strategic Opportunities
- Egyptian Converter Networks:Nile Delta cable and film manufacturing clusters remain underpenetrated by certified non-phthalate suppliers, creating first-mover positioning for pre-qualified adipate distributors.
- Medical-Grade Citrates:South African pharmaceutical packaging regulations aligned with EU MDR migration thresholds open specialty citrate tiers for IV bag and tubing applications.
- Digital Technical Service Platforms:Remote formulation support and certification documentation portals reduce Gulf compounder qualification timelines from months to weeks.
Industry Challenges
- Specialized Ester Chemistry Talent:Regional universities produce limited graduates with hands-on experience in sebacate synthesis and PVC compatibility testing, constraining producer technical service expansion.
- Multi-Jurisdiction Certification Lag:Divergent enforcement timelines between SASO, South Africa's National Regulator for Compulsory Specifications, and GSO harmonization efforts force redundant product testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Non-Phthalate Plasticizers Market |
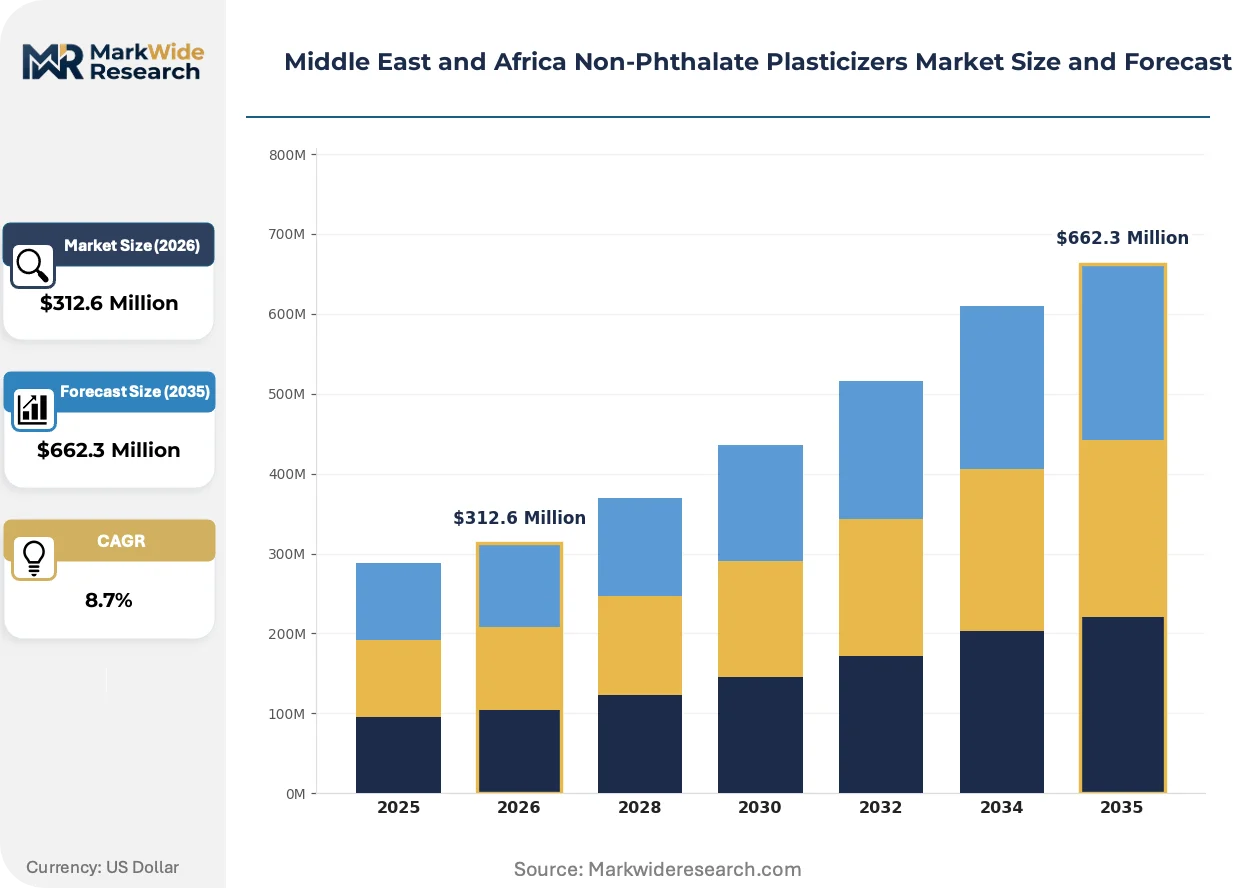
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adipates, Citrates, Sebacates, Others End User: Construction, Automotive, Consumer Goods, Electronics Application: Flexible PVC, Coatings, Sealants, Adhesives Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | BASF SE, Eastman Chemical Company, Evonik Industries AG, LANXESS, Arkema Inc., Avient Corporation, DIC CORPORATION, Perstorp, ExxonMobil Chemical Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Non-Phthalate Plasticizers Market Shifts & Advancements
Reactive extrusion capabilities and bio-based feedstock integration are reconfiguring how Gulf producers formulate heat-stable flexible compounds, compressing traditional technical service relationships while opening new specification tiers.
Polymeric plasticizer technology is fragmenting the historical adipate-sebacate dichotomy in high-durability cable applications. These higher-molecular-weight esters deliver volatility below 0.1% at 105°C while maintaining tensile elongation above 350% in finished Gulf construction cables. Saudi Aramco downstream ventures and Emirates Global Aluminium power infrastructure projects specify these grades for 40-year service life requirements. The technology is fragmenting supplier hierarchies by enabling regional compounders to bypass traditional European technical service dependencies.
REACH Annex XVII alignment through SASO and South Africa's National Regulator for Compulsory Specifications is compressing phthalate tolerance windows across child-product and food-contact categories. Industrial consequence includes mandatory third-party migration testing for all flexible PVC imports into Gulf Cooperation Council customs zones. Medical tubing and IV bag segments face the steepest compliance gradients, with South African pharmaceutical packaging converters accelerating citrate qualification programs ahead of full enforcement timelines.
Specification-driven procurement now dominates Gulf cable and film purchasing, displacing volume-based spot contracting. Procurement teams at Saudi Electricity Company and Dubai Electricity and Water Authority mandate pre-certified plasticizer portfolios with documented heat-aging performance. This compression of supplier qualification cycles favors distributors with integrated technical documentation platforms. The pattern is most visible in Jebel Ali chemical trading hubs, where compounders consolidate purchases through single-source adipate-sebacate portfolios rather than multi-supplier blending strategies.
Middle East and Africa Non-Phthalate Plasticizers Market Segmentation
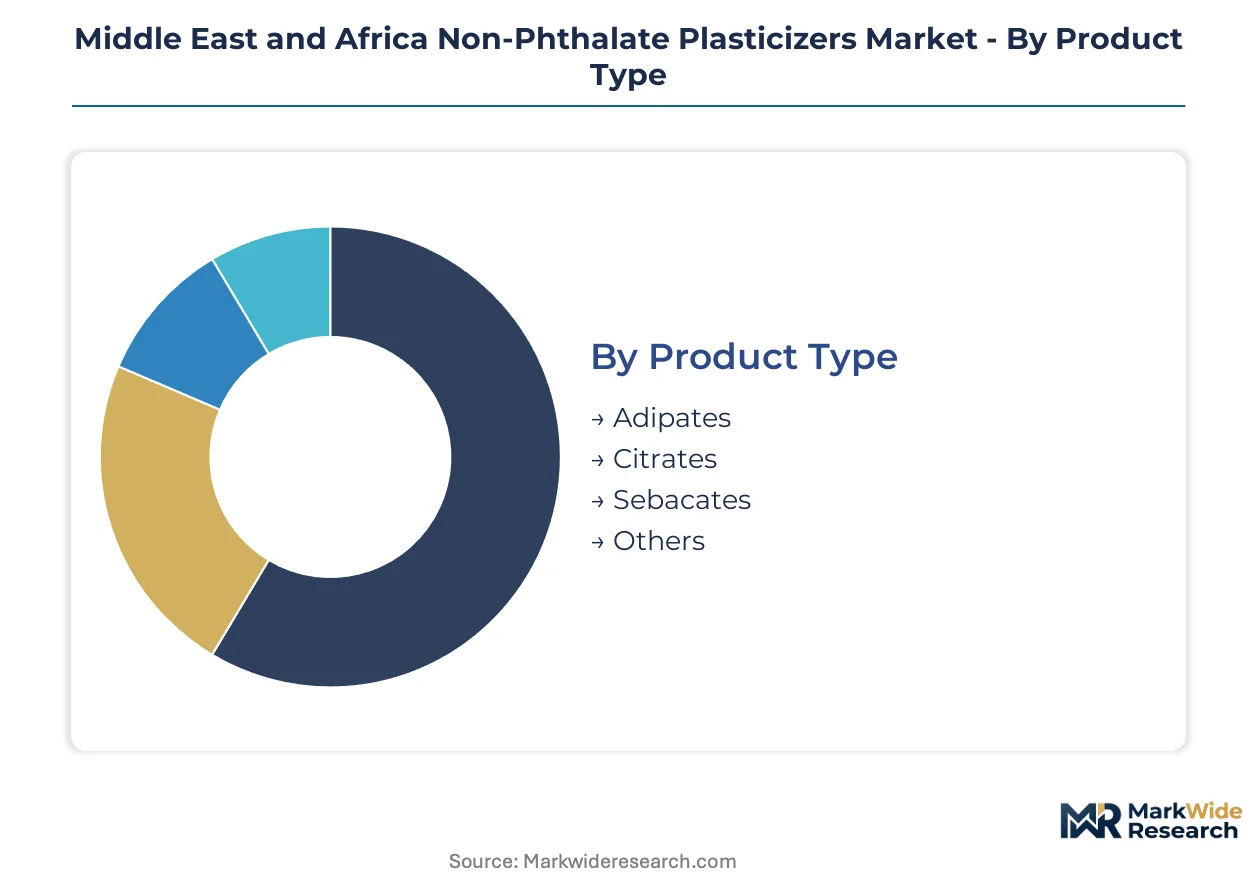
Non-phthalate plasticizer procurement in the Middle East and Africa fragments across specification tiers, end-use durability requirements, and certification complexity. Margin capture varies sharply by product chemistry and application criticality, with Gulf construction cables and South African medical packaging commanding distinct premium structures.
Product Type:
Sebacate formulations command the steepest margin premiums due to castor oil feedstock concentration and hydrolytic stability specifications.
- Adipates:Ester compounds derived from adipic acid and C8-C10 alcohols deliver glass transition reduction with volatility near 0.3% at 105°C. Saudi Electricity Company cable specifications concentrate volume demand in di-2-ethylhexyl adipate grades for Gulf infrastructure power distribution.
- Citrates:Acetyl tributyl citrate and tributyl citrate esters exhibit migration resistance below GSO food-contact thresholds. South African pharmaceutical packaging converters are accelerating qualification of medical-grade citrates for IV bag and tubing applications ahead of full EU MDR alignment.
- Sebacates:Di-2-ethylhexyl sebacate and dibutyl sebacate command premium positioning in North African cable compounds where 40-year heat-aging performance is specified.
- Others:Polymeric plasticizers and bio-based esters serve emerging sustainability mandates in UAE flexible PVC applications.
Adipates hold installed capacity across Gulf petrochemical downstream complexes. Citrates are rotating up the share rankings on regulatory migration pressure.
End User:
Construction sector procurement dominates volume allocation, though medical and automotive specifications concentrate technical service investment.
- Construction:Flexible PVC sheathing for Saudi Aramco power infrastructure and Emirates Global Aluminium distribution networks requires heat-stable adipate and sebacate formulations. Dubai Electricity and Water Authority mandates pre-certified plasticizer portfolios with documented aging performance.
- Automotive:Underhood applications impose volatility ceilings below 0.1% that standard adipates fail to meet, limiting non-phthalate penetration to interior trim and wire insulation.
- Consumer Goods:SASO child-product safety assessments exclude DEHP, redirecting toy and childcare article compounders toward certified adipate alternatives with third-party migration documentation.
- Electronics:Cable jacketing for data center and telecommunications infrastructure in Jebel Ali free trade zones specification-ties procurement to low-smoke zero-halogen compatible plasticizer grades.
Construction absorbs the heaviest volume flows. Automotive represents the steepest specification barrier for chemistry expansion.
Application:
Flexible PVC compounding captures the bulk of formulation value, though sealants and adhesives retain specialty margin pools.
- Flexible PVC:Suspension-grade resin systems plasticized with adipate and sebacate esters maintain tensile elongation above 300% in finished Gulf construction cables. Heat-aging requirements at 105°C for 40-year service life specifications fragment supplier hierarchies toward polymeric alternatives.
- Coatings:Plastisol and organosol formulations for flooring and wall covering applications in Saudi commercial real estate projects concentrate demand in fast-fusing adipate grades.
- Sealants:Hydrolytic stability requirements in North African infrastructure projects command premium sebacate positioning over standard adipate offerings.
- Adhesives:Pressure-sensitive and construction adhesive compounds leverage citrate plasticizers where food-contact and child-product safety certifications overlap.
Flexible PVC holds installed capacity across regional compounding networks. Sealants are climbing the fastest on infrastructure durability specifications.
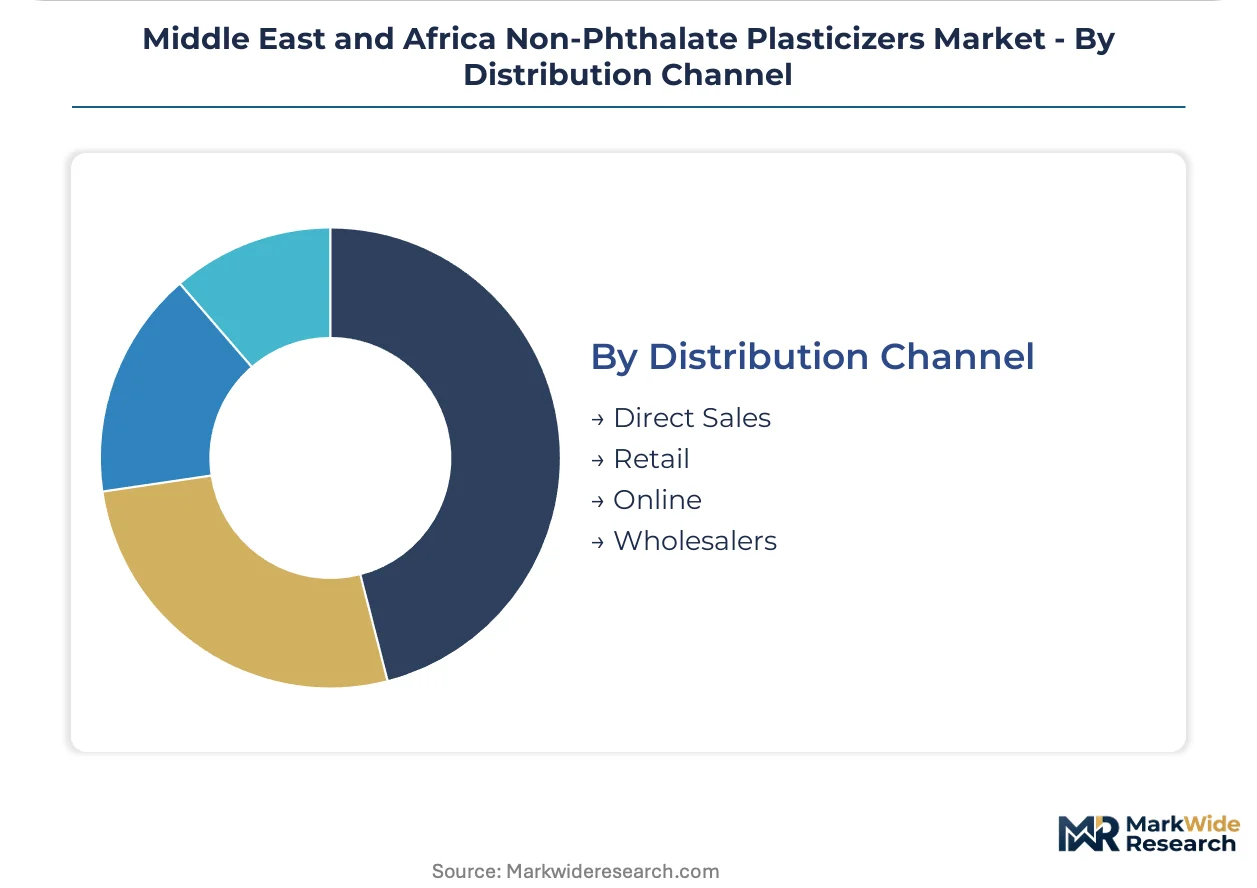
Distribution Channel:
Direct technical service relationships concentrate margin capture, while wholesale and digital channels compress qualification timelines.
- Direct Sales:BASF and Eastman technical service teams co-locate with Saudi converter networks to manage formulation qualification and certification documentation. Pre-certified adipate-sebacate portfolios displace multi-supplier blending strategies at Saudi Electricity Company procurement.
- Retail:Specialty chemical distributors in Jebel Ali trading hubs stock food-contact-grade citrates for smaller packaging converters without direct producer relationships.
- Online:Digital technical service platforms and certification documentation portals reduce Gulf compounder qualification timelines from months to weeks.
- Wholesalers:Nile Delta cable and film manufacturing clusters in Egypt remain underpenetrated by certified suppliers, creating first-mover positioning for pre-qualified adipate distributors with wholesale reach.
Direct sales holds relationship lock-in with major compounders. Online channels are gaining share fastest on qualification efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical downstream investments concentrate formulation supply chains in Saudi Arabia and the United Arab Emirates, while regulatory divergence between Gulf Standards Organization harmonization and South African national enforcement creates multi-jurisdiction complexity for suppliers.
Saudi Arabia
Saudi Electricity Company cable specifications drive adipate-grade demand for infrastructure power distribution. SASO technical regulations mandate child-product safety assessments that exclude conventional DEHP, redirecting compounders toward certified alternatives. Jubail Industrial City hosts expanding specialty chemical capacity as Aramco downstream ventures integrate plasticizer production.
United Arab Emirates
Dubai Electricity and Water Authority procurement mandates pre-certified plasticizer portfolios with documented heat-aging performance. Jebel Ali free trade zones concentrate chemical trading and distribution infrastructure for regional converter networks. Emirates Global Aluminium power infrastructure projects specify polymeric grades for 40-year service life requirements.
South Africa
Pharmaceutical packaging converters accelerate citrate qualification programs for IV bag and tubing applications ahead of EU MDR alignment. The National Regulator for Compulsory Specifications enforces phthalate restrictions aligned with EU REACH Annex XVII thresholds. Gauteng industrial corridors host medical-grade compounders serving sub-Saharan export markets.
Egypt
Nile Delta cable and film manufacturing clusters remain underpenetrated by certified non-phthalate suppliers. GSO migration limits for food-contact applications create compliance pressure on packaging converters. Alexandria and Damietta port zones handle growing volumes of suspension-grade PVC resin imports for domestic compounding.
Morocco
Casablanca-Rabat industrial zones serve as gateway for sebacate formulations targeting North African infrastructure projects. Hydrolytic stability specifications in cable compounds command premium positioning over standard adipate offerings. Tangier Med port logistics support just-in-time delivery to Spanish and French converter networks.
Middle East and Africa Non-Phthalate Plasticizers Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing integrated adipic acid and sebacic acid supply chains. European-headquartered multinationals anchor technical service relationships through co-located formulation support teams. Three archetypes dominate: petrochemical-integrated producers with captive feedstock, specialty ester houses with medical-grade certification depth, and regional distributors with Gulf customs zone warehousing. Competitive moves center on backward integration into castor oil derivative sourcing and digital certification platform deployment.
Within the European-headquartered tier, BASF SE and Evonik Industries AG exemplify archetypes differentiated by technical service reach. Eastman Chemical Company anchors the specialty ester segment with dedicated regional distribution infrastructure. These three entities represent the dominant competitive anchors shaping qualification timelines and specification-setting behavior across Saudi converter networks and South African pharmaceutical packaging channels.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Evonik Industries AG |
| LANXESS |
| Arkema Inc. |
| Avient Corporation |
| DIC CORPORATION |
| Perstorp |
| ExxonMobil Chemical Company |
| Others |
Supply & Pricing Matrix
Aramco downstream capacity utilization at Jubail Industrial City creates scale economies that compress adipate-grade price floors while elevating barriers for non-integrated compounders. Gulf petrochemical reactor expansions concentrate formulation supply in Saudi Arabia and the United Arab Emirates, redirecting procurement power toward buyers with pre-certified portfolios and documented heat-aging performance.
Pricing Analysis
SASO technical regulations dictate the pricing tier structure across child-product and food-contact segments, separating certified adipate-sebacate portfolios from uncertified commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with medical-grade citrates commanding spreads over construction-tier adipates. Pricing pressure stems from castor oil derivative volatility feeding into sebacate production costs. Small Egyptian packaging converters exhibit highest price sensitivity, while Saudi Electricity Company procurement teams prioritize specification compliance over unit economics.
Supply Chain Analysis
Inventory lead times for sebacic acid derivatives extend to 8-12 weeks due to agricultural processing concentration in India and Brazil. Raw material supply draws from castor oil cultivation in Gujarat and Bahia, adipic acid from Gulf petrochemical complexes, and citric acid fermentation capacity in China. Single-source vulnerability sits with castor oil derivative supply chains exposed to monsoon disruption and export restriction risk. Distribution runs through Jebel Ali chemical trading hubs for regional converter networks, with direct technical service relationships capturing premium positioning at Saudi compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-phthalate plasticizer penetration across Middle East and Africa cable and film applications sits at early-cycle expansion, with SASO and GSO regulatory alignment accelerating reformulation timelines ahead of full enforcement.
For Market Incumbents: Consolidate technical service relationships through co-located formulation support at Saudi converter networks, defending against polymeric plasticizer fragmentation in 40-year cable specifications. Backward integration into castor oil derivative sourcing mitigates sebacate margin erosion from Indian agricultural volatility. Pre-certified portfolio depth creates switching-cost barriers against emerging regional compounders. For New Entrants and Emerging Players: SASO fast-track certification for child-product adipate grades opens procurement access at Saudi toy and childcare article compounders. Egyptian Nile Delta cable manufacturing clusters remain underpenetrated by certified suppliers, offering first-mover positioning through wholesale distribution partnerships. Digital technical service platforms compress qualification timelines from months to weeks, enabling remote formulation support without European technical service dependencies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty ester houses with medical-grade certification depth over commodity adipate producers facing polymeric substitution. Long-term viability hinges on migration-limit regulatory convergence across Gulf Standards Organization and South African enforcement timelines. Watch for divergence between SASO and National Regulator for Compulsory Specifications certification timelines as inflection indicator for technical service resource allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Derivatives | Secures sebacate feedstock against Indian agricultural volatility for North African cable compounds. |
| Digital Certification Platform Deployment | Reduces Gulf compounder qualification timelines through remote technical documentation access. |
| Medical-Grade Citrate Capacity Expansion | Captures South African pharmaceutical packaging demand ahead of EU MDR alignment completion. |
| Joint Venture with Gulf Petrochemical Downstream | Locks in adipic acid supply at Jubail Industrial City for construction cable volume. |
| Long-term Supply Agreement with Saudi Electricity Company | Secures 40-year specification lock-in through pre-certified heat-aging documentation. |
Research Methodology
Initial hypotheses were tested against primary input from PVC compounding plant managers, procurement leads at Saudi cable manufacturers, Gulf chemical distribution channel partners, and technical R&D directors at specialty ester producers, then refined against customs trade data, Gulf petrochemical capacity disclosures, SASO regulatory filings, and SEC 10-K chemical segment reports. Bottom-up volume estimates from converter consumption patterns were triangulated with top-down petrochemical production capacity analysis.
Variance decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from segmented adoption curves incorporating cable sheathing demand from Saudi Aramco infrastructure projects, food-contact film migration-limit compliance costs, and medical-grade citrate qualification timelines at South African pharmaceutical packaging converters.
Decision-makers should treat outputs as directional under sustained SASO-GSO regulatory convergence and stable castor oil derivative trade flows; material deviation in enforcement timelines or sebacic acid supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Europe Starch Derivatives Market