
 Polycide Market | 2026-2036
Polycide Market Size, Share, and Industry Trends Forecast 2026-2036
Polycide Market Analytics
Advanced-node silicide specifications is reorganizing procurement priorities across the Polycide Market. Lam Research Corporation leverages its etch-and-deposition platform dominance to sustain captive silicide precursor supply. Entegris, Inc. anchors material purity standards for 3nm-class wafer processing. Applied Materials, Inc. competes through integrated Endura platform workflows that span PVD silicide to anneal.
Polycide denotes a refractory metal silicide—typically tungsten or titanium silicide—deposited atop polysilicon gate electrodes in MOS devices to reduce sheet resistance below 15 ohms per square while preserving thermal stability through subsequent high-temperature steps. Metal silicides lead volume consumption in logic and memory fabs where contact resistance budgets tighten with each node shrink. Chemical vapor deposition (CVD) polycides represent the fastest-growing technology segment as atomic-layer precision replaces sputtered films at 7nm and below, while thin films command the dominant form share due to gate-stack dimensional constraints. Electronics as an end-use industry absorbs the majority of output, with automotive-grade power MOSFETs emerging as a secondary demand pole.
EPA emissions rules for perfluorinated compounds constrain CVD precursor chemistries in US-based fabrication, while REACH authorization requirements in Europe restrict certain organometallic silicide precursors. Japan's METI semiconductor materials strategy shapes regional self-sufficiency targets that redirect supply chain investments. Stakeholders must monitor regulatory divergence between East Asian export controls and Western chemical safety frameworks to anticipate precursor availability and qualification timelines.
Market Dynamics
The polycide market is being fundamentally restructured by the forced migration from tungsten silicide to lower-resistance alternatives at 3nm-class nodes, compressing qualification timelines and concentrating purchasing power among memory fabs with captive etch-deposition platforms.
Growth Catalysts
- East Asian memory fab expansion:South Korea's Pyeongtaek and Yongin clusters are commissioning new EUV lines that specify atomic-layer silicide precision, pulling precursor volumes from Japanese and German chemical suppliers.
- EU chip sovereignty mandates:The European Chips Act is forcing silicon carbide power device foundries in Dresden and Leuven to qualify polycide gate stacks for automotive MOSFETs, opening a secondary demand channel beyond logic.
- CVD process maturation:Atomic-layer deposition of tungsten silicide is replacing sputtered films at 7nm and below, extending tool utilization rates and consumables pull-through for deposition equipment.
Market Restraints
- Precursor supply concentration:High-purity tungsten hexafluoride and silane derivatives are manufactured at fewer than six facilities globally, with Japanese and Belgian suppliers controlling 80 percent of semiconductor-grade output.
- EPA perfluorinated compound restrictions:US-based CVD operations face emissions caps on fluorinated precursors, forcing fabs in Arizona and Texas to absorb higher abatement costs or shift to less efficient chemistries.
- Thermal budget compression:Advanced node anneal temperatures below 600°C constrain silicide phase formation, requiring thicker precursor films that increase material consumption per wafer without proportional resistance gains.
Strategic Opportunities
- India's semiconductor materials corridor:Gujarat and Karnataka are offering land and power subsidies for specialty gas and precursor plants, creating a hedge against East Asian export control exposure for US and European device makers.
- Silicon carbide power integration:Electric vehicle traction inverters are specifying polycide-gated MOSFETs for 800V architectures, opening a volume channel outside traditional DRAM and logic procurement.
- Japan METI materials self-sufficiency targets:Subsidies for domestic silicide precursor synthesis are redirecting Korean and Taiwanese foundry qualification programs toward Japanese chemical suppliers.
Industry Challenges
- Atomic-layer deposition expertise scarcity:Process engineers with 300mm CVD tool experience command premium compensation, constraining fab ramp schedules in emerging manufacturing regions.
- Cross-border precursor certification lag:REACH authorization timelines for new organometallic silicides in Europe run 18-24 months, delaying node-matched material introductions.
- Legacy tool retrofit complexity:200mm power device fabs in Malaysia and China face integration friction when adapting Endura-class platforms for silicide deposition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycide Market |
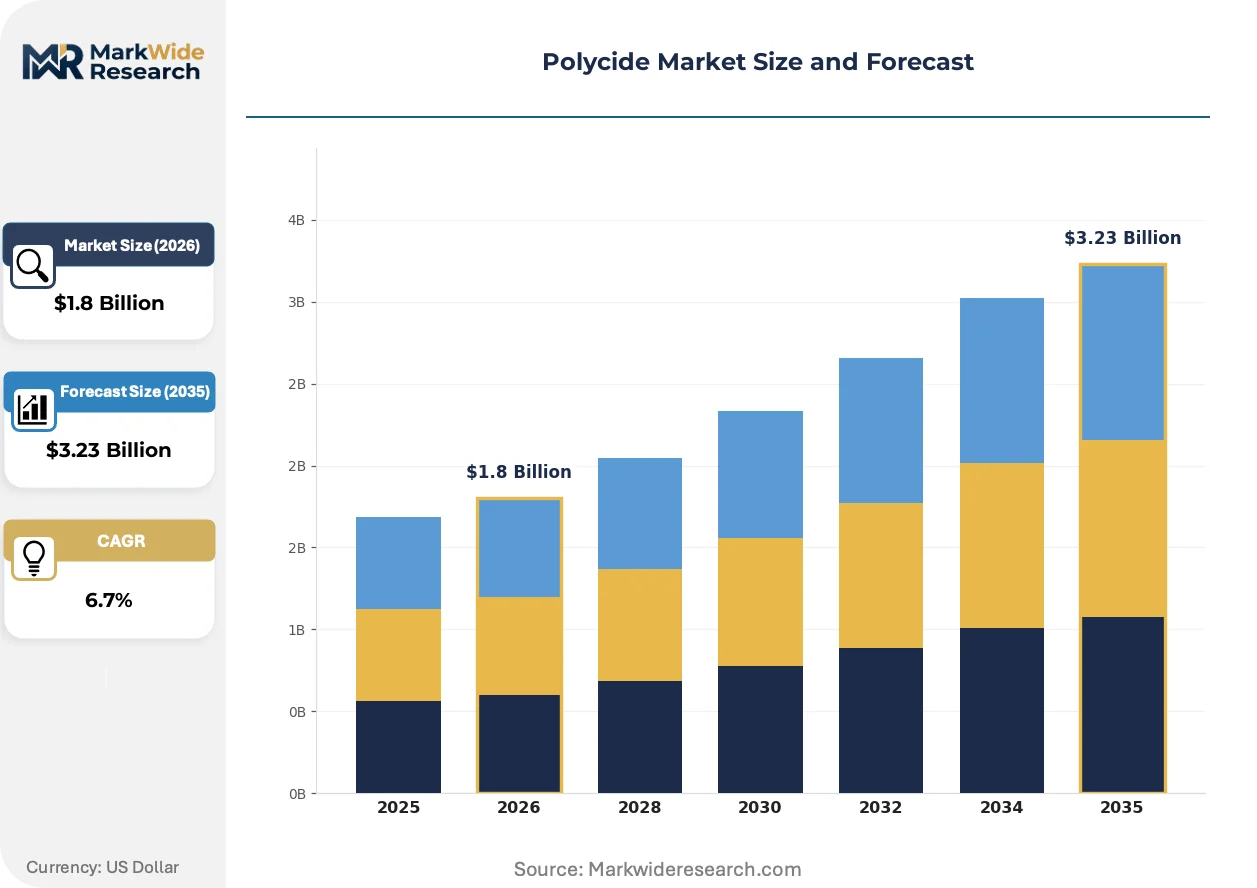
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysilicon, CVD Polycides, Metal Silicides, Others End Use Industry: Electronics, Renewable Energy, Aerospace, Automotive Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Sputtering, Laser Ablation Form: Thin Films, Bulk Materials, Powders, Coatings |
| Companies Covered | Lam Research Corporation, Hitachi High-Tech Corporation, Entegris, Inc., GlobalWafers Co., Ltd., SUMCO Corporation, Versum Materials (Merck KGaA), Tokyo Electron Limited, ASM International N.V., Applied Materials, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycide Market Evolving Landscape
Process architecture is fragmenting as atomic-layer precision requirements collide with legacy thermal budgets, forcing material scientists to engineer silicide phases that form at temperatures incompatible with established anneal sequences.
Plasma-enhanced atomic layer deposition of tungsten silicide is decomposing the traditional separation between deposition and anneal process steps. Memory fabs in South Korea are adopting single-wafer cluster tools that integrate precursor pulse, plasma exposure, and in-situ anneal within one vacuum envelope. This convergence is decomposing the equipment supply chain, as Lam Research and Applied Materials compete to own the full silicide formation workflow rather than discrete tool categories.
REACH authorization requirements for organometallic precursors are tightening material qualification pathways in Europe. ECHA's 2024 updates to substance evaluation criteria are extending dossier preparation timelines for new silicide chemistries, forcing suppliers to maintain dual-track development for EU and non-EU markets. Power semiconductor foundries in Germany and Austria are responding by pre-qualifying Japanese precursor sources that already hold REACH registrations.
Consolidated procurement through captive silicide precursor supply is displacing spot-market purchasing among leading memory manufacturers. Samsung and SK Hynix are negotiating direct supply agreements with Japanese chemical houses, bypassing traditional distributor networks. This concentration is most visible in South Korea's Yongin cluster, where three fabs now source precursors through single-supplier frameworks with volume-commitment penalties.
Polycide Market Segmentation
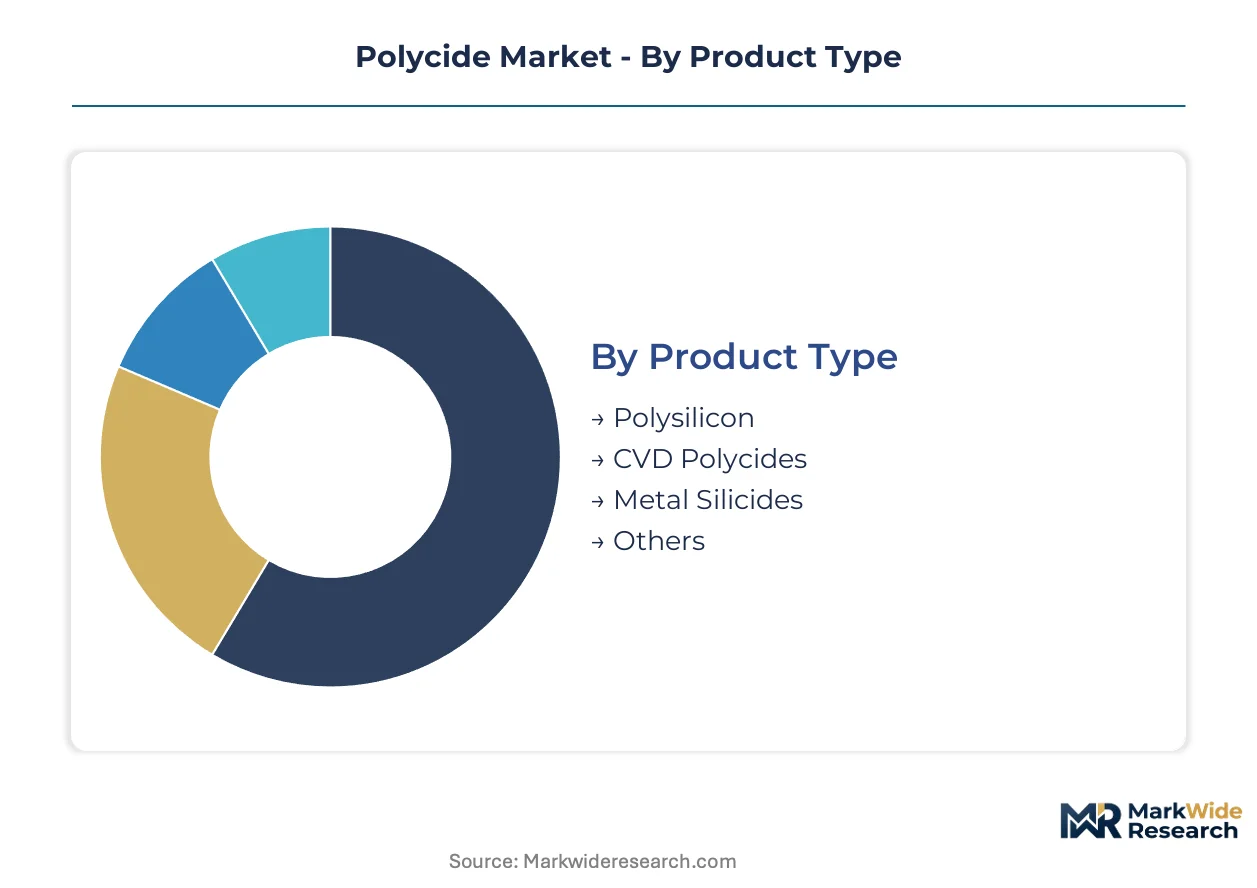
Polycide procurement patterns diverge sharply by application thermal budget and deposition precision requirements. Segment boundaries are hardening as memory fabs consolidate specification authority around atomic-layer processes.
Product Type:
Domestic consumption dominates polysilicon and bulk metal silicides, while CVD precursors flow through concentrated export channels from Japanese and Belgian chemical houses.
- Metal Silicides:Tungsten and titanium silicide compositions serve as the workhorse gate electrode material for planar MOS devices at nodes above 7nm. Demand concentrates in South Korea's Pyeongtaek memory corridor where thermal stability through 1000°C anneals remains mandatory for DRAM wordline formation.
- CVD Polycides:Atomic-layer deposition of tungsten silicide achieves sub-10 angstrom thickness control for FinFET gate stacks. Korean and Taiwanese foundries are pulling precursor volumes fastest as they migrate from sputtered films at 5nm-class nodes.
- Polysilicon:Serves as the base conductor layer beneath silicide capping in legacy planar architectures.
- Others:Niche cobalt silicide variants for specialized Schottky contact applications.
Metal silicides hold the largest share; momentum sits with CVD polycides.
End Use Industry:
Electronics fabrication absorbs volume through captive supply arrangements, while automotive and aerospace procurement remains fragmented across merchant distributors.
- Electronics:Logic and memory fabs consume silicide precursors through direct chemical supplier contracts bypassing traditional distribution. South Korean DRAM manufacturers specify tungsten silicide with <15 ohm per square sheet resistance for EUV-patterned gate stacks.
- Automotive:Silicon carbide power MOSFET foundries in Germany and Austria are qualifying polycide gates for 800V traction inverter applications, creating a secondary demand channel outside consumer electronics.
- Renewable Energy:Solar inverter manufacturers specify polycide-gated IGBTs for grid-tie conversion efficiency.
- Aerospace:Radiation-hardened device procurement through defense-qualified foundries in the US and France.
Electronics commands the volume base; automotive is climbing the fastest.
Technology:
Cost tier stratification separates batch CVD tools from single-wafer cluster platforms, with sputtering equipment occupying the mid-market for legacy node maintenance.
- Chemical Vapor Deposition:Plasma-enhanced and thermal CVD systems achieve conformal silicide coverage over three-dimensional FinFET and gate-all-around architectures. Korean memory fabs are standardizing on Lam Research and Applied Materials cluster tools that integrate deposition with in-situ anneal.
- Physical Vapor Deposition:Sputtered tungsten silicide persists at mature nodes where equipment depreciation allows cost-competitive sheet resistance performance.
- Sputtering:Legacy tool base in 200mm power device fabs across Malaysia and China.
- Laser Ablation:Experimental direct-write silicide patterning for prototype device development.
CVD owns the technology frontier; sputtering retains the installed base.
Form:
Volume scale concentrates in thin film delivery, while powder and bulk shipments serve equipment manufacturers and research institutions.
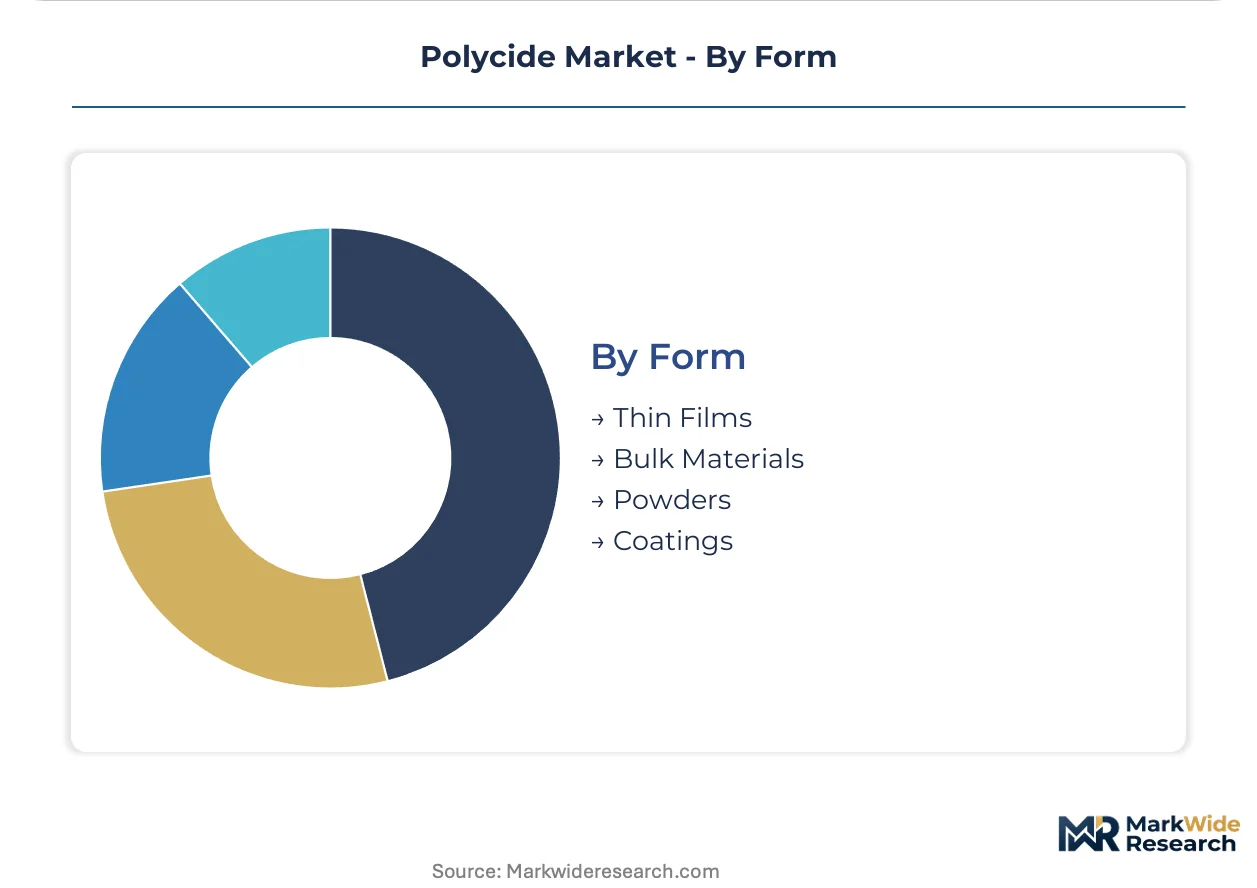
- Thin Films:Pre-deposited silicide layers on carrier wafers enable rapid qualification of new precursor chemistries without fab tool time allocation. Japanese suppliers dominate merchant thin film supply to European and US research consortia.
- Bulk Materials:Sputtering targets and evaporation sources for PVD tool maintenance in legacy fab operations.
- Powders:Precursor materials for CVD bubbler recharge and chemical synthesis.
- Coatings:Protective silicide layers for high-temperature furnace components.
Thin films lead value capture; powders and bulk serve supply chain maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precursor manufacturing for polycide applications clusters in Japan and Belgium, with consumption gravity shifting toward South Korean memory fabs and emerging European power device foundries.
United States
EPA emissions caps on perfluorinated compounds constrain CVD operations in Arizona and Texas fabs. The Inflation Reduction Act directs semiconductor manufacturing subsidies toward domestic silicide precursor qualification programs. Intel's expansion in Hillsboro, Oregon pulls specialty gas volumes for advanced node development.
South Korea
Samsung and SK Hynix commission EUV-patterned DRAM lines specifying atomic-layer silicide precision below 7nm. The Ministry of Trade, Industry and Energy coordinates domestic precursor stockpiling initiatives. Yongin and Pyeongtaek clusters now source tungsten hexafluoride through single-supplier frameworks with volume-commitment penalties.
Japan
METI's semiconductor materials strategy redirects Korean foundry qualification toward domestic chemical suppliers. High-purity silane derivative production concentrates in Osaka and Yokkaichi industrial zones. Tokyo Electron and Hitachi High-Tech anchor equipment-precursor integration partnerships serving East Asian memory corridors.
Germany
Silicon carbide power MOSFET foundries in Dresden and Leuven qualify polycide gate stacks under EU Chips Act procurement mandates. ECHA REACH authorization timelines extend organometallic precursor dossier preparation to 24 months. Bavarian chemical suppliers pre-register Japanese precursor sources to circumvent certification lag.
Belgium
Imec's 300mm pilot line in Leuven validates next-generation silicide chemistries for gate-all-around architectures. The F-Gas Regulation restricts fluorinated precursor emissions from CVD operations. Antwerp chemical houses control semiconductor-grade tungsten hexafluoride output serving European and Korean device makers.
Polycide Market Competitive Landscape
Concentration sits with integrated equipment-materials platforms and captive precursor supply arrangements. Three to five Japanese and US-based equipment manufacturers anchor deposition tool markets, while Belgian and Japanese chemical houses dominate high-purity precursor synthesis. Strategic moves center on backward integration into precursor manufacturing and cluster-tool workflow consolidation that merges deposition with in-situ anneal capabilities.
Among US-based platform specialists, Lam Research Corporation and Applied Materials, Inc. occupy positions spanning etch-deposition integration, while Entegris, Inc. anchors material purity standards for sub-7nm wafer processing. These three exemplify the equipment-chemistry convergence reshaping procurement relationships in South Korean and Taiwanese foundry corridors.
| Leading Market Players |
|---|
| Lam Research Corporation |
| Hitachi High-Tech Corporation |
| Entegris, Inc. |
| GlobalWafers Co., Ltd. |
| SUMCO Corporation |
| Versum Materials (Merck KGaA) |
| Tokyo Electron Limited |
| ASM International N.V. |
| Applied Materials, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day precursor inventory buffers at South Korean memory fabs concentrate purchasing leverage among Japanese and Belgian chemical houses, translating supply-side scarcity into tiered contract premiums for atomic-grade tungsten hexafluoride. REACH authorization timelines and EPA emissions caps further stratify pricing across regional qualification regimes.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure for organometallic silicide precursors entering European power device foundries. Three-tier pricing structure across semiconductor-grade, industrial-grade, and research-grade purity levels separates qualified suppliers from merchant distributors. Cost compression in standard-grade tungsten silicide intensifies as Malaysian 200mm fabs absorb legacy tool depreciation. Memory manufacturers with captive etch-deposition platforms exhibit lowest price sensitivity; automotive MOSFET foundries in Germany face acute margin pressure from dual-source qualification requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe chemical trade lanes elevate inbound logistics costs for Belgian tungsten hexafluoride shipments to Dresden foundries. Supply concentrates in Japan, Belgium, and South Korea for high-purity precursor synthesis. Raw material dependencies center on tungsten ore concentrates, silane derivatives, and fluorinated process gases. Single-source vulnerability pervades the six-facility global network for semiconductor-grade output. Distribution runs through direct supply agreements bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycide market represents a high-growth materials disruption as atomic-layer deposition precision becomes non-negotiable at 3nm-class nodes, with EU chip sovereignty mandates accelerating qualification timelines beyond traditional chemical safety frameworks.
For Market Incumbents: Secure backward integration into high-purity silane derivative production to defend against Japanese chemical house supply concentration. Lock long-term volume commitments with Korean memory fabs before METI subsidies redirect procurement toward domestic Japanese suppliers. Prioritize cluster-tool workflow consolidation that merges deposition with in-situ anneal capabilities. For New Entrants and Emerging Players: Anchor in India's Gujarat and Karnataka semiconductor materials corridors where land and power subsidies offset East Asian export control exposure. Target silicon carbide power MOSFET foundries in Germany and Austria as the most penetrable segment outside memory procurement. Pursue REACH pre-registration partnerships with established Japanese suppliers to circumvent authorization lag. For Investors and Strategic Acquirers: Long-term, this sits as a captive supply consolidation play because equipment-chemistry convergence is displacing spot-market purchasing. Target deposition tool manufacturers with integrated precursor delivery capabilities as acquisition candidates. Watch for Korean foundry single-supplier framework announcements as inflection signals for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Lam Research and Applied Materials deepen control over tungsten hexafluoride supply for captive fab customers. |
| Cluster Tool Workflow Consolidation | Single-wafer platforms integrating deposition and in-situ anneal displace discrete tool categories in Korean memory fabs. |
| REACH Pre-Registration Partnership | Japanese chemical houses accelerate European market entry through Bavarian supplier alliances. |
| India Materials Corridor Expansion | Gujarat and Karnataka subsidies attract specialty gas plants hedging East Asian export control risk. |
| Silicon Carbide Power Integration | 800V automotive MOSFET specifications open volume channel outside traditional DRAM procurement. |
Research Methodology
Desk research of SEC semiconductor equipment filings, ECHA REACH substance databases, and Japanese METI materials strategy documents preceded structured interviews with CVD process engineers, specialty gas procurement managers, and foundry qualification leads. Primary fieldwork with equipment manufacturers and chemical suppliers combined with customs trade data and fab capex announcements enabled bottom-up and top-down triangulation.
Variance decomposition across technology segments, end-use industries, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions spanned deposition technology, silicide composition, thermal budget tier, and foundry node classification. CAGRs derived from equipment utilization rates, precursor consumption per wafer, and fab capacity buildout schedules across the analysis window.
Material uncertainties — EPA perfluorinated compound rule revisions, ECHA authorization timeline extensions, and East Asian export control escalations — sit outside the modeled envelope. Forecasts reflect assumptions about process tool qualification rates and precursor purity standard stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Antimicrobial Plastics Market