
 Microcellular Plastics Market | 2026-2036
Microcellular Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Microcellular Plastics Market Analysis
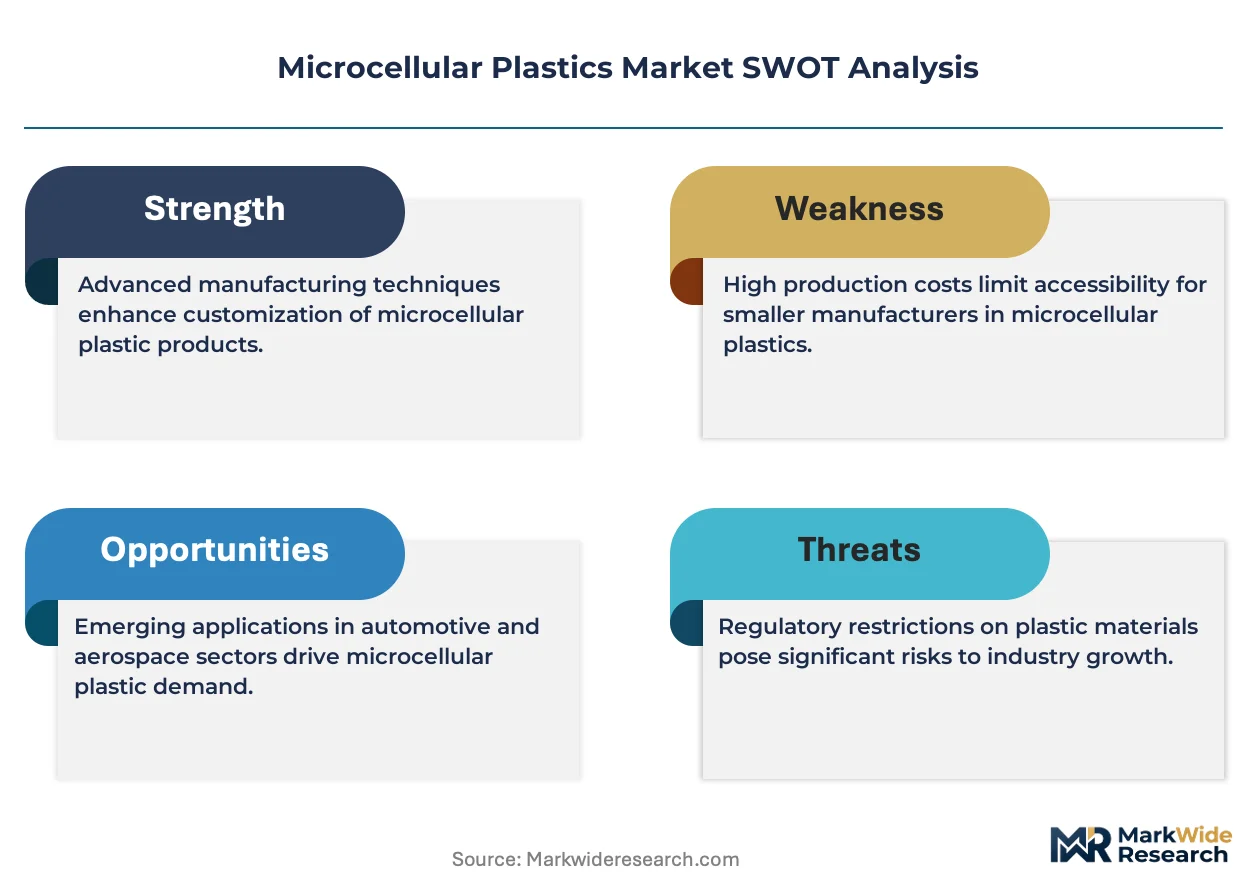
Asset-light leasing models for supercritical fluid injection equipment is fragmenting competitive entry barriers across the microcellular plastics value chain. Trexel Inc. leverages its proprietary MuCell licensing platform to extend process control without captive machinery ownership. BASF SE anchors large-scale polypropylene supply through backward integration into catalyst technology. Rogers Corporation specializes in high-performance silicone-foam laminates for thermal management applications.
Microcellular plastics are thermoplastic materials containing cells typically 1–100 micrometers in diameter, produced via controlled gas saturation and nucleation to achieve density reductions of 5–95% while retaining structural integrity. Physical foaming with supercritical CO2 or N2 dominates current industrial practice due to its elimination of chemical residuals, though water-based foaming is gaining traction in packaging applications seeking to eliminate volatile organic compound exposure. Polycarbonate grades command premium positioning in medical device housings where gamma sterilization compatibility is required, while polystyrene remains volume-dominant in consumer goods due to mature extrusion infrastructure and lower raw material costs.
The EPA regulates blowing agent emissions under Significant New Alternatives Policy frameworks, while OSHA mandates workplace exposure limits for isocyanates and azodicarbonamide decomposition products in chemical foaming operations. REACH restrictions on persistent organic pollutants constrain halogenated flame retardant selection in European electronics applications, redirecting formulation investment toward phosphorus-based systems. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds appear in surfactants used during nucleation control.
Market Dynamics
Automotive OEMs are consolidating their microcellular plastics sourcing around supercritical fluid injection platforms, creating asymmetric power dynamics between licensed process technology providers and compounders lacking proprietary nucleation control.
Growth Catalysts
- EU Green Deal material mandates:Brussels-based automotive assemblers face binding weight reduction targets that favor foamed polypropylene interior panels over dense ABS alternatives.
- Medical device sterilization protocols:Gamma-compatible polycarbonate grades from specialty compounders are capturing housing contracts previously held by standard thermoplastics.
- Water-based foaming chemistry:Packaging converters in food-contact applications are eliminating volatile organic compound exposure through CO2 and steam nucleation systems.
Market Restraints
- Supercritical equipment capex concentration:German and Japanese machinery builders control 70% of precision gas injection system manufacturing, creating supply bottlenecks.
- Azodicarbonamide decomposition hazards:OSHA workplace exposure limits for chemical foaming byproducts constrain US-based extrusion operations.
- Halogenated flame retardant substitution:REACH restrictions on persistent organic pollutants force electronics molders toward unproven phosphorus-based systems.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for lightweighting are attracting microcellular PP compounders to Chennai and Pune manufacturing corridors.
- Silicone-foam thermal interface materials:Battery pack manufacturers are specifying microcellular silicone laminates for electric vehicle thermal management.
- Asset-light licensing platforms:Process technology vendors are decoupling equipment ownership from nucleation expertise, lowering entry barriers for regional compounders.
Industry Challenges
- Supercritical fluid process engineering talent:The shortage of technicians trained in gas saturation pressure control limits plant expansion timelines.
- Per- and polyfluoroalkyl substance compliance:Evolving surfactant restrictions across multiple jurisdictions complicate nucleation additive selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcellular Plastics Market |
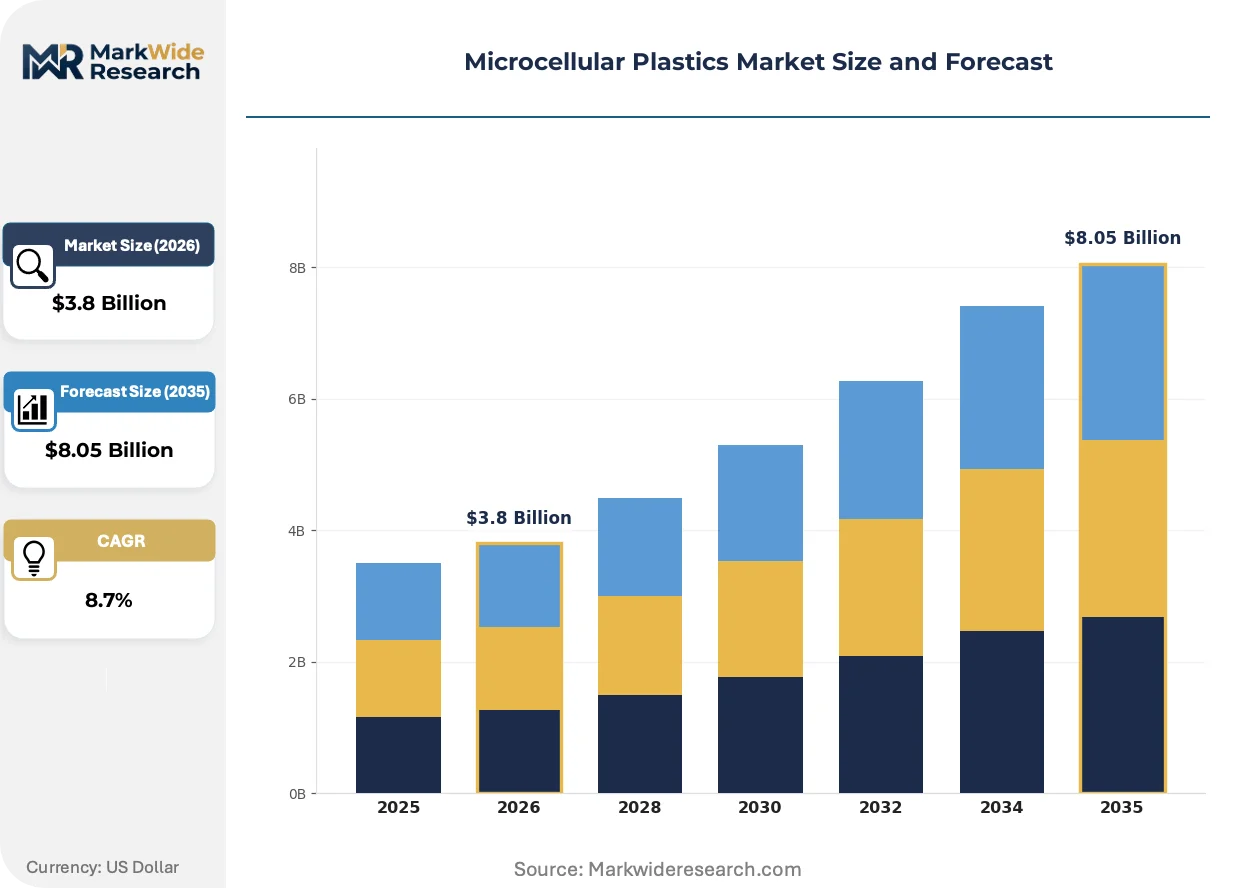
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, Polystyrene, ABS Application: Automotive Interiors, Packaging, Consumer Goods, Electronics Technology: Physical Foaming, Chemical Foaming, Water-Based Foaming, Gas-Assisted Technology Industry Vertical: Aerospace, Industrial Manufacturing, Medical Devices, Construction |
| Companies Covered | BASF SE, Rogers Corporation, INOAC CORPORATION, Armacell, Trexel Inc., Saint-Gobain, Evonik Industries AG, SABIC, General Plastics Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcellular Plastics Market Emerging Trajectories
Physical foaming with supercritical CO2 is displacing legacy chemical blowing agents across packaging and automotive tiers, while regulatory pressure on persistent organic pollutants accelerates formulation chemistry turnover.
Continuous extrusion systems integrating real-time density feedback are rendering obsolete batch autoclave methods for medical-grade polycarbonate sheet production. Tier 1 automotive suppliers in Stuttgart and Wolfsburg are commissioning these lines for instrument panel substrates. The shift compresses lead times from days to hours while eliminating cell-size variability that previously required manual inspection.
REACH restrictions on halogenated flame retardants are forcing electronics enclosure molders toward phosphorus-based systems with unproven long-term aging performance. ECHA substance evaluation timelines create 18-24 month formulation lock-in periods. German compounders are responding with collaborative pre-certification testing pools to share validation costs.
Leasing arrangements for gas injection equipment are displacing traditional machinery purchase models among mid-volume automotive suppliers. Trexel's MuCell platform anchors this shift, allowing compounders to access process control without captive capital deployment. The model concentrates most visibly among Stuttgart-area Tier 2 suppliers serving Mercedes-Benz and Porsche assembly networks.
Microcellular Plastics Market Segmentation
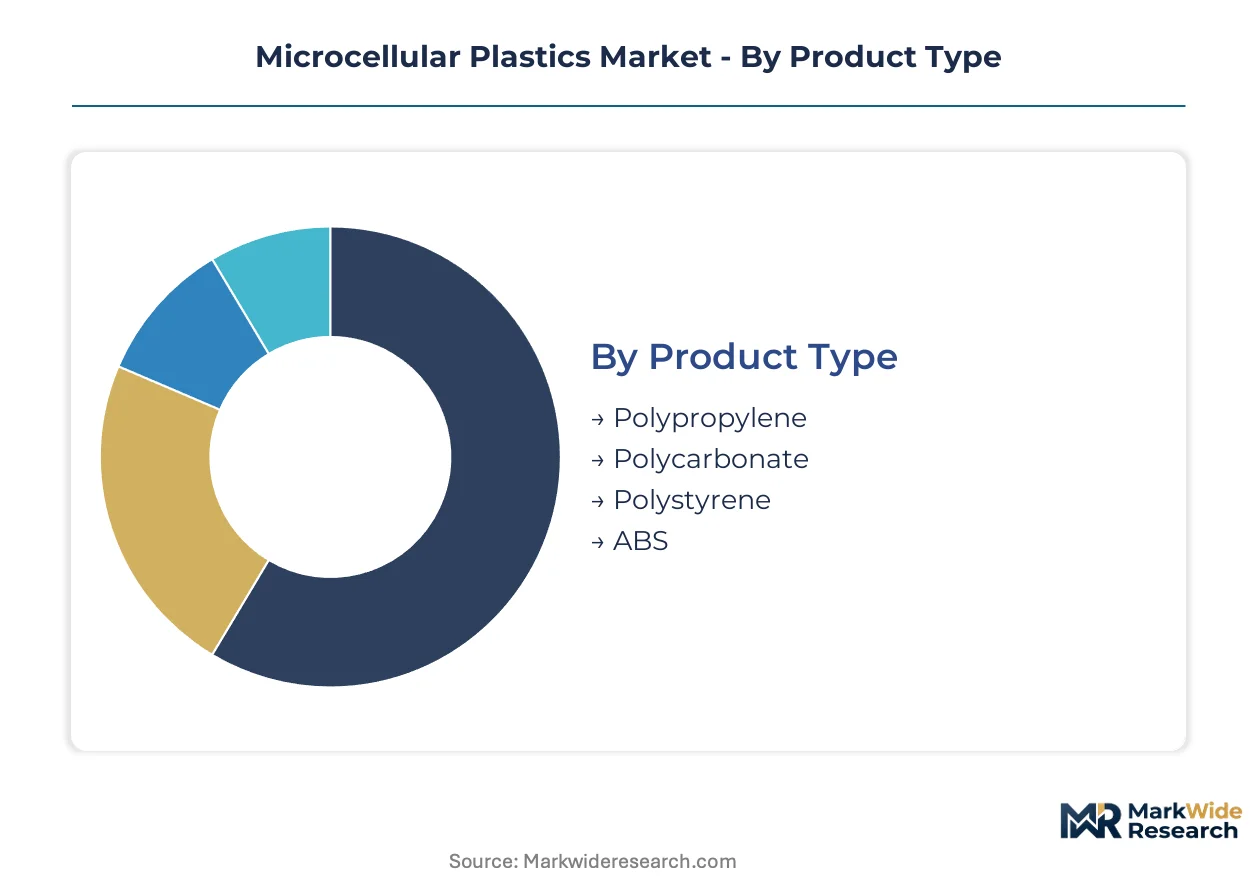
Microcellular plastics command divergent price premiums and technical specifications across material grades and conversion technologies. Understanding these segment boundaries reveals where formulation investments concentrate and which process platforms offer scalable entry points for compounders.
Product Type:
Material selection spans commodity thermoplastics optimized for density reduction through supercritical gas saturation to engineering grades demanding precise cell architecture for structural integrity.
- Polypropylene:Semi-crystalline thermoplastic with excellent chemical resistance and fatigue performance, foamed via supercritical CO2 injection to achieve 20-40% weight reduction in automotive interior panels. Demand clusters around Stuttgart and Wolfsburg manufacturing corridors where Mercedes-Benz and Volkswagen pursue EU Green Deal weight targets.
- Polycarbonate:Amorphous engineering polymer with inherent transparency and gamma sterilization compatibility, processed through continuous extrusion systems for medical device housings. German compounders are capturing contracts previously held by standard thermoplastics in diagnostic equipment enclosures.
- Polystyrene:Volume-dominant commodity resin leveraging mature extrusion infrastructure for consumer goods packaging, though REACH restrictions on chemical blowing agents are redirecting investment toward physical foaming retrofits.
- ABS:Terpolymer combining acrylonitrile, butadiene, and styrene for superior impact resistance and surface finish, utilized in electronics enclosures where phosphorus-based flame retardant systems are substituting halogenated alternatives under ECHA substance evaluations.
The dominant share belongs to polypropylene, while polycarbonate is closing the gap fastest.
Application:
End-use concentration follows regulatory pressure points and OEM lightweighting mandates across mobility, consumer, and industrial sectors.
- Automotive Interiors:Instrument panel substrates, door panels, and HVAC ducting specified by Tier 1 suppliers seeking 5-15% vehicle mass reduction. Stuttgart-area converters are commissioning continuous extrusion lines that compress lead times from days to hours.
- Packaging:Food-contact trays and protective cushioning eliminating volatile organic compound exposure through CO2 and steam nucleation systems. Water-based foaming chemistry is gaining traction among converters serving EU single-use plastics directives.
- Consumer Goods:Durable household products and sporting equipment exploiting mature polystyrene extrusion infrastructure with lower raw material costs, though sustainability pressures are accelerating material substitution toward bio-based alternatives.
- Electronics:Smartphone and laptop enclosures requiring halogen-free flame retardancy under REACH persistent organic pollutant restrictions, forcing molders toward unproven phosphorus-based systems with 18-24 month formulation lock-in periods.
Automotive interiors absorb the greatest volume, yet packaging applications are expanding most quickly as regulatory timelines tighten.
Technology:
Process platform selection determines capital intensity, cell-size precision, and regulatory compliance pathways for nucleation control.
- Physical Foaming:Supercritical CO2 or N2 saturation eliminating chemical residuals, now dominating industrial practice across automotive and medical tiers. German and Japanese machinery builders control 70% of precision gas injection system manufacturing.
- Chemical Foaming:Azodicarbonamide and other blowing agents constrained by OSHA workplace exposure limits for decomposition byproducts, retreating to cost-sensitive applications where equipment retrofit economics prove prohibitive.
- Water-Based Foaming:Steam nucleation systems gaining share in food-contact packaging seeking volatile organic compound elimination, with lower capital barriers than supercritical platforms.
- Gas-Assisted Technology:Nitrogen core-out methods for thick-walled structural components, deployed where hollow-channel designs substitute for solid cross-sections in industrial manufacturing.
Physical foaming commands the installed base, though water-based systems are climbing the fastest as converters prioritize chemical exposure reduction.
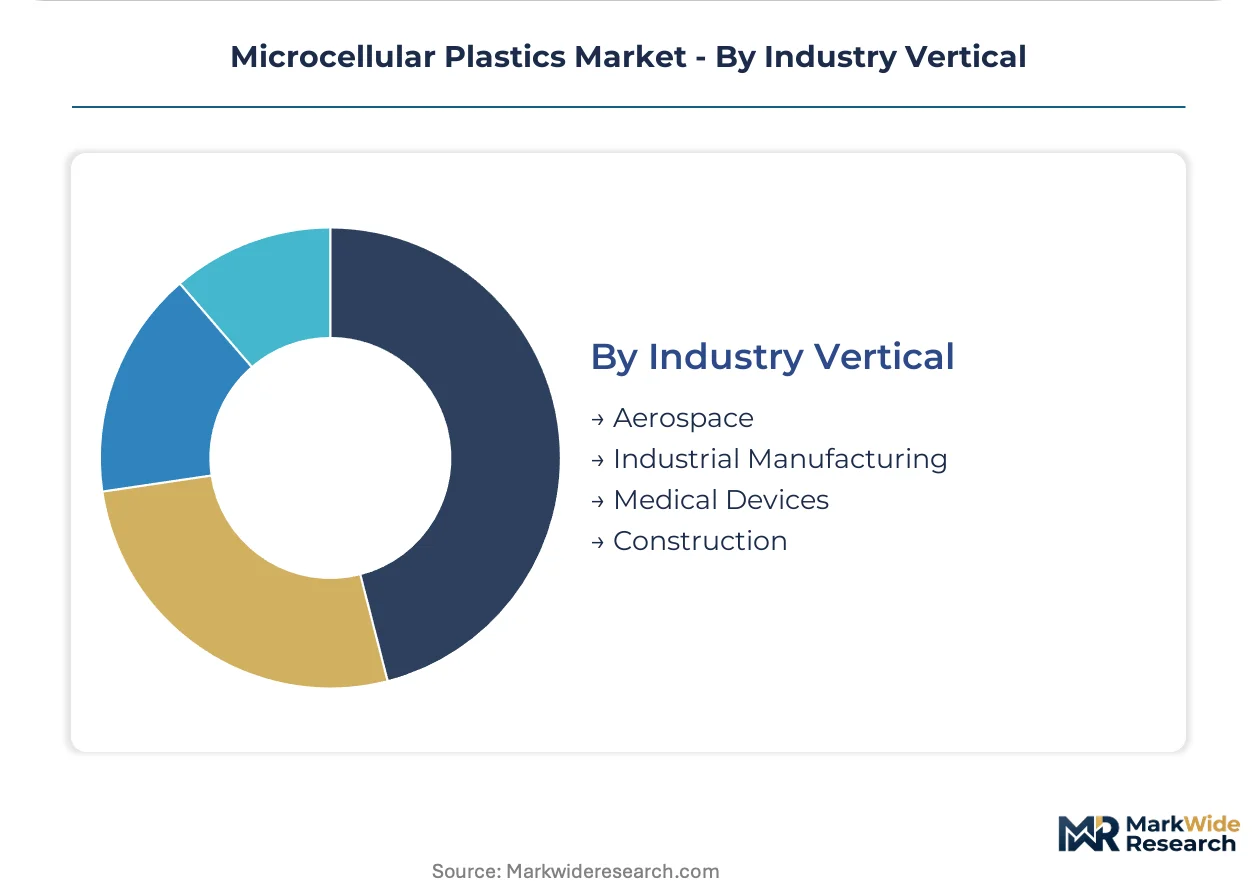
Industry Vertical:
Vertical penetration correlates with performance certification requirements and supply chain proximity to compounder technical service capabilities.
- Medical Devices:Gamma-sterilizable polycarbonate housings for diagnostic and surgical equipment, where FDA and EMA device regulations mandate material traceability and biocompatibility validation.
- Aerospace:Cabin interior panels and ducting meeting flame-smoke-toxicity standards, with Boeing and Airbus Tier 2 suppliers specifying microcellular thermoplastic substitutes for thermoset composites.
- Industrial Manufacturing:Material handling components and machinery housings exploiting density reduction for ergonomic and fuel efficiency gains in logistics equipment.
- Construction:Insulation boards and structural foam elements, though building code fire performance requirements lag material innovation cycles in most jurisdictions.
Medical devices generate the highest margin concentration, while aerospace applications are gaining share fastest as certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in microcellular plastics concentrate around machinery dependency and compounder proximity to automotive assembly networks. Germany and Japan maintain surplus positions in precision gas injection equipment, while importing regions compete for licensed process technology access.
Germany
Mercedes-Benz and Volkswagen weight reduction mandates absorb foamed polypropylene volumes across Stuttgart and Wolfsburg corridors. EU Green Deal binding targets accelerate substitution from dense ABS toward cellular alternatives in instrument panel substrates. Tier 1 suppliers commission continuous extrusion lines that compress medical-grade polycarbonate lead times from days to hours.
United States
EPA Significant New Alternatives Policy frameworks regulate blowing agent emissions while OSHA workplace exposure limits constrain azodicarbonamide decomposition hazards in chemical foaming operations. Medical device sterilization protocols drive gamma-compatible polycarbonate housing contracts toward specialty compounders. Southeast automotive suppliers pursue supercritical fluid platform licensing to serve transplant OEM assembly.
Japan
METI industrial standards shape nucleation control specifications for electronics enclosure molders substituting halogenated flame retardants. Precision machinery builders dominate 70% of global gas injection system manufacturing, creating asymmetric supply relationships with regional compounders. Kanto-based suppliers anchor physical foaming technology exports across Asia-Pacific packaging tiers.
India
PLI scheme incentives for automotive lightweighting attract microcellular PP compounders to Chennai and Pune manufacturing corridors. CDSCO medical device regulations mandate material traceability for diagnostic equipment housings seeking gamma sterilization compatibility. Domestic converters exploit lower capital barriers in water-based foaming retrofits for food-contact packaging applications.
China
MIIT dual carbon goals redirect industrial policy toward density-reduced materials in logistics equipment and consumer durables. NMPA medical device oversight elevates polycarbonate grade specifications for surgical instrument enclosures. Yangtze River Delta compounders integrate supercritical CO2 platforms to serve battery pack thermal management material demand from regional EV manufacturers.
Microcellular Plastics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in catalyst and nucleation additive supply. Market structure concentrates around licensed process technology providers and backward-integrated resin compounders, with mid-volume automotive suppliers fragmenting across leasing arrangements. Three archetypes dominate: machinery-anchored licensors, captive resin producers with catalyst control, and specialty foam laminators serving thermal management applications. Competitive moves center on equipment leasing model expansion and collaborative pre-certification testing pools to share REACH validation costs.
Within the platform licensing tier, Trexel Inc. exemplifies asset-light market entry facilitation through its MuCell system. BASF SE anchors large-scale polypropylene supply through in-house catalyst technology production. Rogers Corporation occupies a position among high-performance silicone-foam specialists targeting electric vehicle battery thermal interface specifications.
| Leading Market Players |
|---|
| BASF SE |
| Rogers Corporation |
| INOAC CORPORATION |
| Armacell |
| Trexel Inc. |
| Saint-Gobain |
| Evonik Industries AG |
| SABIC |
| General Plastics Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Japanese precision gas injection equipment determines both pricing tier spreads and supply chain shape across the microcellular plastics value chain. REACH chemical restrictions and OSHA workplace exposure mandates compress margins for compounders locked into legacy chemical foaming while rewarding licensed physical foaming operators with pricing power.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—gamma-sterilizable polycarbonate commands medical device premiums while commodity polystyrene serves cost-sensitive packaging. Pricing pressure stems from azodicarbonamide substitution costs as compounders absorb reformulation investment. Tier 1 automotive suppliers exhibit lowest price sensitivity due to EU Green Deal compliance mandates; mid-volume converters face acute margin compression from equipment leasing obligations.
Supply Chain Analysis
Tariff exposure between Germany and China dominates strategic planning for nucleation additive sourcing. Manufacturing gravity centers on Germany, Japan, and the United States for supercritical fluid injection systems. Raw material dependencies include catalyst-grade polypropylene, medical-grade polycarbonate resin, and phosphorus-based flame retardant precursors. Single-source vulnerability concentrates in precision gas injection valve assemblies. Distribution runs through licensed process technology platforms rather than traditional chemical distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microcellular plastics constitute a platform-economics inflection where Trexel's MuCell licensing ecosystem is displacing captive machinery ownership across automotive and medical tiers. Interoperability between gas saturation control and real-time density feedback systems is redefining competitive moats.
For Market Incumbents: Insulate process control advantages through deeper backward integration into catalyst technology and nucleation additive formulation. BASF's captive polypropylene supply demonstrates how resin compounders can lock out leasing-dependent challengers. Prioritize collaborative pre-certification testing pools to spread REACH validation costs across German compounder networks.
For New Entrants and Emerging Players: Establish a beachhead in water-based foaming retrofits for Indian food-contact packaging converters seeking lower capital barriers than supercritical platforms. Target Chennai and Pune automotive corridors where PLI scheme incentives concentrate lightweighting demand. Lead with CO2 and steam nucleation systems that eliminate volatile organic compound exposure for EU single-use plastics compliance.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors licensed process technology providers over machinery-dependent compounders. Long-term viability hinges on nucleation control IP rather than resin volume scale. Watch supercritical equipment leasing penetration rates as the inflection signal—acceleration indicates platform economics consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Technology | BASF anchors polypropylene supply through in-house catalyst production, locking out challengers. |
| Asset-Light Licensing Platform Expansion | Trexel's MuCell model decouples equipment ownership from nucleation expertise, fragmenting entry barriers. |
| Collaborative Pre-Certification Testing Pools | German compounders share REACH validation costs for phosphorus-based flame retardant systems. |
| Water-Based Foaming Retrofit Deployment | Indian converters exploit lower capital barriers to serve EU single-use plastics directives. |
| Silicone-Foam Thermal Interface Development | Rogers Corporation targets electric vehicle battery pack specifications for thermal management. |
Methodological Framework
Initial hypotheses were tested against primary input from supercritical fluid process engineers, Tier 1 automotive procurement managers, medical device regulatory affairs leads, and specialty compounder technical directors and refined through secondary validation. Sources included customs and trade flow data for machinery imports, ECHA substance evaluation timelines, SEC 10-K filings from resin producers, and ACC industry reports. Bottom-up triangulation across regional compounder capacity and top-down demand modeling from automotive OEM weight reduction targets converged on segment-level outputs.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included material grade tier, conversion technology platform, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from installed base expansion rates for gas injection equipment and substitution curves from chemical to physical foaming. Industry-specific inputs incorporated EU Green Deal binding targets, OSHA workplace exposure limit enforcement patterns, and REACH persistent organic pollutant restriction timelines.
Stress conditions across supercritical equipment capex cycles, azodicarbonamide substitution cost trajectories, and halogenated flame retardant phase-out schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about licensing platform penetration and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Sodium Polyacrylate Market