
 Global Nylon Market | 2026-2036
Global Nylon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nylon Market Outlook
Automotive engineers is rotating toward high-performance polyamide grades for under-hood thermal management and structural substitution. BASF SE leverages its integrated caprolactam chain to supply engineered nylon compounds with consistent melt-flow specifications for injection molders. Toray Industries anchors its position through filament specialization for airbag fabrics and tire cord reinforcement, sustaining premium pricing in safety-critical applications. Huntsman Corporation competes via differentiated nylon 6,6 formulations targeting electrical connector miniaturization in hybrid powertrains.
Nylon comprises synthetic polyamides formed through condensation polymerization of diamines and dicarboxylic acids, with nylon 6 and nylon 6,6 representing the dominant commercial grades distinguished by their monomer feedstocks and crystalline melting points between 220°C and 265°C. The material serves primarily as a high-strength, thermally resistant engineering thermoplastic and synthetic fiber across load-bearing and abrasion-intensive applications. Nylon 6,6 resin commands the largest value share due to its superior heat deflection temperature and established automotive specification approvals, while nylon 12 film exhibits the fastest growth trajectory driven by moisture-barrier pharmaceutical packaging and fuel-line tubing requirements. Fiber form maintains mature volume leadership in carpet and industrial textile applications, though resin form captures disproportionate margin pools through compounded engineering grades for metal replacement.
EPA fuel-economy standards and NHTSA safety regulations in the United States mandate material lightweighting that directly expands nylon penetration in powertrain and chassis components. ECHA REACH restrictions on short-chain chlorinated paraffins and phthalate plasticizers compel reformulation of legacy nylon compounds, elevating compliance costs for compounders serving European automotive and electrical markets. China's GB standards for automotive interior emissions and MIIT new energy vehicle production quotas simultaneously shape product specification requirements and volume demand curves. Stakeholders must monitor regulatory divergence between jurisdictions as diverging chemical hazard classifications threaten to fragment formulation platforms and complicate global supply chain qualification protocols.
Market Dynamics
Automotive lightweighting mandates and electric vehicle thermal management requirements are compressing metal-to-polymer substitution timelines across powertrain engineering. This structural pull is reorganizing formulation priorities and supply chain qualification protocols for engineering resin compounders.
Growth Catalysts
- EPA fuel-economy standards:Corporate Average Fuel Economy targets compel OEMs to replace aluminum and steel with glass-filled polyamide in chassis and under-hood components.
- Electric vehicle battery housings:Nylon 6,6 flame-retardant grades are penetrating EV thermal management systems as cell-to-pack architectures demand higher heat deflection materials.
- China MIIT production quotas:Domestic new energy vehicle manufacturing targets concentrate demand for locally qualified nylon compounds within Chinese supply chains.
Market Restraints
- Caprolactam feedstock volatility:Benzene and cyclohexane price swings compress compounder margins and destabilize contract pricing for nylon 6 resin.
- European supply concentration:Integrated caprolactam-to-compound production clusters in Germany and Belgium create single-source vulnerability for automotive qualification programs.
- Short-chain chlorinated paraffin restrictions:ECHA REACH Annex XVII limitations on SCCP flame retardants force reformulation of legacy electrical connector grades.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for advanced chemistry cell batteries create virgin demand for localized nylon compound production.
- Hydrogen fuel-line tubing:Nylon 12 barrier layers are penetrating high-pressure hydrogen distribution systems as fuel cell commercialization accelerates.
- EU Green Deal circularity mandates:End-of-life vehicle recycling targets incentivize chemically recycled polyamide feedstock development.
Industry Challenges
- Automotive qualification timelines:OEM material approval cycles spanning 18-36 months delay revenue recognition for new compound introductions.
- Polymer processing expertise gaps:Shortage of injection molding engineers trained in high-temperature nylon processing constrains tier supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nylon Market |
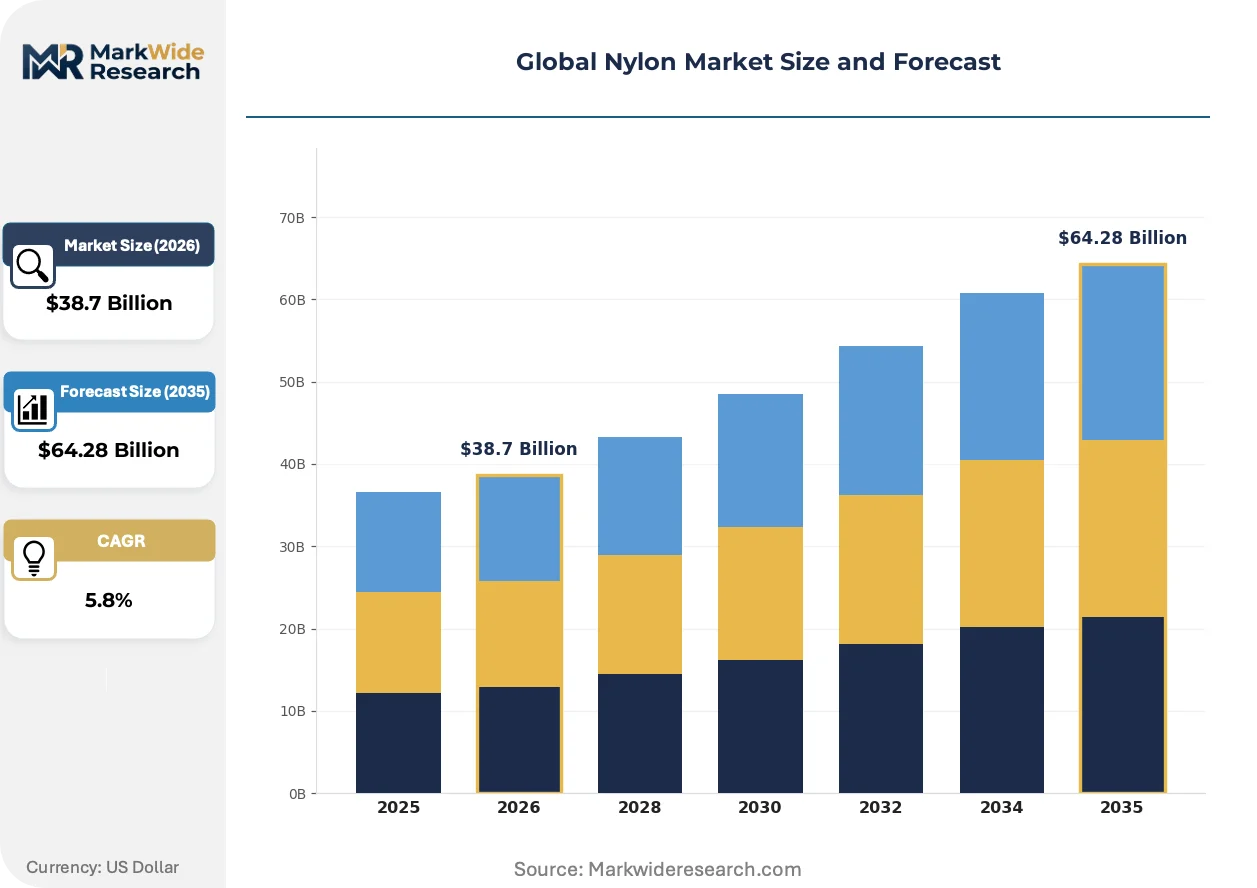
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6, Nylon 66, Nylon 12, Nylon 4 End User: Textiles, Automotive, Electronics, Consumer Goods Form: Fibers, Films, Resins, Reinforcements Application: Apparel, Ropes, Carpets, Industrial Products |
| Companies Covered | BASF SE, Toray Industries, Huntsman Corporation, LANXESS, AdvanSix, INVISTA, Ascend Performance Materials, Domo Chemicals, UBE Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nylon Market Strategic Shifts
Bio-based feedstock integration and advanced recycling technologies are restructuring raw material sourcing strategies. These developments are compressing reliance on fossil-derived monomers while opening qualification pathways for circular polyamide grades.
Long-chain bio-polyamides derived from castor oil sebacic acid are supplanting petroleum-based nylon 10,10 and 6,10 in automotive fuel-line and pneumatic tubing applications. Tier suppliers in Germany and Japan are qualifying these grades for under-hood thermal stability. This substitution is enabling OEMs to meet Scope 3 emissions targets without sacrificing hydrolysis resistance.
REACH chemical restriction expansions are forcing systematic reformulation of plasticized nylon compounds across European electrical and automotive markets. ECHA SVHC candidate list updates now target specific phthalate alternatives previously adopted as SCCP replacements. Wire harness and connector manufacturers are accelerating halogen-free flame retardant qualification programs.
Automotive OEMs are consolidating resin procurement through direct compounder relationships, bypassing traditional distributor channels for engineering-grade specifications. Tier suppliers in Michigan and Stuttgart are negotiating frame contracts with melt-flow certification guarantees. This concentration is most visible in hybrid powertrain connector programs where thermal aging specifications exceed standard distributor inventory capabilities.
Global Nylon Market Segmentation
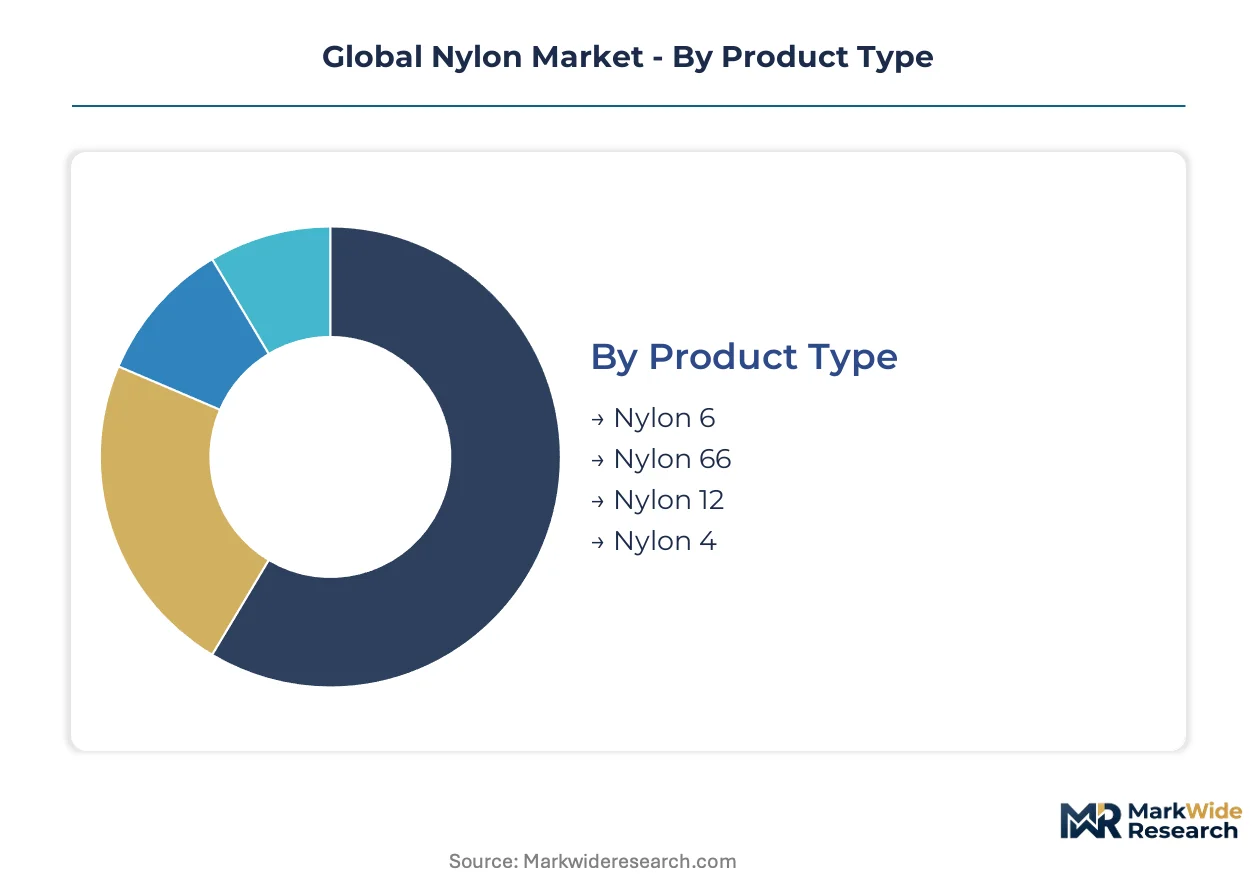
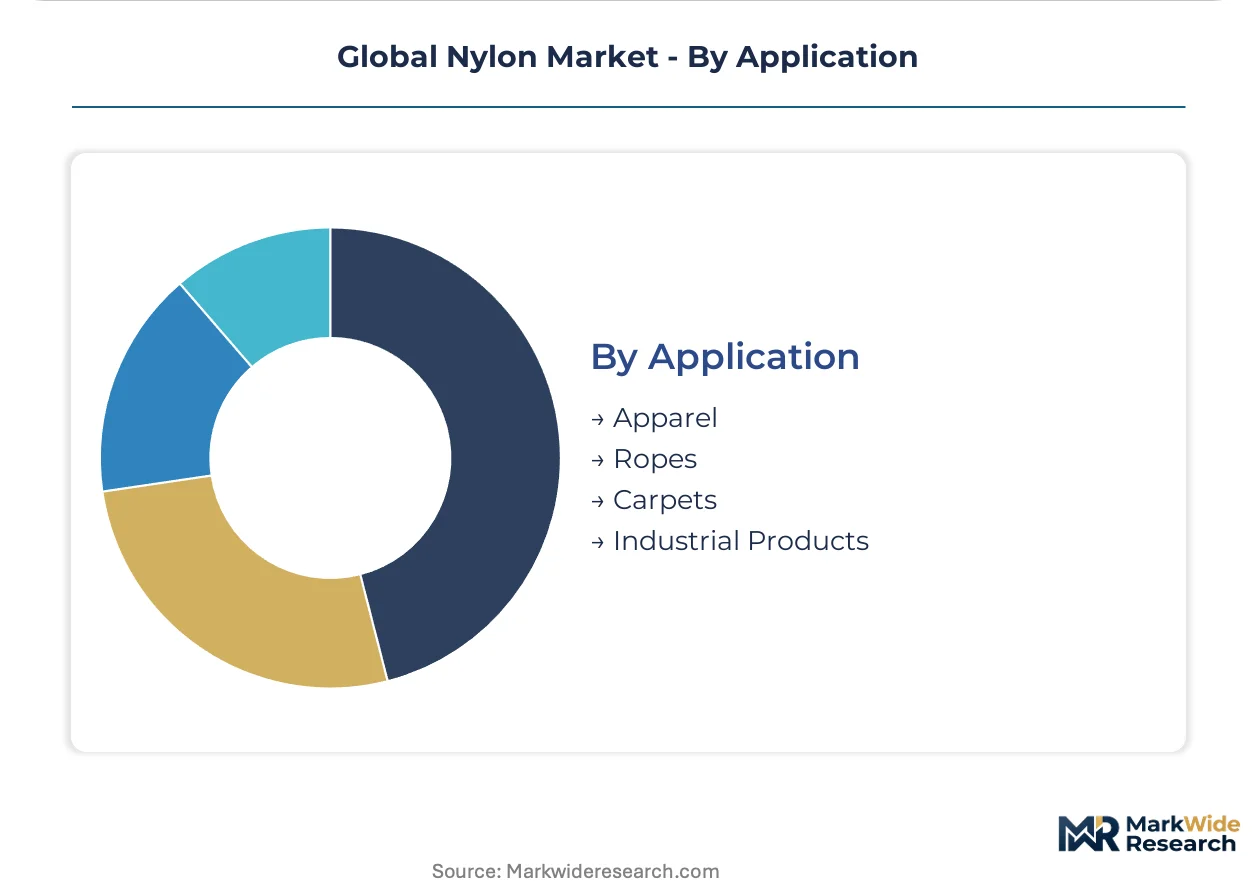
Nylon market segmentation reflects divergent technical specifications across automotive thermal management, pharmaceutical barrier properties, and textile mechanical performance. Regulatory frameworks in the United States, Europe, and China enforce distinct material qualification protocols that reshape demand concentration by grade and form.
Product Type:
EPA fuel-economy standards and ECHA REACH chemical restrictions create divergent formulation requirements across automotive and electrical applications.
- Nylon 6:Polymerized from caprolactam monomer with crystalline melting point near 220°C. Glass-filled compounds dominate under-hood automotive components in Michigan and Stuttgart manufacturing clusters as OEMs pursue metal substitution for chassis brackets.
- Nylon 66:Condensation product of adipic acid and hexamethylenediamine delivering superior heat deflection temperature above 260°C. Demand concentrates in hybrid powertrain connector programs across German and Japanese automotive supply chains where thermal aging specifications exceed standard grades.
- Nylon 12:Long-chain aliphatic polyamide with lowest moisture absorption among commercial grades. Penetrates hydrogen fuel-line tubing and pharmaceutical blister packaging.
- Nylon 4:Bio-based polyamide derived from biomass fermentation routes. Emerging qualification in sustainable textile fiber applications.
Nylon 66 handles the majority of throughput; Nylon 12 is the fastest mover on share.
End User:
Cost tier differentiation separates specification-grade compounds from commodity volume plays across customer categories.
- Automotive:Engineering-grade compounds command premium pricing for under-hood thermal management and structural metal replacement. MIIT production quotas in China concentrate demand for locally qualified materials in electric vehicle battery housings.
- Electronics:Miniaturized connector housings and wire harness components require halogen-free flame retardant formulations compliant with ECHA SVHC restrictions.
- Textiles:Carpet fiber and industrial yarn applications operate on volume-driven contract pricing with mature specification standards.
- Consumer Goods:Appliance housings and sporting equipment utilize unfilled or mineral-reinforced grades with less stringent thermal requirements.
Automotive generates the highest value per kilogram; Electronics is expanding most quickly as connector miniaturization accelerates.
Form:
Supply concentration in integrated caprolactam-to-compound production clusters favors resin form for automotive qualification programs.
- Resins:Pelletized engineering thermoplastics for injection molding and extrusion. Glass-filled and flame-retardant grades capture disproportionate margin pools through direct OEM compounder relationships bypassing traditional distribution.
- Fibers:Melt-spun continuous filament for textile and industrial applications. Airbag fabric and tire cord reinforcement sustain premium pricing in safety-critical specifications.
- Films:Cast or oriented barrier layers for pharmaceutical packaging and food flexible packaging. Nylon 6 and Nylon 66 coextrusions dominate moisture-sensitive applications.
- Reinforcements:Glass fiber and carbon fiber pre-impregnated tapes for composite structural applications. Emerging penetration in aerospace secondary structures.
Resins command the dominant revenue position; Films are climbing the fastest as pharmaceutical barrier requirements tighten.
Application:
Geographic production gravity centers on China for industrial products and Germany for specialized automotive components.
- Industrial Products:Gears, bearings, and abrasion-resistant components for manufacturing equipment. Demand clusters in Chinese industrial automation expansion and German machinery exports.
- Carpets:Bulked continuous filament for residential and commercial flooring. Volume leadership in United States residential replacement cycles.
- Apparel:Sportswear and hosiery applications leveraging moisture-wicking and elasticity properties. Southeast Asian cut-and-sew operations drive fiber demand.
- Ropes:Marine, industrial, and safety rope constructions requiring high tenacity and UV resistance. Fishing and offshore oil applications concentrate in Norway and Japan.
Industrial Products absorbs the largest compound volume; Ropes are gaining share fastest in offshore wind and marine safety specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export specification-grade nylon resins to automotive engineering centers in Stuttgart, Wolfsburg, and Munich, while Chinese caprolactam producers feed domestic electric vehicle battery housing programs and Southeast Asian textile operations.
United States
EPA Corporate Average Fuel Economy standards and NHTSA safety regulations compel Detroit automakers to substitute glass-filled polyamide for metal chassis components. Michigan-based tier suppliers negotiate direct frame contracts with melt-flow certification guarantees. The Midwest manufacturing corridor concentrates injection molding capacity for under-hood thermal management parts.
Germany
ECHA REACH Annex XVII restrictions on short-chain chlorinated paraffins force systematic reformulation of legacy electrical connector grades. The country's integrated caprolactam-to-compound production clusters in North Rhine-Westphalia and Bavaria create single-source vulnerability for automotive qualification programs. Stuttgart engineering centers specify halogen-free flame retardant formulations for hybrid powertrain applications.
China
MIIT new energy vehicle production quotas concentrate demand for locally qualified nylon compounds in electric vehicle battery housings. GB standards for automotive interior emissions shape product specification requirements for domestic OEMs. Yangtze River Delta chemical parks deepen caprolactam supply chain integration to serve Shanghai and Hangzhou automotive manufacturing.
Japan
METI carbon neutrality targets accelerate bio-based polyamide qualification for automotive fuel-line applications. Toray Industries anchors filament specialization for airbag fabrics and tire cord reinforcement in safety-critical specifications. Nagoya and Osaka industrial clusters sustain premium pricing through technical textile engineering expertise.
India
PLI scheme incentives for advanced chemistry cell batteries create virgin demand for localized nylon compound production. BIS automotive material standards delay qualification timelines for imported resin grades. Maharashtra and Gujarat manufacturing corridors attract compounder joint ventures to serve domestic electric vehicle programs.
Global Nylon Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive caprolactam supply. Three structural tiers separate global specification-grade compounders, regional fiber specialists, and commodity resin traders. Strategic archetypes include backward-integrated monomer producers, application-focused compounders, and textile filament verticals. Dominant competitive moves encompass direct OEM procurement relationships bypassing distribution channels, and chemical recycling partnerships to secure circular feedstock for EU Green Deal compliance.
Among German-based integrated producers, BASF SE and LANXESS occupy positions exemplifying the backward-integrated archetype with captive caprolactam chains. Toray Industries represents the textile filament specialist tier with Japanese technical fiber engineering heritage. Huntsman Corporation sits within the differentiated compounder category targeting thermal management specifications.
| Leading Market Players |
|---|
| BASF SE |
| Toray Industries |
| Huntsman Corporation |
| LANXESS |
| AdvanSix |
| INVISTA |
| Ascend Performance Materials |
| Domo Chemicals |
| UBE Industries |
| Others |
Value Chain & Pricing Dynamics
Integrated caprolactam production at world-scale facilities in Germany and China establishes cost floors that smaller compounders cannot match without captive benzene supply or long-term offtake contracts. This scale concentration compresses margin structures for non-integrated players while elevating pricing power for backward-linked producers serving automotive qualification programs.
Pricing Analysis
Grade-generation pricing gaps separate legacy nylon 6 compounds from next-generation bio-based polyamides and high-heat nylon 6,6 formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with UL-certified flame-retardant grades commanding substantial premiums over distributor commodity resin. Pricing pressure stems from benzene feedstock volatility compressing compounder margins. Tier suppliers in automotive applications show least price sensitivity due to qualification lock-in, while consumer goods molders exhibit highest elasticity.
Supply Chain Analysis
Germany and China anchor integrated caprolactam-to-compound production, while Belgium and Japan sustain specialized engineering resin output. Raw material flows draw from benzene crackers in the US Gulf Coast, cyclohexane derivatives from Korean petrochemical complexes, and sebacic acid from Indian castor oil processors. Single-source vulnerability concentrates in North Rhine-Westphalia caprolactam clusters serving Stuttgart automotive engineering centers. Distribution runs through direct OEM compounder relationships bypassing traditional resin distributors for specification-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, ECHA, and MIIT jurisdictions fragments formulation platforms, creating niche qualification opportunities for specialized compounders serving divergent compliance requirements.
For Market Incumbents: Secure captive caprolactam supply through long-term benzene offtake agreements or backward integration into cyclohexane production. Expand flame-retardant certification portfolios ahead of ECHA SVHC list expansions targeting phthalate alternatives. Defend automotive qualification positions by embedding technical service teams within Detroit and Stuttgart OEM engineering centers. For New Entrants and Emerging Players: Differentiate on bio-based feedstock credentials targeting Scope 3 emissions accounting requirements at European automotive OEMs. Penetrate India PLI scheme battery housing programs before domestic compounder joint ventures achieve scale. Pursue hydrogen fuel-line tubing qualifications as fuel cell commercialization accelerates in Japan and South Korea. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with direct OEM frame contracts and melt-flow certification guarantees. Five-to-ten year viability favors integrated producers with captive monomer supply and circular recycling partnerships. Target acquisition archetype: mid-cap compounders with automotive qualification pipelines but subscale caprolactam positions. Watch ECHA REACH Annex XVII expansion timelines as inflection signals for reformulation-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive benzene supply insulates BASF and LANXESS from cyclohexane price volatility in European automotive supply chains. |
| Halogen-Free Flame Retardant Qualification | ECHA SVHC restrictions on SCCP replacements compel wire harness reformulation investments by connector manufacturers. |
| Chemical Recycling Partnership | EU Green Deal circularity mandates incentivize Domo Chemicals and others to secure post-consumer polyamide feedstock streams. |
| Direct OEM Procurement Relationships | Bypassing distributors for engineering-grade specifications locks in multi-year frame contracts with melt-flow guarantees. |
| Bio-Based Polyamide Scale-Up | Toray Industries and UBE Industries leverage castor oil sebacic acid to capture automotive fuel-line tubing demand from petroleum-based grades. |
Study Parameters
The analysis maps nylon 6, nylon 6,6, nylon 12, and bio-based polyamide sub-sectors, each validated through plant managers at integrated producers, procurement leads at Tier 1 automotive suppliers, distribution channel partners, and technical R&D directors at compounders. Primary interview findings triangulate against customs and trade data from Germany's Federal Statistical Office and China's General Administration of Customs, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up volume builds from resin production capacities and fiber spinning line counts reconcile with top-down demand estimates from automotive production databases and textile consumption indices.
Consistency checks validate volume and value outputs against external benchmarks including IHS Markit chemical pricing assessments and ICIS supply-demand balances across the projection horizon. Segmentation dimensions model grade tier, end-use industry concentration, form factor, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand curves incorporating EPA fuel-economy compliance timelines, MIIT production quota trajectories, and ECHA regulatory phase-in schedules. Forecast inputs include benzene-cyclohexane spread projections and electric vehicle battery housing content-per-vehicle assumptions.
The analysis sits within stated boundaries; outcomes outside sustained automotive lightweighting momentum, stable caprolactam feedstock economics, or coherent regulatory implementation would require recalibration. Forecasts reflect assumptions regarding OEM qualification cycle durations, chemical recycling technology maturation, and bio-based monomer cost convergence. Specific risk factors encompass REACH restriction scope expansion, China domestic supply chain substitution policies, and hydrogen fuel cell deployment delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycide Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Propylene Terpolymer Market