
 Resin Glue Market | 2026-2036
Resin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Glue Market Analytics
REACH is rebalancing the cost-of-entry calculus for European resin glue manufacturers by mandating extensive substance registration and safety documentation. Dow Chemical leverages its integrated petrochemical feedstock position to absorb compliance costs that strain smaller rivals. Huntsman Corporation specializes in differentiated polyurethane systems that navigate tighter VOC thresholds without sacrificing bond performance. Georgia-Pacific Chemicals anchors its position through captive phenolic resin capacity serving North American plywood and engineered wood markets.
Resin glue comprises synthetic adhesive formulations built from thermosetting polymers that cure through cross-linking reactions to form durable, load-bearing bonds. Epoxy systems deliver tensile strengths exceeding 2,000 psi and chemical resistance for structural metal-to-metal joints, while phenolic resins withstand temperatures above 150°C in plywood lamination and brake lining applications. Polyurethane adhesives dominate flexible packaging and automotive interior assembly where vibration damping and impact resistance matter. Phenolic formulations occupy mature, cost-sensitive woodworking segments with thin margin pools, whereas epoxy commands premium positioning in aerospace and electronics bonding where failure tolerance approaches zero.
EPA regulations on formaldehyde emissions from composite wood products directly constrain phenolic and melamine resin formulations in US manufacturing. ECHA's REACH restrictions and the EU Green Deal carbon border adjustments are reshaping import competitiveness for Asian resin suppliers. China's MEE enforces GB standards on volatile organic compound content in architectural adhesives, tightening product access for uncertified imports. Stakeholders must monitor how divergent chemical safety regimes fragment formulation platforms and force regional specialization in R&D investment.
Market Dynamics
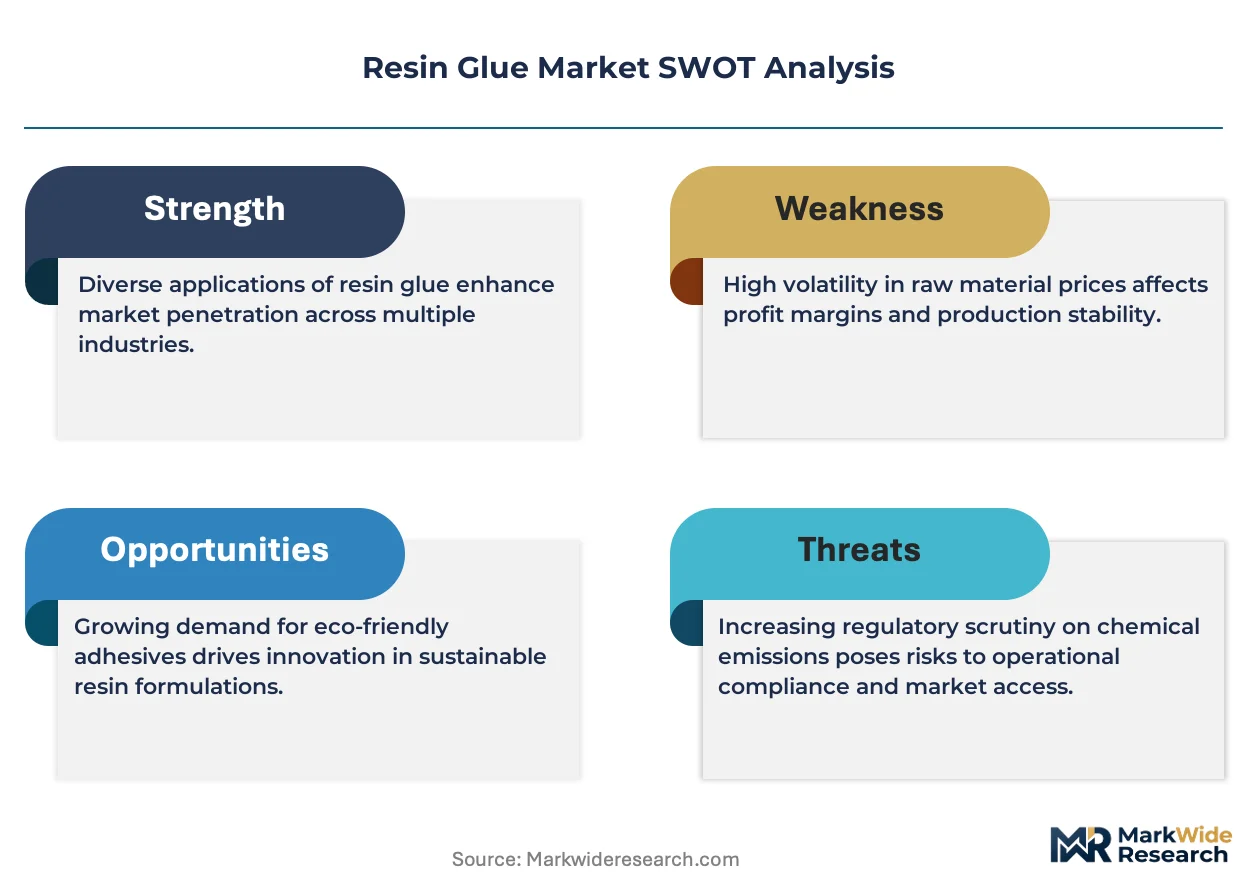
Construction procurement of high-performance adhesives is intensifying as builders pursue structural integrity under stricter building codes, while REACH compliance in Europe elevates formulation costs and filters out smaller compounders from viable participation.
Growth Catalysts
- GB Standards Enforcement:China's MEE enforces volatile organic compound limits in architectural adhesives, pulling demand toward certified domestic suppliers with compliant phenolic and epoxy formulations.
- Wind Energy Expansion:Blade manufacturers specify toughened epoxy systems for fiber-reinforced composite bonding in turbine construction, creating specification lock-in for qualified resin compounders.
- EU Green Deal Carbon Border Adjustments:Import levies on carbon-intensive phenolic resins are reshaping competitiveness for Asian suppliers serving European engineered wood markets.
Market Restraints
- Formaldehyde Input Volatility:Phenolic resin production depends on petrochemical-derived phenol and formaldehyde, exposing margin pools to feedstock price swings and energy cost spikes.
- REACH Registration Burden:European compounders face six-figure substance documentation costs that disproportionately strain mid-tier formulators without diversified revenue bases.
- Mechanical Fastener Substitution:Structural bolting and welding retain preference in heavy steel fabrication where bond-line inspection and load verification remain regulatory requirements.
Strategic Opportunities
- India Infrastructure Build-Out:National highway and affordable housing programs are generating specification demand for moisture-resistant phenolic plywood adhesives in sub-tropical construction.
- EV Battery Module Bonding:Thermal management and vibration-resistant polyurethane systems are penetrating electric vehicle assembly as pack designers replace mechanical retention with adhesive joining.
- Bio-Based Feedstock Convergence:Lignin-derived phenolic substitutes and plant-based polyols are unifying sustainability credentials with performance parity in certified green building applications.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in thermoset kinetics and cure-profile optimization is concentrating at legacy compounders, constraining R&D velocity for newer entrants.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA, REACH, and GB standard approvals extend product launch cycles by 18-24 months for global adhesive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resin Glue Market |
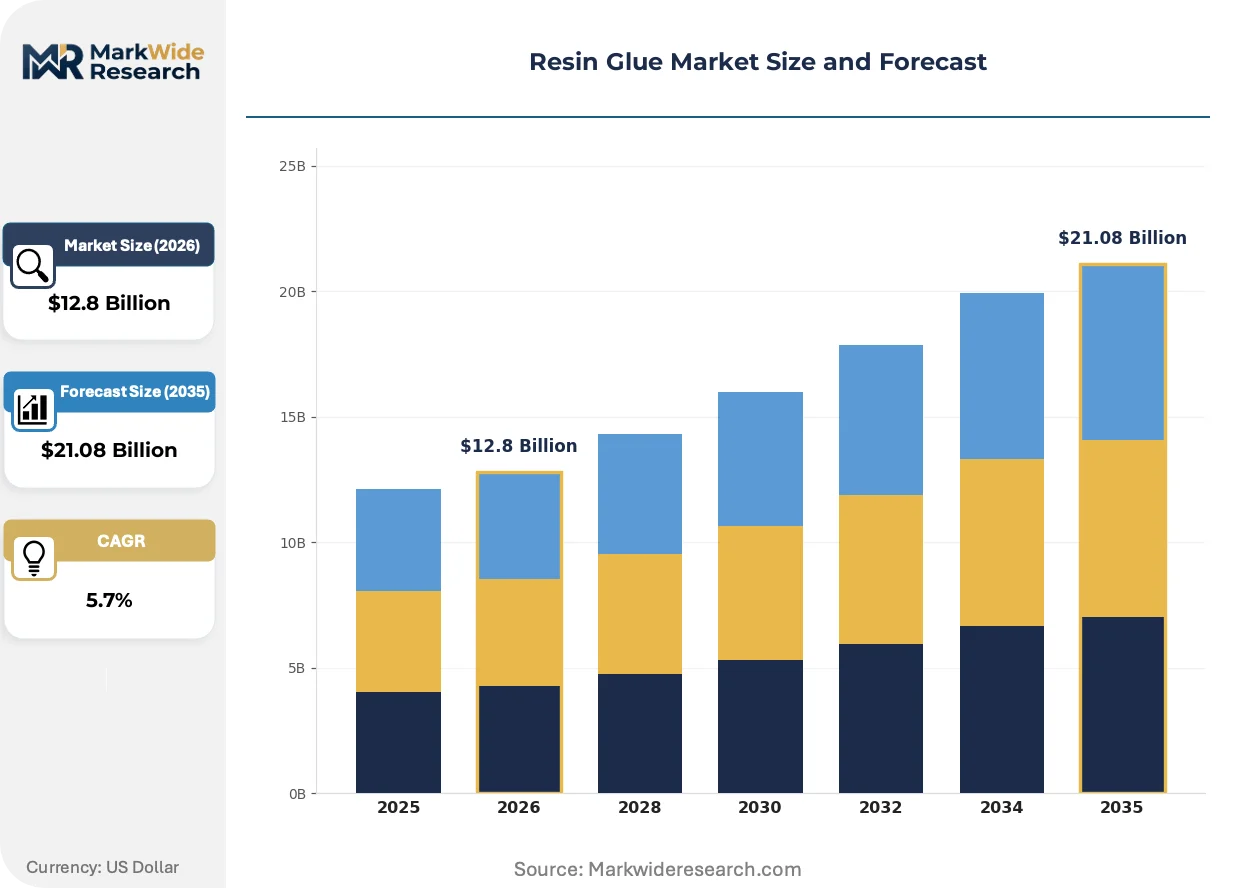
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Melamine, Phenolic Application: Construction, Automotive, Packaging, Woodworking End User: Manufacturers, Contractors, Retailers, Distributors Form: Liquid, Paste, Granular, Solid |
| Companies Covered | Dow Chemical, Eastman Chemical, ExxonMobil Chemical, Mitsubishi Chemical, DuPont, 3M, Olin Corporation, Huntsman Corporation, Georgia-Pacific Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Glue Market Evolving Landscape
Formulation chemistry is converging with digital manufacturing controls and circular material sourcing, compressing development cycles while expanding addressable applications beyond traditional bonding.
Hybrid epoxy-acrylate systems are unifying rapid cure speeds with structural load-bearing capacity in automotive lightweighting programs. Tier-one suppliers specify these materials for aluminum-to-composite joining where line-speed throughput and crashworthiness must coexist. The technology is compressing equipment footprint requirements and reducing WIP inventory at assembly plants.
ECHA's REACH restrictions on Substances of Very High Concern are forcing reformulation of legacy phenolic resins used in plywood and particleboard manufacturing. European producers are substituting formaldehyde-scavenging additives and modified resole chemistries to maintain emission certifications. North American exporters to EU markets face parallel compliance investments or exclusion from specification chains.
Specification decisions are consolidating at architectural engineering firms and OEM technical centers rather than distributing through distributor recommendations. Construction adhesives procurement in Germany and France now routes through centralized EPD-verified product databases that filter uncertified options before contractor exposure. This pattern concentrates volume at compounders with pre-submitted environmental documentation and third-party verified performance data.
Resin Glue Market Segmentation
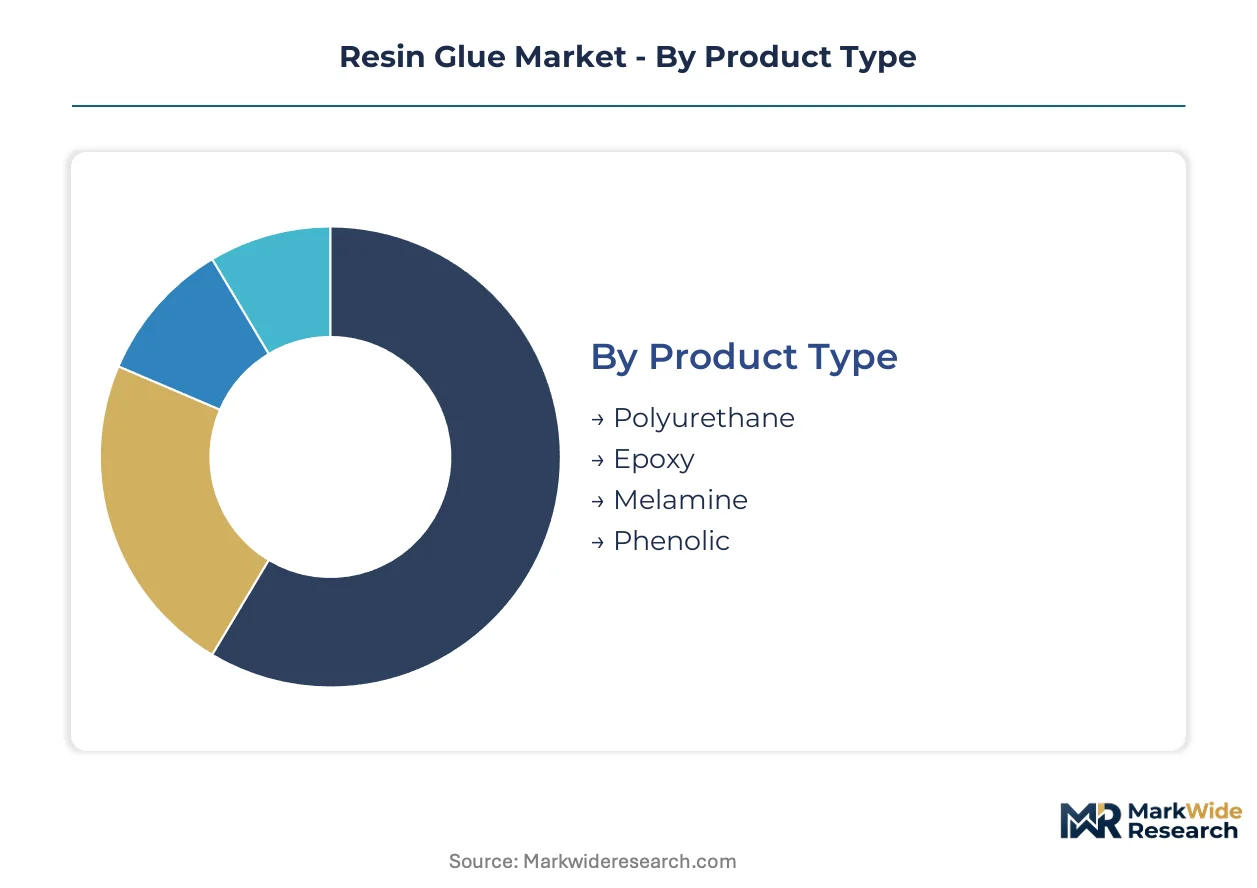
Resin glue market segmentation reveals how formulation chemistry and delivery format dictate supply chain configuration, procurement behavior, and margin capture across distinct industrial workflows. Understanding these divides exposes where specification power concentrates and where substitution threats emerge.
Product Type:
Supply concentration varies sharply across chemistries, with integrated petrochemical producers dominating phenolic and epoxy while specialty compounders control differentiated polyurethane systems.
- Polyurethane:Two-component systems built from isocyanate and polyol reactions deliver flexible, impact-resistant bonds with cure profiles tunable from seconds to hours. Demand concentrates in Germany and China's automotive assembly plants where lightweighting programs specify polyurethane for aluminum-to-composite joining, though raw isocyanate volatility strains formulator margins.
- Epoxy:Thermosetting polymers formed from epichlorohydrin and bisphenol-A cross-linking achieve tensile strengths exceeding 2,000 psi and chemical resistance critical for structural metal bonding. China's wind turbine blade manufacturers specify toughened epoxy systems for fiber-reinforced composite lamination, creating qualification barriers for uncertified suppliers.
- Melamine:Formaldehyde-based thermoset resins provide moisture-resistant bonds in decorative laminates and furniture facing applications.
- Phenolic:Oldest synthetic adhesive chemistry delivers heat resistance above 150°C in plywood lamination and brake lining fabrication.
Today's leader: Epoxy commands premium positioning in structural and electronic bonding. Tomorrow's challenger: Polyurethane gains specification share fastest in automotive lightweighting and flexible packaging.
Application:
Cost tier stratification separates specification-driven aerospace and electronics bonding from price-sensitive woodworking and general construction procurement.
- Construction:Structural adhesives for concrete anchoring, panel bonding, and façade installation must satisfy building code load ratings and fire resistance standards. China's state-backed infrastructure spending pulls volume toward domestic suppliers with GB-certified phenolic and epoxy formulations, while EU Green Deal carbon border adjustments reshape import competitiveness for Asian producers.
- Automotive:Assembly line adhesives must survive vibration, thermal cycling, and crash loading while enabling line-speed throughput. Germany's KBA type-approval requirements and China's MIIT vehicle certification drive qualification complexity for bonding systems in electric vehicle battery module assembly.
- Packaging:Flexible film lamination and carton sealing demand food-contact compliant formulations with rapid set characteristics.
- Woodworking:Plywood, particleboard, and engineered wood bonding consumes mature phenolic and urea-formaldehyde chemistries with thin margin pools.
Construction absorbs the highest absolute volume. Automotive offers the steepest expansion trajectory as electrification redesigns assembly bonding requirements.
End User:
Procurement authority is shifting from distributor recommendations toward centralized technical specification at OEM engineering centers and architectural firm material databases.
- Manufacturers:OEMs and tier suppliers with in-house formulation expertise and direct compounder relationships.
- Contractors:Construction firms sourcing through project-specified product databases with EPD verification requirements.
- Retailers:Consumer and light commercial channels with private-label and branded adhesive portfolios.
- Distributors:Industrial supply intermediaries facing disintermediation as specification consolidates upstream.
Manufacturers retain the deepest technical engagement and longest contract horizons. Contractors are gaining procurement influence fastest through centralized green building certification requirements.
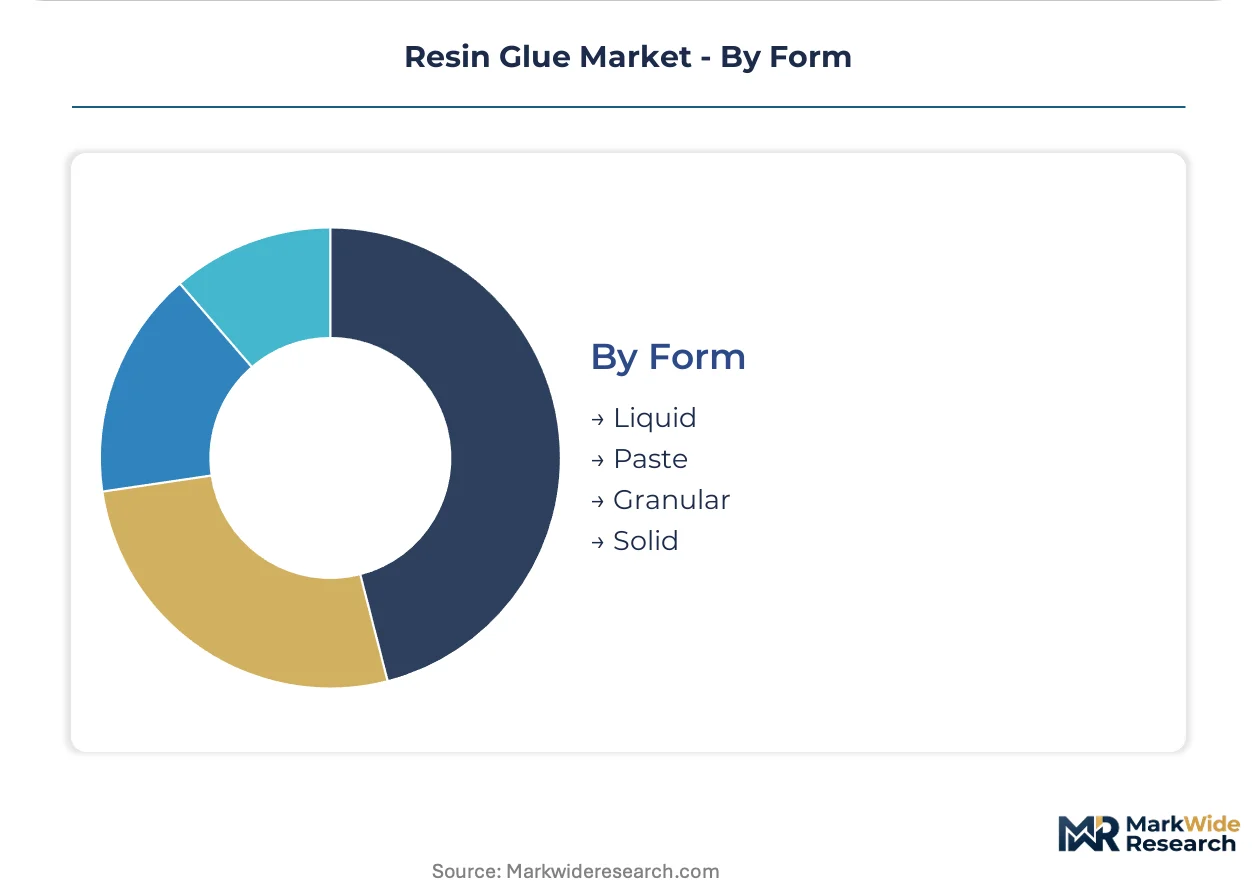
Form:
Volume and handling characteristics determine logistics economics and application equipment requirements across manufacturing environments.
- Liquid:Pumpable systems for automated dispensing in high-throughput assembly operations.
- Paste:Thixotropic formulations for vertical and overhead bonding without sag.
- Granular:Solid phenolic and melamine pre-polymers for hot-press plywood and particleboard lamination.
- Solid:Film and powder adhesives for pre-positioned bonding in aerospace composite fabrication.
Liquid dominates by volume throughput in automotive and construction. Solid forms command the highest per-kilogram value in aerospace and electronics precision bonding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in Germany's industrial Rhineland and China's Yangtze River Delta, anchoring regional R&D capacity for thermoset adhesive development. These talent clusters shape how procurement specifications propagate through construction and automotive supply chains.
China
State-backed infrastructure spending and domestic chemical capacity expansion pull volume toward certified suppliers with GB-compliant phenolic and epoxy formulations. The Ministry of Ecology and Environment enforces volatile organic compound limits in architectural adhesives, tightening product access for uncertified imports. Yangtze River Delta clusters around Shanghai and Jiangsu province host wind turbine blade manufacturers specifying toughened epoxy systems for fiber-reinforced composite lamination.
Germany
Automotive lightweighting programs specify polyurethane for aluminum-to-composite joining at assembly plants across Bavaria and Baden-Württemberg. The Kraftfahrt-Bundesamt type-approval requirements drive qualification complexity for bonding systems in electric vehicle battery module assembly. Cologne-Düsseldorf chemical corridors concentrate formulation expertise serving EU Green Deal carbon border adjustment compliance.
United States
Engineered wood producers in the Pacific Northwest and Southeast source phenolic resins under EPA formaldehyde emission standards for composite wood products. The Inflation Reduction Act provisions accelerate wind energy deployment, expanding specification demand for toughened epoxy in turbine blade manufacturing. Georgia-Pacific Chemicals anchors North American supply through captive phenolic capacity serving plywood markets.
India
National highway and affordable housing programs generate specification demand for moisture-resistant phenolic plywood adhesives in sub-tropical construction. The Bureau of Indian Standards enforces certification requirements for structural adhesives in public infrastructure procurement. Gujarat and Maharashtra industrial corridors concentrate domestic compounding capacity serving western and southern construction markets.
Japan
Electronics and automotive OEMs in the Kanto and Kansai regions specify high-purity epoxy systems for precision bonding applications. The Ministry of Economy, Trade and Industry promotes advanced materials development through technology licensing frameworks. Nagoya-Tokyo industrial corridors host formulation specialists serving semiconductor packaging and electric vehicle assembly requirements.
Resin Glue Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, with integrated petrochemical producers dominating commodity phenolic and epoxy while specialty compounders control differentiated polyurethane systems. Market structure reflects feedstock access advantages and qualification barriers in specification-driven segments. Three archetypes define competitive positioning: integrated chemical majors with captive raw material supply, regional compounders with formulation flexibility, and application-focused specialists with OEM qualification depth. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock positions and expand geographic certification coverage.
Within the integrated chemical major tier, Dow Chemical and Huntsman Corporation exemplify scale-driven positioning anchored by petrochemical feedstock integration and differentiated system development respectively. Eastman Chemical and Olin Corporation occupy mid-tier compounder positions with regional formulation flexibility and epoxy specialty focus. Among Asia-Pacific-based suppliers, Mitsubishi Chemical represents the diversified industrial conglomerate archetype with cross-segment chemical capabilities. Georgia-Pacific Chemicals anchors North American supply through captive phenolic resin capacity serving engineered wood markets.
| Leading Market Players |
|---|
| Dow Chemical |
| Eastman Chemical |
| ExxonMobil Chemical |
| Mitsubishi Chemical |
| DuPont |
| 3M |
| Olin Corporation |
| Huntsman Corporation |
| Georgia-Pacific Chemicals |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon border adjustments gate qualified supply and premium-tier pricing access, filtering out uncertified Asian phenolic resin exporters while rewarding European compounders with pre-submitted environmental documentation. This regulatory screen concentrates procurement authority at compounders with captive feedstock positions and third-party verified performance data.
Pricing Analysis
Bundled technical service contracts versus unbundled commodity resin sales split the market into two pricing architectures. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified epoxy systems from construction-grade phenolic formulations, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-tier phenolic resins is intensifying because of formaldehyde input volatility and energy cost spikes. Woodworking contractors exhibit the highest price sensitivity, while wind turbine OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
China's GB standards enforcement and India's BIS certification mandates are reshaping sourcing patterns toward domestic-content-compliant suppliers. Raw material supply draws from petrochemical-derived phenol, formaldehyde, and epichlorohydrin feedstocks anchored in China, Germany, and the United States. Single-source vulnerability concentrates in Yangtze River Delta epoxy resin capacity serving wind turbine blade manufacturers. Distribution runs through direct compounder relationships with OEM engineering centers, bypassing traditional industrial distributors as specification authority consolidates upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between REACH-burdened European formulation costs and state-subsidized Chinese chemical capacity expansion, with margin capture favoring producers with integrated petrochemical feedstock positions.
For Market Incumbents: To counter formaldehyde input volatility and margin compression in commodity phenolic tiers, deepen backward integration into captive phenol production and expand GB-certified capacity in Jiangsu province to serve state-backed infrastructure procurement. Prioritize qualification depth in wind turbine epoxy systems where specification lock-in creates multi-year contract horizons. For New Entrants and Emerging Players: Launch via private-label supply to Indian affordable housing contractors seeking BIS-certified moisture-resistant plywood adhesives, exploiting underpenetration in sub-tropical construction segments. Target EV battery module bonding applications where thermal management polyurethane specifications remain fluid and incumbent qualification advantages have not yet solidified. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European compounders facing REACH registration cost strain without diversified revenue bases, presenting consolidation targets with reformulation expertise and existing EPD documentation. The signal to watch is carbon border adjustment implementation timing, which will determine competitive repositioning windows for Asian suppliers serving European engineered wood markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Captive raw material supply insulates margin pools from petrochemical price volatility affecting Huntsman and Dow competitors. |
| GB Certification Investment in China | MEE volatile organic compound compliance unlocks state-backed infrastructure procurement channels in Yangtze River Delta clusters. |
| Long-term Supply Agreement with Wind OEMs | Toughened epoxy qualification lock-in secures specification-driven revenue streams from Goldwind and Envision turbine programs. |
| Joint Venture with Lignin Derivative Suppliers | Bio-based phenolic substitutes address EU Green Deal carbon border adjustments while maintaining performance parity in plywood lamination. |
| Capacity Expansion in Gujarat Industrial Corridor | Bureau of Indian Standards proximity reduces certification timelines for national highway and affordable housing adhesive specifications. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market's formulation chemists, plant managers at downstream engineered wood producers, procurement leads at wind turbine OEMs, and distribution channel partners. Secondary validation draws from customs and trade data, SEC 10-K filings, American Chemistry Council reports, and ECHA substance registration databases. Bottom-up volume estimates and top-down macroeconomic triangulation cross-check segment-level outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window, with segmentation modeling across formulation chemistry, application end-use, delivery form, and regional production hub. CAGRs derive from regression analysis against construction spending indices, automotive production forecasts, and wind energy deployment trajectories. Industry-specific inputs include turbine blade specification trends and electric vehicle battery pack bonding technology roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under formaldehyde emission regulation stringency shifts and feedstock price spike scenarios. Forecasts reflect documented assumptions regarding REACH enforcement continuity and Chinese state infrastructure spending levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Global Resin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Bio-Based Polypropylene Market