
 Plasmid DNA Manufacturing Market | 2026-2036
Plasmid DNA Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmid DNA Manufacturing Market Intelligence
GMP-grade plasmid specifications is redrawing competitive boundaries across the manufacturing landscape. Lonza leverages its integrated biologics network to anchor high-volume pDNA supply for gene therapy customers. Thermo Fisher Scientific sustains broad technology leadership across microbial fermentation and downstream purification platforms. Aldevron specializes in linearized DNA and GMP plasmid formats, occupying a differentiated position in the nucleic acid supply chain.
Plasmid DNA manufacturing encompasses the production, purification, and quality-controlled preparation of circular double-stranded DNA molecules, typically 2–20 kilobases in size, propagated in bacterial hosts such as Escherichia coli through fed-batch fermentation and recovered via alkaline lysis followed by chromatographic polishing. These plasmids serve as critical starting materials for viral vector production, direct gene therapy, and DNA vaccine applications, with endotoxin levels and supercoiled content representing key release specifications. pDNA products command the dominant share of current manufacturing volume, while gene therapy applications absorb the fastest-growing demand as AAV and lentiviral vector programs multiply. Electroporation technology leads process innovation for large-scale transient transfection, though microbial fermentation retains scale advantages for bulk plasmid propagation.
FDA gene therapy CMC guidance, EMA ATMP quality requirements, and ISO 20399 standards for nucleic acid delivery collectively elevate barriers to market entry and enforce documentation rigor across plasmid supply chains. These frameworks compel manufacturers to validate continuous processes, demonstrate lot-to-lot consistency, and maintain viral safety testing protocols that extend production timelines. Stakeholders must weigh capacity commitments against program attrition risks in a pipeline where clinical-stage gene therapies outnumber approved products by a wide margin.
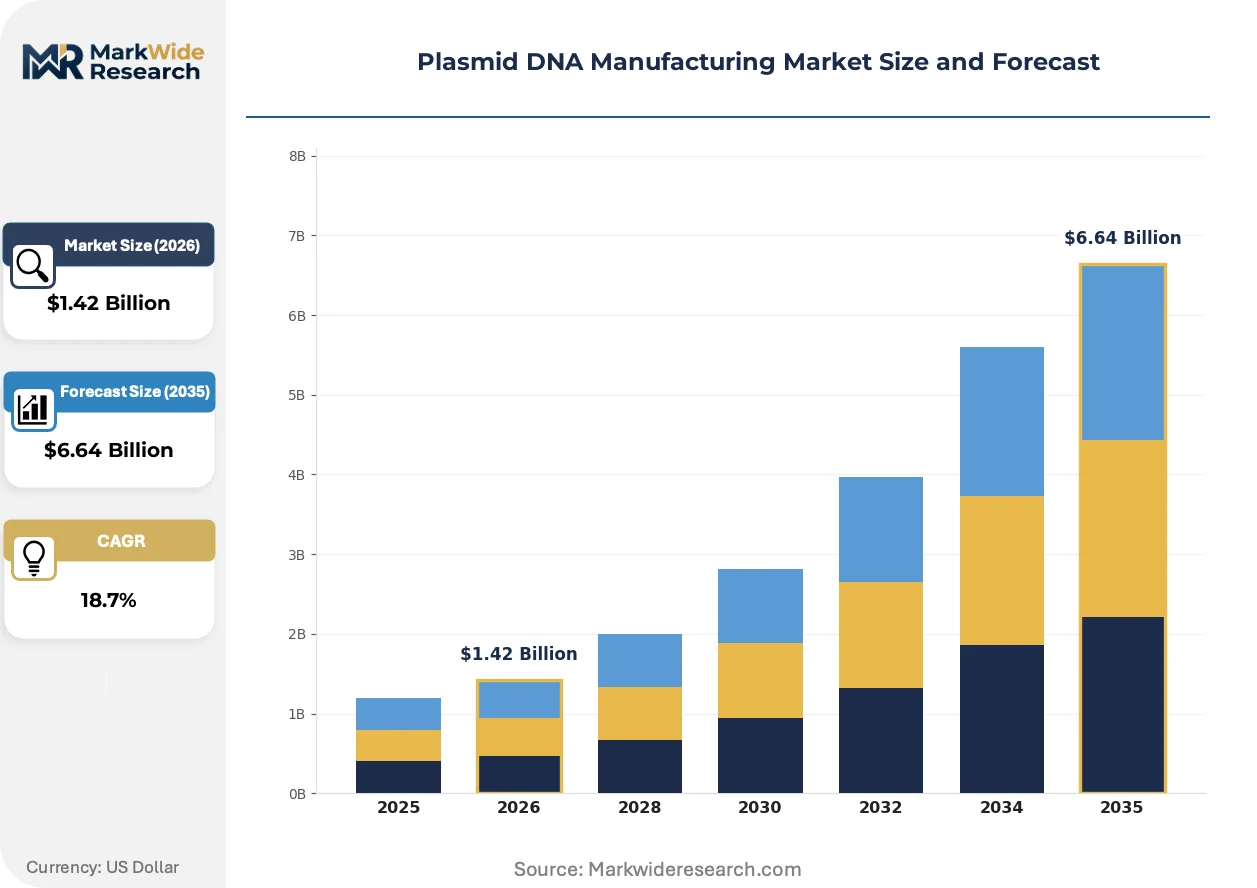
Market Dynamics
Cell and gene therapy pipelines are compressing plasmid DNA lead times from months to weeks, forcing manufacturers to reconfigure batch scheduling around clinical trial randomization rather than traditional campaign planning. This demand volatility is reshaping capacity allocation across microbial fermentation networks.
Growth Catalysts
- EMA ATMP quality requirements:Tighter starting material specifications for advanced therapy medicinal products are pulling GMP-grade plasmid into earlier clinical phases, expanding addressable volume.
- Electroporation technology:Large-scale transient transfection platforms are reducing viral vector production timelines, accelerating plasmid consumption rates in lentiviral and AAV programs.
- United States gene therapy cluster:Concentration of Phase III programs in Boston, San Francisco, and Research Triangle Park is anchoring domestic CDMO investment.
Market Restraints
- Chromatography resin supply:Single-source dependency for anion exchange media creates input bottlenecks during demand surges.
- Endotoxin clearance:Alkaline lysis yields require extensive downstream polishing to meet FDA gene therapy CMC specifications, extending production cycles.
- Program attrition risk:Clinical-stage gene therapies outnumber approved products, creating capacity commitment uncertainty for manufacturers.
Strategic Opportunities
- ISO 20399 compliance:Nucleic acid delivery standards for exosome and lipid nanoparticle applications open adjacent markets beyond viral vectors.
- Linearized DNA formats:Minicircle and linear DNA constructs reduce immunogenicity concerns, creating differentiation for next-generation gene therapies.
- Continuous processing validation:Real-time release testing and integrated analytics reduce batch failure rates while compressing regulatory review timelines.
Industry Challenges
- Supercoiled content optimization:Maintaining topological purity above 90% through fermentation scale-up requires precise copy number control and lysis parameter tuning.
- Quality control staffing:Shortage of analytical scientists trained in residual host cell DNA and endotoxin assays limits throughput expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmid DNA Manufacturing Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pDNA, Lentiviral Vectors, Viral Vectors, RNAi End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Academic Institutions Technology: Electroporation, Microbial Fermentation, Transfection, Polymerase Chain Reaction Application: Gene Therapy, Vaccine Development, Cell Therapy, Diagnostics |
| Companies Covered | Lonza, Catalent, Aldevron, Plasmidfactory GmbH, Cobra Biologics, VGXI, Inc., Thermo Fisher Scientific, Nature Technology, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmid DNA Manufacturing Market Strategic Shifts & Innovations
Process intensification and digital integration are converging to redefine plasmid DNA manufacturing economics, with automation replacing manual intervention at critical control points. These shifts are compressing development timelines while elevating release specification rigor.
Continuous chromatography systems are fragmenting traditional batch purification workflows in plasmid DNA manufacturing. Gene therapy CDMOs in the United States and Switzerland are piloting multi-column periodic counter-current systems to boost resin utilization rates. This technology is fragmenting the dominance of batch affinity and ion exchange steps, enabling smaller footprint facilities to match legacy plant output.
REACH registration requirements for novel process chemicals are expanding documentation burdens for European plasmid manufacturers using synthetic alternatives to animal-derived reagents. EMA guidance on minimizing TSE risk in starting materials is accelerating substitution of bovine-derived enzymes with recombinant alternatives. German and Swiss production sites are absorbing the highest compliance costs, passing these through to gene therapy developers in premium pricing tiers.
Biopharma procurement teams are consolidating plasmid suppliers to dual-source arrangements with integrated viral vector partners, displacing fragmented multi-vendor strategies. This consolidation is compressing qualification timelines for second-source manufacturers while elevating importance of regulatory filing support services. The pattern is most visible among mid-cap gene therapy developers in Massachusetts and North Carolina seeking supply security for pivotal trials.
Plasmid DNA Manufacturing Market Segmentation
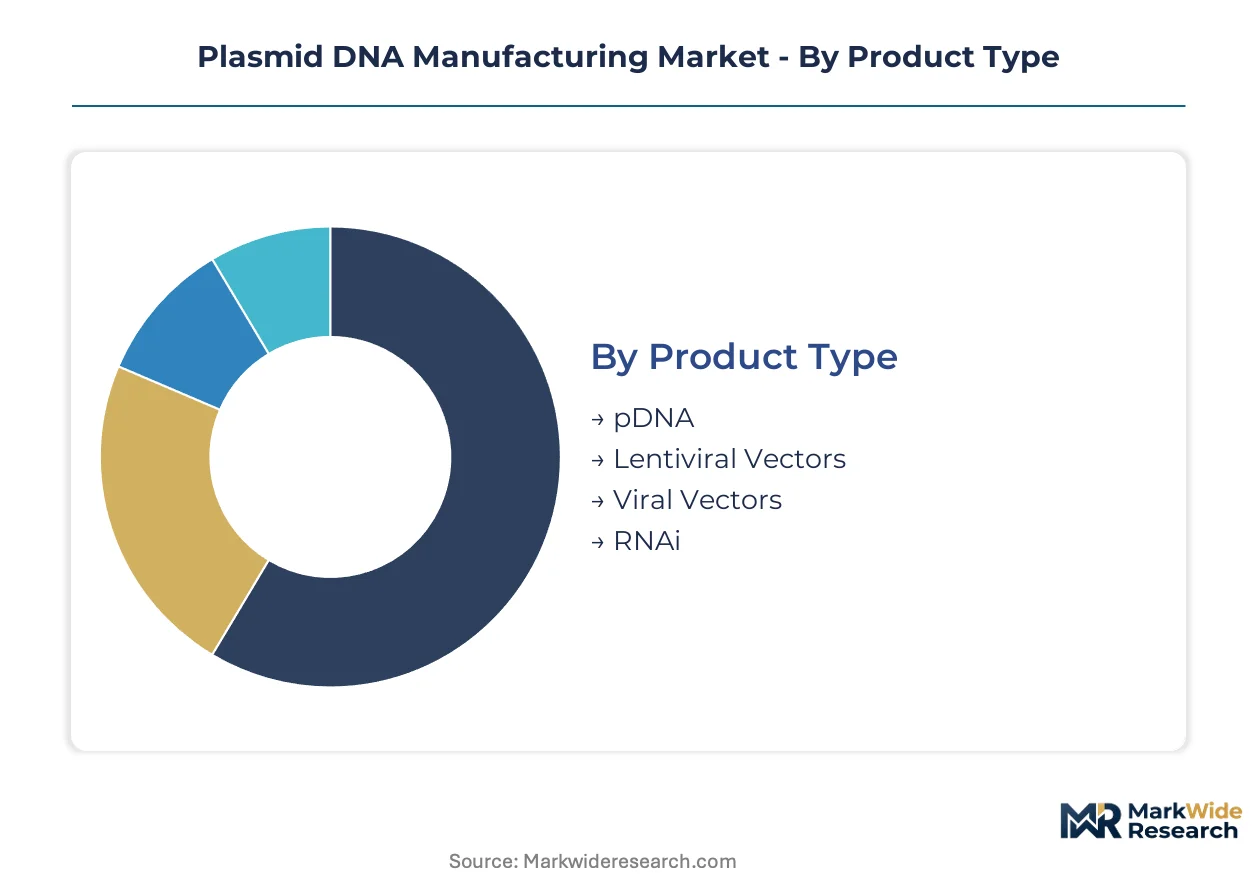
Plasmid DNA manufacturing segments reflect divergent technical requirements and margin structures across the gene therapy value chain. Product format and end-user procurement patterns determine capacity allocation and pricing power for manufacturers competing on GMP compliance timelines.
Product Type:
Margin pools concentrate in clinical-grade formats where endotoxin clearance and supercoiled content validation command premium pricing tiers.
- pDNA:Circular double-stranded DNA propagated in E. coli through fed-batch fermentation, typically 2–20 kilobases, serves as the foundational starting material for viral vector production. FDA gene therapy CMC specifications for residual host cell DNA and endotoxin levels pull demand toward qualified GMP suppliers in Massachusetts and North Carolina. The dominant share belongs to pDNA, while Lentiviral Vectors are closing the gap fastest.
- Lentiviral Vectors:Integrase-deficient viral particles packaged using plasmid transfection systems enable stable gene delivery into dividing and non-dividing cells. Electroporation-based transient transfection platforms in California and Switzerland are accelerating plasmid consumption rates for lentiviral programs targeting hematologic indications.
- Viral Vectors:AAV and other viral delivery systems require multiple plasmid components—helper, transfer, and packaging constructs—multiplying per-dose material requirements.
- RNAi:Short interfering RNA and microRNA expression cassettes delivered via plasmid vectors support functional genomics and therapeutic silencing applications.
Product type selection hinges on therapeutic modality, with integrating vectors absorbing higher plasmid volumes per batch than non-integrating formats.
End User:
Procurement sophistication varies sharply across customer types, with integrated biopharma operators demanding regulatory filing support that smaller research buyers cannot justify.
- Biopharmaceutical Companies:Mid-cap and large developers running Phase III gene therapy programs in Boston and San Francisco anchor high-volume pDNA contracts. Dual-source arrangements with integrated viral vector CDMOs are displacing fragmented multi-vendor strategies among Massachusetts developers seeking supply security for pivotal trials.
- Contract Manufacturing Organizations:Viral vector specialists in the United States and Switzerland are internalizing plasmid production or locking in captive supply agreements to compress lead times. CDMO procurement teams consolidate suppliers around partners capable of simultaneous IND-enabling documentation.
- Research Institutions:Preclinical programs utilize non-GMP pDNA for proof-of-concept studies, prioritizing turnaround speed over regulatory documentation.
- Academic Institutions:Grant-funded laboratories source small-batch plasmid through shared core facilities, with pricing sensitivity limiting engagement with commercial GMP manufacturers.
Biopharmaceutical companies command the dominant volume position, while Contract Manufacturing Organizations are expanding their share fastest through backward integration into plasmid production.
Technology:
Process technology selection determines capital intensity and batch economics, with scale-up bottlenecks concentrated in downstream purification rather than upstream propagation.
- Microbial Fermentation:Fed-batch E. coli cultivation remains the workhorse for bulk plasmid propagation, offering established scale advantages and regulatory familiarity. German and Swiss production sites are absorbing elevated compliance costs from REACH registration requirements for synthetic process chemicals, passing premiums to gene therapy developers.
- Electroporation:Large-scale transient transfection platforms reduce viral vector production timelines, directly accelerating plasmid consumption rates in lentiviral and AAV manufacturing suites across United States CDMO networks.
- Transfection:Calcium phosphate and lipid-based methods persist in early-phase applications where throughput requirements remain modest.
- Polymerase Chain Reaction:Linear amplification supports template generation for specialized applications, though replication fidelity limits therapeutic-grade deployment.
Microbial Fermentation retains the dominant installed base, while Electroporation is gaining share fastest as viral vector programs multiply.
Application:
Application-driven demand exhibits divergent growth velocities, with clinical-stage gene therapies outnumbering approved products and creating capacity commitment uncertainty.
- Gene Therapy:AAV and lentiviral vector programs for monogenic diseases and oncology indications absorb the fastest-expanding pDNA volumes. FDA and EMA guidances on starting material specifications are tightening quality requirements earlier in clinical development, pulling GMP-grade plasmid into Phase I trials.
- Vaccine Development:DNA vaccine platforms experienced renewed investment following platform validation during recent pandemic preparedness exercises, with electroporation delivery systems enabling enhanced immunogenicity.
- Cell Therapy:CAR-T and other engineered cell products utilize plasmid for genetic modification, though mRNA electroporation is displacing plasmid in some manufacturing workflows.
- Diagnostics:Reference standards and controls for molecular assays represent stable, low-volume demand with limited GMP requirements.
Gene Therapy commands the dominant demand position, while Vaccine Development is climbing fastest following platform technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German plasmid exports flow primarily to Swiss viral vector CDMOs and US gene therapy developers, establishing a transatlantic supply corridor that channels European manufacturing capacity into North American clinical pipelines.
United States
FDA gene therapy CMC guidance and IRA domestic manufacturing incentives pull GMP-grade plasmid demand toward Massachusetts and North Carolina production sites. Boston's Kendall Square cluster anchors Phase III program sourcing, while Research Triangle Park CDMOs absorb expanding lentiviral vector plasmid volumes.
Germany
REACH registration requirements for synthetic process chemicals and EMA ATMP quality specifications elevate compliance costs for Hamburg and Heidelberg manufacturing sites. Bavarian production facilities pass these premiums to gene therapy developers through contracted GMP supply agreements.
Switzerland
Swissmedic nucleic acid delivery standards and ISO 20399 adoption timelines position Basel and Zurich CDMO networks as quality gatekeepers for European viral vector programs. Continuous chromatography pilots at Swiss production sites are fragmenting traditional batch purification workflows.
United Kingdom
MHRA post-Brexit gene therapy guidance and Oxford-Cambridge biotech cluster expansion concentrate plasmid demand around Stevenage and Harwell manufacturing corridors. UK CDMOs are internalizing plasmid production to compress lead times for domestic AAV programs.
India
CDSCO gene therapy draft regulations and PLI scheme biopharma incentives attract microbial fermentation investment toward Hyderabad and Bengaluru contract manufacturing parks. Indian suppliers serve preclinical and early-phase pDNA demand for US and European research institutions.
Plasmid DNA Manufacturing Market Key Industry Players
Listed leaders compete with private specialists across capacity commitment timelines, creating a tiered structure where public company scale advantages meet private firm flexibility in batch scheduling. The vendor base concentrates around integrated biologics networks, viral vector CDMOs with backward integration capabilities, and standalone nucleic acid specialists. Dominant competitive moves include captive supply agreements that lock in plasmid volumes and continuous processing validation that compresses regulatory review timelines.
Among Swiss and German fabricators, Lonza and Plasmidfactory GmbH exemplify the integrated biologics archetype, while Aldevron occupies a differentiated position as a standalone nucleic acid specialist. Thermo Fisher Scientific represents scale-driven technology leadership across microbial fermentation platforms. These three anchors illustrate how geographic clustering around Basel and Hamburg production corridors reinforces quality specification advantages in FDA and EMA filing support.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Aldevron |
| Plasmidfactory GmbH |
| Cobra Biologics |
| VGXI, Inc. |
| Thermo Fisher Scientific |
| Nature Technology |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
Sixteen-week lead times for GMP-grade plasmid DNA compress pricing power toward domestic CDMO networks in Massachusetts and North Carolina, while REACH-registered synthetic reagents from German suppliers command 15-20% premiums over animal-derived alternatives. FDA gene therapy CMC specifications and EMA ATMP quality requirements stratify the market into certification-driven tiers where documentation rigor translates directly into contracted rate structures.
Pricing Analysis
Biopharmaceutical companies anchor a three-tier pricing structure across premium, standard, and economy levels, with Phase III program sponsors absorbing premium GMP documentation costs while research institutions prioritize speed over certification. Price differentiation hinges on supercoiled content validation above 90% and endotoxin clearance below 0.1 EU/μg, with FDA filing support services adding substantial uplift. Cost compression in the standard tier is intensifying as mid-cap developers consolidate around dual-source arrangements. Academic buyers exhibit highest price sensitivity, frequently sourcing through shared core facilities rather than commercial GMP manufacturers.
Supply Chain Analysis
Container availability constraints on transatlantic lanes from Hamburg and Rotterdam elevate inbound logistics costs for European manufacturers serving US gene therapy clusters. Production gravity centers on the United States, Germany, and Switzerland, with Swiss CDMOs drawing from Bavarian fermentation capacity and Massachusetts developers sourcing predominantly from domestic networks. Raw material dependencies span anion exchange chromatography resins, recombinant enzyme alternatives to bovine-derived inputs, and synthetic process chemicals subject to REACH registration. Single-source vulnerability for chromatography media creates input bottlenecks during demand surges. Distribution runs through captive supply agreements and integrated viral vector partnerships rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA electroporation workflows are displacing plasmid-based genetic modification in select CAR-T manufacturing processes, forcing incumbents to defend substitution risk through format innovation and regulatory lock-in.
For Market Incumbents: Shield market position by deepening backward integration into linearized DNA formats that reduce immunogenicity concerns and extend relevance beyond circular plasmid applications. Secure captive supply agreements with lentiviral and AAV CDMOs to compress qualification timelines for second-source manufacturers. Invest in continuous processing validation to compress regulatory review timelines and elevate switching costs for gene therapy developers. For New Entrants and Emerging Players: Lead with ISO 20399 compliance capabilities for exosome and lipid nanoparticle applications, opening adjacent markets beyond viral vectors where incumbent documentation advantages remain thinner. Target preclinical research institutions in India and early-phase developers seeking faster turnaround than established GMP suppliers provide. Emphasize turnaround speed and flexible batch sizing as the primary go-to-market angle against legacy campaign-planning workflows. For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained infrastructure play because clinical-stage gene therapies outnumber approved products by a wide margin, creating durable demand for qualified manufacturing slots. Prioritize acquisition targets with validated continuous chromatography systems and established FDA gene therapy CMC filing support capabilities. Watch program advancement rates from Phase I to Phase III as the critical signal for inflection in capacity utilization and pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Validation | Real-time release testing at Swiss and US sites compresses regulatory review timelines for gene therapy sponsors. |
| Linearized DNA Format Development | Minicircle and linear constructs reduce immunogenicity concerns for next-generation EMA ATMP submissions. |
| Captive Supply Agreement Expansion | Dual-source arrangements with viral vector CDMOs in Massachusetts secure pivotal trial supply security. |
| ISO 20399 Compliance Investment | Nucleic acid delivery standards open exosome and lipid nanoparticle markets beyond traditional viral vectors. |
| REACH-Registered Reagent Substitution | Synthetic alternatives to animal-derived enzymes satisfy EMA TSE risk minimization guidance for European filings. |
Research Approach
Cross-validation between primary interviews with gene therapy CMC executives, viral vector manufacturing heads, regulatory affairs leads, and CDMO procurement managers anchors the qualitative findings, supplemented by secondary validation through FDA gene therapy guidance documents, EMA ATMP quality guidelines, ISO 20399 standards filings, and ClinicalTrials.gov pipeline tracking. Bottom-up capacity modeling across microbial fermentation suites and top-down demand triangulation from Phase I-III program counts ensure analytical robustness.
Sensitivity analysis around program attrition rates, regulatory approval timelines, and technology substitution scenarios informs the projection framework across the analysis window. Segmentation dimensions include product format, end-user procurement sophistication, application modality, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical capacity expansion patterns and sponsor-reported plasmid consumption rates per viral vector batch.
Forecasts assume regulatory continuity in FDA and EMA gene therapy frameworks; material policy shifts around starting material specifications or viral safety testing protocols would require re-modeling. Technology substitution risk from mRNA electroporation and synthetic DNA amplification methods represents a specific boundary condition. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Protein Therapeutics Market