
 Levofloxacin Cyclized Ester Market | 2026-2036
Levofloxacin Cyclized Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Levofloxacin Cyclized Ester Market Insights
Hospital procurement of injectable formulations is hardening as the dominant demand channel for levofloxacin cyclized ester intermediates. Ningbo Inno Pharmchem leverages its coastal manufacturing base to serve European and North American API buyers. Cipla anchors its position through backward integration into key intermediate sourcing for domestic and export markets. Teva Pharmaceutical Industries competes on manufacturing scale across multiple fluoroquinolone product lines.
Levofloxacin cyclized ester functions as a critical chiral intermediate in the synthesis of levofloxacin hemihydrate, typically requiring stereoselective cyclization under controlled temperature and pH conditions to achieve enantiomeric excess above 99.5%. The compound serves primarily as a building block for third-generation fluoroquinolone antibiotics targeting Gram-negative and atypical respiratory pathogens. Tablet formulations occupy the largest volume share among product types due to outpatient prescribing patterns, while injection segments capture higher value per kilogram driven by hospital critical-care applications. Infectious disease applications lead absolute demand, though urinary tract infection formulations represent the fastest-expanding application segment as resistance patterns shift prescribing behavior.
FDA current Good Manufacturing Practice enforcement and EMA active substance master file requirements shape supplier entry barriers and batch-release protocols for this intermediate. China's NMPA alignment with ICH Q7 guidelines is forcing domestic manufacturers toward dedicated facility investments. India's CDSCO and state FDA inspectors maintain heightened surveillance of fluoroquinolone API facilities following prior warning letters. Stakeholders must monitor evolving monograph standards from pharmacopeias and regulatory divergence between major import jurisdictions.
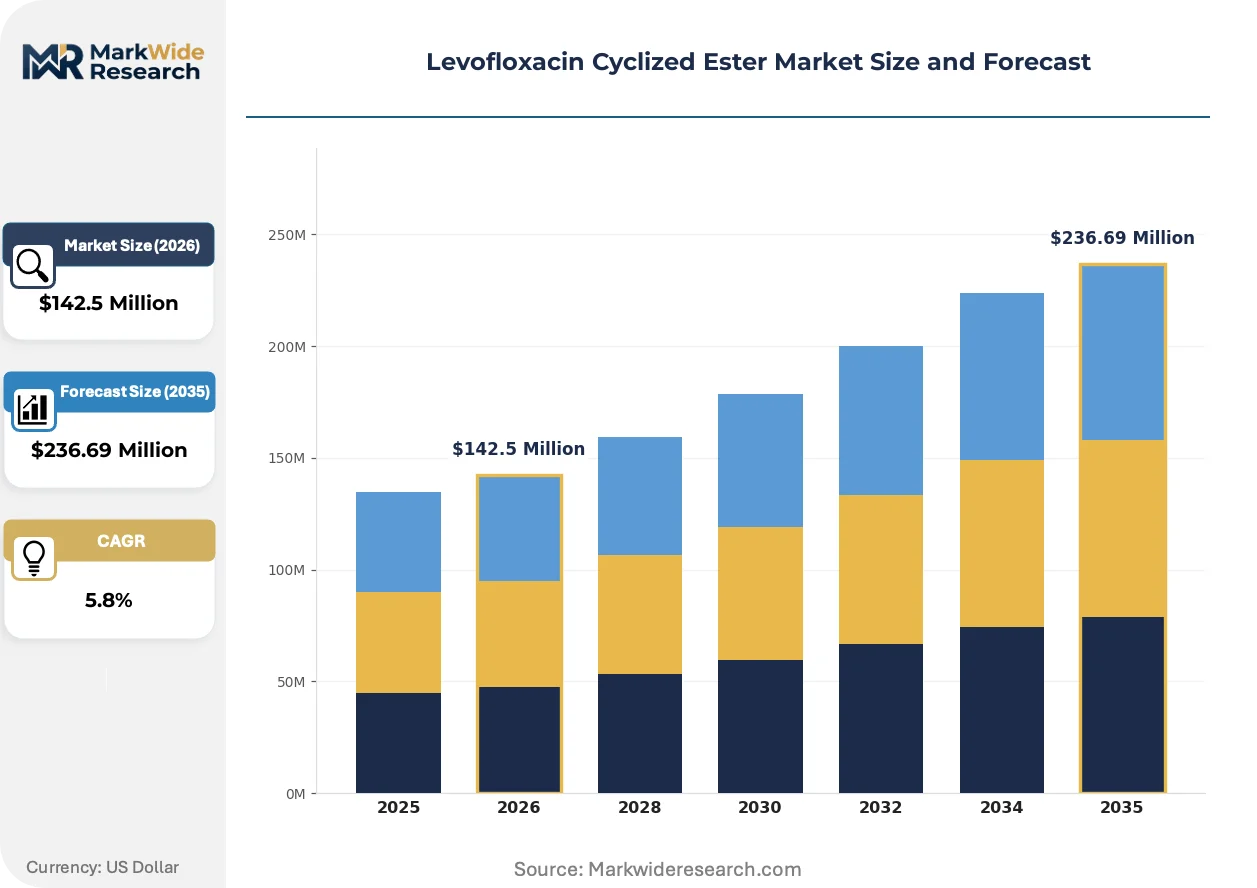
Market Dynamics
Pharmaceutical manufacturers face mounting pressure from FDA and EMA purity mandates that are forcing dedicated facility investments and batch-release protocol overhauls across the levofloxacin cyclized ester supply base.
Growth Catalysts
- Respiratory infection burden:Hospital procurement of injectable fluoroquinolone formulations is hardening as the dominant demand channel across India and China, pulling intermediate volumes upward through API synthesis clusters.
- ICH Q7 alignment:China's NMPA adoption of international GMP standards is accelerating facility modernization investments that expand export-qualified manufacturing capacity.
- Urinary tract infection prescribing:Shifting resistance patterns in Gram-negative pathogens are expanding levofloxacin utilization in outpatient urology clinics, driving tablet formulation demand for the cyclized ester intermediate.
Market Restraints
- Enantiomeric purity thresholds:Stereoselective cyclization requiring 99.5% enantiomeric excess demands specialized chiral catalysts and temperature-controlled reactors, compressing margin structures for non-specialized producers.
- API synthesis concentration:Intermediate supply chains cluster in specific coastal manufacturing zones of Zhejiang and Gujarat, creating geographic vulnerability to regional environmental enforcement actions or logistics disruptions.
- Fluoroquinolone class scrutiny:EMA pharmacovigilance reviews and FDA boxed warning expansions for tendon and neurological adverse events are constraining formulation growth in select European markets.
Strategic Opportunities
- CDSCO state-level surveillance:Heightened Indian FDA inspection intensity following prior warning letters is creating qualification windows for exporters meeting dedicated facility standards ahead of domestic competitors.
- Continuous flow chemistry:Convergence of microreactor technology with process analytical technology (PAT) is enabling real-time chiral control that reduces batch failure rates and solvent waste volumes.
- Hospital formulary consolidation:Critical-care antibiotic stewardship programs are concentrating procurement through centralized hospital pharmacy committees, favoring intermediates from vertically integrated API suppliers.
Industry Challenges
- Active substance master file compilation:EMA ASMF documentation requirements demand 12-18 month preparation cycles with specialized regulatory affairs expertise that smaller intermediate suppliers struggle to resource.
- Legacy quality system integration:Paper-based batch records and standalone equipment in older facilities require capital-intensive digitization to meet data integrity expectations from European and North American API buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Levofloxacin Cyclized Ester Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Oral Solutions, Infusions End User: Hospitals, Clinics, Pharmacies, Contract Research Organizations Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Infectious Diseases, Respiratory Infections, Urinary Tract Infections, Skin Infections |
| Companies Covered | Ningbo Inno Pharmchem Co.,Ltd., Allfluoro Pharmaceutical Co.,Ltd., Skylead Pharmaceuticals & Chemicals, Jiangxi Chibang Pharmaceutical Co.,Ltd., Hangzhou Dawn Ray Pharmaceutical Co.,Ltd., Cipla, Aurobindo Pharma, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Levofloxacin Cyclized Ester Market Trends and Innovations
Process intensification and regulatory digitization are compressing development timelines while reshaping supplier qualification protocols across the levofloxacin cyclized ester value chain.
Continuous manufacturing platforms employing microreactor arrays for stereoselective cyclization are modularizing production scale, allowing API manufacturers to match capacity increments to hospital procurement contract volumes without batch-size penalties. European and North American buyers are qualifying these systems ahead of traditional stirred-tank operations. The technology is modularizing capital deployment patterns and reducing minimum efficient scale thresholds for market entry.
EMA's updated active substance master file guidance and FDA's enhanced data integrity expectations are forcing documentation system overhauls that extend batch-release timelines. Intermediate suppliers must implement audit trail software and electronic signature workflows to maintain qualified supplier status. Facilities in India and China are responding with dedicated regulatory technology investments ahead of scheduled re-inspections.
Hospital pharmacy committees are consolidating antibiotic procurement through sole-source contracts tied to pharmacoeconomic outcomes, displacing fragmented distributor networks. API manufacturers are responding with direct supply agreements that bundle intermediate traceability guarantees. This concentration is most visible in tertiary hospital systems across Germany and the United States where formulary control has tightened post-pandemic.
Levofloxacin Cyclized Ester Market Segmentation
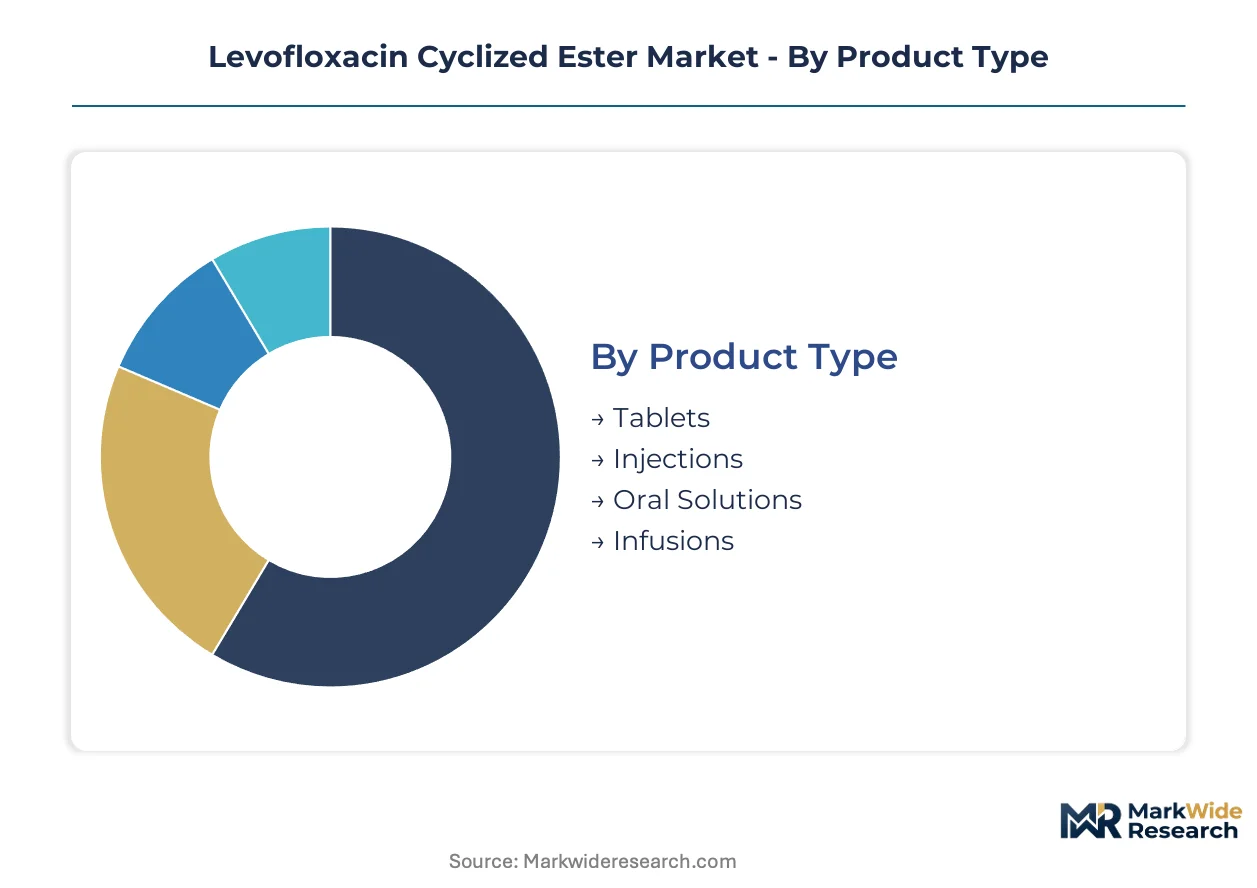
Segmentation in the levofloxacin cyclized ester market reveals how formulation chemistry, procurement authority, and resistance pattern shifts allocate value across the value chain. Hospital formulary committees and API synthesis economics determine which intermediate specifications command premium pricing.
Product Type:
Hospital procurement committees weight manufacturing complexity against therapeutic urgency when qualifying intermediate suppliers for different formulation outputs.
- Tablets:Oral solid dosage forms require intermediate batches meeting standard purity grades for high-volume outpatient dispensing. Demand concentrates in retail pharmacy chains across India and China where urology and respiratory prescriptions drive repeat orders.
- Injections:Parenteral formulations demand elevated endotoxin control and sterile intermediate handling protocols that compress supplier margins. Hospital critical-care procurement in tertiary medical centers across Germany and the United States pulls volumes through vertically integrated API manufacturers.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations requiring dose flexibility.
- Infusions:Large-volume parenteral bags for extended antibiotic therapy require specialized intermediate solubility profiles.
Volume sits with Tablets; growth tilts toward Injections.
End User:
Procurement sophistication varies sharply across customer types, with centralized purchasing systems demanding traceability documentation that fragments the supplier base.
- Hospitals:Tertiary care institutions with antibiotic stewardship programs mandate batch-level intermediate certificates of analysis and dedicated facility audits. Infectious disease wards in Mumbai and Shanghai medical centers anchor demand for high-purity cyclized ester lots.
- Clinics:Outpatient facilities concentrate tablet formulation demand through distributor networks with less stringent documentation requirements.
- Pharmacies:Community and hospital outpatient dispensaries handle the final patient-facing distribution of finished levofloxacin products.
- Contract Research Organizations:CROs engaged in bioequivalence studies require small-batch intermediate supplies with custom specification flexibility.
Procurement volume clusters at Hospitals; Clinics are expanding most quickly as ambulatory care shifts post-acute antibiotic therapy.
Distribution Channel:
Channel selection determines working capital intensity and regulatory exposure for intermediate suppliers navigating qualified buyer lists.
- Retail:Direct pharmacy sales of finished formulations create pull-through demand for standard-grade intermediate batches.
- Wholesale:Distributor networks aggregate fragmented clinic and pharmacy demand across regional territories.
- Online:E-commerce platforms for pharmaceutical intermediates are gaining traction among smaller API manufacturers seeking spot purchases.
- Direct Sales:Long-term supply agreements between intermediate manufacturers and vertically integrated API producers eliminate margin capture by intermediaries.
Wholesale channels handle current volume; Direct Sales are climbing the fastest as hospital formulary consolidation favors sole-source contracts.
Application:
Resistance surveillance data from national health institutes redirect prescribing patterns and reshape intermediate demand by therapeutic indication.
- Infectious Diseases:Broad-spectrum Gram-negative coverage maintains levofloxacin as a first-line option in hospital protocols. Tertiary centers in the United States and Germany sustain demand through empiric therapy guidelines for sepsis and pneumonia.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis represent the historical core indication with stable but mature demand curves.
- Urinary Tract Infections:Escalating resistance to trimethoprim-sulfamethoxazole and nitrofurantoin is redirecting outpatient urology prescribing toward fluoroquinolones.
- Skin Infections:Complicated skin and soft tissue infections command smaller intermediate volumes as alternative agents dominate this category.
Infectious Diseases applications anchor current volume; Urinary Tract Infections represent the steepest expansion trajectory as resistance patterns shift outpatient prescribing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India dominate cyclized ester output for levofloxacin APIs, while hospital procurement in Germany and the United States pulls volumes through qualified supply chains. Regulatory divergence between FDA, EMA, and NMPA compliance standards fragments supplier qualification across import markets.
China
Zhejiang coastal manufacturing clusters anchor intermediate synthesis capacity serving European and North American API buyers. NMPA alignment with ICH Q7 guidelines forces dedicated facility investments among Zhejiang province producers seeking export qualification. Ningbo manufacturers leverage port infrastructure for bulk intermediate shipments to Indian formulation sites.
India
Domestic respiratory infection burden and export-oriented API synthesis create dual demand channels for cyclized ester intermediates. CDSCO state-level surveillance following prior FDA warning letters accelerates quality system upgrades among Gujarat and Maharashtra manufacturers. Hyderabad and Ahmedabad clusters specialize in chiral intermediate production for vertically integrated pharmaceutical exporters.
United States
Hospital antibiotic stewardship programs concentrate procurement through centralized pharmacy committees demanding batch-level documentation. FDA current Good Manufacturing Practice enforcement and data integrity expectations filter qualified suppliers to dedicated-fabrication sources. New Jersey and Massachusetts tertiary medical centers anchor injectable formulation demand for critical-care applications.
Germany
EMA active substance master file requirements and pharmacovigilance reviews shape supplier entry barriers for fluoroquinolone intermediates. Bavarian and North Rhine-Westphalia hospital networks drive high-purity cyclized ester demand through empiric sepsis therapy protocols. Frankfurt and Munich distribution hubs coordinate just-in-time intermediate deliveries to API synthesis facilities.
Switzerland
Swissmedic quality standards and proximity to German pharmaceutical markets position Swiss traders as qualification intermediaries for Asian suppliers. Basel and Zurich pharmaceutical logistics clusters specialize in documentation-heavy intermediate shipments requiring cold-chain integrity. Swiss-based API manufacturers source cyclized ester through audited Asian supply chains meeting European pharmacopeia monographs.
Levofloxacin Cyclized Ester Market Competitive Landscape
Top-tier vendors anchor hospital-direct supply chains, while mid-scale specialists serve distributor networks with standard-grade intermediate batches. The supplier base stratifies across three tiers: coastal Chinese manufacturers with export-qualified dedicated facilities, Indian backward-integrated pharmaceutical companies controlling captive intermediate supply, and European traders managing qualification documentation for Asian sources. Competitive positioning hardens around EMA ASMF compilation capabilities and FDA inspection readiness. Consolidation pressure favors acquisitions of CDSCO-compliant facilities and partnerships with continuous-flow technology licensors.
Among coastal Chinese manufacturers, Ningbo Inno Pharmchem Co.,Ltd. and Jiangxi Chibang Pharmaceutical Co.,Ltd. occupy positions within the export-qualified tier, representing archetypes of Zhejiang-based producers leveraging port logistics for North American and European API buyers. Within the Indian pharmaceutical complex, Cipla and Aurobindo Pharma exemplify backward-integrated formulators securing cyclized ester supply through in-house or affiliated intermediate production. These four entities represent distinct competitive vectors: Chinese coastal exporters competing on scale and logistics, Indian integrated players competing on formulation-to-intermediate traceability.
| Leading Market Players |
|---|
| Ningbo Inno Pharmchem Co.,Ltd. |
| Allfluoro Pharmaceutical Co.,Ltd. |
| Skylead Pharmaceuticals & Chemicals |
| Jiangxi Chibang Pharmaceutical Co.,Ltd. |
| Hangzhou Dawn Ray Pharmaceutical Co.,Ltd. |
| Cipla |
| Aurobindo Pharma |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Zhejiang and Gujarat anchor cyclized ester production, their conservative balance-sheet discipline limiting capacity overbuild while sustaining pricing power through dedicated-facility scarcity. These ownership structures resist price wars that erode margin structures, instead favoring long-term contract stability with vertically integrated API buyers.
Pricing Analysis
Margin tightening in standard-grade batches reflects enantiomeric purity thresholds demanding specialized chiral catalysts and temperature-controlled reactors. Three-tier pricing structure across premium, standard, and economy levels separates export-qualified dedicated facilities from domestic-grade producers and spot-market traders. Cost-down pressure on economy-tier lots accelerates because Indian and Chinese state-level surveillance is disqualifying paper-based quality systems. Hospital procurement committees demonstrate lowest price sensitivity, while distributor networks serving outpatient clinics negotiate aggressively on standard-grade volumes.
Supply Chain Analysis
Regional distribution centers in Ningbo, Hyderabad, and Ahmedabad coordinate hub-and-spoke patterns for intermediate shipments to European and North American API synthesis sites. Manufacturing concentrates in China, India, and Switzerland, with Swiss traders managing documentation-heavy cold-chain logistics. Raw material dependencies rest on specialty fluorinated feedstocks, chiral auxiliary reagents, and high-purity solvents. Single-source vulnerability from environmental enforcement actions in coastal Zhejiang zones threatens batch continuity. Distribution runs through direct long-term supply agreements between intermediate manufacturers and backward-integrated pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow chemistry platforms are displacing legacy stirred-tank operations across stereoselective cyclization processes, compressing batch failure rates and solvent waste volumes while resetting capital efficiency benchmarks.
For Market Incumbents: Hedge against continuous manufacturing disruption by patenting microreactor process configurations before technology licensors consolidate control. Acquire CDSCO-compliant facilities in Gujarat to preempt state-level surveillance disqualification of competitors. Reinforce hospital-direct supply relationships through bundled intermediate traceability guarantees that distributor networks cannot replicate. For New Entrants and Emerging Players: Launch via spot-market e-commerce platforms serving smaller API manufacturers seeking custom specification flexibility outside long-term contracts. Target urinary tract infection formulation demand in outpatient urology clinics where resistance-pattern shifts are expanding fluoroquinolone prescribing fastest. Penetrate through regulatory technology partnerships that accelerate EMA ASMF documentation cycles for mid-scale producers. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian backward-integrated formulators with captive intermediate supply and pending FDA warning letter resolution. Long-term viability hinges on 5-10 year antimicrobial stewardship program consolidation sustaining hospital formulary concentration. Watch for NMPA ICH Q7 enforcement intensity as inflection signal for export-qualified capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Microreactor arrays enable real-time chiral control that reduces batch failure rates for European API buyers. |
| EMA ASMF Documentation Investment | Electronic audit trail systems maintain qualified supplier status through enhanced data integrity expectations. |
| Backward Integration into Intermediate Supply | Cipla and Aurobindo secure cyclized ester through in-house production eliminating margin capture by traders. |
| Hospital Formulary Direct Contracts | Sole-source agreements with tertiary medical centers bundle traceability guarantees displacing fragmented distributors. |
| CDSCO-Compliant Facility Acquisition | State-level surveillance following prior FDA warning letters creates qualification windows for exporters ahead of domestic competitors. |
Research Methodology
Independent corroboration across regulatory affairs directors, API synthesis plant managers, and hospital procurement officers underwrites the qualitative findings. Primary fieldwork with chiral chemistry specialists, pharmaceutical distribution channel partners, and CDSCO inspection consultants combined with secondary validation from FDA warning letter databases, EMA ASMF submission records, and Indian state FDA enforcement notices. Bottom-up capacity assessments across Zhejiang and Gujarat manufacturing clusters triangulate against top-down demand estimates from hospital formulary consolidation trends.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end user procurement authority, distribution channel structure, and therapeutic application indication. CAGRs derive from regression analysis of historical intermediate pricing against purity grade premiums and facility qualification status. Forecast inputs incorporate NMPA ICH Q7 alignment timelines and EMA pharmacovigilance review intensity for fluoroquinolone class restrictions.
Regulatory enforcement intensity shifts, antimicrobial resistance pattern redirections, and continuous manufacturing technology diffusion rates are the dominant revision risks. Forecasts reflect documented assumptions regarding hospital stewardship program consolidation speed and export qualification facility commissioning delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Global Thrombin Market