
 Protein Therapeutics Market | 2026-2036
Protein Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Therapeutics Market Intelligence
The divergence between premium innovator biologics and commodity biosimilar tiers is hardening as payers tighten formularies and manufacturing complexity widens cost spreads. AbbVie Inc. leverages its immunology portfolio depth to sustain pricing power in high-margin monoclonal antibody segments. Novo Nordisk anchors metabolic disorder therapies through vertical control over peptide production and fill-finish capacity. Roche competes on oncology biologic innovation while navigating biosimilar erosion in mature European markets.
Protein therapeutics comprise purified or recombinant proteins engineered for pharmacological activity, typically exceeding 50 amino acids with tertiary structure-dependent function, manufactured through mammalian cell culture or microbial fermentation systems. These agents treat disease by replacing deficient proteins, modulating signaling pathways, or eliciting immune responses. Monoclonal antibodies occupy the largest revenue pool given established oncology and autoimmune indications, while recombinant proteins show fastest volume expansion in metabolic disorder applications. Subcutaneous delivery modes gain share as formulation technologies reduce injection frequency and enable self-administration outside hospital settings.
FDA, EMA, and WHO frameworks govern protein therapeutics through biosimilar comparability protocols, good manufacturing practice inspections, and international reference standard harmonization. These regulators shape demand by determining interchangeability designations, batch release requirements, and post-market pharmacovigilance obligations that directly affect product lifecycle economics. Stakeholders must monitor evolving biosimilar substitution policies and manufacturing site inspection backlogs as decisive variables for capacity planning and geographic market prioritization.
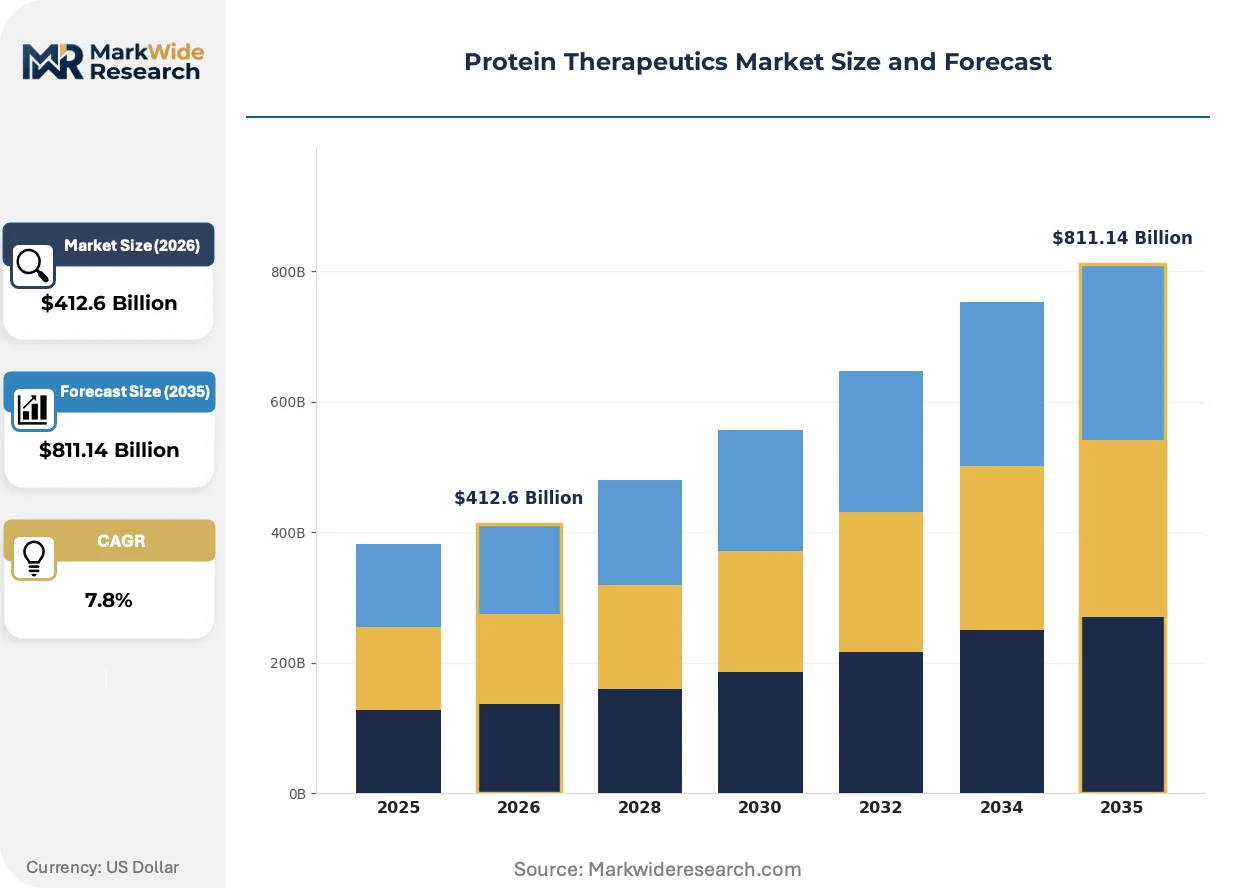
Market Dynamics
Biosimilar substitution policies are compressing pricing power for mature biologics while forcing innovators to accelerate next-generation molecule development. Manufacturing site inspection backlogs at FDA and EMA are creating geographic supply bottlenecks that reshape capacity planning decisions.
Growth Catalysts
- IRA Medicare Price Negotiation:The US Inflation Reduction Act's biologic price negotiation provisions are accelerating pipeline investments in novel protein constructs to offset revenue erosion in mature categories.
- Subcutaneous Formulation Advances:Concentrated protein formulations and device integration are shifting administration from infusion centers to home settings, expanding addressable patient populations.
- Oncology Biologics Demand:Academic medical centers in the United States, Germany, and Japan are driving adoption of checkpoint inhibitors and antibody-drug conjugates for solid tumor indications.
Market Restraints
- Chinese Hamster Ovary Cell Supply Concentration:Mammalian cell culture media and single-use bioreactor components concentrate among three dominant suppliers, creating input vulnerability.
- EMA Batch Release Complexity:European Medicines Agency centralized batch certification timelines extend lead times for products manufactured outside the European Economic Area.
- Peptide Manufacturing Cost Structure:Solid-phase peptide synthesis raw materials and chromatography resins face volatile pricing due to petrochemical feedstock exposure.
Strategic Opportunities
- Indian CDMO Expansion:Contract development and manufacturing organizations in India are capturing fill-finish and analytical services as Western sponsors seek cost arbitrage.
- WHO Prequalification Pathway:World Health Organization biosimilar prequalification is opening institutional procurement channels in low- and middle-income country markets.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with continuous capture chromatography is rewriting facility throughput economics.
Industry Challenges
- Process Analytical Technology Talent Gap:Biopharmaceutical manufacturers face scarcity of professionals trained in multivariate data analysis and real-time release testing implementation.
- Comparability Protocol Execution:FDA and EMA post-approval manufacturing change management requires extensive analytical characterization that strains internal capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Therapeutics Market |
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $811.14 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Vaccines, Enzymes Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Metabolic Disorders Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Inhalation End User: Hospitals, Clinics, Research Labs, Pharmaceutical Companies |
| Companies Covered | AbbVie Inc., Amgen Inc., Bristol-Myers Squibb, Sanofi, Thermo Fisher Scientific Inc., Pfizer Inc., Johnson and Johnson, Novo Nordisk, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Therapeutics Market Strategic Shifts & Innovations
Protein engineering platforms and delivery technologies are compressing development timelines while expanding the therapeutic modalities competing for the same clinical indications and payer budgets.
Single-domain antibody formats and bispecific constructs are rewriting target engagement possibilities in immuno-oncology. Large pharmaceutical sponsors are prioritizing these modalities in early-phase portfolios. The structural consequence is compression of traditional monoclonal antibody lifecycle economics as differentiation becomes harder.
EMA's revised guideline on similar biological medicinal products containing biotechnology-derived proteins as active substance is tightening analytical similarity thresholds. This regulatory friction is extending development timelines for European biosimilar filings. Oncology and immunology indications face the steepest evidentiary burdens.
Hospital and integrated delivery network procurement is consolidating supplier relationships around preferred biologic vendors with interchangeability designations. Group purchasing organizations in the United States are negotiating exclusive distribution agreements that disintermediate traditional wholesaler channels. This concentration is most visible in oncology and autoimmune therapeutic categories where infusion center economics dominate site-of-care decisions.
Protein Therapeutics Market Segmentation
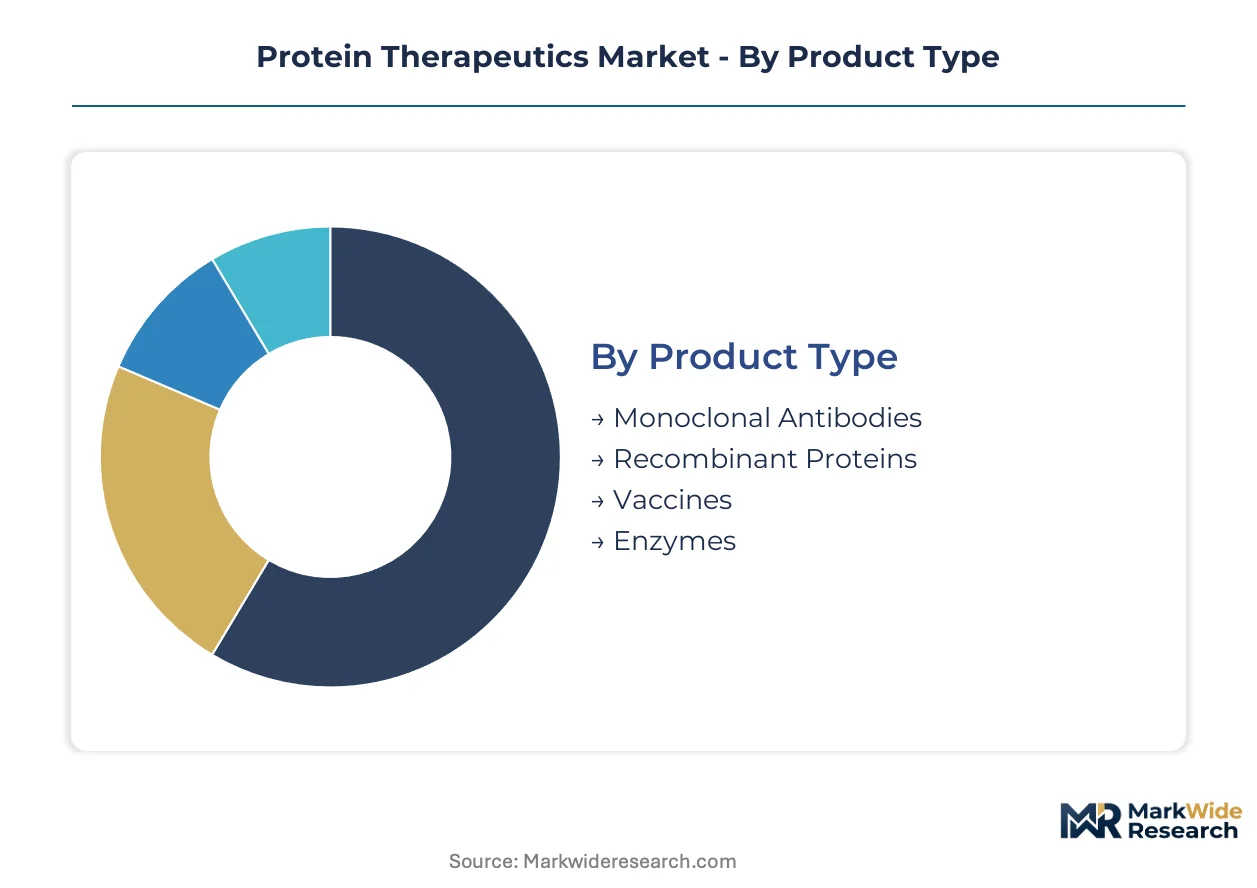
Protein therapeutics segmentation reveals how manufacturing complexity and clinical application intersect to determine capacity allocation. Supply concentration in mammalian cell culture systems shapes which product categories absorb capital investment and which face input bottlenecks.
Product Type:
Manufacturing platform economics concentrate supply capacity among modalities with established cell culture infrastructure and regulatory pathways.
- Monoclonal Antibodies:Large glycoproteins produced via Chinese hamster ovary cell culture, requiring extensive downstream purification and viral clearance validation. Demand concentrates in academic medical centers across the United States, Germany, and Japan for oncology and autoimmune indications, though biosimilar substitution policies are compressing pricing power in mature markets.
- Recombinant Proteins:Engineered polypeptides manufactured through microbial fermentation or mammalian expression systems, encompassing hormones, growth factors, and clotting factors. Metabolic disorder applications in the United States and Japan are driving volume expansion as formulation advances enable less frequent dosing.
- Vaccines:Immunogenic protein constructs including recombinant subunit and virus-like particle formats, produced across diverse expression platforms from yeast to insect cells.
- Enzymes:Catalytic proteins for replacement therapy in rare genetic disorders, typically requiring specialized production and ultra-pure formulation standards.
Monoclonal antibodies absorb the bulk of installed capacity; recombinant proteins are expanding most quickly.
Therapy Area:
Clinical development pipelines and reimbursement dynamics determine which disease categories attract manufacturing investment and regulatory prioritization.
- Oncology:Checkpoint inhibitors, antibody-drug conjugates, and bispecific constructs dominate late-phase development portfolios. The United States, Germany, and Japan drive adoption through academic medical center networks, though EMA batch release complexity extends lead times for products manufactured outside the European Economic Area.
- Autoimmune Disorders:TNF inhibitors, IL inhibitors, and B-cell targeting biologics constitute a mature but high-volume category facing intensifying biosimilar competition.
- Infectious Diseases:Monoclonal antibody prophylaxis and therapeutic vaccines target resistant pathogens and emerging viral threats.
- Metabolic Disorders:Insulin analogs, GLP-1 agonists, and enzyme replacement therapies are gaining share as subcutaneous formulation advances shift administration to home settings.
Oncology commands the deepest development pipelines; metabolic disorders are climbing the fastest as peptide manufacturing scales to serve expanding patient populations.
Delivery Mode:
Formulation technology capabilities and site-of-care economics determine which administration routes capture investment and patient preference.
- Subcutaneous:Concentrated protein formulations and device-integrated delivery systems enable self-administration outside hospital settings. Formulation advances in the United States are expanding addressable populations for metabolic and autoimmune therapies.
- Intravenous:Infusion center administration remains standard for high-dose oncology biologics and complex glycoproteins requiring precise pharmacokinetic control.
- Intramuscular:Vaccine delivery and certain hormone therapies utilize this route for depot release and immune response optimization.
- Inhalation:Pulmonary delivery of protein therapeutics addresses localized respiratory conditions, though formulation stability challenges limit current adoption.
Intravenous delivery retains the largest installed manufacturing footprint; subcutaneous formulations are gaining share fastest as patient preference shifts toward home-based care.
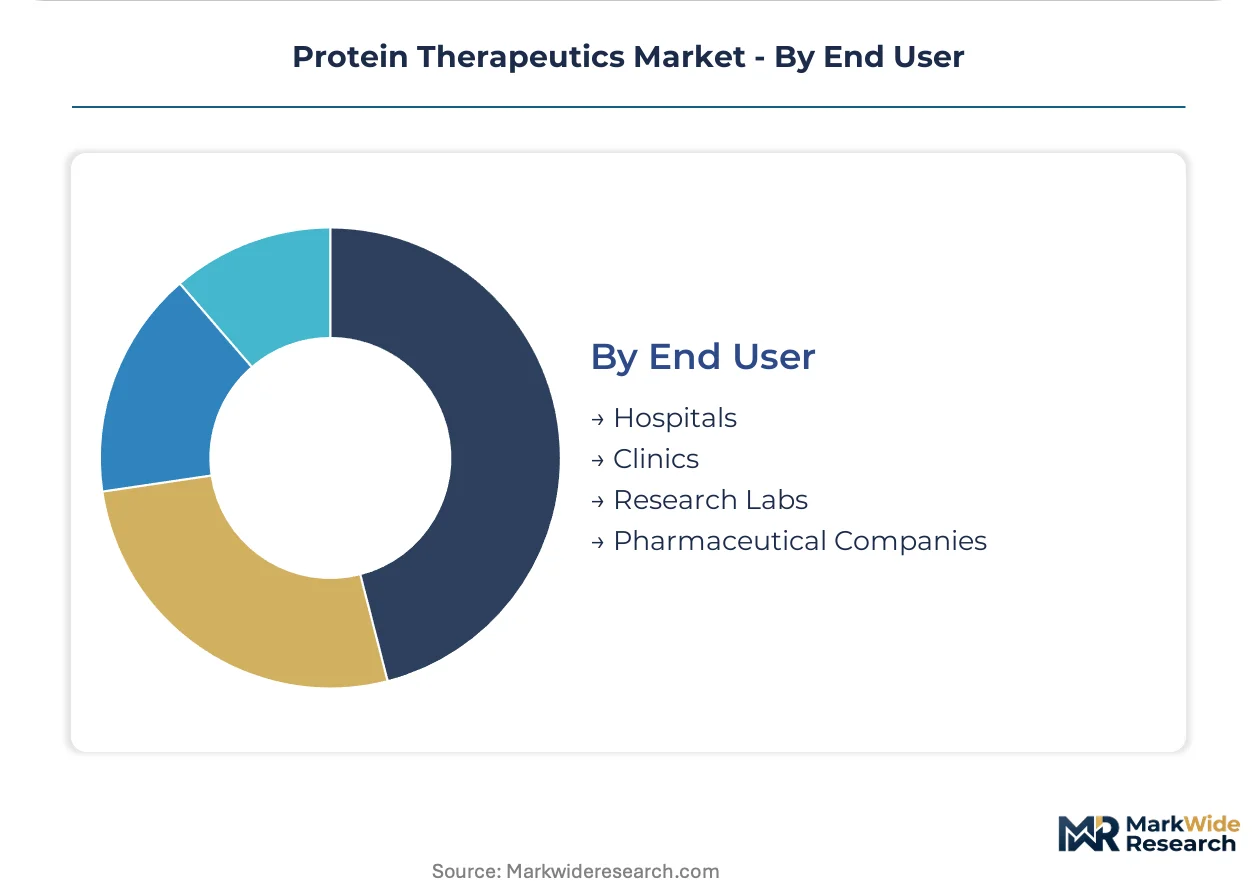
End User:
Procurement consolidation and site-of-care economics determine which customer categories shape supplier relationships and distribution strategies.
- Hospitals:Integrated delivery networks and academic medical centers concentrate demand for oncology biologics and infusion-administered therapies. Group purchasing organizations in the United States are negotiating exclusive distribution agreements that disintermediate traditional wholesaler channels.
- Clinics:Outpatient infusion centers and specialty practices handle stable patients on established biologic regimens, particularly in autoimmune and metabolic categories.
- Research Labs:Preclinical and clinical trial material supply supports pipeline development, with demand tied to sponsor funding cycles and regulatory milestone timing.
- Pharmaceutical Companies:In-licensing and partnership activities drive demand for contract manufacturing and analytical services, particularly among emerging biotechnology sponsors.
Hospitals absorb the bulk of commercial volume; pharmaceutical companies are expanding their outsourcing footprint fastest as pipeline complexity outpaces internal manufacturing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors North American protein therapeutic development, with academic medical centers driving clinical adoption and FDA regulatory pathways shaping commercialization timelines across multiple continents.
United States
Oncology biologics demand concentrates in academic medical centers across Massachusetts, California, and Texas. The IRA Medicare price negotiation provisions are accelerating pipeline investments in novel protein constructs. Greater Boston's biotech cluster leads monoclonal antibody development through proximity to MIT and Harvard research infrastructure.
Germany
EMA batch release complexity extends lead times for products manufactured outside the European Economic Area. The country's national pharmaceutical regulator enforces stringent analytical similarity thresholds for biosimilar filings. Baden-Württemberg's industrial corridor hosts concentrated fill-finish capacity serving European distribution networks.
Japan
PMDA review timelines and reimbursement negotiations shape commercial entry for metabolic disorder therapies. METI industrial policy supports domestic peptide manufacturing scale-up. Tokyo-Osaka corridor demand for subcutaneous formulations is expanding as patient preference shifts toward home-based administration.
India
Contract development and manufacturing organizations in Hyderabad and Bangalore are capturing analytical services as Western sponsors seek cost arbitrage. CDSCO regulatory harmonization with ICH guidelines is streamlining export pathways. Maharashtra's biotech parks are scaling mammalian cell culture capacity for biosimilar production.
Switzerland
Swissmedic oversight of biologics manufacturing maintains high barriers to European market entry. Basel-Zurich corridor concentration of pharmaceutical headquarters drives regional procurement consolidation. The country's specialized logistics infrastructure supports temperature-controlled distribution of high-value protein therapeutics.
Protein Therapeutics Market Key Industry Players
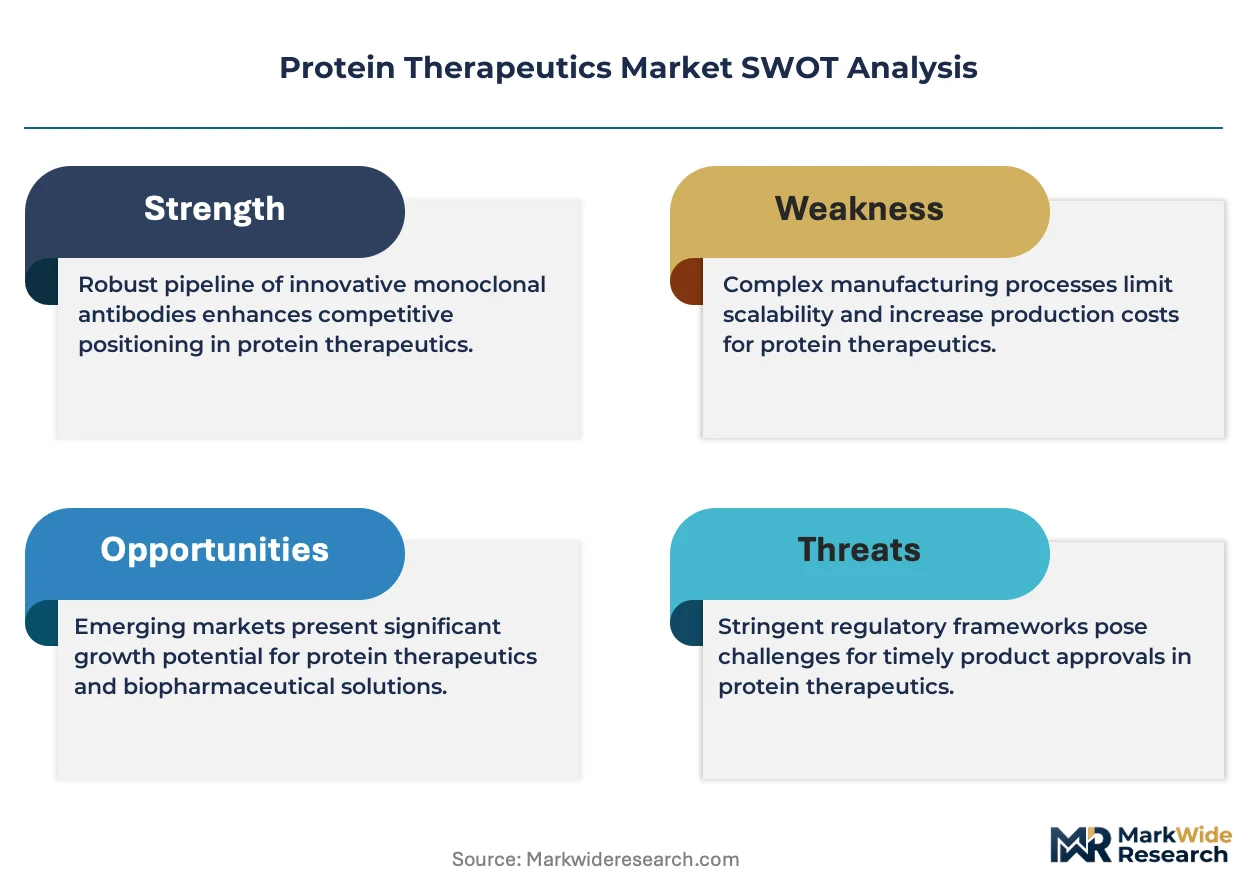
Capital-heavy producers compete with asset-light designers across the protein therapeutics landscape, with manufacturing scale determining competitive position more than molecular innovation alone. The market structure consolidates around three tiers: integrated innovators with captive bioreactor networks, specialized CDMOs offering capacity arbitrage, and emerging biotechnology sponsors outsourcing entirely. Strategic moves center on backward integration into peptide raw materials and geographic diversification of manufacturing sites to mitigate regulatory inspection backlogs.
Among North American pharmaceutical conglomerates, AbbVie Inc., Amgen Inc., and Bristol-Myers Squibb occupy positions representing distinct competitive archetypes. AbbVie exemplifies the immunology portfolio depth model sustaining pricing power in mature monoclonal antibody categories. Amgen represents the biotechnology originator transitioning toward biosimilar defense through manufacturing efficiency investments. Bristol-Myers Squibb anchors the oncology-focused strategy prioritizing checkpoint inhibitor development over metabolic disorder diversification.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| Bristol-Myers Squibb |
| Sanofi |
| Thermo Fisher Scientific Inc. |
| Pfizer Inc. |
| Johnson and Johnson |
| Novo Nordisk |
| Roche |
| Others |
Cost & Logistics Intelligence
Process analytical technology specialists concentrated in the Greater Boston corridor command compensation premiums that compress margins for mid-tier biosimilar producers while widening spreads between innovator and commodity pricing tiers. Labor-cost differentials between United States-based formulation scientists and Indian analytical teams enable three-tier pricing stratification across premium monoclonal antibodies, standard recombinant proteins, and economy peptide segments.
Pricing Analysis
Outcome-based pricing anchors oncology biologics reimbursement through progression-free survival metrics tied to checkpoint inhibitor performance. Three-tier pricing structure across premium, standard, and economy levels reflects biosimilar interchangeability designation status, FDA approval pathway complexity, and volume commitment scale from integrated delivery networks. Cost compression in mature TNF inhibitor categories is intensifying because Medicare price negotiation provisions force reference price adjustments. Hospital procurement committees exhibit highest price sensitivity for chronic administration therapies, while academic medical centers prioritize clinical efficacy data over acquisition cost for novel immuno-oncology constructs.
Supply Chain Analysis
Regional distribution centers in Basel, Hyderabad, and Singapore orchestrate hub-and-spoke patterns for temperature-sensitive biologics requiring cold-chain integrity through last-mile delivery. Manufacturing concentrates in the United States, Germany, and India for mammalian cell culture capacity, with Ireland and Switzerland hosting specialized fill-finish operations. Chinese hamster ovary cell media, single-use bioreactor bags, and chromatography resins constitute critical input dependencies. Single-source vulnerability concentrates among three dominant suppliers for cell culture media components. Distribution runs through pharmaceutical wholesaler networks with direct-to-hospital agreements displacing traditional channel intermediaries in oncology categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing technology is displacing legacy batch manufacturing platforms, compressing facility capital intensity while rewriting competitive economics for protein therapeutic production. Stakeholders must position around this transition to capture margin expansion and capacity flexibility advantages.
For Market Incumbents: Extend manufacturing efficiency advantages through backward integration into peptide raw materials and chromatography resin supply. Accelerate next-generation molecule development to offset biosimilar erosion in mature monoclonal antibody categories. Captive bioreactor networks in Singapore and Ireland provide geographic diversification against FDA and EMA inspection backlogs that threaten supply continuity.
For New Entrants and Emerging Players: Capture analytical services and fill-finish capacity contracts from Western sponsors seeking cost arbitrage in Indian CDMO partnerships. Target metabolic disorder applications with subcutaneous formulation expertise as patient preference shifts toward home-based administration. WHO prequalification pathway offers institutional procurement access in low- and middle-income country markets with reduced regulatory friction.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized CDMOs possessing continuous bioprocessing capabilities given IRA-driven pipeline investment acceleration. Five-to-ten year viability favors asset-light designers with captive manufacturing partnerships over capital-heavy integrated producers facing biosimilar margin compression. Signal to watch is EMA batch release timeline extension for products manufactured outside the European Economic Area.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion cell culture integration rewrites facility throughput economics for mammalian-derived biologics. |
| Regulatory Approval Pathway | WHO prequalification opens institutional procurement channels in low- and middle-income country markets. |
| Backward Integration | Upstream control over peptide raw materials mitigates petrochemical feedstock price volatility exposure. |
| Pipeline Diversification | Bispecific constructs and antibody-drug conjugates offset biosimilar erosion in mature oncology categories. |
| Strategic Partnership | Group purchasing organization agreements disintermediate traditional wholesaler channels in hospital procurement. |
Research Approach
Independent corroboration across regulatory filings, clinical trial registries, and procurement databases underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue reconciliation across product type, therapy area, delivery mode, and end user segments anchored the analytical framework.
Comparable-period anchoring to historical biosimilar launch trajectories and innovator lifecycle patterns structured the forecast window across the analysis window. Segmentation dimensions modeled encompass product type, therapy area, delivery mode, end user category, and regional regulatory cluster. CAGRs were derived through patient volume expansion rates, pricing trajectory assumptions, and biosimilar penetration curves. Forecast inputs incorporated IRA Medicare price negotiation implementation timelines and EMA batch release complexity adjustments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosimilar substitution policy acceleration, manufacturing site inspection backlog resolution, and continuous bioprocessing adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Global Topical Antibiotics Market