
 Pruritus Therapeutics Market | 2026-2036
Pruritus Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pruritus Therapeutics Market Outlook
North American biopharmaceutical capacity is fragmenting across multiple therapeutic modalities as pruritus drug developers compete for manufacturing slots and payer attention. Pfizer Inc. leverages its established inflammation franchise to sustain commercial reach across dermatology and allergy segments. AbbVie Inc. anchors its position through R&D intensity in immunology, while Galderma S.A. specializes in topical delivery science for corticosteroid and calcineurin inhibitor portfolios. Bristol-Myers Squibb competes via systemic immunology assets that address refractory pruritus in hematology settings.
Pruritus therapeutics comprise pharmacological agents engineered to interrupt peripheral and central itch signaling pathways, with topical corticosteroids typically formulated at 0.05% to 0.25% potency tiers and calcineurin inhibitors requiring cold-chain stability for tacrolimus ointment variants. These agents serve to modulate neuroimmune crosstalk in conditions ranging atopic dermatitis to cholestatic pruritus. Corticosteroids dominate current prescription volumes yet face margin compression from generic saturation, while injectable biologics represent the fastest-expanding delivery mode as payers recalibrate reimbursement for IL-13 and IL-31 pathway inhibitors. Dermatology applications command the largest addressable patient pool, though palliative care segments offer premium pricing for refractory cases.
FDA review standards for novel pruritus mechanisms are tightening around long-term safety databases, while EMA's MDR requirements for combination drug-device products are extending development timelines for advanced topical systems. The EPA maintains residual oversight for steroid manufacturing effluent controls, particularly at API synthesis facilities. Stakeholders must monitor how payer prior authorization criteria evolve for biologic antipruritics versus conventional systemic immunosuppressants.
Market Dynamics
The FDA's evolving guidance on topical JAK inhibitors is compressing clinical development timelines while fragmenting biopharmaceutical manufacturing capacity across competing therapeutic modalities. Developers now face acute slot competition for contract manufacturing organization capacity as novel antipruritic agents advance through regulatory review.
Growth Catalysts
- Prior Authorization Reform:United States specialty dermatology networks are accelerating patient access pathways for IL-13 and IL-31 pathway inhibitors through streamlined reimbursement protocols.
- EMA MDR Pathway:The European Medical Device Regulation's clarity on combination drug-device products is enabling advanced topical system developers to lock in extended market exclusivity periods.
- Cold-Chain Infrastructure:Tacrolimus ointment stability requirements are driving investment in temperature-controlled distribution networks that expand rural and suburban prescription fulfillment.
Market Restraints
- API Synthesis Effluent Controls:EPA manufacturing discharge regulations at corticosteroid active pharmaceutical ingredient facilities are elevating compliance capital requirements for domestic production.
- Generic Corticosteroid Saturation:0.05% to 0.25% potency tier topical formulations face margin compression from multi-source generic competition that constrains branded pricing power.
- Long-Term Safety Database Mandates:FDA review standards for novel pruritus mechanisms now require extended post-marketing surveillance that extends time-to-market for first-in-class agents.
Strategic Opportunities
- Palliative Care Premium Pricing:Refractory pruritus management in hematology and cholestatic settings commands reimbursement multiples above dermatology applications due to limited therapeutic alternatives.
- Injectable Biologic Formulation:IL-31 receptor antagonist delivery mode expansion is capturing payer preference over conventional systemic immunosuppressants in prior authorization tiering.
- Peripheral-Itch Signaling Research:Neuroimmune crosstalk modulation targets outside established Th2 pathways offer white-space positioning for developers facing crowded JAK and biologic competitive sets.
Industry Challenges
- Specialty Dermatology Network Access:Concentrated prescriber pools in academic medical centers and large group practices limit field force efficiency for novel agent launches.
- Combination Product Technical Standards:EMA MDR compliance timelines for advanced topical delivery systems extend development cycles beyond conventional pharmaceutical pathways.
- Biologic Cold-Chain Integration:Injectable antipruritic distribution requires temperature monitoring infrastructure that conflicts with existing corticosteroid and calcineurin inhibitor logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pruritus Therapeutics Market |
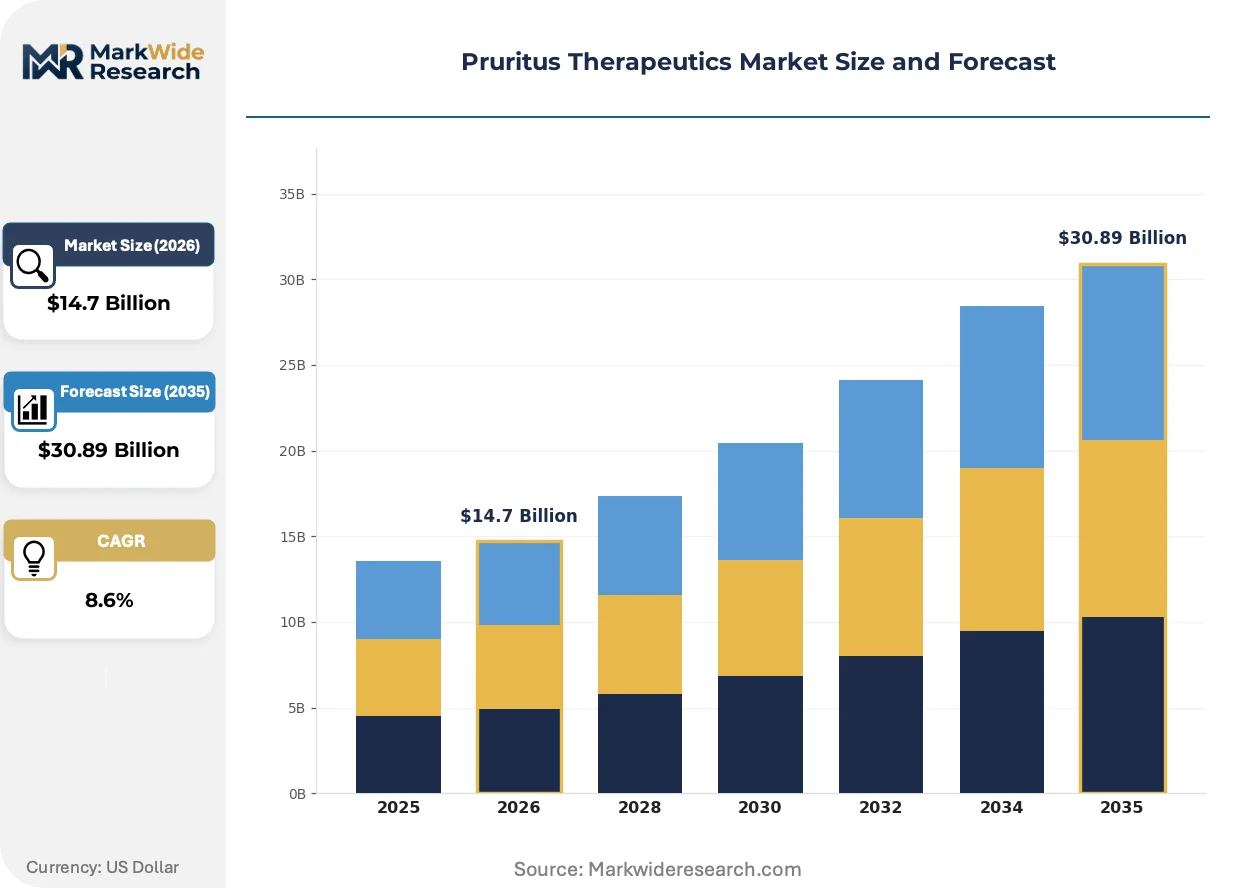
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Antihistamines, Moisturizers, Calcineurin Inhibitors Application: Dermatology, Palliative Care, Allergy Treatment, Hematology Delivery Mode: Topical, Systemic, Injectable, Oral End User: Hospitals, Dermatology Clinics, Homecare, Pharmacies |
| Companies Covered | Cara Therapeutics, GSK plc, AbbVie Inc., Bristol-Myers Squibb, Amgen Inc., Pfizer Inc., Astellas Pharma Inc., Galderma S.A., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pruritus Therapeutics Market Strategic Shifts
Topical delivery science is converging with systemic immunology to reshape how pruritus therapeutics reach peripheral and central itch signaling pathways. Developers are engineering hybrid modalities that bridge dermatology clinic formularies with specialty pharmacy distribution.
Transdermal JAK inhibitor formulations are hybridizing small-molecule penetration enhancement with targeted immune modulation. Dermatology clinics in the United States are adopting these systems at accelerating pace for chronic pruritus management. The technology is hybridizing topical corticosteroid convenience with biologic-like efficacy signals that compress conventional step-therapy protocols.
EMA MDR requirements for combination drug-device products are extending development timelines for advanced topical systems while clarifying exclusivity pathways. Manufacturers must now integrate device constituent validation with pharmaceutical quality systems before European market entry. Dermatology applications face the most pronounced timeline compression as developers reconfigure regulatory strategies around the MDR's Article 117 consultation mandates.
Specialty pharmacy channels are displacing traditional wholesale distribution for injectable biologic antipruritics as payers consolidate reimbursement administration. United States specialty dermatology networks now require prior authorization navigation through captive pharmacy relationships that extract value from administration fee structures. This concentration is most visible in metropolitan markets where integrated delivery networks control both prescribing and dispensing functions.
Pruritus Therapeutics Market Segmentation
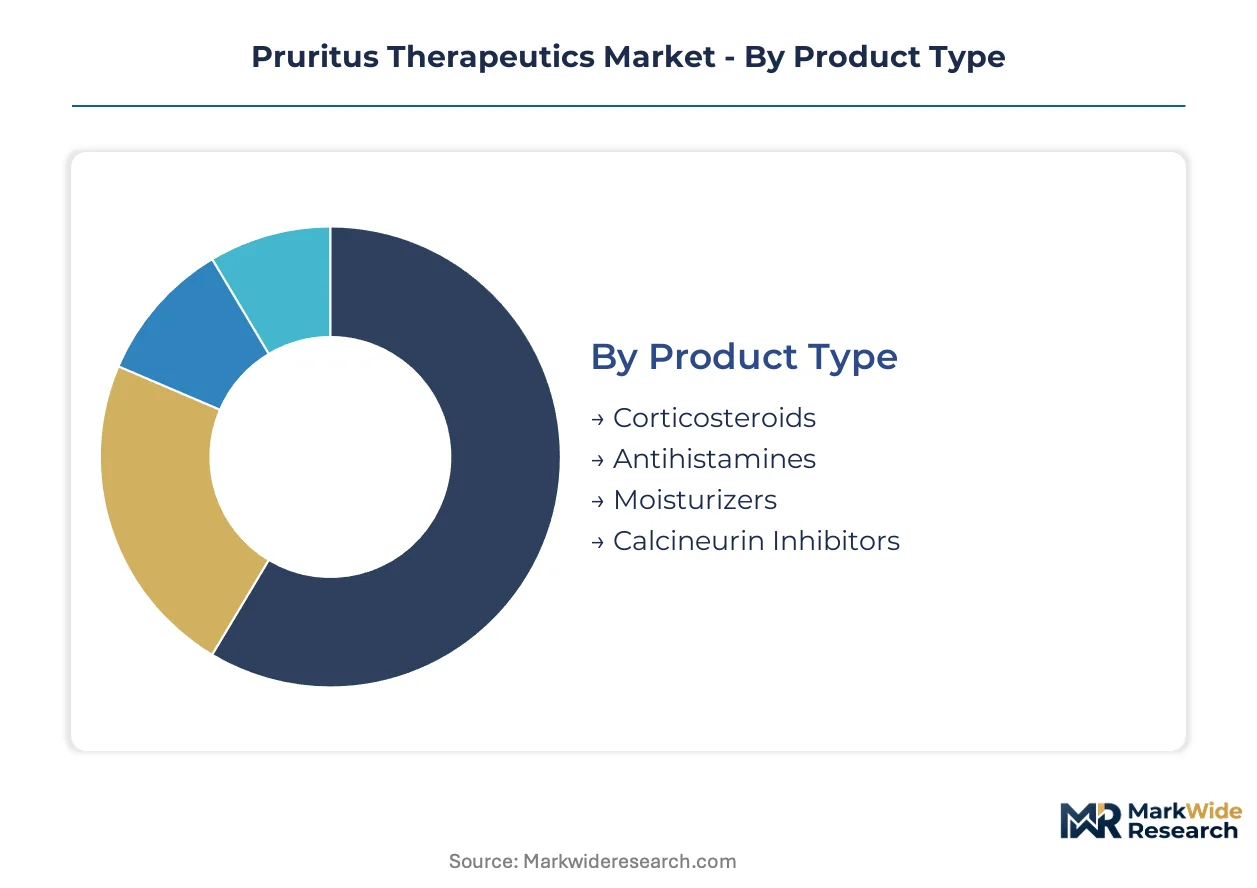
Pruritus therapeutics span formulations from 0.05% hydrocortisone creams to IL-31 receptor antagonists, each segment commanding distinct reimbursement pathways and prescriber relationships. Understanding how product types, applications, delivery modes, and end users intersect reveals where commercial investment concentrates versus where white-space opportunity remains.
Product Type:
Pruritus drug portfolios stratify across potency tiers, with legacy small-molecule franchises competing against biologic entrants for formulary placement.
- Corticosteroids:Formulated at 0.05% to 0.25% potency tiers, these agents modulate local inflammation through glucocorticoid receptor agonism. United States dermatology clinics prescribe these as first-line therapy for atopic pruritus, though generic saturation constrains branded pricing power.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus ointments require cold-chain stability and interrupt T-cell activation without steroid-related skin atrophy. Demand concentrates in pediatric and facial applications where corticosteroid avoidance drives prescriber preference.
- Antihistamines:First-generation H1 antagonists with sedating profiles address histamine-mediated itch in acute urticaria settings.
- Moisturizers:Emollient formulations restore barrier function in xerosis-associated pruritus, serving as adjunctive therapy across all severity tiers.
Established volume favors corticosteroids; emerging adoption favors calcineurin inhibitors.
Application:
Clinical settings determine pricing elasticity, with refractory cases in specialty settings commanding reimbursement multiples above routine dermatology.
- Dermatology:Atopic dermatitis, psoriasis, and lichen planus represent the largest addressable patient pools, with biologic step-therapy protocols now standard in United States academic medical centers.
- Palliative Care:Refractory pruritus in cholestatic and uremic settings offers premium pricing due to limited therapeutic alternatives and severity of patient burden.
- Hematology:Paraneoplastic itch and graft-versus-host disease drive demand for systemic immunomodulation in oncology and transplant centers.
- Allergy Treatment:Acute urticaria and allergic contact dermatitis respond to antihistamine and corticosteroid combinations in urgent care and primary care channels.
Reimbursement concentration favors dermatology; pricing premium favors palliative care.
Delivery Mode:
Route of administration dictates manufacturing complexity, cold-chain requirements, and prescriber administration settings.
- Topical:Creams, ointments, and lotions dominate prescription volumes through convenient self-administration, though bioavailability limitations restrict efficacy in systemic pruritus.
- Injectable:IL-13 and IL-31 pathway inhibitors require specialty pharmacy distribution and prior authorization navigation, capturing payer preference over conventional immunosuppressants in moderate-to-severe atopic dermatitis.
- Oral:Small-molecule JAK inhibitors and traditional antihistamines offer systemic exposure with patient-administered convenience.
- Systemic:Intravenous and subcutaneous immunosuppressants address refractory cases in hospital and infusion center settings.
Prescription volume favors topical; steepest expansion trajectory favors injectable.
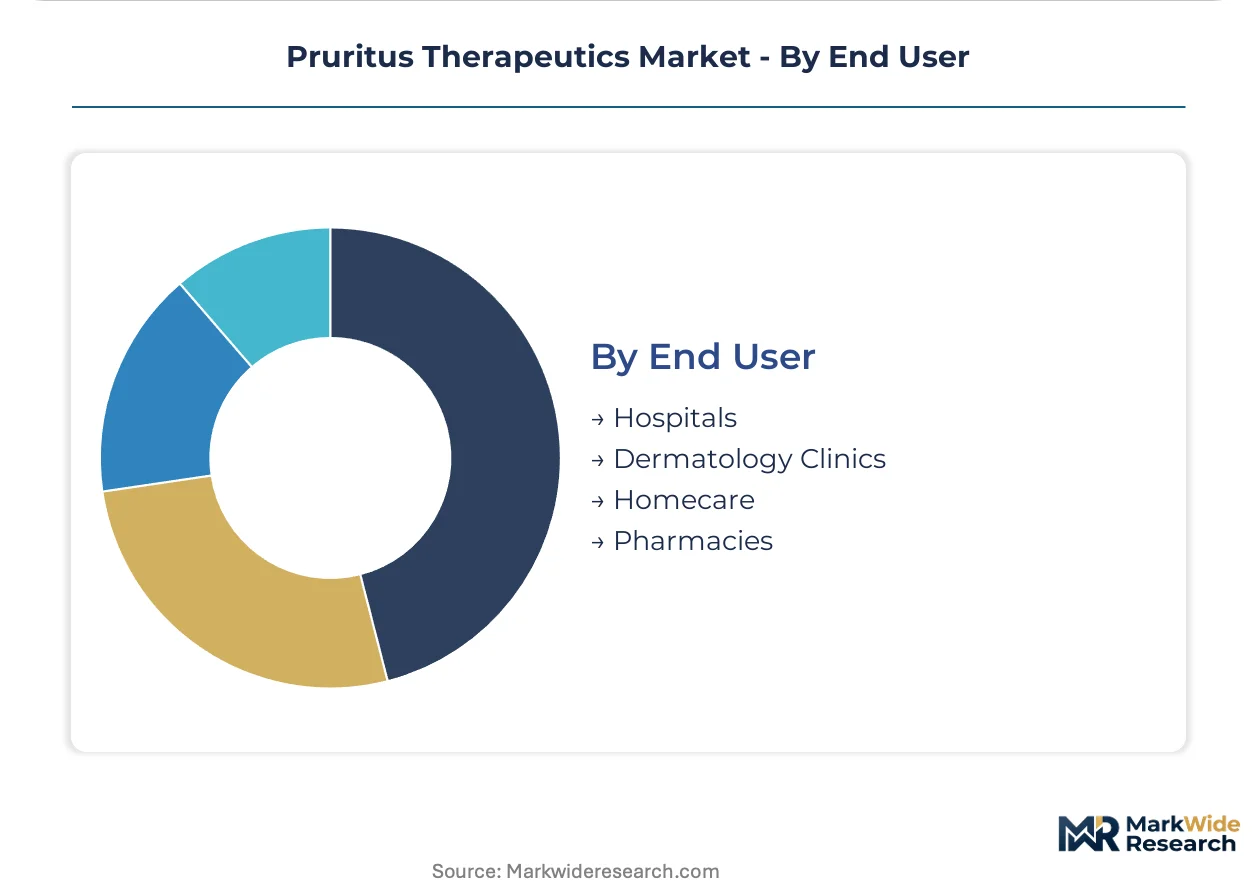
End User:
Care setting determines procurement authority, with integrated delivery networks consolidating purchasing decisions across multiple sites.
- Dermatology Clinics:United States specialty networks control formulary placement for novel agents, with prior authorization reform accelerating access to biologics in metropolitan markets.
- Hospitals:Inpatient and infusion center settings administer systemic and injectable therapies for acute exacerbations and refractory cases.
- Homecare:Self-administered topical and oral regimens dominate chronic maintenance therapy, supported by mail-order pharmacy fulfillment.
- Pharmacies:Retail and specialty channels dispense prescription antipruritics, with specialty pharmacies extracting value from biologic administration fee structures.
Patient volume favors homecare; revenue concentration favors dermatology clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on topical JAK inhibitors is compressing clinical timelines in the United States while EMA MDR requirements reshape European pathways. Manufacturing slot competition intensifies across North American biopharmaceutical capacity as novel antipruritic agents advance.
United States
Specialty dermatology networks in metropolitan markets drive demand concentration for IL-13 and IL-31 pathway inhibitors. Prior authorization reform through Medicare Advantage plans accelerates patient access to biologic antipruritics. The Boston-Cambridge cluster anchors translational research in neuroimmune crosstalk modulation, with multiple developers advancing peripheral itch signaling programs.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia prescribe calcineurin inhibitors at elevated rates for pediatric atopic dermatitis. EMA MDR Article 117 consultation mandates extend development timelines for combination drug-device topical systems. The Frankfurt-Rhine-Main pharmaceutical manufacturing corridor hosts API synthesis facilities subject to stringent effluent control standards.
Japan
PMDA review standards for novel pruritus mechanisms emphasize long-term safety databases for first-in-class agents. Domestic demand concentrates in Tokyo-Osaka metropolitan corridors where academic medical centers pilot biologic step-therapy protocols. The Kansai region maintains specialized cold-chain infrastructure for tacrolimus ointment distribution to suburban and rural pharmacies.
United Kingdom
NHS England's prior authorization criteria for biologic antipruritics favor IL-31 receptor antagonists over conventional systemic immunosuppressants. The London-Southeast corridor dominates specialist dermatology referrals for refractory pruritus in hematology settings. Manchester and Birmingham academic centers coordinate multicenter trials for cholestatic pruritus therapeutics.
Switzerland
Swissmedic maintains alignment with EMA MDR requirements while offering accelerated assessment pathways for orphan pruritus indications. Basel's pharmaceutical R&D cluster concentrates immunology-focused developers addressing graft-versus-host disease-associated itch. The Zurich-Geneva corridor supports niche manufacturing of high-potency corticosteroid formulations for export markets.
Pruritus Therapeutics Market Competitive Environment
Capability concentration sits with biologic developers possessing immunology platform expertise; scale advantage sits with established dermatology franchises with field force density. The market structure stratifies across three tiers: inflammation-focused pharmaceutical conglomerates, specialized dermatology companies, and emerging biotechs with novel mechanism assets. Competitive dynamics center on M&A activity targeting peripheral-itch signaling programs and strategic partnerships securing manufacturing capacity for injectable biologics.
Within the inflammation-franchise tier, Pfizer Inc. and AbbVie Inc. exemplify scale-driven positioning through established immunology portfolios. Galderma S.A. occupies a specialized position anchored in topical delivery science. These three entities represent distinct archetypes: the diversified pharmaceutical conglomerate leveraging cross-therapeutic reach, the immunology-intensive developer with R&D depth, and the dermatology-dedicated specialist with formulation expertise.
| Leading Market Players |
|---|
| Cara Therapeutics |
| GSK plc |
| AbbVie Inc. |
| Bristol-Myers Squibb |
| Amgen Inc. |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Galderma S.A. |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Frankfurt-Rhine-Main pharmaceutical manufacturing corridor freight costs are transmitting upstream API pricing pressure into downstream corticosteroid tier differentiation, while cold-chain logistics investments for calcineurin inhibitors are widening the spread between urban and rural prescription fulfillment economics.
Pricing Analysis
Geographic price spreads between United States metropolitan dermatology clinics and suburban retail pharmacies exceed threefold for IL-31 receptor antagonists due to specialty pharmacy administration fee structures. Pricing stratifies across biologic premium, branded topical standard, and generic corticosteroid economy tiers, with differentiation driven by FDA approval pathway and prescriber network exclusivity. Cost compression in the corticosteroid tier is intensifying because multi-source generic saturation erodes branded pricing power. Hospital infusion centers exhibit lowest price sensitivity for systemic immunosuppressants, while primary care channels remain most responsive to generic substitution incentives.
Supply Chain Analysis
Extended payment terms from United States specialty pharmacy networks are squeezing contract manufacturing organization cash cycles for injectable biologic fill-finish operations. API synthesis concentrates in India, China, and the United States, with corticosteroid manufacturing drawing from Chinese chemical intermediate feedstocks and Indian finishing capabilities. Tacrolimus ointment production rests on Taiwanese fermentation-derived starting materials and European formulation sites. Single-source vulnerability in JAK inhibitor active pharmaceutical ingredient supply creates exposure to regulatory inspection delays. Distribution runs through temperature-monitored specialty pharmacy channels for biologics, contrasting with wholesale distribution for topical corticosteroids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pruritus therapeutics are recovering from generic corticosteroid margin compression as biologic adoption cycles through prior authorization reform in United States Medicare Advantage plans.
For Market Incumbents: Pre-empt biosimilar entry by locking in exclusive specialty pharmacy distribution contracts for IL-13 pathway inhibitors before patent cliff exposure. Secure backward integration into corticosteroid API synthesis to defend margin position against Indian and Chinese generic API pricing pressure. Prioritize FDA breakthrough therapy designation pursuit for peripheral-itch signaling programs to extend exclusivity runway. For New Entrants and Emerging Players: Establish a beachhead in palliative care cholestatic pruritus where reimbursement multiples exceed dermatology benchmarks and prescriber concentration in academic medical centers reduces field force requirements. Target the United Kingdom NHS England prior authorization pathway for IL-31 receptor antagonists, where formulary placement favors novel mechanisms over conventional immunosuppressants. Deploy health economics outcomes research partnerships with Manchester and Birmingham academic centers to accelerate market access. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting legacy topical corticosteroid franchises to focus on systemic immunology assets. Long-term viability centers on developers possessing both biologic manufacturing capacity and neuroimmune crosstalk intellectual property. Watch FDA guidance evolution on long-term safety database requirements as the inflection indicator for first-in-class agent time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for novel peripheral-itch signaling mechanisms. |
| Manufacturing Scale-Up | Cold-chain capacity expansion in the Kansai region secures tacrolimus distribution to rural Japanese pharmacies. |
| Licensing Agreement | EMA MDR Article 117 consultation partnerships accelerate European market entry for combination drug-device topicals. |
| Pipeline Diversification | Neuroimmune crosstalk programs outside crowded Th2 pathways reduce competitive overlap with established biologics. |
| Reimbursement Strategy | Medicare Advantage prior authorization reform navigation captures payer preference for IL-31 receptor antagonists. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and payer access specialists provided ongoing calibration against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling triangulated with top-down pharmaceutical revenue estimates across the analysis window.
Scenario-bracketing framed demand projections across treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patent expiry schedules, biosimilar entry assumptions, and prior authorization reform velocity. Forecast inputs incorporated IL-13 and IL-31 pathway inhibitor adoption curves and corticosteroid generic substitution elasticities.
Sensitivities concentrate around FDA long-term safety database mandate evolution and EMA MDR compliance timeline extensions for combination products. Forecasts reflect documented assumptions on biologic cold-chain infrastructure investment and specialty pharmacy channel consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market