
 Clindamycin Phosphate Market | 2026-2036
Clindamycin Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Clindamycin Phosphate Market Outlook
The capital-intensity divergence between large-scale sterile injectable manufacturers and topical-focused formulators is bifurcating competitive dynamics in clindamycin phosphate supply. Pfizer Inc leverages its parenteral manufacturing infrastructure to sustain hospital-grade vial production at scale. Fresenius Kabi anchors critical care and hospital channel access through its generic injectables portfolio. Sun Pharmaceutical Industries differentiates via backward integration into active pharmaceutical ingredient supply and cost-efficient topical production.
Clindamycin phosphate is a water-soluble ester of clindamycin, typically formulated at concentrations of 1% in topical preparations and supplied as the equivalent of 150 mg per mL in injectable solutions, manufactured through controlled esterification of clindamycin base followed by salt formation and crystallization. It serves primarily as a lincosamide antibiotic for treating anaerobic infections and as a topical anti-acne agent with demonstrated efficacy against Cutibacterium acnes. Topical gel and foam formulations within the product type dimension lead volume consumption due to patient preference for non-greasy application, while injectable presentations command higher unit margins in hospital settings. The acne treatment application segment drives consistent demand cycles tied to adolescent demographics, whereas bacterial infections applications exhibit greater sensitivity to formulary positioning and stewardship protocols.
The FDA's antibiotic stewardship requirements and USP sterility standards for parenteral products shape manufacturing compliance burdens and facility investment thresholds for market participants. EMA's Good Manufacturing Practice inspections and REACH obligations for excipient sourcing constrain European supply chain configurations and vendor qualification timelines. India's CDSCO and PLI scheme for bulk drugs influence API cost structures and import substitution trajectories for global formulators. Stakeholders must monitor regulatory divergence between US and European compendial standards for topical versus injectable specifications when allocating R&D and capacity investments.
Market Dynamics
Antibiotic stewardship protocols are compressing prescribing volumes for systemic clindamycin phosphate while simultaneously elevating topical demand for acne management, creating divergent growth trajectories across formulation types.
Growth Catalysts
- FDA Antibiotic Stewardship Guidelines:Restrictions on broad-spectrum oral antibiotics redirect prescribers toward targeted topical therapies for Cutibacterium acnes infections.
- Adolescent Demographics:Persistent acne prevalence among populations aged 12-24 sustains baseline consumption of gel and foam formulations in dermatology channels.
- India's PLI Scheme for Bulk Drugs:Domestic API production incentives reduce input cost volatility for formulators sourcing clindamycin base.
Market Restraints
- Clindamycin Base Supply Concentration:API manufacturing clusters in China and India create geographic vulnerability to export restrictions or environmental compliance shutdowns.
- Macrolide Substitution:Azithromycin and erythromycin alternatives compete for anaerobic infection indications, particularly in cost-sensitive hospital formularies.
- USP Sterility Standards:Parenteral manufacturing compliance costs exclude smaller formulators from injectable market participation.
Strategic Opportunities
- Combination Topical Formulations:Fixed-dose pairing with benzoyl peroxide or tretinoin addresses resistance concerns and commands premium positioning.
- Telemedicine Dermatology Channels:Direct-to-patient prescription platforms bypass traditional pharmacy distribution for recurring acne therapy.
- CDSCO Streamlined Approvals:India's regulatory pathway acceleration enables faster market entry for novel topical delivery systems.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Aseptic processing technicians with USP compliance experience command premium wages and extended recruitment timelines.
- Esterification Process Validation:Controlled crystallization parameters require specialized analytical chemistry capabilities that constrain batch scale-up velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clindamycin Phosphate Market |
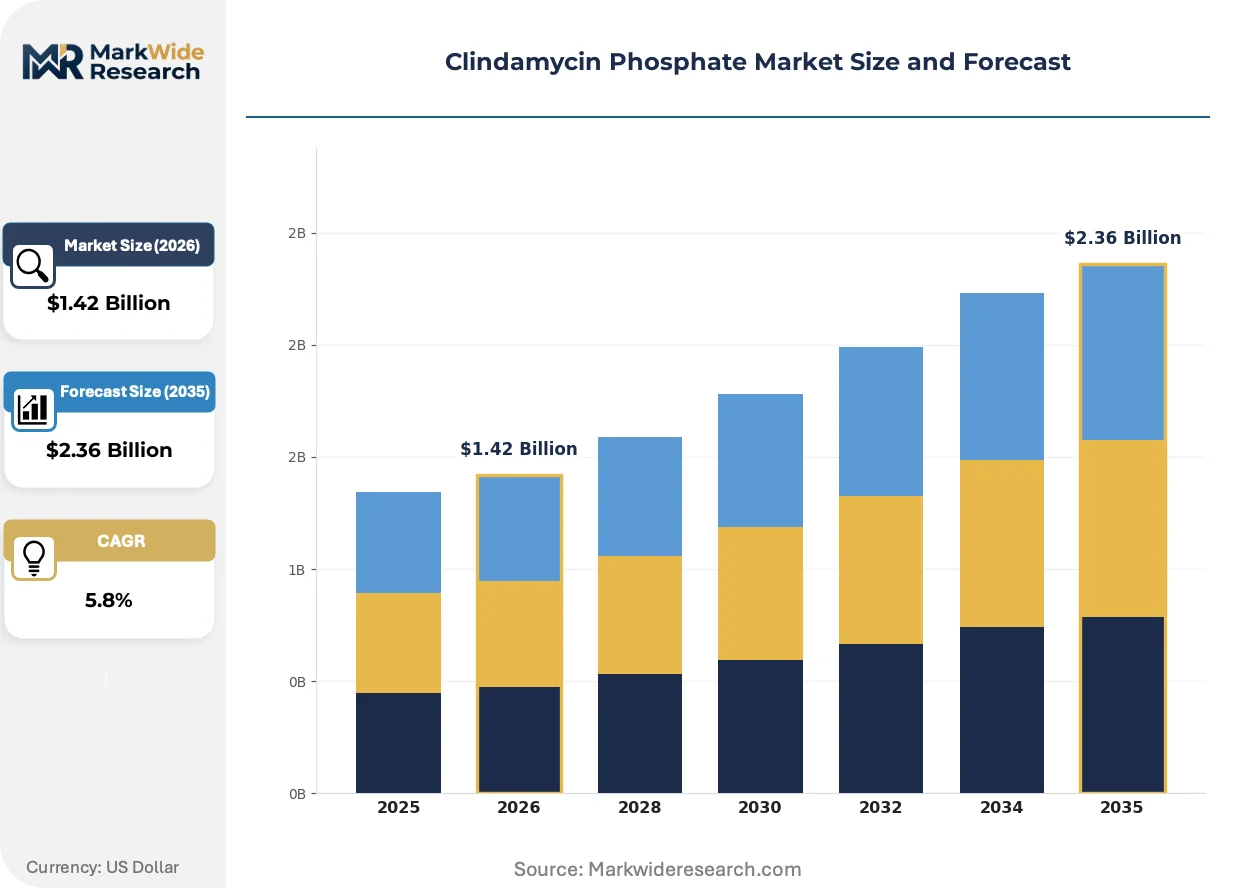
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Gel, Topical Foam, Lotion, Cream Application: Acne Treatment, Bacterial Infections, Skin Disorders, Inflammatory Conditions Formulation: Liquid, Semi-Solid, Solid, Gel-Based End User: Dermatology Clinics, Hospitals, Retail Pharmacies, Home Healthcare |
| Companies Covered | Fresenius Kabi, Sandoz, Pfizer Inc, Mylan (Viatris), Abbott Laboratories, Sanofi, Sun Pharmaceutical Industries, Aurobindo Pharma Limited, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clindamycin Phosphate Market Strategic Shifts
Formulation science and regulatory pressure are reshaping competitive positioning in clindamycin phosphate, with delivery mechanism innovation outpacing molecular modification.
Microsphere encapsulation technology is fragmenting the topical segment by enabling controlled-release clindamycin phosphate delivery. Galderma and generic dermatology specialists are adopting these systems to reduce irritation profiles and extend dosing intervals. The technology is fragmenting market share between conventional gel formulations and premium-priced encapsulated alternatives.
EMA's Good Manufacturing Practice inspection harmonization is compressing approval timelines for sterile injectable facilities across European member states. Manufacturers are consolidating batch testing protocols to satisfy centralized assessment procedures. Hospital procurement groups in Germany and France are prioritizing suppliers with EMA-certified sites over legacy national approvals.
Subscription-based acne therapy platforms are disintermediating traditional pharmacy fulfillment for chronic topical users. Ro and Hims channel models bundle clindamycin phosphate with virtual dermatologist consultations and automated refill logistics. This pattern concentrates in the United States where direct-to-consumer advertising regulations permit branded-generic promotion.
Clindamycin Phosphate Market Segmentation
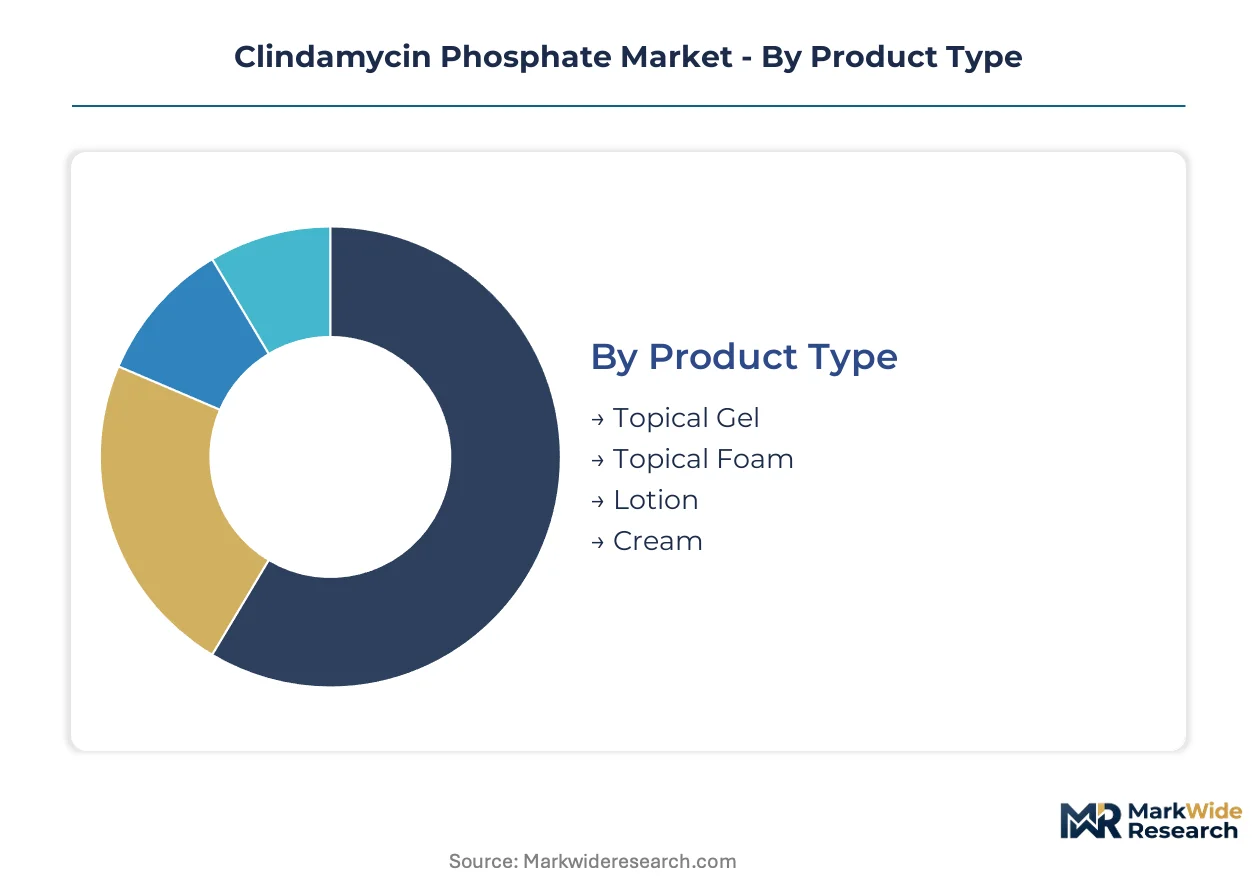
Segmentation in clindamycin phosphate reveals how formulation physics and prescribing site determine margin structure. Product viscosity and sterility requirements split manufacturing investment across radically different facility types.
Product Type:
Topical gel and foam formulations dominate domestic consumption in the United States and Western Europe, while injectable presentations flow through export channels to hospital systems in emerging markets.
- Topical Gel:Aqueous-based 1% clindamycin phosphate suspension with carbomer thickening agents. Dermatology clinics in Germany and France prescribe gel as first-line acne therapy, driven by patient preference for rapid absorption without residue.
- Topical Foam:Alcohol-free mousse delivery using propellant-free pump systems. United States telemedicine platforms are routing recurring prescriptions toward foam due to superior cosmetic elegance and compliance among adolescent demographics.
- Lotion:Emulsion-based vehicle with lower viscosity for trunk and back application. Retail pharmacy chains in India stock lotion for broader body surface coverage.
- Cream:Oil-in-water emulsion with occlusive properties for drier skin types. Home healthcare providers in Japan favor cream for elderly patients with xerosis comorbidities.
Topical Gel commands the established base. The steepest expansion runs through Topical Foam.
Application:
Cost tier stratification separates premium-positioned acne therapies from commoditized bacterial infection protocols in hospital formularies.
- Acne Treatment:Cutibacterium acnes-directed therapy with benzoyl peroxide combination options. United States direct-to-consumer platforms are capturing refill volume from traditional pharmacy channels.
- Bacterial Infections:Anaerobic coverage for intra-abdominal and soft tissue infections. Hospital antibiotic stewardship committees in the United Kingdom are restricting systemic use to culture-confirmed cases.
- Skin Disorders:Off-label rosacea and folliculitis management. Dermatology specialists in Spain prescribe for inflammatory papules beyond labeled indications.
- Inflammatory Conditions:Adjunctive therapy for hidradenitis suppurativa. Tertiary care centers in Italy are piloting topical protocols for early-stage disease.
Acne Treatment anchors volume concentration. Bacterial Infections faces the sharpest prescribing compression.
Formulation:
Manufacturing maturity separates legacy liquid injectables from emerging gel-based delivery innovations requiring specialized rheology control.
- Liquid:Parenteral solution at 150 mg per mL for IV or IM administration. Sterile manufacturing facilities in Ireland supply hospital systems across the European Union.
- Semi-Solid:Cream and ointment bases with petrolatum or fatty acid esters. Contract manufacturers in Gujarat, India produce for export to Middle Eastern markets.
- Solid:Lyophilized powder for reconstitution in critical care settings. Compounding pharmacies in the United States prepare patient-specific concentrations.
- Gel-Based:Hydrophilic polymer matrices enabling controlled-release kinetics. Microsphere encapsulation specialists in Switzerland are scaling novel topical delivery platforms.
Liquid formulations retain the production volume base. Gel-Based systems are climbing the fastest on innovation premiums.
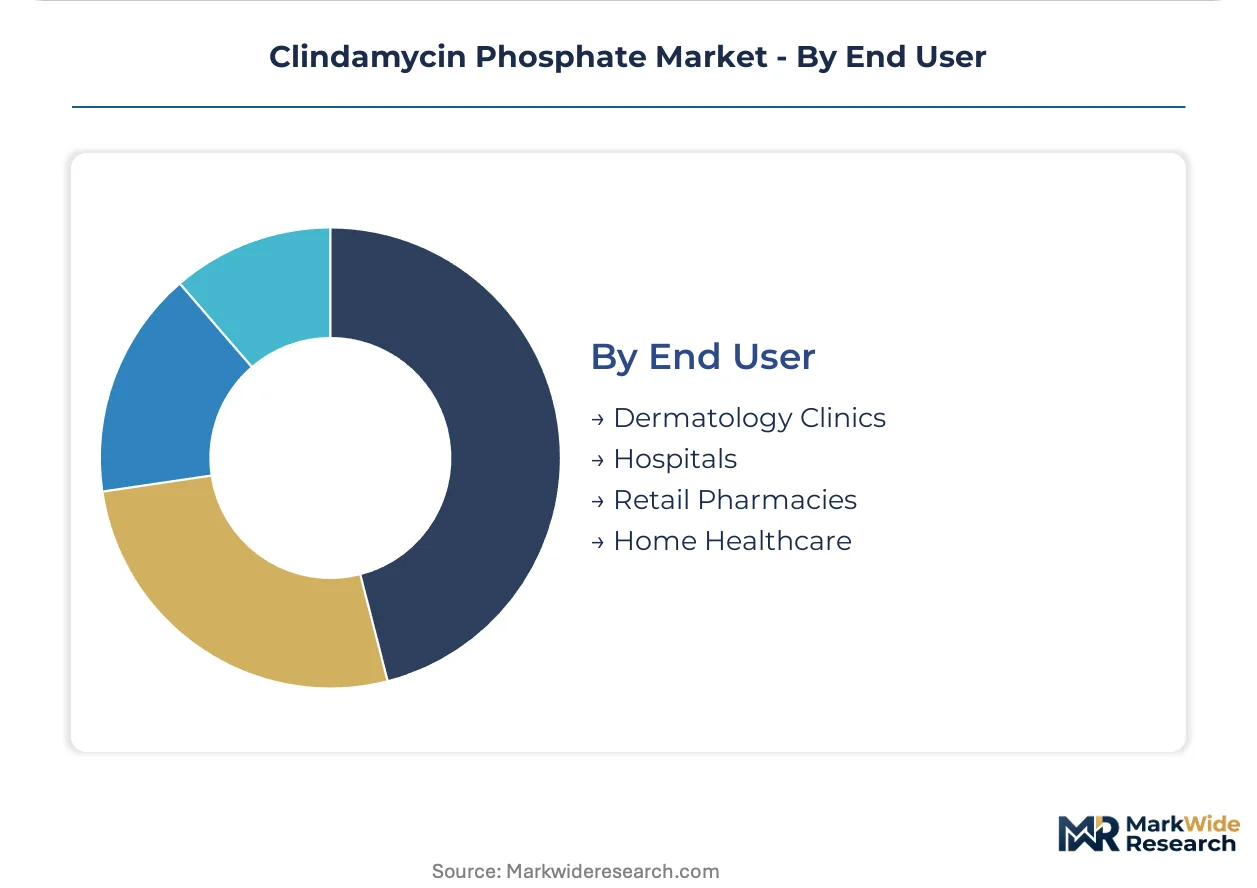
End User:
Customer type determines channel economics, with institutional procurement diverging sharply from direct-to-patient subscription models.
- Dermatology Clinics:Specialized prescribing with sample-driven trial initiation. Group practices in Florida and Texas are consolidating purchasing through GPO arrangements.
- Hospitals:Formulary-controlled systemic use with stewardship oversight. IDSA guideline adherence in Massachusetts and California academic centers restricts empiric clindamycin initiation.
- Retail Pharmacies:Generic substitution at the pharmacy counter. Chains in Ontario, Canada negotiate rebate structures with multiple source suppliers.
- Home Healthcare:Long-term topical therapy for chronic conditions. Visiting nurse organizations in Pennsylvania manage adherence through blister packaging.
Dermatology Clinics command the established base. Home Healthcare is gaining share fastest on aging-in-place trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology channels favor topical gel and foam formulations for acne management, while European hospital systems sustain injectable demand through anaerobic infection protocols. India's API manufacturing clusters supply raw material to formulators worldwide.
United States
Telemedicine platforms and direct-to-consumer subscription models are capturing refill volume for topical acne therapies. FDA antibiotic stewardship guidelines restrict systemic prescribing while redirecting demand toward targeted topical alternatives. Massachusetts and California academic medical centers enforce formulary controls that limit empiric clindamycin initiation.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia prescribe gel formulations as first-line acne therapy driven by patient preference for rapid absorption. EMA Good Manufacturing Practice inspections compress approval timelines for sterile injectable facilities. The Frankfurt-Rhine-Main pharmaceutical cluster consolidates batch testing protocols to satisfy centralized assessment procedures.
India
Domestic formulators leverage CDSCO streamlined approvals to accelerate market entry for novel topical delivery systems. The PLI scheme for bulk drugs reduces input cost volatility for clindamycin base production. Gujarat and Maharashtra manufacturing hubs supply API to export markets across Southeast Asia and the Middle East.
Japan
Home healthcare providers favor cream formulations for elderly patients with xerosis comorbidities requiring long-term topical therapy. METI and PMDA standards govern excipient sourcing and manufacturing compliance for dermatology products. The Kansai region around Osaka anchors domestic semi-solid formulation production for the aging population.
United Kingdom
Hospital antibiotic stewardship committees restrict systemic clindamycin use to culture-confirmed anaerobic infections. NHS England procurement frameworks prioritize suppliers with EMA-certified manufacturing sites. The Southeast England pharmaceutical corridor maintains sterile injectable capacity serving hospital systems across the European Union.
Clindamycin Phosphate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in clindamycin phosphate supply. Large-scale sterile injectable manufacturers deploy capital-intensive parenteral infrastructure to serve hospital formularies, while topical-focused formulators compete on formulation elegance and dermatology channel access. The competitive terrain splits between backward-integrated API producers and formulation specialists dependent on external raw material sourcing. Capacity expansion and portfolio diversification into combination therapies represent the dominant competitive moves.
Among the integrated pharmaceutical majors, Pfizer Inc and Fresenius Kabi exemplify the sterile manufacturing archetype with established hospital channel infrastructure. Sun Pharmaceutical Industries occupies a position within the backward-integrated tier, combining API production with cost-efficient topical manufacturing capabilities. These three anchors illustrate how competitive positioning diverges between parenteral scale economies and topical formulation agility.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Sandoz |
| Pfizer Inc |
| Mylan (Viatris) |
| Abbott Laboratories |
| Sanofi |
| Sun Pharmaceutical Industries |
| Aurobindo Pharma Limited |
| Glenmark Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Hospital-grade sterile manufacturing capacity utilization above 85 percent in Ireland and the United States creates fixed cost absorption advantages that protect price floors for injectable clindamycin phosphate while squeezing margin recovery for smaller topical formulators lacking comparable scale.
Pricing Analysis
After-sales service contracts for aseptic manufacturing technical support and batch release documentation drive lifetime value for hospital procurement relationships. The market operates on a contract-based long-term offtake model for parenteral products, with price differentiation resting on USP sterility certification tier and geographic delivery cost to hospital systems. Pricing pressure stems from macrolide substitution in cost-sensitive formularies, compressing unit margins for systemic presentations. Retail pharmacy chains exhibit highest price sensitivity through aggressive generic substitution, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites API shipment security for clindamycin base moving from Gujarat and Maharashtra manufacturing hubs to Southeast Asian formulators. Supply concentrates in India and China for active pharmaceutical ingredient production, with sterile fill-finish capacity clustering in Ireland and the United States for parenteral presentations. Raw material dependencies center on clindamycin base, specialized carbohydrate fermentation media, and USP-grade water for injection systems. Single-source vulnerability from environmental compliance shutdowns in Indian API clusters represents the dominant structural risk. Distribution runs through hospital procurement groups and group purchasing organizations for injectables, with telemedicine platforms and retail pharmacy chains handling topical fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based acne therapy platforms and automated refill logistics represent a service-attach opportunity expanding faster than conventional topical product sales, converting transactional prescriptions into recurring revenue streams with superior retention economics.
For Market Incumbents: Fortify parenteral manufacturing infrastructure through capacity maintenance in EMA-certified Irish facilities and USP-compliant United States sites to defend against emerging sterile injectable specialists from South Korea. Deepen backward integration into clindamycin base production through Gujarat or Maharashtra API partnerships to reduce exposure to Chinese export restriction volatility. Channel control through exclusive group purchasing organization contracts with Massachusetts and California academic medical centers protects hospital formulary positioning against azithromycin substitution.
For New Entrants and Emerging Players: Anchor in telemedicine dermatology channels where direct-to-patient subscription models bypass traditional pharmacy distribution and capture recurring refill volume with minimal customer acquisition cost. The most penetrable segment lies in topical foam formulations for adolescent demographics in United States direct-to-consumer platforms, where cosmetic elegance drives compliance premiums over generic gel alternatives. A white-space target exists in combination topical delivery systems pairing clindamycin phosphate with benzoyl peroxide microsphere encapsulation for resistance-sensitive prescribing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among topical-focused formulators with established telemedicine platform relationships and subscription logistics infrastructure, positioning these assets for premium multiples relative to commodity injectable manufacturers. Long-term viability over the projection horizon favors backward-integrated specialists with captive API supply and EMA-certified sterile capacity serving European hospital systems. The acquisition target archetype combines CDSCO-registered topical innovation pipelines with existing United States direct-to-consumer channel access. Watch FDA antibiotic stewardship guideline revisions as the critical inflection signal for topical demand acceleration versus systemic prescribing compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Microsphere Encapsulation Scale-Up | Galderma's controlled-release technology commands premium positioning in dermatology channels. |
| EMA Certification Consolidation | Frankfurt-Rhine-Main cluster batch testing satisfies centralized assessment procedures for EU hospital access. |
| Telemedicine Platform Partnership | Ro and Hims channel models bundle virtual consultation with automated refill logistics for retention. |
| CDSCO Streamlined Approval Pathway | India's regulatory acceleration enables faster market entry for novel topical delivery systems. |
| Combination Formulation Development | Fixed-dose benzoyl peroxide pairing addresses Cutibacterium acnes resistance concerns. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic prescribing leads, hospital formulary directors, sterile manufacturing facility managers, and API procurement specialists at Indian formulators. Secondary validation drew from FDA Orange Book filings, EMA GMP inspection records, CDSCO approval databases, and United States import trade data for clindamycin base. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to produce segmentation outputs.
Across the analysis window, the forecast framework applied treatment line stratification by acne severity, formulation physics by viscosity and release kinetics, and regional regulatory cluster differentiation between FDA, EMA, and CDSCO jurisdictions. CAGRs were derived from demographic-adjusted prevalence modeling for adolescent acne populations and stewardship-constrained hospital prescribing trends for anaerobic infections. Industry-specific inputs included CDSCO PLI scheme implementation timelines and EMA GMP inspection harmonization schedules.
Material uncertainties — API export restriction events, environmental compliance shutdowns in Indian manufacturing clusters, and FDA stewardship guideline revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable clindamycin base supply concentration and continued telemedicine platform regulatory permissiveness. Practitioners should keep alternative scenarios live as antibiotic resistance surveillance data and stewardship protocol stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Insulin Pens Market