
 Bioactive Protein and Peptides Market | 2026-2036
Bioactive Protein and Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Protein and Peptides Market Insights
Plant-based protein isolates is repositioning conventional dairy-derived formulations across functional food economics. Kerry Group leverages its extraction technology leadership to sustain premium positioning in European nutraceutical supply chains. Cargill Inc. anchors North American volume through its integrated pea protein processing infrastructure. Royal DSM competes on microbial fermentation platforms that differentiate its amino acid profiling capabilities.
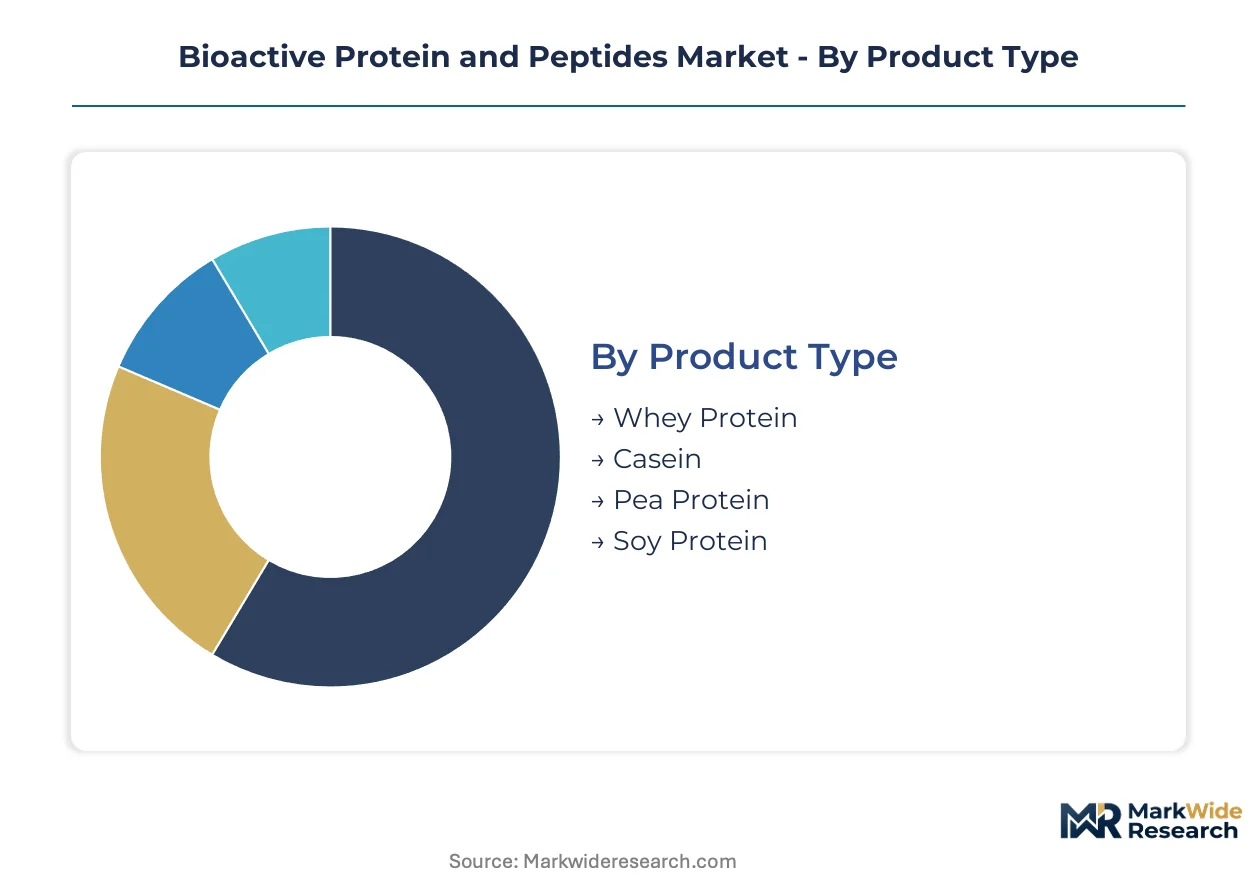
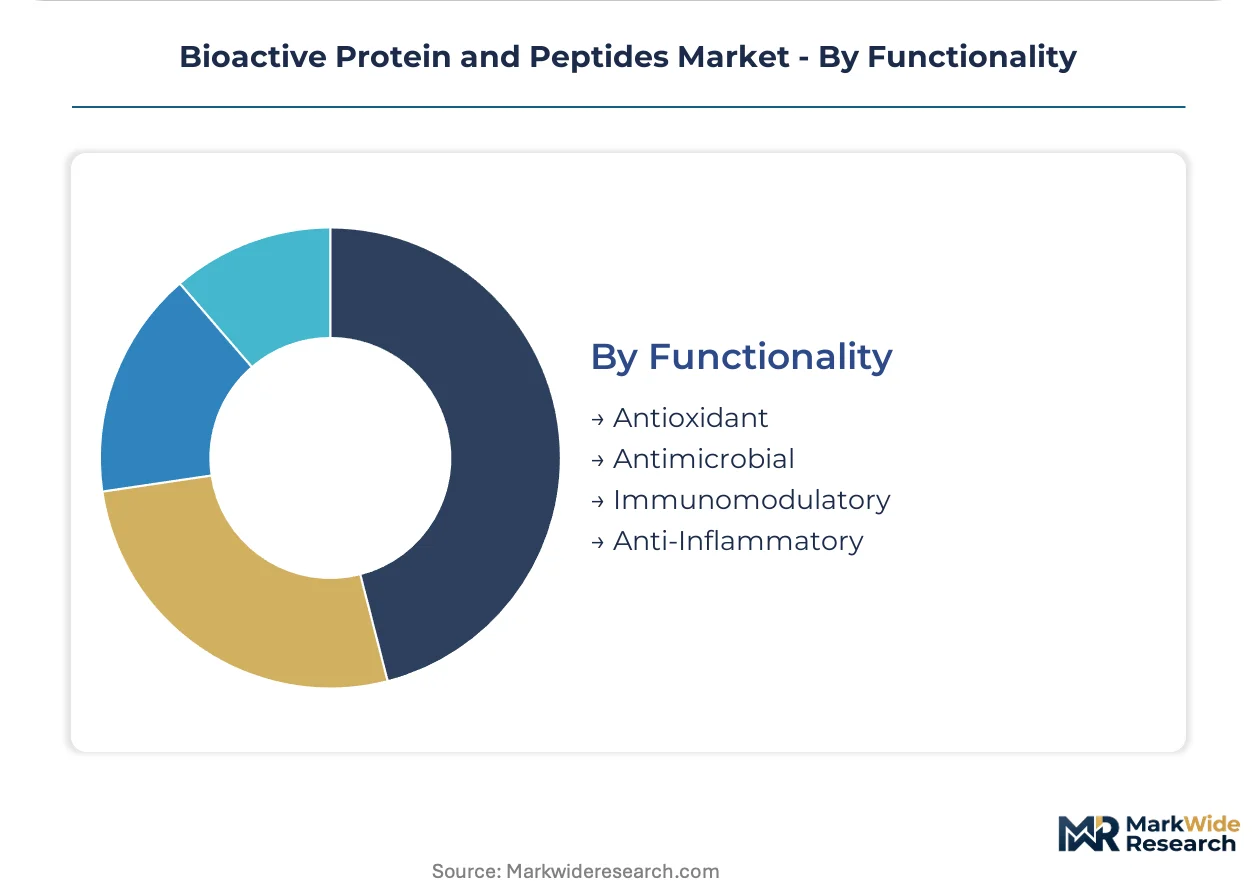
Bioactive proteins and peptides comprise oligomeric and polymeric amino acid chains with defined molecular weights, typically manufactured through enzymatic hydrolysis, microbial fermentation, or chromatographic purification to achieve specific biofunctional properties such as ACE-inhibitory activity or antioxidant capacity; these compounds serve primarily as physiologically active ingredients in formulated foods, dietary supplements, and dermatological preparations. Whey protein retains the largest share of the product type landscape due to its established sports nutrition infrastructure, while pea protein captures the fastest trajectory as beverage brands reformulate for allergen-free positioning. The functionality dimension concentrates margin pools in immunomodulatory and antimicrobial segments where clinical validation commands formulation premiums.
The FDA GRAS notification pathway and EFSA health claims framework jointly govern market access for novel bioactive peptide entrants, with EFSA's substantiation requirements demanding human intervention data that extends development timelines. China's NMPA and SAMR enforce GB standards on imported protein isolates that constrain foreign supplier participation without domestic testing partnerships. Stakeholders must monitor evolving peptide-specific regulatory categories as jurisdictions diverge on whether to classify certain hydrolysates as food ingredients or novel therapeutic agents.
Market Dynamics
Precision fermentation infrastructure in China's Yangtze River Delta is compressing cost curves for bioactive peptide production, forcing legacy enzymatic hydrolysis operations to rationalize capacity or relocate toward feedstock-advantaged geographies.
Growth Catalysts
- EU Novel Food Regulation:Streamlined approval pathways for protein hydrolysates with documented bioactivity are accelerating European functional food launches. Manufacturers leverage EFSA health claim frameworks to command formulation premiums.
- Sports nutrition infrastructure:Established whey protein processing networks in the US and Germany enable rapid scale-up of peptide-enriched recovery formulations. Athlete endorsement pipelines compress commercialization timelines.
- Enzymatic hydrolysis optimization:Advances in substrate specificity and reaction control are yielding peptide fractions with targeted ACE-inhibitory or antioxidant properties. Food technologists integrate these into clean-label positioning strategies.
Market Restraints
- Pea protein input volatility:North American pulse crop yields fluctuate with prairie drought cycles, transmitting price instability to isolate producers. Contracting strategies struggle to hedge multi-year exposure.
- EFSA substantiation requirements:Human intervention study mandates extend development timelines for novel bioactive entrants. Smaller ingredient suppliers lack capital reserves to complete full clinical validation programs.
- Dairy-derived formulation substitution:Plant-based isolates capture reformulation mandates from allergen-sensitive beverage brands. Whey protein retains share in sports nutrition but loses ground in mainstream functional foods.
Strategic Opportunities
- Indian nutraceutical channel expansion:FSSAI regulatory harmonization with Codex standards reduces import friction for validated peptide ingredients. Domestic contract manufacturing capacity remains underutilized relative to projected demand.
- Precision fermentation-microbial convergence:Integration of synthetic biology platforms with continuous bioprocessing enables novel amino acid sequences unattainable through enzymatic hydrolysis. Early movers capture IP positions in immunomodulatory fractions.
- Direct-to-practitioner distribution:Functional medicine clinicians prescribe peptide-enriched protocols for metabolic health interventions. This channel bypasses conventional retail margin structures.
Industry Challenges
- Peptide characterization expertise scarcity:Mass spectrometry and bioinformatics proficiency required for structure-function documentation remains concentrated in academic and CRO settings. Commercial labs face recruitment bottlenecks.
- Dual-use regulatory ambiguity:Jurisdictions diverge on whether certain hydrolysates qualify as food ingredients or novel therapeutic agents. SAMR and FDA notification pathways demand distinct technical dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Protein and Peptides Market |
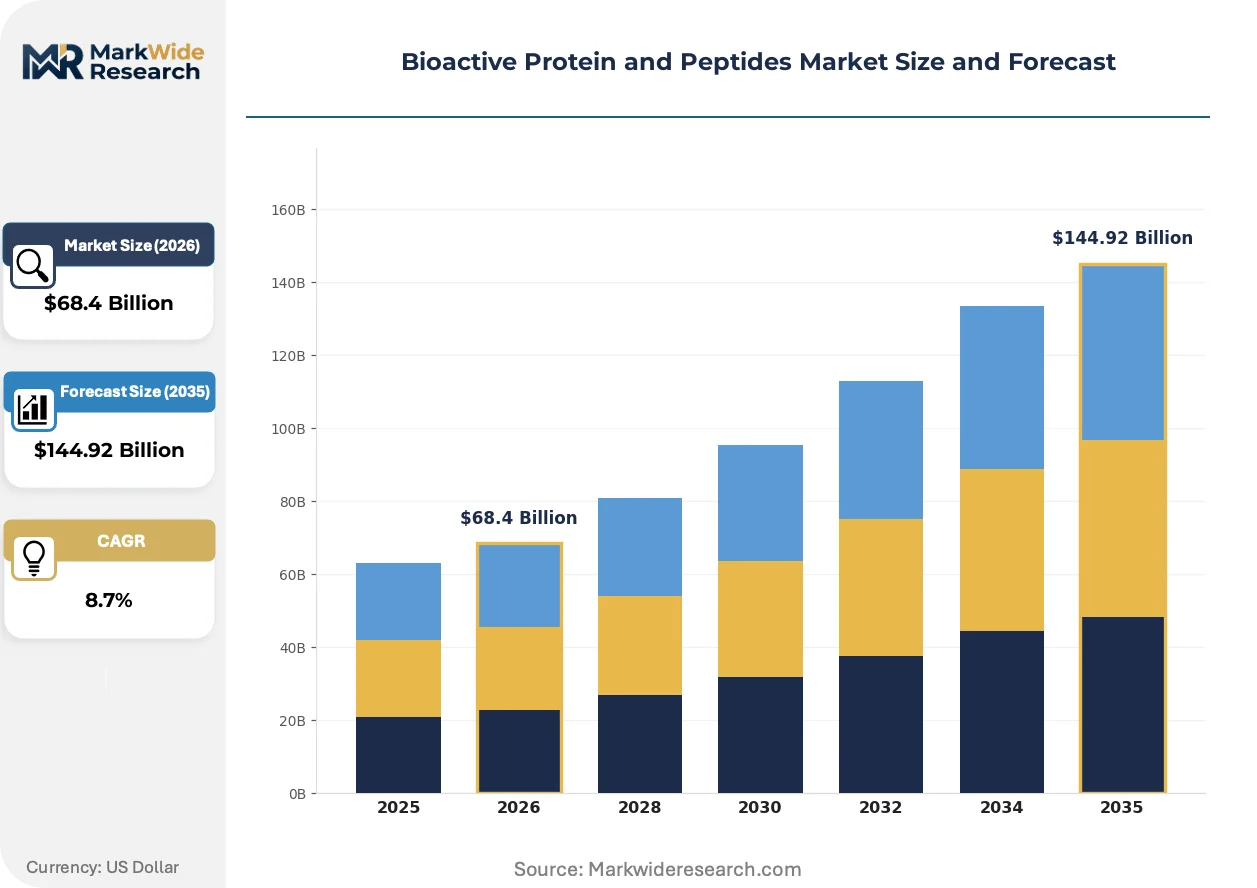
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Pea Protein, Soy Protein End Use: Food & Beverages, Nutraceuticals, Personal Care, Animal Feed Source: Animal-Based, Plant-Based, Microbial, Synthetic Functionality: Antioxidant, Antimicrobial, Immunomodulatory, Anti-Inflammatory |
| Companies Covered | Archer Daniels Midland Company (ADM), Kerry Group, Cargill Inc., Royal DSM, Bunge Ltd., Fonterra Co-operative Group Ltd., Omega Protein Corporation, E.I. Du Pont De Nemours and Company, PolyPeptide Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Protein and Peptides Market Trends and Innovations
Biomanufacturing scale-up and regulatory science advances are converging to redefine competitive advantage in bioactive peptide supply. Incumbents must reconfigure technical capabilities or cede margin to fermentation-native entrants.
Precision fermentation platforms producing bioactive peptides from engineered microbial chassis are overtaking traditional dairy and plant extraction methods in cost-efficiency at commercial scale. Sports nutrition and dermatological formulation houses in Germany and South Korea are adopting these inputs for batch-to-batch consistency. The technology is compressing capital requirements for novel peptide market entry while fragmenting incumbent supplier concentration.
EFSA's evolving health claims substantiation framework now explicitly recognizes peptide-specific bioactivity markers in cardiovascular and immune function categories. This regulatory clarity enables proactive dossier preparation by ingredient developers rather than reactive compliance. European functional food manufacturers are restructuring R&D timelines to align with EFSA opinion schedules, prioritizing peptides with existing safety documentation.
Clean-label procurement mandates from multinational beverage brands are eliminating synthetic preservative carriers in peptide isolate formulations. Suppliers must demonstrate all-natural stabilization systems or forfeit preferred vendor status. This behavioral shift is most visible in German and Dutch contract manufacturing agreements, where formulation transparency clauses now specify excipient disclosure thresholds.
Bioactive Protein and Peptides Market Segmentation
Bioactive protein and peptide suppliers configure production assets around distinct buyer requirements across product chemistry, application intensity, and regulatory exposure. Segmentation discipline separates commodity volume plays from premium formulation partnerships.
Product Type:
Buyers differentiate by protein digestibility scores, allergen profiles, and sports nutrition brand equity rather than amino acid content alone.
- Whey Protein:Rapid-absorption concentrate and isolate fractions dominate sports nutrition formulations. Demand concentrates in German and US athlete recovery products where established processing infrastructure enables rapid scale-up of peptide-enriched variants.
- Pea Protein:Hypoallergenic isolate with neutral flavor profiles captures beverage reformulation mandates. North American pulse processors in Saskatchewan and Manitoba face yield volatility from prairie drought cycles that transmit price instability to contract manufacturers.
- Casein:Slow-release micellar structures sustain overnight recovery positioning in clinical nutrition.
- Soy Protein:Cost-competitive isolate retains share in Asian functional foods despite Western allergen concerns.
Volume sits with whey protein; growth tilts toward pea protein.
End Use:
Application intensity varies by clinical validation requirements and margin capture potential across consumer touchpoints.
- Food & Beverages:Clean-label beverage brands in Germany and the Netherlands specify excipient disclosure thresholds that eliminate synthetic preservative carriers. Suppliers must demonstrate all-natural stabilization systems or forfeit preferred vendor status.
- Nutraceuticals:Direct-to-practitioner distribution channels bypass conventional retail margin structures. Functional medicine clinicians in South Korea and Germany prescribe peptide-enriched protocols for metabolic health interventions.
- Personal Care:Dermatological formulation houses adopt precision fermentation inputs for batch-to-batch consistency in topical applications.
- Animal Feed:Regulatory arbitrage between feed-grade and food-grade specifications constrains supplier participation in premium pet nutrition.
Margin concentrates in nutraceuticals; reformulation activity accelerates fastest in food and beverages.
Source:
Supply chain provenance determines carbon accounting transparency and novel food regulatory pathway complexity.
- Plant-Based:Pea and soy isolates reposition conventional dairy-derived formulations across functional food economics. Procurement teams prioritize water-stress indices and deforestation-free certification in supplier scorecards.
- Animal-Based:Dairy and egg-derived fractions retain infrastructure advantages in sports nutrition. Whey processing networks in the US and Germany enable rapid commercialization of peptide-enriched recovery formulations.
- Microbial:Precision fermentation platforms from engineered chassis overtake extraction methods in cost-efficiency at commercial scale. China's Yangtze River Delta infrastructure compresses production cost curves.
- Synthetic:Solid-phase peptide synthesis serves research-scale and orphan therapeutic applications with limited food-grade penetration.
Capital deployment favors microbial platforms; incumbent volume remains with animal-based sources.
Functionality:
Bioactivity specificity commands formulation premiums where clinical validation documentation exists.
- Immunomodulatory:Peptide fractions with documented cytokine modulation activity capture premium positioning in European functional foods. EFSA's evolving health claims framework now explicitly recognizes peptide-specific bioactivity markers in immune function categories.
- Antimicrobial:Natural preservation systems replace synthetic additives in clean-label meat and dairy applications. Suppliers leverage bacteriocin-producing fermentation strains to meet beverage brand procurement mandates.
- Antioxidant:ACE-inhibitory and free radical scavenging properties target cardiovascular positioning in Asian nutraceutical channels.
- Anti-Inflammatory:C-reactive protein modulation claims require human intervention data that extends development timelines for novel entrants.
Commercial traction clusters around immunomodulatory and antimicrobial segments; anti-inflammatory applications face substantiation bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's precision fermentation corridor around Shanghai and Tianjin concentrates the fastest capacity expansion for bioactive peptide manufacturing. Germany's functional food sector drives European immunomodulatory peptide adoption through EFSA-aligned health claim substantiation. The United States maintains dominant sports nutrition infrastructure for whey protein peptide scale-up.
China
Yangtze River Delta biomanufacturing clusters compress production cost curves for microbial-derived bioactive peptides. NMPA and SAMR enforce GB standards on imported protein isolates that constrain foreign supplier participation without domestic testing partnerships. Shanghai-based precision fermentation facilities are overtaking traditional enzymatic hydrolysis operations in cost-efficiency at commercial scale.
Germany
Functional food manufacturers accelerate adoption of immunomodulatory peptide isolates for cardiovascular and immune positioning. EFSA health claims frameworks demand human intervention data that extends development timelines but commands formulation premiums. Bavaria and North Rhine-Westphalia host established whey protein processing networks enabling rapid commercialization of peptide-enriched recovery formulations.
United States
Sports nutrition brands drive demand for rapid-absorption whey protein concentrate and isolate fractions in athlete recovery products. FDA GRAS notification pathways govern market access for novel bioactive peptide entrants with distinct technical dossier requirements. Midwest dairy processing infrastructure enables rapid scale-up of peptide-enriched formulations through established supplier relationships.
India
Nutraceutical channel expansion accelerates as FSSAI regulatory harmonization with Codex standards reduces import friction for validated peptide ingredients. Domestic contract manufacturing capacity remains underutilized relative to projected demand for metabolic health interventions. Maharashtra and Gujarat-based formulation houses are restructuring procurement to capture precision fermentation inputs.
South Korea
Dermatological formulation houses adopt precision fermentation inputs for batch-to-batch consistency in topical bioactive peptide applications. MFDS peptide-specific regulatory categories diverge from food ingredient classifications for certain hydrolysates with therapeutic positioning. Seoul Capital Area manufacturers integrate synthetic biology platforms with continuous bioprocessing for novel amino acid sequences.
Bioactive Protein and Peptides Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dairy-derived incumbents defending sports nutrition positions while fermentation-native entrants capture functional food reformulation mandates. The vendor base organizes around three strategic archetypes: extraction technology leaders sustaining premium European nutraceutical supply chain positions, integrated agricultural processors anchoring North American volume through captive feedstock infrastructure, and microbial fermentation platform operators differentiating on amino acid profiling capabilities. Consolidation pressure concentrates among mid-cap enzymatic hydrolysis operations facing cost compression from precision fermentation scale-up. Dominant competitive moves include backward integration into pulse crop contracting and technology licensing partnerships for novel peptide characterization.
Within the extraction technology tier, Kerry Group represents branded specialist positioning in European nutraceutical channels. Cargill Inc. exemplifies integrated agricultural processing scale in North American pea protein infrastructure. Royal DSM occupies a position within microbial fermentation platform differentiation. These three entities anchor distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| Kerry Group |
| Cargill Inc. |
| Royal DSM |
| Bunge Ltd. |
| Fonterra Co-operative Group Ltd. |
| Omega Protein Corporation |
| E.I. Du Pont De Nemours and Company |
| PolyPeptide Group |
| Others |
Pricing and Supply Chain Analysis
Clean-label procurement mandates from multinational beverage brands in Germany and the Netherlands are forcing peptide isolate suppliers to reformulate with all-natural stabilization systems, compressing margins for legacy operations while rewarding fermentation-native entrants with compliant process architectures.
Pricing Analysis
Volume concentrates in commodity whey protein isolates where scale economics dominate, while margin pools accrue to immunomodulatory peptide fractions with EFSA-aligned health claim documentation. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade isolates with human intervention data from feed-grade alternatives. Pricing pressure stems from precision fermentation scale-up in China's Yangtze River Delta, which is undercutting enzymatic hydrolysis operations on unit economics. Contract manufacturers exhibit highest price sensitivity due to thin conversion margins, whereas direct-to-practitioner nutraceutical channels absorb premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from European functional food manufacturers mandate qualification of both microbial fermentation and plant-extraction suppliers, fragmenting procurement leverage across incompatible process platforms. Supply concentrates in China for precision fermentation infrastructure, Germany for whey protein processing networks, and Canada for pea protein isolate production. Raw material dependencies include prairie pulse crops, dairy whey permeate, and engineered microbial chassis strains. Single-source vulnerability runs through China's NMPA-certified fermentation capacity, which dominates novel peptide commercialization timelines. Distribution runs through integrated ingredient suppliers with captive extraction infrastructure and contract manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
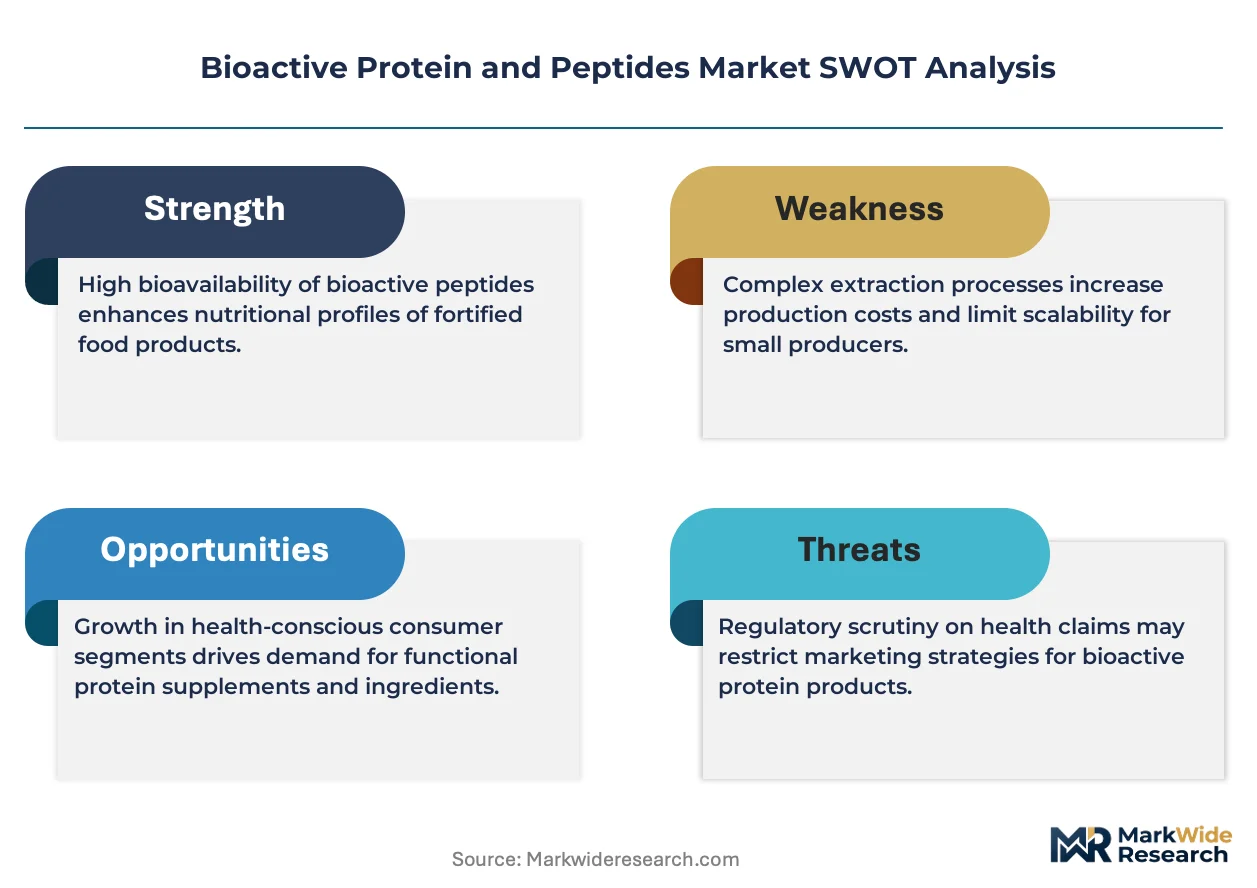
EFSA's human intervention study mandates for health claim substantiation erect a cost-of-compliance moat that advantages capitalized incumbents while screening out underfunded peptide developers lacking clinical validation reserves.
For Market Incumbents: Deploy backward integration into pulse crop contracting to secure feedstock cost stability against prairie drought volatility. Incumbents must accelerate precision fermentation platform licensing to neutralize cost compression from Yangtze River Delta entrants, while defending sports nutrition share through athlete endorsement pipeline control. Kerry Group and Cargill Inc. anchor positions through extraction technology leadership and integrated agricultural processing respectively. For New Entrants and Emerging Players: Direct-to-practitioner distribution channels offer the most penetrable entry vector, bypassing conventional retail margin structures that favor established supplier relationships. New entrants should target India's underutilized contract manufacturing capacity as FSSAI regulatory harmonization reduces import friction, while leveraging precision fermentation IP positions in immunomodulatory fractions to differentiate from commodity isolates. For Investors and Strategic Acquirers: The window for entry favors fermentation-native platform operators with synthetic biology capabilities and existing EFSA safety documentation. Long-term viability hinges on acquiring technical talent in mass spectrometry and bioinformatics for structure-function characterization, as peptide expertise scarcity concentrates in academic and CRO settings. Watch for SAMR peptide-specific regulatory category clarifications as the signal for therapeutic-positioning entrants to accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Shanghai and Tianjin facilities compress cost curves below enzymatic hydrolysis economics. |
| EFSA Health Claim Dossier Investment | Human intervention data commands formulation premiums in European functional foods. |
| Backward Integration into Pulse Contracting | Saskatchewan and Manitoba crop agreements hedge prairie drought price volatility. |
| Direct-to-Practitioner Channel Development | South Korean and German functional medicine clinicians bypass retail margin structures. |
| Peptide Characterization Lab Acquisition | Mass spectrometry proficiency concentration in academic settings creates recruitment bottlenecks. |
Research Methodology
Trade databases, regulatory filing repositories, and ingredient supplier financial disclosures formed the secondary backbone, cross-referenced with primary interviews involving peptide characterization scientists, functional food R&D directors, EFSA regulatory consultants, and contract manufacturing procurement leads. Bottom-up and top-down triangulation validated volume estimates across enzymatic hydrolysis, microbial fermentation, and chromatographic purification platforms.
Bottom-up modeling anchored forecasts to individual production facility capacities and utilization rates, while top-down constraints drew from end-use demand aggregation across sports nutrition, clinical nutrition, and dermatological formulation segments. Segmentation dimensions included product chemistry, application intensity, regulatory exposure tier, and source provenance. CAGRs derived from fitted growth curves incorporating precision fermentation adoption rates and EFSA opinion schedule impacts.
The model holds under stable EFSA substantiation timelines and NMPA GB standard enforcement; deviation in regulatory category reclassification or trade restriction escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Chemotherapy Drugs Market