
 Female Infertility Drugs Market | 2026-2036
Female Infertility Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Female Infertility Drugs Market Foresight
Recombinant follicle-stimulating hormone is expanding its share over urinary-derived gonadotropins as purity standards tighten and batch consistency improves. Merck & Co., Inc. leverages its position in recombinant hormone manufacturing to sustain premium positioning across fertility clinic networks. Ferring B.V. anchors its portfolio in peptide-based therapies with specialized cold-chain distribution capabilities. Bayer AG competes through broad gynecological portfolios that extend into adjacent reproductive health segments.
Female infertility drugs comprise pharmacological agents designed to modulate ovarian function, induce ovulation, or correct hormonal imbalances underlying conception failure. These compounds typically target hypothalamic-pituitary-ovarian axis signaling through synthetic estrogen modulators, purified gonadotropins, or aromatase inhibitors administered via calibrated dosing regimens. Gonadotropins command the largest revenue pool due to complex biomanufacturing requirements and chronic multi-cycle administration patterns. Oral clomiphene citrate retains dominant volume share in first-line ovulatory disorder treatment. Subcutaneous injection formats are gaining fastest as patient self-administration protocols reduce clinic dependency and improve cycle timing flexibility.
The FDA oversees New Drug Applications and Risk Evaluation and Mitigation Strategies for fertility therapeutics, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across European member states. The FDA's 505(b)(2) pathway enables abbreviated development for reformulated hormonal products, compressing time-to-market for improved delivery systems. Stakeholders must monitor biosimilar entry timelines for reference gonadotropins and evolving reimbursement criteria from public and private payers that will determine accessible patient volumes and brand switching dynamics.
Market Dynamics
The FDA's 505(b)(2) pathway is compressing development timelines for reformulated hormonal products, while fertility clinic consolidation concentrates purchasing power among fewer institutional buyers. Recombinant manufacturing investments are reshaping competitive positioning as purity standards displace urinary-derived alternatives.
Growth Catalysts
- Accelerated FDA Review Pathways:The FDA's 505(b)(2) regulatory route enables abbreviated clinical development for improved gonadotropin delivery systems, shortening time-to-market for subcutaneous injection formats.
- Fertility Clinic Network Expansion:Specialized reproductive health centers are standardizing treatment protocols across the United States, driving prescription volumes for ovulation-inducing agents through centralized procurement.
- Recombinant Biomanufacturing Scale-up:Single-use bioreactor technology is expanding production capacity for follicle-stimulating hormone, resolving batch consistency constraints that previously limited supply security.
Market Restraints
- Gonadotropin Input Cost Volatility:Purified hormone raw materials face price instability due to concentrated biomanufacturing inputs from Chinese contract manufacturing organizations.
- Cold-Chain Distribution Concentration:Peptide-based fertility therapies require specialized logistics networks dominated by three European cold-chain providers, creating single-point vulnerability.
- Substitution Threat from Aromatase Inhibitors:Letrozole and similar oral compounds are capturing first-line ovulatory disorder cases previously managed with injectable gonadotropins.
Strategic Opportunities
- Self-Administration Protocol Adoption:Patient-managed subcutaneous injection systems are reducing clinic dependency in the United States, opening direct-to-patient pharmacy channels previously blocked by institutional purchasing.
- Insurance Coverage Expansion Mandates:State-level fertility treatment mandates in New York and Illinois are extending reimbursement to oral ovulation inducers previously excluded from commercial formularies.
- Digital Cycle Tracking Convergence:Smartphone-based fertility monitoring applications are integrating with pharmaceutical adherence programs, creating data-linked prescription renewal models.
Industry Challenges
- Reproductive Endocrinology Specialist Shortage:Fellowship-trained clinicians are concentrating in coastal metropolitan areas, leaving interior regions underserved for complex gonadotropin protocol management.
- Biosimilar Interchangeability Certification Delays:The FDA's evolving standards for gonadotropin biosimilar switching protocols are extending pre-launch compliance timelines beyond original forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Female Infertility Drugs Market |
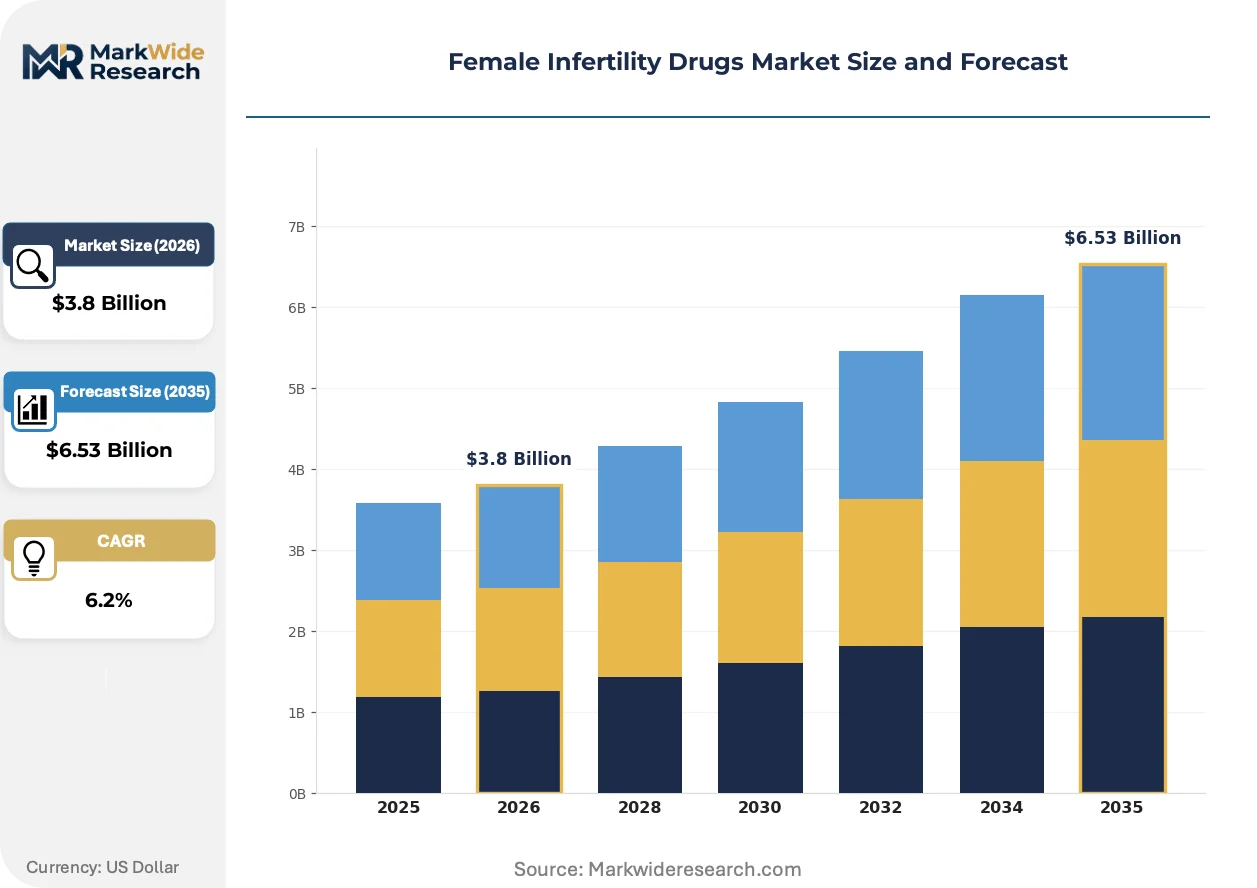
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Clomiphene Citrate, Gonadotropins, Letrozole, Metformin Administration Route: Oral, Subcutaneous, Intravenous, Intramuscular Therapy Area: Polycystic Ovary Syndrome, Endometriosis, Ovulatory Disorders, Unexplained Infertility End User: Hospitals, Fertility Clinics, Home Care, Research Laboratories |
| Companies Covered | Merck & Co., Inc., Ferring B.V., Bayer AG, Novartis AG, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Abbott, Sanofi, IBSA Institut Biochimique SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Female Infertility Drugs Market Shifts & Advancements
Recombinant protein engineering is displacing extraction-based hormone production, while digital health integration and regulatory pathway innovation are compressing product development cycles. These forces are restructuring how fertility therapeutics reach patients.
Pen-injector delivery systems for follicle-stimulating hormone are converging with connected health platforms that log dosing timestamps and physiological response data. Fertility clinics in the United States are adopting these devices at accelerating rates, particularly among networks seeking to reduce nursing staff time per patient cycle. This convergence is enabling remote monitoring protocols that shift cycle management partially outside clinical settings.
The EMA's centralized marketing authorization procedures are harmonizing batch release standards across European member states, eliminating redundant national testing requirements that previously delayed product launches. Manufacturers now submit single dossiers to the Committee for Medicinal Products for Human Use rather than navigating fragmented national procedures. Centralized cold-chain distribution hubs in the Netherlands and Germany are consolidating logistics to match this regulatory unification.
Patient-driven pharmacy selection is displacing clinic-captive dispensing models as self-administration protocols expand. United States fertility patients increasingly source gonadotropins through specialty pharmacies offering home delivery and insurance pre-authorization support. This behavioral shift is most visible in states with mandated fertility coverage, where out-of-pocket cost sensitivity drives pharmacy switching despite physician preferences for integrated clinic dispensing.
Female Infertility Drugs Market Segmentation
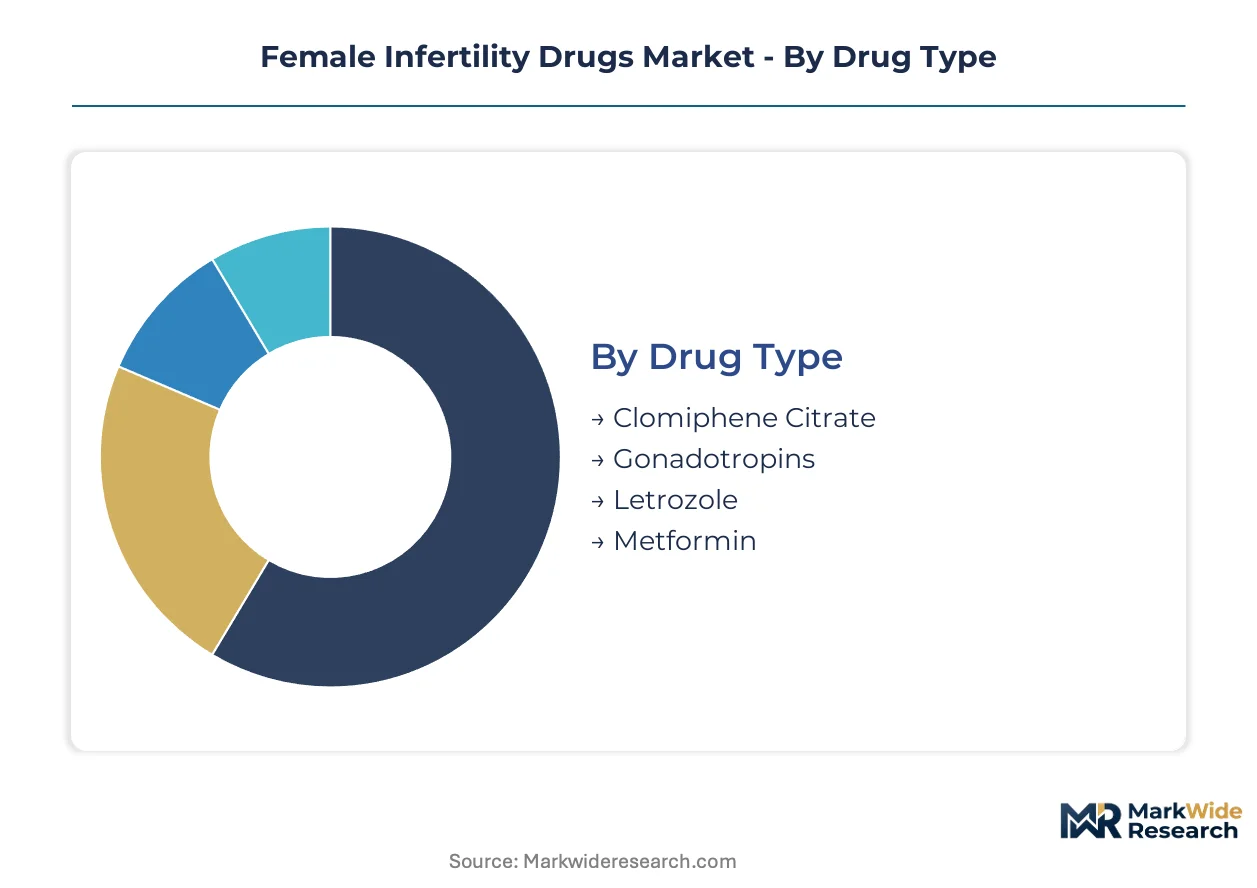
Drug type and administration route configurations determine reimbursement pathways and manufacturing investment priorities across female infertility therapeutics. Therapy area specialization shapes clinical trial design and regulatory submission strategies. End-user channel selection influences cold-chain logistics requirements and patient education protocols.
Drug Type:
Manufacturing complexity and purity specifications differentiate competitive positioning across hormonal and non-hormonal fertility agents.
- Gonadotropins:Purified follicle-stimulating hormone and luteinizing hormone preparations require recombinant biomanufacturing or urinary extraction protocols with stringent batch consistency controls. Demand concentrates in fertility clinic networks across the United States where multi-cycle administration protocols drive prescription volumes and cold-chain logistics investment.
- Clomiphene Citrate:Synthetic estrogen receptor modulator administered orally for first-line ovulatory disorder treatment with established generic manufacturing infrastructure. Volume leadership persists in emerging markets where cost sensitivity favors oral administration over injectable alternatives.
- Letrozole:Aromatase inhibitor repurposed for ovulation induction with off-label prescribing patterns in polycystic ovary syndrome cases.
- Metformin:Insulin-sensitizing agent addressing metabolic dysfunction underlying insulin-resistant infertility subtypes.
Gonadotropins lead on scale; Letrozole leads on momentum.
Administration Route:
Patient self-management capabilities and clinic resource constraints reshape delivery format preferences across treatment settings.
- Subcutaneous:Pen-injector and pre-filled syringe formats enable home administration with reduced nursing supervision requirements. Adoption accelerates in United States fertility clinic networks seeking to decentralize cycle monitoring and expand patient throughput without proportional staff expansion.
- Oral:Tablet and capsule formulations eliminate cold-chain dependencies and enable retail pharmacy dispensing with minimal patient training. First-line therapy protocols across public health systems favor oral routes for cost containment and treatment accessibility.
- Intramuscular:Deep injection requirements limit self-administration and sustain clinic-dependent dispensing models for specific gonadotropin preparations.
- Intravenous:Hospital-administered protocols reserved for specialized interventions with intensive monitoring requirements.
Oral administration leads on scale; Subcutaneous injection leads on momentum.
Therapy Area:
Underlying pathophysiology determines treatment duration, combination therapy requirements, and success rate benchmarking across patient populations.
- Polycystic Ovary Syndrome:Metabolic and endocrine dysfunction requiring multi-modal intervention with insulin sensitizers, ovulation inducers, and lifestyle modification protocols. Patient volumes concentrate in United States fertility networks where diagnostic criteria standardization has expanded treatable population identification.
- Ovulatory Disorders:Hypothalamic-pituitary axis dysfunction addressed through targeted hormonal stimulation with individualized dosing titration. Treatment protocols vary across European member states based on national reimbursement guidelines for gonadotropin coverage.
- Endometriosis:Inflammatory and anatomical factors complicating conception requiring surgical-pharmaceutical combination approaches.
- Unexplained Infertility:Diagnosis of exclusion prompting empirical treatment protocols with variable response predictability.
Polycystic Ovary Syndrome leads on scale; Ovulatory Disorders leads on momentum.
End User:
Channel configuration determines procurement scale, patient education investment, and regulatory compliance burden across care settings.
- Fertility Clinics:Specialized reproductive health centers with consolidated purchasing power and standardized treatment protocols driving gonadotropin volume concentration. Network expansion across United States metropolitan markets accelerates prescription growth through centralized formulary management.
- Home Care:Self-administration protocols with remote monitoring support reducing clinic visit frequency for stable patients. Channel development concentrates in states with mandated fertility coverage where insurance pre-authorization processes enable direct-to-patient pharmacy fulfillment.
- Hospitals:Acute care settings managing complex cases with comorbidity considerations and surgical intervention requirements.
- Research Laboratories:Academic and commercial investigators conducting clinical trials with specialized compound sourcing needs.
Fertility Clinics leads on scale; Home Care leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertility clinic networks across the United States concentrate the highest prescription volumes for gonadotropin therapies. State-level insurance mandates and specialized reproductive health infrastructure shape demand patterns across major markets.
United States
Specialized fertility clinic networks in New York and Illinois drive gonadotropin prescription volumes through state-mandated insurance coverage expansions. The FDA's 505(b)(2) pathway accelerates approval timelines for reformulated hormonal delivery systems. Greater Boston anchors research-intensive fertility centers where pen-injector adoption rates exceed national averages.
Germany
Centralized procurement through the EMA harmonizes batch release standards for recombinant hormone products across member states. The country's statutory health insurance system maintains consistent reimbursement for ovulation-inducing agents. The Rhine-Ruhr metropolitan region concentrates fertility clinic networks with standardized treatment protocols.
United Kingdom
National Health Service funding allocations determine regional access to gonadotropin therapies across England and devolved administrations. The Medicines and Healthcare products Regulatory Agency oversees post-Brexit marketing authorization procedures. London's Harley Street medical district hosts concentrated private fertility clinic capacity serving international patients.
Japan
PMDA review timelines for reproductive health therapeutics influence product launch sequencing across Asia-Pacific markets. The country's aging demographic profile sustains demand for assisted reproductive technology services. The Tokyo-Osaka corridor concentrates fertility clinic networks with advanced hormone protocol management capabilities.
India
CDSCO regulatory pathways for hormonal fertility products attract multinational manufacturing investments targeting price-sensitive emerging markets. Domestic pharmaceutical production scales oral ovulation inducers for regional export. Maharashtra's Mumbai-Pune industrial corridor hosts contract manufacturing organizations supplying purified hormone raw materials.
Female Infertility Drugs Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from core gonadotropin production into adjacent reproductive health segments. The market structures around three tiers: multinational pharmaceutical conglomerates with broad hormonal portfolios, specialized reproductive health companies with dedicated cold-chain capabilities, and regional generic manufacturers of oral ovulation inducers. Strategic archetypes include recombinant biomanufacturing specialists, peptide-based therapy developers, and broad gynecological portfolio players. Competitive intensity concentrates in M&A activity targeting fertility clinic distribution networks and licensing agreements for improved subcutaneous delivery formats.
Among established pharmaceutical conglomerates, Merck & Co., Inc. and Bayer AG occupy positions reflecting diversified hormonal product portfolios spanning multiple therapeutic areas. Ferring B.V. exemplifies the specialized reproductive health archetype with concentrated expertise in peptide-based fertility therapies. These three companies represent distinct strategic approaches to market participation: broad portfolio leverage, dedicated reproductive specialization, and integrated gynecological-to-fertility extension.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Ferring B.V. |
| Bayer AG |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Abbott |
| Sanofi |
| IBSA Institut Biochimique SA |
| Others |
Supply & Pricing Matrix
Urinary-derived gonadotropin extract prices cascade through three pricing tiers for fertility therapeutics, with recombinant follicle-stimulating hormone commanding premium positioning while oral clomiphene citrate anchors volume-accessible segments. Chinese contract manufacturing organization pricing volatility for purified hormone raw materials feeds directly into gonadotropin cost structures, compressing margins for mid-tier suppliers dependent on outsourced biomanufacturing inputs.
Pricing Analysis
Input-cost pass-through from recombinant biomanufacturing investments is stratifying pricing across premium, standard, and economy tiers. Brand premiums for FDA-approved pen-injector formats differentiate from urinary-derived alternatives, while volume scale discounts concentrate among consolidated fertility clinic networks. Pricing pressure stems from letrozole substitution in first-line ovulatory disorder protocols. Oral administration patients exhibit highest price sensitivity; fertility clinic procurement officers show lowest sensitivity due to insurance pre-authorization coverage.
Supply Chain Analysis
Single-source vulnerability sits with European cold-chain providers dominating peptide-based fertility therapy distribution. Manufacturing concentration centers on China, India, and the United States for hormone raw materials and finished dosage forms. Recombinant protein production draws from single-use bioreactor inputs, purified gonadotropin extracts, and specialized peptide synthesis precursors. Tariff exposure on Chinese biomanufacturing inputs poses structural risk. Distribution runs through fertility clinic networks, specialty pharmacies, and hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The female infertility drugs market functions as a geographic-arbitrage play, with state-level insurance mandates in New York and Illinois creating reimbursement advantages unavailable in non-mandated jurisdictions, enabling volume concentration and pricing power for suppliers aligned with covered clinic networks.
For Market Incumbents: Cement recombinant manufacturing scale advantages through backward integration into single-use bioreactor production, reducing dependency on Chinese contract manufacturing organizations. Fortify fertility clinic distribution relationships against biosimilar entry by embedding pen-injector devices with digital adherence tracking, creating switching costs for institutional buyers.
For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy channels in states with mandated fertility coverage, bypassing clinic-captive dispensing models. Target home care administration protocols with subcutaneous injection training support, capturing patients seeking reduced clinic visit frequency. White-space opportunity concentrates in underserved interior regions facing reproductive endocrinology specialist shortages.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized reproductive health companies possessing dedicated cold-chain capabilities and peptide formulation expertise. Long-term viability hinges on regulatory pathway navigation and fertility clinic network access rather than manufacturing scale alone. Watch FDA biosimilar interchangeability certification timelines as inflection indicator for gonadotropin reference product defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Manufacturing Scale-Up | Single-use bioreactor investments resolve batch consistency constraints for follicle-stimulating hormone production. |
| Pen-Injector Digital Integration | Connected health platforms logging dosing timestamps enable remote cycle monitoring outside clinical settings. |
| Specialty Pharmacy Channel Development | Direct-to-patient fulfillment with insurance pre-authorization support captures self-administration protocol growth. |
| State Mandate Alignment Strategy | Formulary positioning in New York and Illinois maximizes reimbursement capture under expanded coverage mandates. |
| Biosimilar Defense Certification | FDA interchangeability pathway navigation extends reference product exclusivity through compliance complexity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reproductive endocrinologists, fertility clinic procurement directors, pharmaceutical regulatory affairs specialists, and specialty pharmacy operations managers with secondary validation against FDA 505(b)(2) filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov fertility intervention records, and state-level insurance mandate legislative databases. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates.
Comparable-period anchoring calibrated the projection horizon against historical gonadotropin shipment data and fertility clinic network expansion rates. Segmentation dimensions spanned drug type, administration route, therapy area, and end-user channel. CAGRs derived from patient volume trajectories, treatment cycle frequency patterns, and reimbursement expansion assumptions. Forecast inputs incorporated biosimilar entry probability assessments and cold-chain logistics capacity constraints.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, pandemic-related fertility clinic capacity disruptions, and radical substitution by in vitro maturation technologies eliminating pharmacological ovulation induction. Forecasts reflect documented assumptions about patient adherence rates and insurance coverage stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market