
 Combination Antibody Therapy Market | 2026-2036
Combination Antibody Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Combination Antibody Therapy Market Analysis
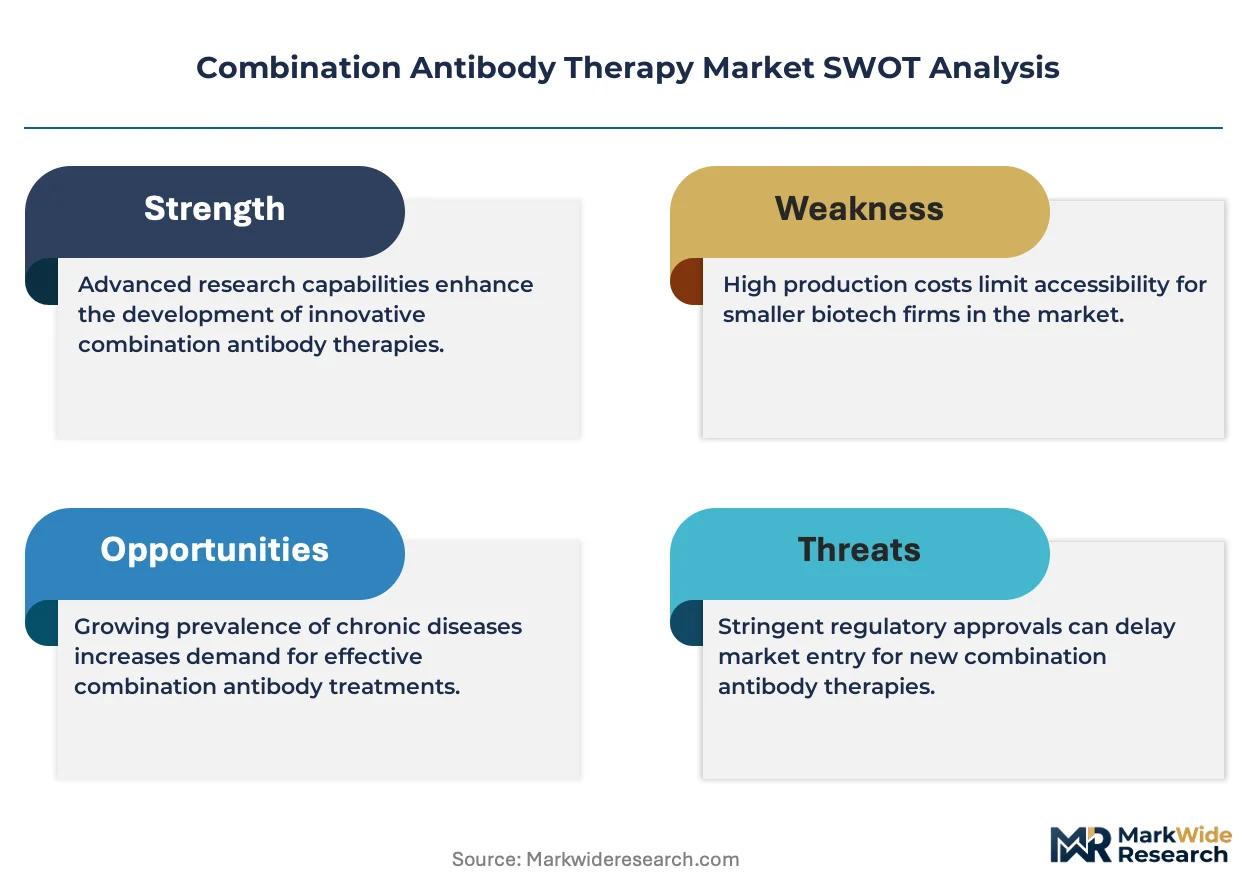
Buyer concentration among oncology hospital networks is consolidating as large health systems centralize infusion services and formulary decisions under single pharmacy committees. Roche Holding AG leverages its diagnostic companion test infrastructure to lock in combination therapy protocols. Bristol-Myers Squibb Company anchors its position through PD-1 backbone franchises that pair with partner antibodies. Merck and Co., Inc. competes by sustaining one of the largest immuno-oncology clinical trial portfolios in combination settings.
Combination antibody therapy deploys two or more engineered immunoglobulins simultaneously to engage multiple disease targets, with bispecific formats typically constructed from fragment crystallizable regions fused to distinct variable domains for dual-antigen recognition. The primary purpose centers on overcoming tumor resistance mechanisms and amplifying immune cell activation beyond what monotherapy achieves. Bispecific antibodies command the fastest expansion trajectory as manufacturing yields improve and T-cell engager designs mature, while monoclonal antibody pairings retain the largest revenue pool due to established safety databases and payer familiarity. Cancer applications absorb the majority of development investment, though autoimmune disease combinations are gaining trial momentum as IL-17 and IL-23 pathway blockers enter pairing studies.
FDA breakthrough therapy designation and EMA priority medicines pathways compress review timelines for combination regimens, directly influencing sponsor R&D allocation toward dual-mechanism candidates. The FDA's Project Optimus is reshaping dose-finding expectations for combination trials, forcing earlier biomarker stratification. China's NMPA has expanded its accelerated approval framework for innovative biologics, opening parallel development tracks for multinational sponsors. Stakeholders must monitor evolving biosimilar entry timelines for legacy monoclonal components, as patent cliffs on combination anchors threaten to commoditize backbone therapy pricing before novel pairings reach maturity.
Market Dynamics
Academic medical centers are consolidating infusion services under centralized pharmacy committees, compressing formulary access for combination antibody developers and amplifying bargaining leverage among oncology hospital networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Compressed review timelines for bispecific constructs redirect sponsor R&D budgets toward dual-mechanism candidates.
- Companion Diagnostic Infrastructure:Diagnostic-therapy pairing protocols lock in protocol adherence at major cancer centers.
- T-Cell Engager Manufacturing Yields:Improved bioprocess economics for bispecific formats accelerate clinical pipeline advancement.
Market Restraints
- Patent Cliff Exposure:Biosimilar entry timelines for legacy PD-1 backbone monoclonals threaten to commoditize anchor therapy pricing before novel pairings mature.
- Bioprocess Input Concentration:Protein A resin and single-use bioreactor supply chains concentrate among limited vendors, creating procurement vulnerability.
- EMA Dose-Finding Requirements:Project Optimus-aligned expectations force earlier biomarker stratification, extending Phase I timelines.
Strategic Opportunities
- Autoimmune Disease Pairings:IL-17 and IL-23 pathway blocker combinations represent underpenetrated therapeutic territory beyond oncology.
- China NMPA Parallel Tracks:Expanded accelerated approval framework for innovative biologics enables simultaneous East-West development.
- Site-of-Care Expansion:Community oncology infusion centers offer channel diversification beyond academic medical center concentration.
Industry Challenges
- Bioprocess Talent Scarcity:Cell line development and continuous manufacturing expertise concentrates among experienced specialists, constraining capacity expansion.
- Combination IP Complexity:Cross-licensing negotiations between backbone and partner antibody patent holders create transaction friction.
- Legacy System Integration:Electronic health record interoperability gaps complicate combination protocol adherence tracking across health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combination Antibody Therapy Market |
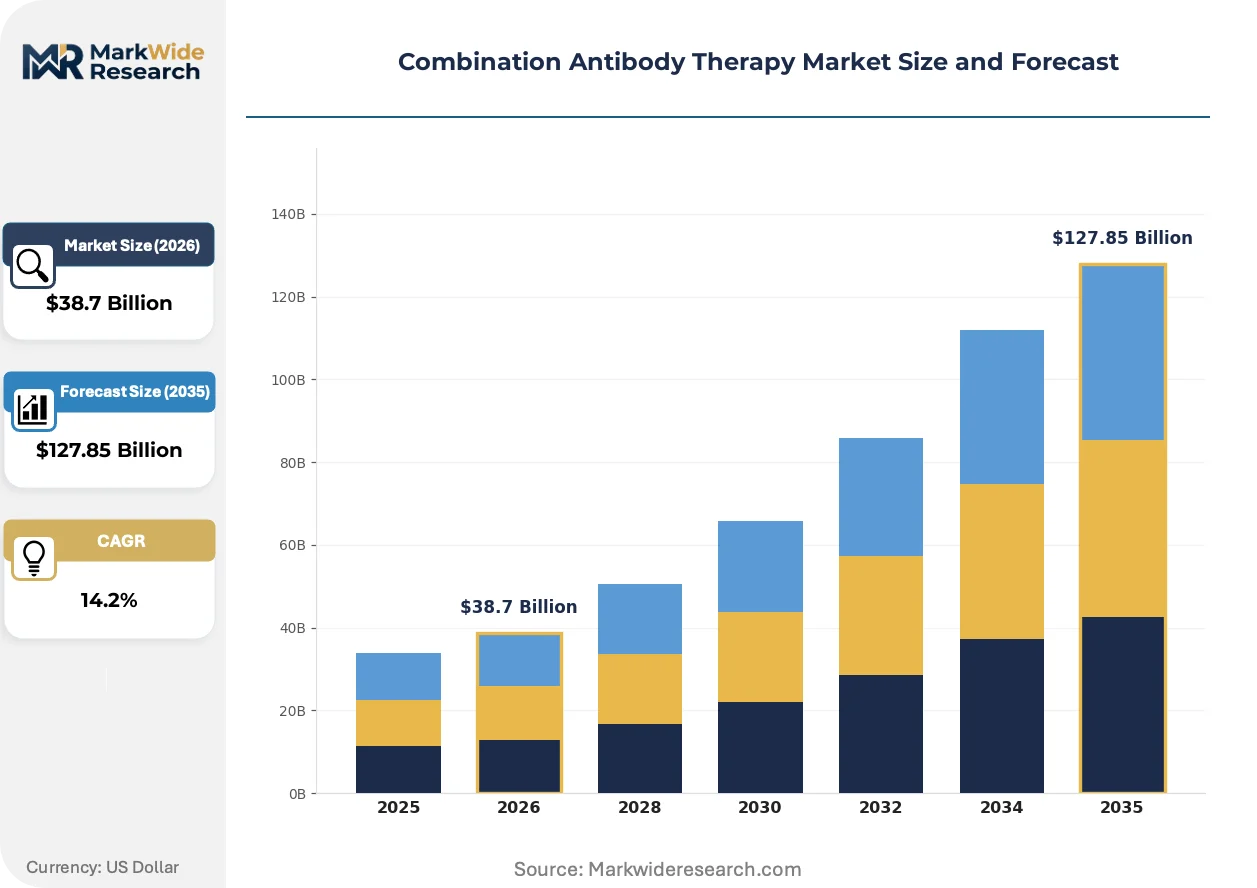
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Bispecific Antibodies, ADCs, ScFv Therapy Area: Cancer, Autoimmune Diseases, Infectious Diseases, Neurological Disorders End User: Hospitals, Research Institutes, Pharmaceutical Companies, Clinics Administration Route: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | Roche Holding AG, Merck and Co., Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, Pfizer Inc., Novartis AG, Sanofi S.A., Amgen Inc., Regeneron Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combination Antibody Therapy Market Emerging Trajectories
Bispecific antibody engineering is compressing development timelines while regulatory pathways and procurement models simultaneously reshape competitive access. Three forces merit particular attention.
Modular bispecific platforms employing common light-chain architectures and Fc-silencing mutations are electrifying clinical pipeline productivity. Mid-cap biotech sponsors adopt these toolkits to bypass traditional hybridoma timelines. The structural consequence is collapsing the gap between target validation and IND filing for combination candidates.
EMA's Priority Medicines pathway and FDA's Project Optimus are forcing earlier biomarker integration into combination dose-finding studies. Sponsors now stratify patient populations before Phase II expansion. Oncology trials in Germany and France are most affected, with protocol amendments rising to accommodate adaptive designs.
Hospital network procurement committees are unbundling combination therapy purchasing from diagnostic service agreements. Standalone antibody contracts replace bundled offerings. This pattern is most visible in United States integrated delivery networks, where pharmacy benefit managers now negotiate combination regimens separately from companion testing.
Combination Antibody Therapy Market Segmentation
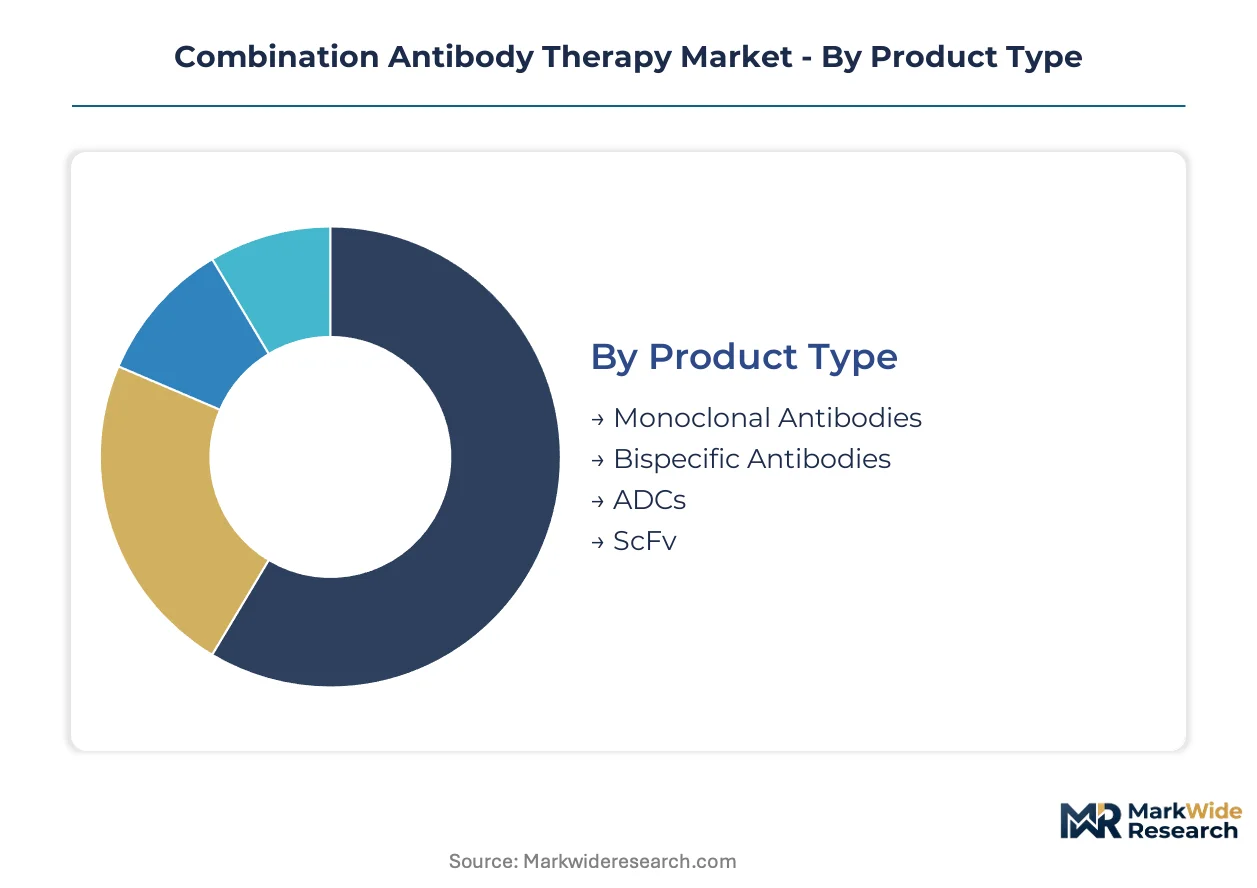
Combination antibody therapy segmentation reveals divergent commercial trajectories across molecular formats and clinical settings. Product architecture determines manufacturing complexity, reimbursement pathways, and prescriber familiarity. Understanding these divides illuminates where development capital concentrates versus where novel modalities are displacing established protocols.
Product Type:
Volume concentration sits with legacy monoclonal formats, while premium pricing and fastest expansion attach to engineered constructs with dual-targeting capability.
- Monoclonal Antibodies:Established immunoglobulin structures with single-antigen specificity dominate current prescription volumes. Demand clusters in United States oncology networks where PD-1 backbone familiarity streamlines payer negotiation, though biosimilar pressure on anchor therapies compresses margin expansion for new pairings.
- Bispecific Antibodies:Engineered constructs presenting two distinct antigen-binding domains enable simultaneous engagement of T-cells and tumor targets. Manufacturing yield improvements and T-cell engager maturation are accelerating clinical advancement, with Germany and Japan showing strongest early adoption among academic medical centers.
- ADCs:Antibody-drug conjugates linking cytotoxic payloads to tumor-targeting immunoglobulins.
- ScFv:Single-chain variable fragments offering reduced molecular weight for enhanced tissue penetration.
Mature deployment sits with Monoclonal Antibodies. Newer deployment is concentrated in Bispecific Antibodies.
Therapy Area:
Cancer applications absorb the dominant share of clinical trial investment, though autoimmune indications are emerging as the next major expansion frontier.
- Cancer:Solid tumor and hematologic malignancy applications command the majority of combination protocol development. United States academic medical centers anchor demand through centralized infusion services, while EMA priority medicines pathways accelerate European access for breakthrough bispecific regimens.
- Autoimmune Diseases:IL-17 and IL-23 pathway blocker combinations are gaining trial momentum beyond oncology. Japan's PMDA has shown regulatory receptivity to cytokine-targeting pairings, creating parallel development opportunities with FDA tracks.
- Infectious Diseases:Neutralizing antibody cocktails for viral and resistant bacterial pathogens.
- Neurological Disorders:Blood-brain barrier penetration challenges limit current deployment.
Established revenue concentration remains in Cancer. Steepest expansion trajectory is emerging in Autoimmune Diseases.
End User:
Procurement authority is consolidating under centralized pharmacy committees, reshaping access dynamics across delivery settings.
- Hospitals:Integrated delivery networks and academic medical centers control the majority of combination therapy administration. Formulary decisions increasingly concentrate under single pharmacy committees in United States health systems, amplifying bargaining leverage and compressing access timelines for new entrants.
- Pharmaceutical Companies:Sponsors conducting combination trials in-house drive demand for contract manufacturing and clinical supply. China's NMPA parallel track framework attracts multinational development investment, expanding East-West simultaneous filing strategies.
- Research Institutes:Academic laboratories conducting early mechanistic and translational studies.
- Clinics:Community oncology infusion centers seeking protocol diversification beyond academic referral patterns.
Current purchasing volume concentrates in Hospitals. Emerging channel diversification is shifting toward Clinics.
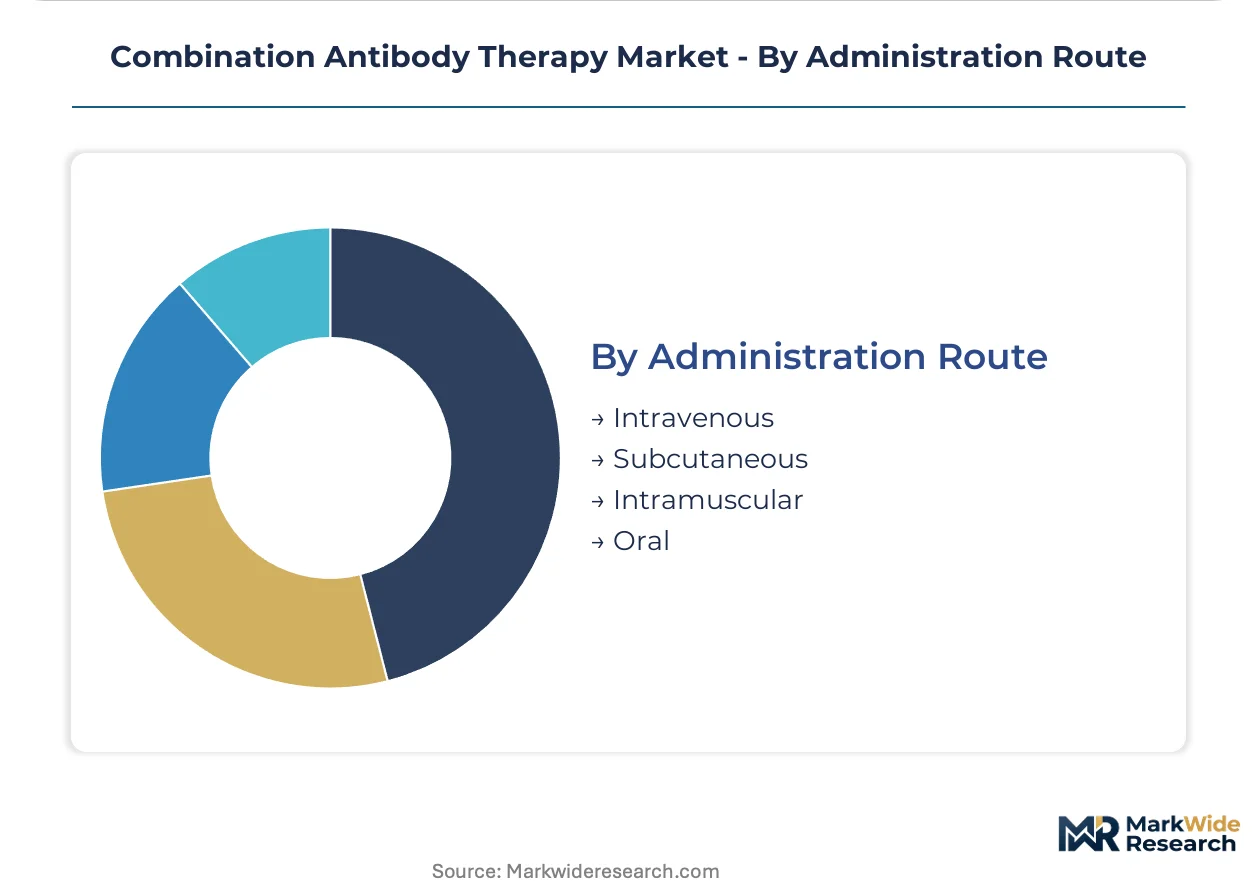
Administration Route:
Infusion logistics and patient convenience preferences are creating divergence between institutional and ambulatory delivery models.
- Intravenous:Hospital-based infusion remains the standard for most combination antibody protocols. Germany's outpatient oncology infrastructure supports same-day administration, while United States site-of-care reimbursement differences create channel friction.
- Subcutaneous:Self-administration potential and reduced infusion center burden are driving format innovation. Japan's aging population demographics favor reduced clinic visit requirements, supporting development investment in subcutaneous delivery systems.
- Intramuscular:Limited current deployment for select infectious disease prophylaxis applications.
- Oral:Bioavailability barriers restrict antibody delivery through gastrointestinal routes.
Institutional dependency anchors Intravenous protocols. Patient convenience pressures are accelerating Subcutaneous format development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell culture media and protein A resin supply chains concentrate in Massachusetts and Basel, anchoring clinical trial infrastructure and manufacturing scale for combination antibody development. Academic medical centers in these localities drive protocol adoption through centralized infusion networks.
United States
Oncology hospital networks in Boston, New York, and Houston consolidate formulary decisions under single pharmacy committees, amplifying bargaining leverage for combination regimens. FDA breakthrough therapy designation and Project Optimus reshape dose-finding expectations, compressing review timelines for bispecific constructs. The National Cancer Institute's clinical trial networks in Maryland accelerate patient recruitment for combination protocols.
Germany
Academic medical centers in Munich and Heidelberg expand combination antibody infusion services through centralized outpatient oncology infrastructure. EMA priority medicines pathways accelerate European access for dual-mechanism candidates, with Germany hosting the most adaptive design protocol amendments. The Rhine-Main biotech cluster concentrates contract manufacturing for T-cell engager formats.
Japan
PMDA regulatory receptivity to cytokine-targeting pairings creates parallel development tracks with FDA pathways, particularly for IL-17 and IL-23 blocker combinations. Aging demographics in Tokyo and Osaka favor subcutaneous delivery format investment to reduce clinic visit burdens. The Kansai region anchors bioprocess development for reduced-molecular-weight antibody constructs.
China
NMPA's expanded accelerated approval framework for innovative biologics attracts multinational sponsor investment for simultaneous East-West filing strategies. Shanghai and Suzhou biotech parks concentrate cell line development expertise for bispecific manufacturing. The Yangtze River Delta cluster hosts the majority of domestic contract development organizations supporting combination trials.
Switzerland
Swissmedic maintains alignment with EMA priority pathways while offering distinct regulatory consultation for complex biologics, streamlining combination therapy submissions. Basel and Zurich anchor diagnostic companion test infrastructure that locks in protocol adherence at European cancer centers. The country's concentrated vendor ecosystem for protein A resin and single-use bioreactors creates procurement proximity for sponsors.
Combination Antibody Therapy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular bispecific platforms and autoimmune disease pairings beyond oncology. The market structure concentrates around diversified pharmaceutical conglomerates with PD-1 backbone franchises and diagnostic infrastructure, while mid-cap biotech sponsors adopt common light-chain toolkits to collapse development timelines. Three archetypes dominate: diagnostic-therapy integrators, immuno-oncology portfolio holders, and platform-technology licensors. Competitive moves center on cross-licensing negotiations for combination IP and backward integration into cell line development capabilities.
Within the diagnostic-therapy integration tier, Roche Holding AG exemplifies the archetype through companion test infrastructure that locks in protocol adherence. Bristol-Myers Squibb Company and Merck and Co., Inc. occupy positions as immuno-oncology portfolio anchors, with the former representing PD-1 backbone pairing strategies and the latter exemplifying large-scale clinical trial investment in combination settings. These three entities sit within the premium tier of competitive positioning.
| Leading Market Players |
|---|
| Roche Holding AG |
| Merck and Co., Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| Amgen Inc. |
| Regeneron Pharmaceuticals, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive bioprocess infrastructure anchors both supply security and pricing power for combination antibody developers, as sponsors with in-house cell line development capabilities command premium positioning against contract-dependent rivals facing resin scarcity and single-use bioreactor allocation constraints.
Pricing Analysis
Companion diagnostic bundling has unbundled from antibody contracts across United States integrated delivery networks, with pharmacy benefit managers now negotiating combination regimens separately from testing services. Pricing stratifies across premium, standard, and economy tiers based on manufacturing complexity and biomarker stratification requirements. Cost compression in PD-1 backbone therapies is intensifying because biosimilar entry timelines threaten anchor therapy commoditization. Academic medical centers demonstrate highest price sensitivity due to formulary committee consolidation, while specialty oncology clinics show lowest sensitivity for breakthrough bispecific constructs.
Supply Chain Analysis
Domestic-content mandates under China's NMPA parallel track framework are reshaping sourcing patterns, requiring multinational sponsors to establish cell line development capabilities within Shanghai and Suzhou biotech parks. Protein A resin and single-use bioreactor supply chains concentrate in Massachusetts, Basel, and the Rhine-Main cluster, with raw material dependencies tethered to chromatography media, sterile filtration assemblies, and genetically engineered cell substrates. Single-source vulnerability from limited qualified resin vendors creates procurement chokepoints. Distribution runs through centralized pharmacy committees at academic medical centers before reaching community infusion sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with cell line development capabilities and diagnostic companion test infrastructure representing the decisive upstream and downstream levers separating premium-tier positioning from margin compression.
For Market Incumbents: Cement protocol adherence through diagnostic-therapy integration investments that lock in formulary positioning at consolidating oncology hospital networks. Defend against modular bispecific platform disruption by acquiring cell line development specialists in the Yangtze River Delta and Rhine-Main clusters. Prioritize backward integration into protein A resin supply relationships to insulate against single-vendor procurement vulnerability.
For New Entrants and Emerging Players: Modular common light-chain architectures offer the most penetrable wedge for collapsing IND filing timelines against established hybridoma-dependent rivals. Target autoimmune disease pairings beyond oncology, specifically IL-17 and IL-23 pathway blocker combinations where regulatory receptivity in Japan and trial momentum remain underexploited. Pursue site-of-care expansion through community oncology infusion centers as the primary go-to-market channel diversification play.
For Investors and Strategic Acquirers: Exit pathways concentrate in diagnostic-therapy integrators and platform-technology licensors with captive manufacturing capabilities. Long-term viability over the next decade hinges on backward integration depth and biomarker stratification infrastructure. Monitor biosimilar entry timelines for legacy PD-1 anchors as the critical inflection signal for backbone therapy pricing trajectories and novel pairing margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Roche's diagnostic infrastructure locks in protocol adherence at major cancer centers. |
| Modular Bispecific Platform Licensing | Common light-chain toolkits collapse development timelines for mid-cap biotech sponsors. |
| Cell Line Development Acquisition | Captive bioprocess capabilities insulate against protein A resin supply concentration. |
| Autoimmune Disease Pipeline Expansion | IL-17 and IL-23 blocker combinations open underpenetrated therapeutic territory beyond oncology. |
| Community Infusion Center Partnership | Site-of-care diversification reduces dependency on academic medical center procurement committees. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced against formulary databases and hospital procurement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated quantitative assumptions. Bottom-up and top-down triangulation anchored volume estimates across molecular formats and therapy areas.
Bottom-up modeling anchored patient-flow analysis across cancer and autoimmune indications, while top-down approaches validated against biopharmaceutical R&D expenditure patterns. Segmentation dimensions included product architecture, therapy area, end-user setting, and regional regulatory cluster. CAGRs were derived from patent cliff exposure timelines, biosimilar entry assumptions, and accelerated approval pathway expansion rates. Forecast inputs incorporated T-cell engager manufacturing yield improvement curves and companion diagnostic penetration assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on accelerated approval pathways, catastrophic bioprocess facility contamination events, and geopolitical trade restrictions on critical chromatography media. Forecasts reflect documented assumptions regarding reimbursement stability and manufacturing scale-up success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
A - Estradiol Market