
 Somatostatin Analogs Market | 2026-2036
Somatostatin Analogs Market Size, Share, and Industry Trends Forecast 2026-2036
Somatostatin Analogs Market Intelligence
Demand for somatostatin analogs is rotating from general hospital pharmacies toward specialized oncology centers and clinics. This shift reflects the increasing complexity of treating neuroendocrine tumors and acromegaly. Novartis AG leverages its deep R&D pipeline and established brand presence in this space. Ipsen Pharma specializes in lanreotide-based therapies, while Sun Pharmaceutical Industries Ltd expands access through its generic offerings in multiple countries.
Somatostatin analogs are synthetic peptides designed to mimic natural somatostatin by binding to specific somatostatin receptors like SSTR2 and SSTR5. Their primary function is to inhibit aberrant hormone secretion, particularly growth hormone in acromegaly. While octreotide represents a mature product segment, long-acting lanreotide formulations are capturing market share due to improved patient convenience. The treatment of neuroendocrine tumors remains the dominant and most valuable therapy area.
Market access is governed by stringent regulatory reviews from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These agencies' approvals for new indications and long-acting release formulations are critical for commercial success. Orphan drug designations further influence development strategies for rare conditions. Future value capture depends on developing novel delivery systems and managing the lifecycle of established molecules against emerging biosimilars.
Market Dynamics
The concentration of care for neuroendocrine tumors and acromegaly into specialized oncology and endocrinology centers is the central force shaping the somatostatin analogs market. This shift dictates prescriber behavior, distribution channels, and patient access models globally.
Growth Catalysts
- Orphan Drug Incentives:Regulatory frameworks like the Orphan Drug Act in the United States and similar programs by the European Medicines Agency (EMA) provide market exclusivity and development support, encouraging investment in therapies for rare conditions like acromegaly.
- Expanding Healthcare Access:Rising diagnostic rates and expanding access to specialized oncological care in countries like China are creating significant new patient populations for both branded and generic somatostatin analogs.
- Long-Acting Formulations:The development of long-acting release (LAR) and depot injection technologies improves patient compliance and therapeutic outcomes by reducing dosing frequency, which is a primary driver for adoption by clinicians.
Market Restraints
- High Treatment Costs:The significant expense associated with long-term somatostatin analog therapy creates access barriers for patients in healthcare systems with limited reimbursement coverage or high out-of-pocket costs.
- Advent of Biosimilars:The patent expiration of first-generation molecules like octreotide is leading to the entry of biosimilars, creating price erosion and revenue pressure on originator products in this segment.
- Non-Curative Nature:These therapies primarily manage symptoms and inhibit tumor growth or hormone secretion rather than providing a cure, representing a fundamental therapeutic limitation for conditions like neuroendocrine tumors.
Strategic Opportunities
- Indication Expansion:Pursuing regulatory approvals from agencies like the US FDA for new indications beyond neuroendocrine tumors and acromegaly presents a significant opportunity to expand the addressable patient population.
- Novel Delivery Systems:Research into non-injectable delivery methods, such as oral formulations or transdermal patches, represents a major area for innovation that could capture share by dramatically improving patient convenience.
- Underpenetrated Markets:Increasing clinical education and diagnostic capabilities in large markets like Brazil, supported by its regulator ANVISA, can unlock substantial new demand as awareness of target diseases grows.
Industry Challenges
- Complex Manufacturing:The production of synthetic peptides is a highly specialized and capital-intensive process, creating supply chain vulnerabilities and requiring significant expertise in biomanufacturing to ensure quality and consistency.
- Cold Chain Logistics:Many long-acting formulations require stringent temperature controls throughout the distribution and storage process, adding complexity and cost to the supply chain, particularly in emerging markets.
- Clinical Trial Recruitment:The rarity of conditions like acromegaly and specific types of neuroendocrine tumors makes recruiting sufficient patient numbers for clinical trials a lengthy and expensive challenge for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Somatostatin Analogs Market |
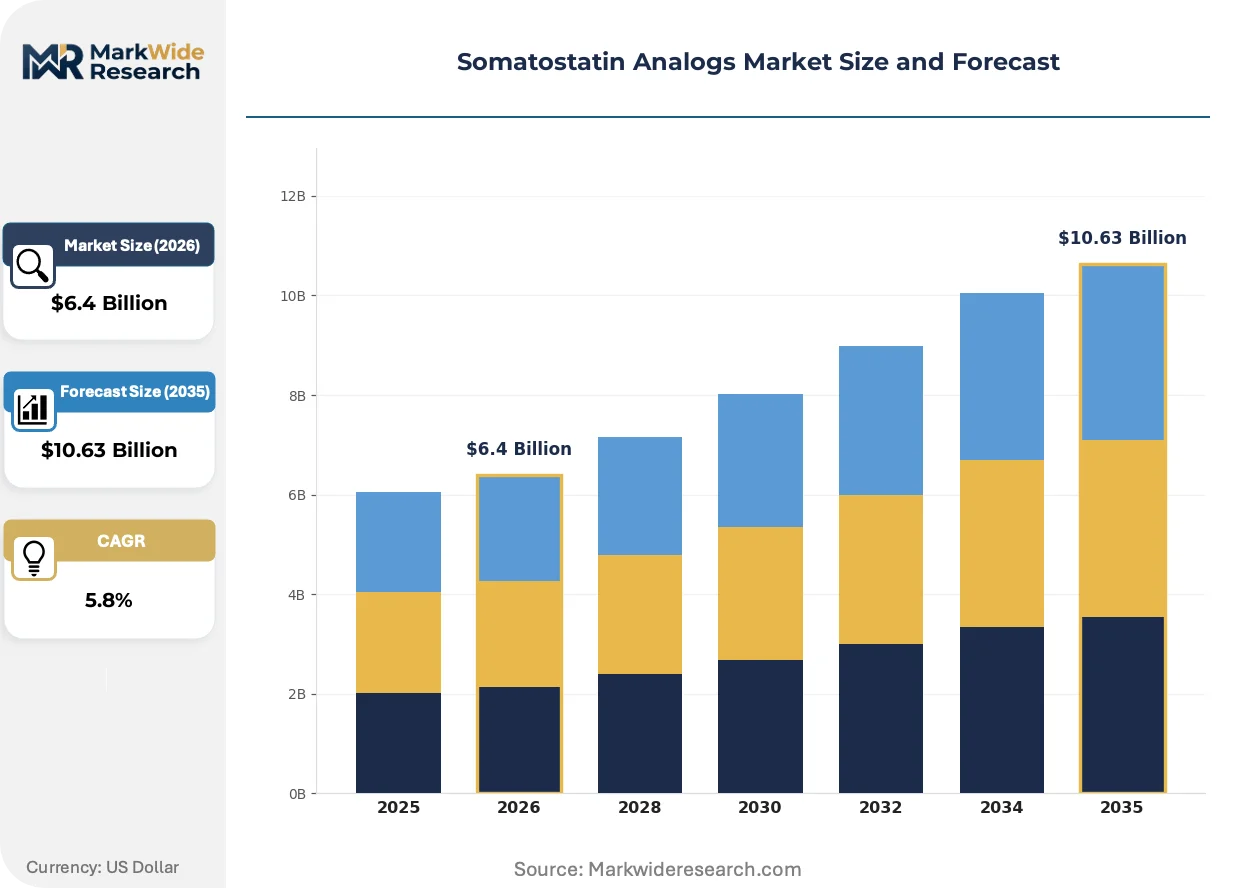
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Octreotide, Lanreotide, Pasireotide, Vapreotide Therapy Area: Acromegaly, Neuroendocrine Tumors, Cushing's Disease, Gastrointestinal Disorders End User: Specialty Clinics, Hospital Pharmacies, Oncology Centers, Research Institutes Delivery Mode: Injection, Implant, Depot, Extended-release Formulation |
| Companies Covered | Teva Pharmaceuticals Ltd, Camurus AB, Novartis AG, Fresenius Kabi, Peptron Inc., Ipsen Pharma, Sun Pharmaceutical Industries Ltd, Merck & Co., Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Somatostatin Analogs Market Strategic Shifts & Innovations
Innovation is centered on enhancing patient quality of life through advanced drug delivery systems and managing the product lifecycle against emerging biosimilar competition. This evolution prioritizes convenience and therapeutic efficacy, reshaping how these chronic conditions are managed over the long term.
Long-acting release (LAR) technologies, delivered via depot injections, provide a sustained therapeutic effect over weeks or months. Endocrinologists and oncologists are rapidly adopting these formulations for managing chronic conditions like acromegaly and neuroendocrine tumors. The reduced dosing frequency, from daily to monthly or quarterly, is displacing older, short-acting subcutaneous injections that require more frequent administration.
Regulatory frameworks for biosimilars, established by the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA), are altering the competitive environment. These pathways enable lower-cost biologic alternatives to enter the market after originator patents expire, increasing price competition. The octreotide segment is the most impacted, compelling innovators to focus on patent-protected, next-generation molecules and new indications.
A distinct migration of care delivery is occurring away from general hospital settings. This movement favors specialized, high-volume endocrinology and oncology centers that have the diagnostic tools and expertise to manage complex therapies for rare diseases. This concentration of care is most advanced in North America and Europe, where it streamlines patient monitoring and administration of specialized injectable drugs.
Somatostatin Analogs Market Segmentation
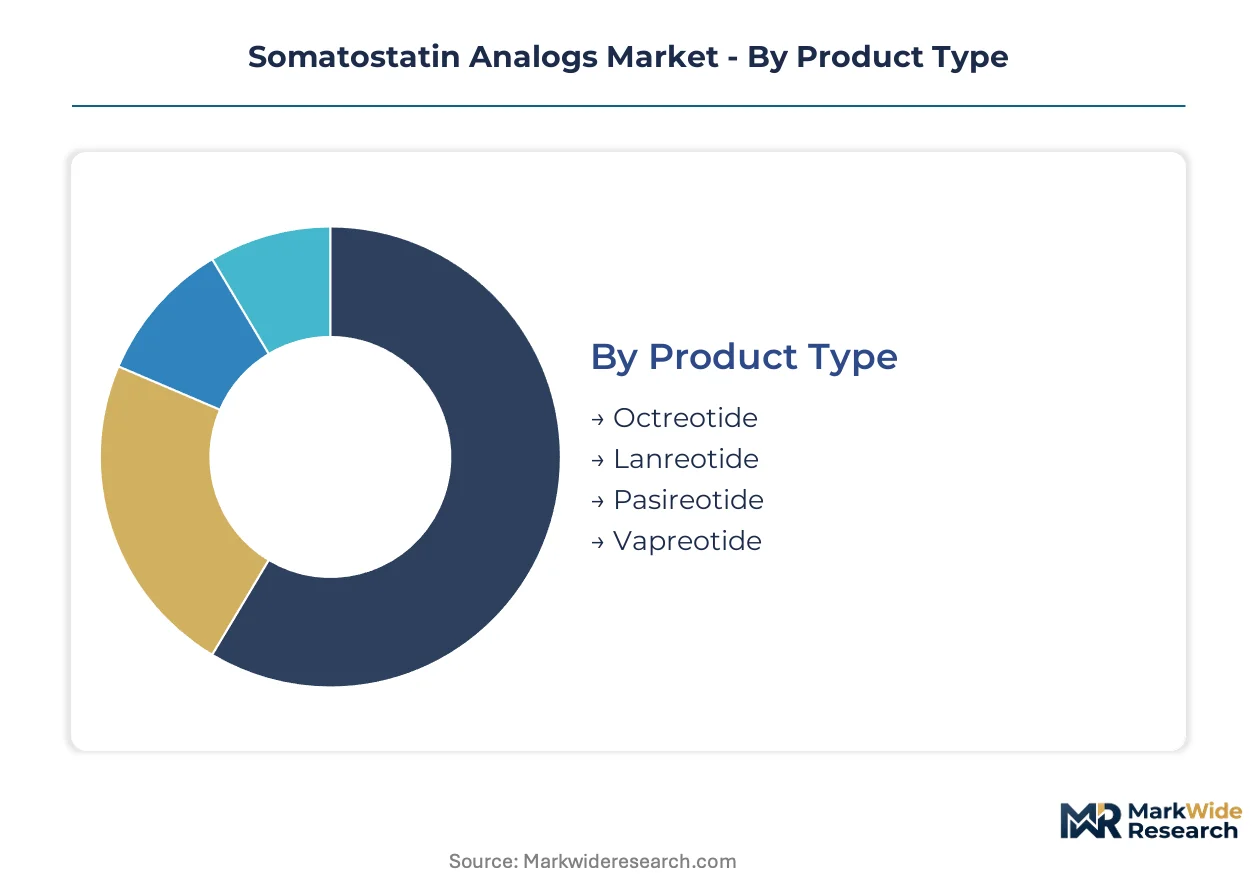
Understanding the somatostatin analogs market through segmentation reveals distinct value pools and demand drivers for different product types and therapy areas. This granular view helps stakeholders identify where innovation and market access strategies yield the highest returns. Analyzing end-user shifts and delivery modes further clarifies evolving patient needs and commercial priorities.
Product Type:
Margin pools within product types are heavily influenced by patent protection and formulation complexity, favoring novel long-acting therapies.
- Lanreotide:This synthetic octapeptide binds to SSTR2 and SSTR5, inhibiting growth hormone secretion and tumor growth. Demand is concentrating in Europe and North America, driven by its long-acting release formulations which enhance patient convenience for chronic conditions.
- Pasireotide:A multireceptor-targeting somatostatin analog, pasireotide exhibits high affinity for SSTR1, 2, 3, and 5. Its demand for Cushing's disease treatment is expanding in specialized endocrinology centers, supported by its efficacy in reducing cortisol levels.
- Octreotide:This first-generation synthetic somatostatin analog primarily targets SSTR2, providing effective symptom control.
- Vapreotide:A synthetic somatostatin analog, vapreotide is typically used for acute variceal bleeding and other gastrointestinal conditions.
Octreotide holds installed capacity. Lanreotide is rotating up the share rankings.
Therapy Area:
The cost tier for somatostatin analog therapies varies significantly based on disease complexity and required treatment duration, with neuroendocrine tumors often representing the highest burden.
- Neuroendocrine Tumors:These therapies manage hormone-producing tumors by inhibiting aberrant hormone secretion and tumor proliferation through SSTR binding. Demand for treatment is expanding in China, driven by increasing diagnostic rates and access to specialized oncological care.
- Acromegaly:Somatostatin analogs reduce elevated growth hormone and IGF-1 levels in acromegaly patients, alleviating symptoms and normalizing hormone profiles. Adoption is high in countries with established reimbursement policies, such as Germany and France, due to improved patient outcomes.
- Cushing's Disease:This therapy area focuses on reducing excessive cortisol production, often with pasireotide for patients unsuitable for or failing surgery.
- Gastrointestinal Disorders:Somatostatin analogs are used to manage symptoms like refractory diarrhea and fistulas in various gastrointestinal conditions.
Neuroendocrine Tumors are gaining share fastest. Acromegaly therapies are also expanding significantly.
End User:
The application of somatostatin analogs is increasingly concentrated in specialized settings that possess the necessary diagnostic and administrative infrastructure for complex therapies.
- Oncology Centers:These facilities provide integrated care for cancer patients, including advanced diagnostics, chemotherapy, and specialized drug administration. Demand is concentrating here as neuroendocrine tumor management becomes more sophisticated, requiring multidisciplinary teams.
- Specialty Clinics:These outpatient facilities focus on specific medical conditions like endocrinology or gastroenterology, offering tailored treatment plans. Patient compliance improves with long-acting formulations administered in these settings, particularly in countries like the United States.
- Hospital Pharmacies:These pharmacies manage the procurement, storage, and dispensing of medications within hospital systems, including somatostatin analogs for inpatient and outpatient use.
- Research Institutes:These entities conduct clinical trials and fundamental research into new somatostatin analog formulations and indications, driving future market innovations.
Oncology Centers are on the steepest expansion trajectory. Specialty Clinics are also experiencing substantial growth.
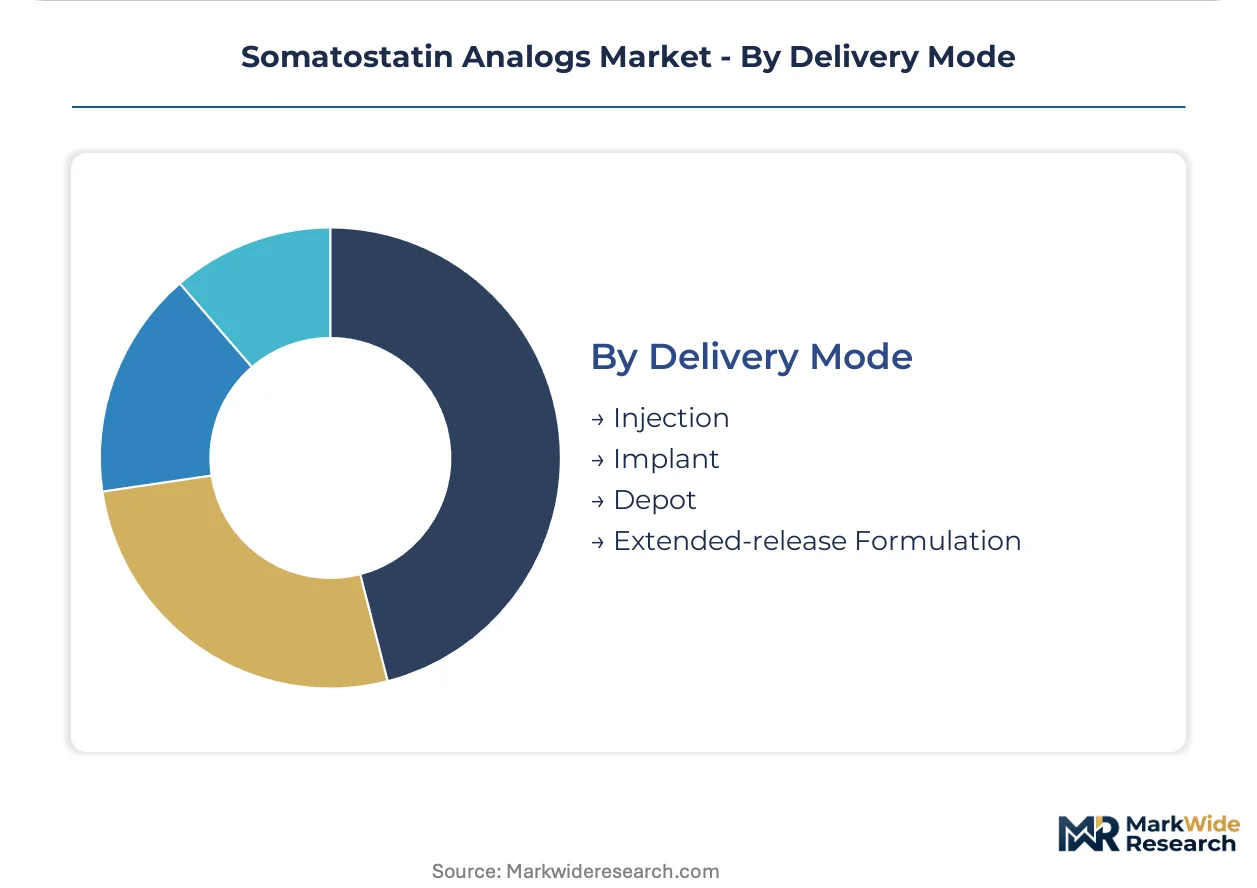
Delivery Mode:
Volume in delivery modes is shifting towards methods that prioritize patient convenience and sustained therapeutic effect, reducing the burden of frequent administration.
- Depot:This delivery mode involves an intramuscular or subcutaneous injection that slowly releases the active pharmaceutical ingredient over several weeks or months. Its demand is high in North America and Europe due to improved patient adherence and reduced dosing frequency for chronic conditions.
- Extended-release Formulation:These formulations are designed to release the drug over an extended period, maintaining therapeutic levels and reducing the need for frequent dosing. Adoption is growing in markets like Japan, where patient convenience is a significant factor in treatment choice.
- Injection:Standard injectable formulations require more frequent administration, typically daily or multiple times per day, often for acute conditions.
- Implant:This delivery method involves surgically placing a device that continuously releases the drug over an extended period, offering long-term treatment.
Depot delivery modes are climbing fastest. Extended-release Formulations are also seeing significant uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The somatostatin analogs market sees significant trade flows, particularly with innovations from European pharmaceutical hubs reaching North American and Asian markets. Specialized oncology treatments and long-acting formulations drive this global exchange, meeting expanding patient needs across continents.
United States
The United States represents a primary demand center for somatostatin analogs, driven by a large patient population with neuroendocrine tumors and acromegaly. US FDA approvals for novel long-acting formulations provide critical market access for innovators. Boston's biotech cluster actively contributes to research and development in this therapeutic area.
Germany
Germany's robust healthcare system supports high adoption rates for somatostatin analogs, particularly for acromegaly due to established reimbursement policies. European Medicines Agency (EMA) approvals facilitate market entry for advanced therapies across the region. Specialized oncology centers in Munich and Frankfurt drive clinical expertise and patient access.
China
China's rapidly expanding healthcare access and rising diagnostic rates fuel significant demand for somatostatin analogs, especially for neuroendocrine tumor treatment. China's NMPA is streamlining approvals for innovative and essential medicines, improving patient availability. Specialized oncological care centers in Shanghai and Beijing are critical for administering these complex therapies.
Japan
Japan prioritizes patient convenience, driving uptake of extended-release somatostatin analog formulations for chronic conditions. The PMDA's rigorous approval process ensures high-quality and effective treatments reach the market. Advanced medical facilities in Tokyo and Osaka are at the forefront of adopting these innovative delivery systems.
India
India presents a significant growth vector for both branded and generic somatostatin analogs, supported by a rising burden of chronic diseases. CDSCO regulations are evolving to facilitate the entry of specialized therapies and biosimilars. Hyderabad and Mumbai are emerging as key hubs for pharmaceutical manufacturing and specialty clinics.
Somatostatin Analogs Market Key Industry Players
Player mix skews toward established pharmaceutical innovators and an expanding segment of generic manufacturers. The market exhibits a tiered structure, with a few large players dominating the branded long-acting formulations and a growing number of companies entering the biosimilar space. Strategic archetypes include R&D-intensive pioneers focusing on novel mechanisms, biosimilar developers challenging existing market share, and regional access providers. Portfolio diversification into new indications and geographic expansion into underpenetrated markets are common competitive moves.
Within the innovator tier, Novartis AG exemplifies a large pharmaceutical corporation with a deep R&D pipeline and established brand presence in somatostatin analogs. This company maintains a strong focus on advanced therapeutic solutions. Ipsen Pharma, conversely, represents a specialized player focused on lanreotide-based therapies and advanced delivery systems, emphasizing patient convenience. Sun Pharmaceutical Industries Ltd. occupies a position as a significant generic manufacturer, expanding access through its offerings in multiple countries and addressing cost-sensitive markets. These players collectively shape the market's competitive dynamics.
| Leading Market Players |
|---|
| Teva Pharmaceuticals Ltd |
| Camurus AB |
| Novartis AG |
| Fresenius Kabi |
| Peptron Inc. |
| Ipsen Pharma |
| Sun Pharmaceutical Industries Ltd |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
US FDA approvals for novel long-acting formulations gate both market entry for specialized somatostatin analogs and influence pricing power. These stringent regulatory pathways ensure product quality while allowing innovators to command premium pricing.
Pricing Analysis
The pricing gap between mature octreotide products and novel long-acting lanreotide formulations defines current market dynamics. Value-based pricing models dominate for advanced somatostatin analogs, reflecting their therapeutic efficacy and improved patient convenience. Price differentiation stems from regulatory approvals for new indications and the brand premium associated with innovator products like Novartis AG's offerings. Pricing softness runs through the octreotide segment due to biosimilar entry, compelling healthcare systems with limited reimbursement to favor these lower-cost alternatives. Specialized oncology centers, however, exhibit lower price sensitivity for advanced long-acting formulations.
Supply Chain Analysis
Cold chain logistics costs for long-acting somatostatin analogs add complexity, particularly across long-haul trade lanes to emerging markets. Manufacturing of synthetic peptides concentrates in specialized facilities across Europe, India, and China, drawing from a limited pool of expertise. Raw material dependencies include highly purified synthetic peptides and specialized excipients for controlled release formulations. A structural risk involves the complex manufacturing processes required, creating potential single-source vulnerabilities for specific advanced molecules. Distribution runs through specialized pharmaceutical distributors directly to oncology and endocrinology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense as incumbents navigate the increasing threat from biosimilars entering the octreotide segment. Protecting market share necessitates strategic investments in next-generation therapies and delivery systems.
For Market Incumbents: Fortify patent portfolios around novel long-acting formulations and new indications to counter biosimilar erosion. Invest heavily in R&D for non-injectable delivery systems, leveraging a deep R&D pipeline for lifecycle management. Expand geographic reach into underpenetrated markets like Brazil, utilizing established distribution channels. This proactive approach defends against margin pressure from generic competition in mature product segments.
For New Entrants and Emerging Players: Patient compliance support services represent a service-layer gap where incumbents under-serve, especially for complex injectable therapies. Target the generic octreotide segment in cost-sensitive markets like India through competitive pricing and broad distribution. Focus on developing biosimilars with improved patient administration features to gain market share. A direct-to-clinic distribution model can streamline access and reduce overhead for emerging players.
For Investors and Strategic Acquirers: US FDA orphan drug designations reshape the acquisition landscape, offering attractive market exclusivity and development incentives. The long-term viability of this market remains strong, driven by increasing diagnostic rates for chronic conditions. Target specialty pharmaceutical companies with advanced R&D pipelines in novel delivery systems or multireceptor-targeting analogs. The signal to watch is the approval rate for non-injectable somatostatin analog formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification into Novel Analogs | This move expands therapeutic options beyond SSTR2, targeting a broader range of neuroendocrine tumor subtypes. |
| Development of Oral Formulations | Oral delivery systems significantly improve patient convenience and adherence for chronic acromegaly management. |
| Geographic Expansion in Emerging Markets | Expanding into China and Brazil leverages rising diagnostic rates and increasing access to specialized oncological care. |
| Strategic Partnerships for Biosimilar Development | Collaborations enable faster market entry for lower-cost alternatives, addressing patent expiry of octreotide. |
| Investment in Advanced Drug Delivery Technology | This focus enhances sustained therapeutic effects, reducing dosing frequency for neuroendocrine tumor patients. |
Research Approach
A spread of perspectives from oncology key opinion leaders, pharmaceutical R&D executives, hospital formulary directors, and regulatory affairs specialists converged on the working assumptions for this analysis. Primary interviews were triangulated with extensive secondary validation from sources including US FDA filings, EMA submissions, and specialized medical journal databases. This approach ensures robust data integrity through both bottom-up market insights and top-down industry trends.
Product type, therapy area, end-user, and delivery mode formed the core segmentation dimensions modeled across the analysis window. The analytical framework integrated historical sales data with projected patient populations and treatment adoption rates. Compound Annual Growth Rates were derived from a multi-variant regression model incorporating regulatory approval timelines and biosimilar entry forecasts. Future value projections consider the impact of novel long-acting formulations on market share.
Material uncertainties — unforeseen regulatory shifts, major clinical trial failures, or disruptive non-analog therapies — sit outside the modeled envelope. Forecasts reflect current market dynamics and known pipeline developments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Rhu Albumin Market