
 Tamoxifen Market | 2026-2036
Tamoxifen Market Size, Share, and Industry Trends Forecast 2026-2036
Tamoxifen Market Outlook
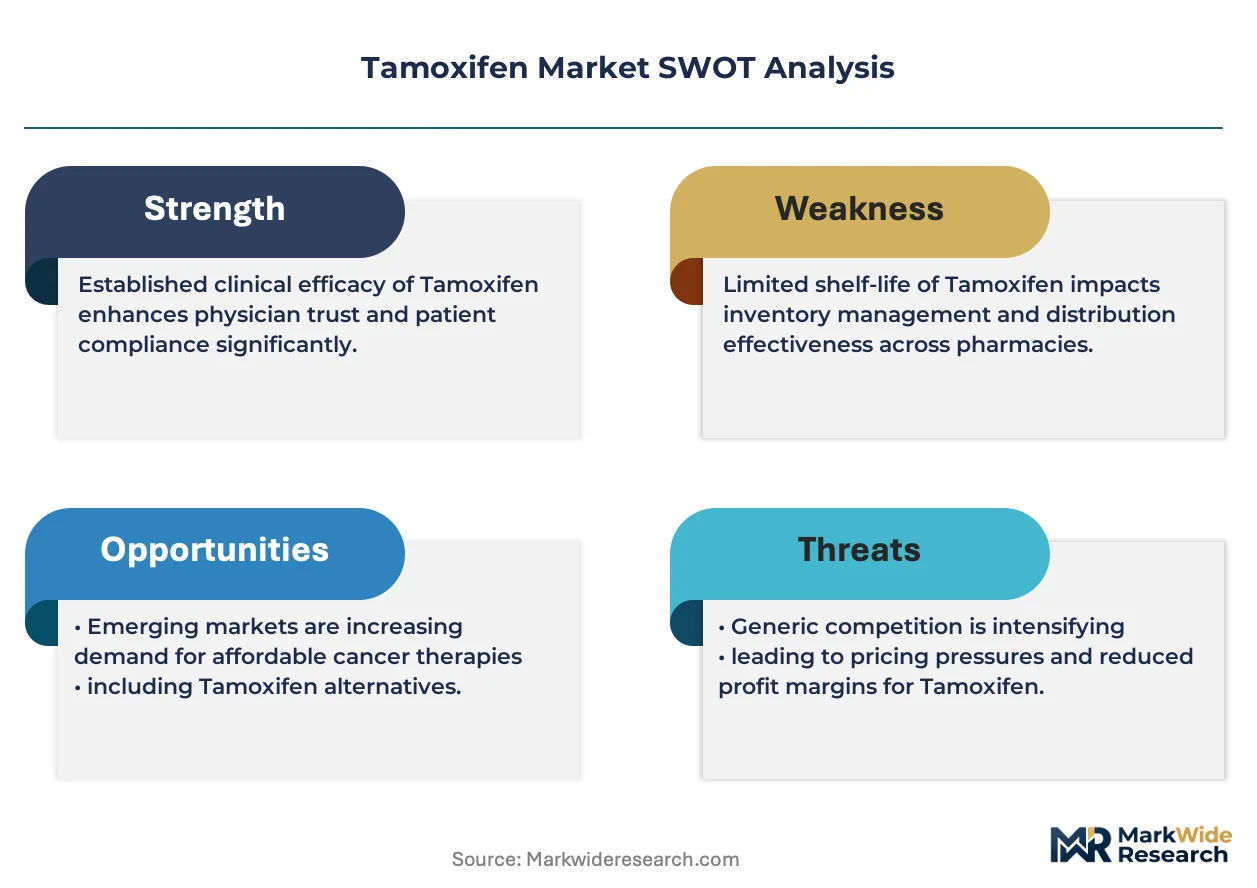
USP-grade tamoxifen citrate specifications is rotating toward higher-purity API requirements as oncology formulators tighten impurity thresholds. AstraZeneca plc leverages its original research heritage to sustain brand loyalty among oncologists prescribing adjuvant protocols. Teva Pharmaceutical Industries Ltd anchors the generic segment through manufacturing scale across multiple production sites. Sun Pharmaceutical Industries Ltd differentiates via cost-optimized tablet formulations that compete aggressively in price-sensitive markets.
Tamoxifen is a selective estrogen receptor modulator (SERM) synthesized as the citrate salt, typically dosed at 10 mg or 20 mg for oral administration, functioning as a competitive antagonist at estrogen receptor sites in breast tissue. The compound serves as a foundational pharmaceutical for hormone receptor-positive breast cancer management across both curative and palliative settings. Tablet formulations dominate procurement volumes across hospital pharmacies due to stability and dosing precision, while injectable presentations capture specialized neoadjuvant therapy applications where bioavailability timing matters. Homecare distribution channels represent the fastest-expanding access point as oral anti-hormonal protocols shift administration away from institutional settings.
FDA bioequivalence standards and EMA's Good Manufacturing Practice inspections jointly enforce quality benchmarks that determine which manufacturers gain commercial access. India's CDSCO aligns with these frameworks through tightened API import testing protocols that filter substandard suppliers. The WHO Essential Medicines List inclusion sustains procurement priority for tamoxifen within national cancer programs. Stakeholders must monitor evolving pharmacovigilance requirements for generic SERMs as regulators tighten post-market surveillance obligations.
Market Dynamics
FDA bioequivalence enforcement for generic oncology drugs is compressing formulation margins while specialty clinics absorb administration volumes previously handled by hospital infusion centers.
Growth Catalysts
- USP-grade API specifications:Oncology formulators are tightening impurity thresholds for tamoxifen citrate, pulling demand toward certified high-purity suppliers.
- Homecare administration protocols:Oral anti-hormonal therapies are shifting patient management away from institutional settings into supervised home environments.
- CDSCO import testing alignment:India's tightened API verification protocols are filtering substandard suppliers and consolidating procurement toward compliant manufacturers.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters heavily in Indian and Chinese chemical manufacturing zones, exposing buyers to geopolitical friction.
- EMA inspection backlog:Extended Good Manufacturing Practice audit timelines delay facility certifications and compress launch windows for new entrants.
- Aromatase inhibitor substitution:Anastrozole and letrozole protocols displace tamoxifen in certain adjuvant settings among post-menopausal patient cohorts.
Strategic Opportunities
- Sub-Saharan Africa procurement gaps:WHO Essential Medicines List inclusion positions tamoxifen for national cancer program tenders in underpenetrated markets.
- Specialty clinic channel expansion:Community-based oncology hubs are capturing prescription volumes through integrated care models.
- Pharmacovigilance data monetization:Post-market surveillance obligations create revenue streams for adverse event monitoring services.
Industry Challenges
- Chromatography analyst shortage:Impurity profiling for USP-grade certification requires specialized analytical chemistry expertise that outpaces training pipeline output.
- Legacy ERP integration:Track-and-trace serialization mandates force compatibility upgrades across multi-site manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamoxifen Market |
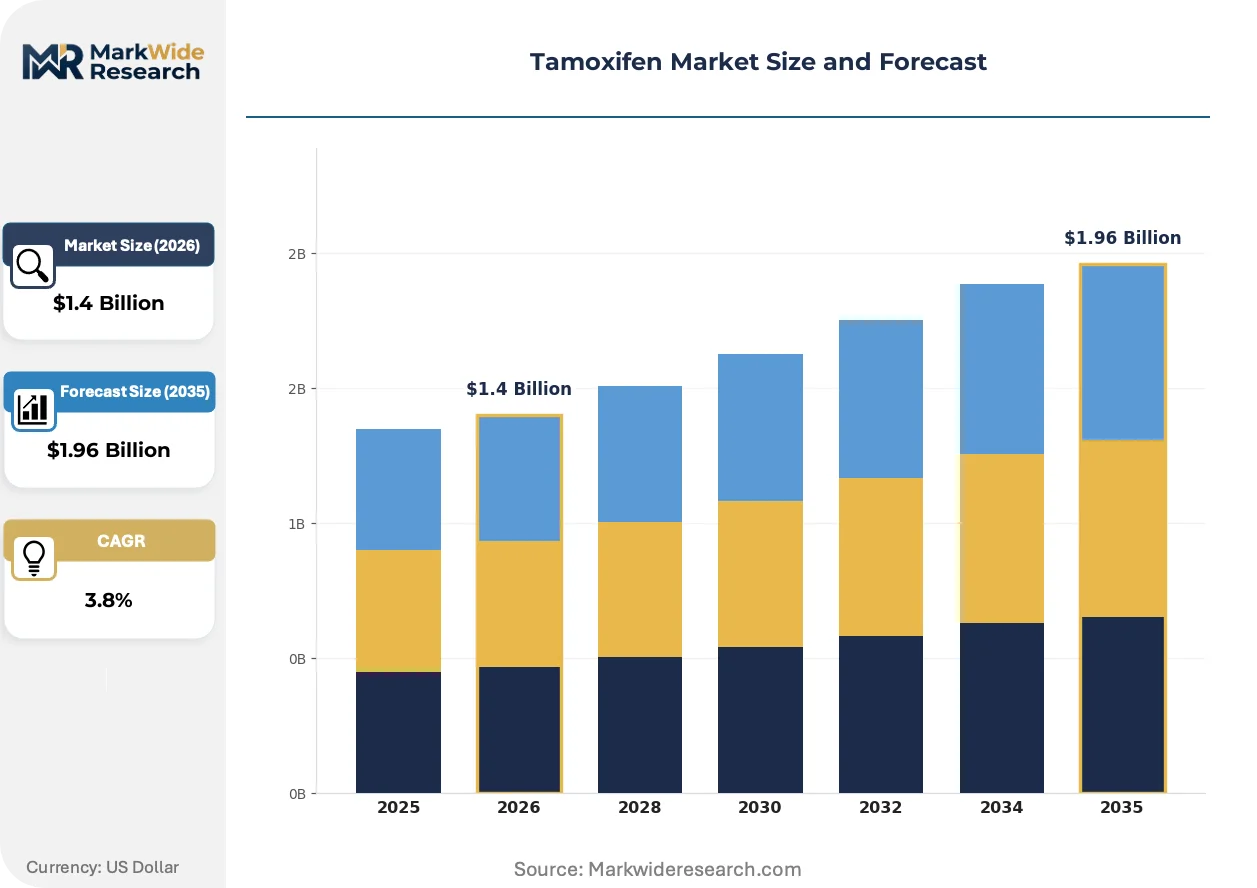
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Oral Solution End User: Hospitals, Specialty Clinics, Outpatient Facilities, Homecare Therapy Area: Breast Cancer, Anti-hormonal Treatment, Neoadjuvant Therapy, Adjuvant Therapy Distribution Channel: Pharmacies, Hospital Pharmacies, Online Stores, Wholesale Distributors |
| Companies Covered | AstraZeneca plc, Teva Pharmaceutical Industries Ltd, Pfizer Inc, Mylan N.V, Novartis AG, Sun Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, Cipla Limited, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamoxifen Market Strategic Shifts
Continuous manufacturing technologies are disrupting batch-production economics in oral solid dose formulation, while regulatory data integrity requirements reshape quality assurance staffing models.
Hot-melt extrusion for tamoxifen citrate tablet production is fragmenting traditional wet-granulation capacity investments. Contract development and manufacturing organizations in India and Germany are adopting twin-screw extrusion lines to compress processing times. This technology is fragmenting the competitive map by enabling smaller batch runs with faster changeover.
EMA's revised Good Manufacturing Practice Annex 1 for sterile products is forcing contamination control strategy overhauls across European manufacturing sites. Facilities must document risk assessments for viable and non-viable particle sources. Injectable tamoxifen presentations face heightened environmental monitoring requirements that extend validation timelines.
Hospital pharmacy procurement committees are consolidating supplier lists to reduce vendor management overhead. Oncology drug purchasing groups in the United States now require three-year pricing commitments with inflation caps. This concentration is visible most acutely in integrated delivery networks across Texas and Florida.
Tamoxifen Market Segmentation
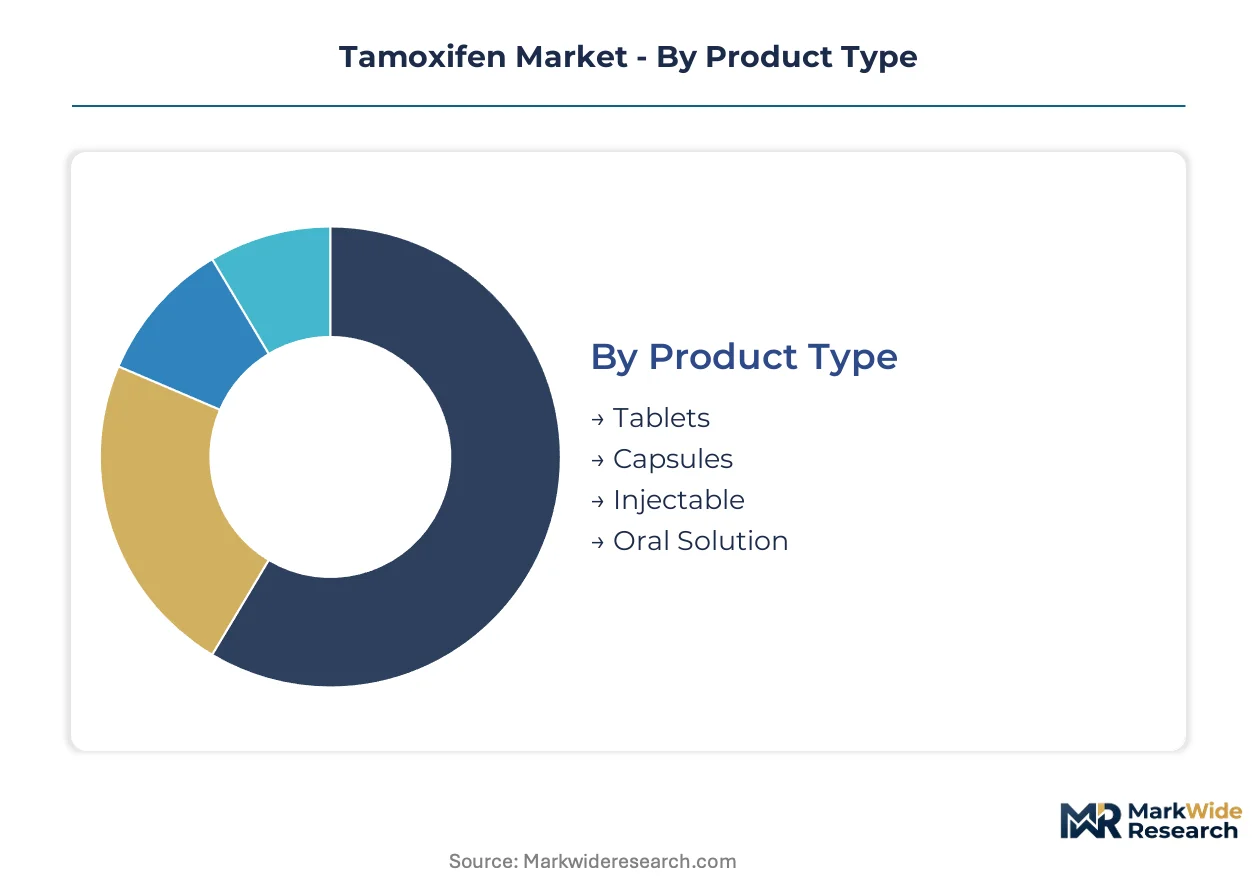
Tamoxifen procurement patterns diverge sharply across administration settings and formulation types. Manufacturers calibrate production capacity against channel-specific bioequivalence requirements and dosing protocol preferences.
Product Type:
Margin pools concentrate in tablet formulations where manufacturing scale and FDA bioequivalence certification create defensible positions for established suppliers.
- Tablets:Oral solid dose at 10 mg and 20 mg strengths dominates hospital pharmacy procurement volumes. USP-grade citrate salt specifications with tight impurity thresholds pull demand toward certified high-purity API suppliers in India and Germany.
- Capsules:Gelatin and HPMC shell alternatives serve patients with tablet swallowing difficulties. Demand concentrates in outpatient facilities across the United States where formulary flexibility permits therapeutic substitution.
- Injectable:Intravenous presentations capture neoadjuvant protocols requiring precise bioavailability timing. EMA's revised Annex 1 contamination control requirements extend validation timelines for European manufacturing sites.
- Oral Solution:Liquid formulations address pediatric and geriatric dosing precision needs. CDSCO import testing alignment filters substandard API suppliers from Indian procurement channels.
Tablets hold installed capacity. Injectable presentations are rotating up the share rankings as specialty clinics adopt neoadjuvant protocols.
End User:
Volume concentration tracks the migration of anti-hormonal administration from institutional settings toward supervised community-based care.
- Hospitals:Academic medical centers and integrated delivery networks anchor adjuvant therapy initiation. Texas and Florida oncology purchasing groups now require three-year pricing commitments with inflation caps.
- Specialty Clinics:Community-based oncology hubs capture prescription volumes through integrated care models. These facilities absorb administration volumes previously handled by hospital infusion centers.
- Outpatient Facilities:Ambulatory surgery centers and infusion suites handle intermittent monitoring for stable patients. Demand clusters in metropolitan areas with established breast cancer screening programs.
- Homecare:Supervised oral administration protocols are expanding most quickly as payors favor reduced institutional utilization. Home nursing services manage adherence monitoring for extended adjuvant courses.
Hospitals retain protocol initiation authority. Homecare is climbing the fastest as reimbursement shifts favor non-institutional settings.
Therapy Area:
Clinical positioning determines API purity requirements and regulatory documentation burdens across the citrate salt supply base.
- Breast Cancer:Hormone receptor-positive disease management anchors tamoxifen demand across curative and palliative settings. WHO Essential Medicines List inclusion sustains procurement priority within national cancer programs.
- Anti-hormonal Treatment:Competitive estrogen receptor antagonism defines mechanism-of-action positioning. Aromatase inhibitor substitution in post-menopausal cohorts constrains volume expansion in this segment.
- Neoadjuvant Therapy:Pre-surgical cytoreduction protocols favor injectable presentations where bioavailability timing matters. Specialty clinics drive demand concentration for this application.
- Adjuvant Therapy:Extended oral administration for five to ten years post-surgery generates recurring prescription volumes. Homecare channels capture the majority of maintenance dosing.
Adjuvant therapy holds installed capacity. Neoadjuvant protocols are gaining share fastest as neoadjuvant trial data reshapes practice patterns.
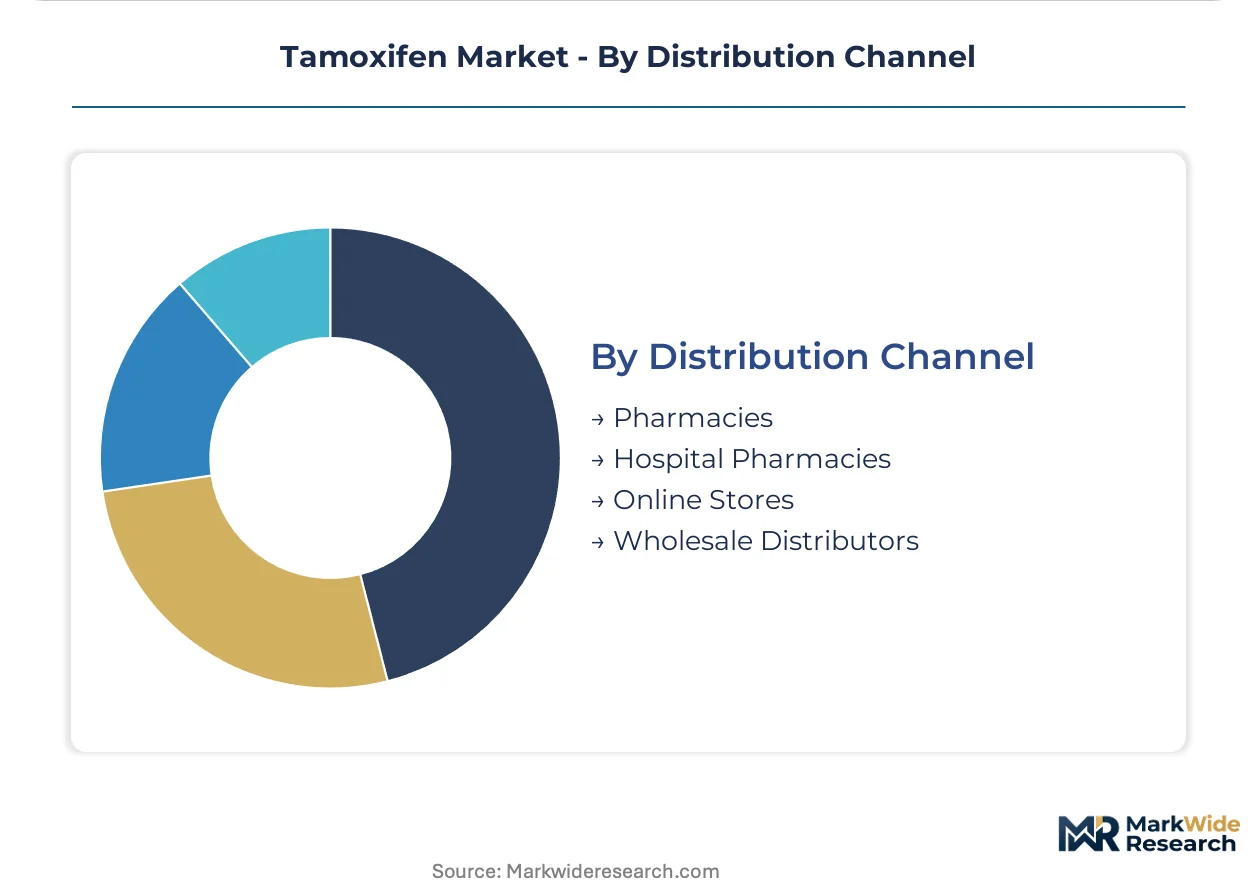
Distribution Channel:
Channel selection reflects inventory velocity requirements and serialization compliance investments across multi-site manufacturing networks.
- Pharmacies:Community retail and specialty pharmacy networks handle oral prescription fulfillment. Track-and-trace mandates force ERP compatibility upgrades across wholesale relationships.
- Hospital Pharmacies:Formulary committees consolidate supplier lists to reduce vendor management overhead. Procurement concentration is visible most acutely in integrated delivery networks.
- Online Stores:Mail-order and digital pharmacy platforms expand access for maintenance therapy patients. FDA bioequivalence enforcement for generic oncology drugs shapes permissible sourcing.
- Wholesale Distributors:Three-tier distribution networks manage cold chain and controlled substance requirements. Legacy ERP integration challenges filter smaller manufacturers from approved vendor lists.
Hospital pharmacies hold installed capacity. Online stores are rotating up the share rankings as oral maintenance protocols extend treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for tamoxifen citrate diverges sharply across geographies. United States buyers absorb premium pricing for FDA-certified formulations, while Indian and Chinese procurement channels prioritize cost-optimized generic sourcing.
United States
Breast cancer screening programs in Texas and Florida sustain consistent prescription volumes through integrated delivery networks. FDA bioequivalence enforcement for generic oncology drugs compresses formulation margins while consolidating supplier lists. Oncology purchasing groups in the Southwest now require three-year pricing commitments with inflation caps.
Germany
EMA's revised Good Manufacturing Practice Annex 1 extends validation timelines for sterile injectable presentations. German chemical manufacturing clusters in the Rhine-Ruhr region anchor high-purity API production for European formulators. Bavaria-based contract manufacturers are adopting continuous processing technologies to compress batch-production economics.
India
CDSCO tightened API import testing protocols filter substandard suppliers from domestic procurement channels. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate citrate salt production capacity. Mumbai-based formulators compete aggressively in price-sensitive African and Southeast Asian export markets.
China
NMPA alignment with international GMP standards shapes facility certification requirements for oncology API producers. Yangtze River Delta chemical clusters supply intermediate compounds to Indian and European formulators. Shanghai-based manufacturers face heightened environmental monitoring obligations under MEE dual carbon implementation timelines.
Brazil
ANVISA regulatory harmonization with FDA bioequivalence frameworks determines generic oncology drug market access. São Paulo specialty clinics absorb administration volumes previously handled by hospital infusion centers. Minas Gerais manufacturing investments target regional supply security for hormone receptor-positive breast cancer protocols.
Tamoxifen Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the tamoxifen citrate value chain. The market structure concentrates around three strategic tiers: originator heritage brands, scale-driven generic manufacturers, and regional cost-optimized formulators. Two dominant competitive moves define current positioning: manufacturing network consolidation across multiple production sites, and specialty clinic channel partnerships that capture prescription volumes from institutional settings.
Among originator heritage players, AstraZeneca plc occupies a position sustained by adjuvant protocol loyalty among prescribing oncologists. Teva Pharmaceutical Industries Ltd and Sun Pharmaceutical Industries Ltd exemplify the scale-driven generic archetype, with the former anchoring manufacturing breadth and the latter representing cost-optimized tablet formulation specialization for price-sensitive markets.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Mylan N.V |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| Cipla Limited |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
FDA bioequivalence certification gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified manufacturers while rewarding certified producers with hospital formulary access and multi-year contract eligibility. USP-grade API specifications create tiered purchasing power across oncology procurement committees in Texas and Florida integrated delivery networks.
Pricing Analysis
After-market pharmacovigilance services and extended adverse-event monitoring contracts drive lifetime value for generic SERM manufacturers beyond tablet margins. Three-tier pricing structure across originator heritage brands, FDA-certified generics, and cost-optimized regional suppliers reflects certification grade and manufacturing scale. Pricing pressure stems from aromatase inhibitor substitution in post-menopausal protocols, compressing adjuvant therapy margins. Specialty clinics demonstrate lowest price sensitivity due to protocol loyalty, while Indian export markets exhibit highest sensitivity to per-unit tablet costs.
Supply Chain Analysis
India and China anchor citrate salt API production for global oncology formulators, with Maharashtra and Gujarat manufacturing zones concentrating capacity for price-sensitive export markets. Active pharmaceutical ingredient supply draws from Yangtze River Delta chemical intermediates and Rhine-Ruhr high-purity purification operations. Single-source vulnerability concentrates in Indian API verification protocols filtering substandard suppliers. Distribution runs through three-tier wholesale networks managing hospital pharmacy consolidation and track-and-trace serialization compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital pharmacy procurement committee consolidation, with integrated delivery networks in Texas and Florida reducing approved vendor lists to three-year pricing commitment holders.
For Market Incumbents: Consolidate manufacturing scale across multiple production sites to defend against CDSCO import testing alignment filtering substandard suppliers from Indian procurement channels. Deepen backward integration into citrate salt API production to capture margin compression from FDA bioequivalence enforcement. Prioritize specialty clinic channel partnerships that capture prescription volumes migrating from hospital infusion centers. For New Entrants and Emerging Players: Pharmacovigilance data services represent an under-served layer where incumbents lack dedicated adverse-event monitoring infrastructure. Target sub-Saharan African national cancer program tenders for WHO Essential Medicines List procurement gaps. Deploy hot-melt extrusion continuous manufacturing technology to compress batch-production economics against legacy wet-granulation capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous processing technology adoption in oral solid dose formulation. Five-to-ten year viability favors contract development and manufacturing organizations with twin-screw extrusion line investments and EMA Annex 1 contamination control compliance. Monitor EMA inspection backlog resolution as inflection signal for European manufacturing site certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-site production networks defend FDA bioequivalence certification against CDSCO filtering protocols. |
| Specialty Clinic Partnership | Community-based oncology hubs capture prescription volumes from hospital infusion center migration. |
| Continuous Processing Adoption | Twin-screw extrusion lines compress batch-production economics for oral solid dose tablets. |
| Pharmacovigilance Infrastructure | Post-market surveillance capabilities monetize adverse-event monitoring obligations for generic SERMs. |
| Backward Integration | In-house citrate salt API production captures margin compression from tightening USP-grade impurity thresholds. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with oncology formulators, hospital procurement managers, CDSCO regulatory leads, and specialty clinic administrators; and secondary validation through FDA ANDA filings, EMA GMP inspection records, ClinicalTrials.gov protocol registries, and WHO Essential Medicines List procurement databases. Bottom-up tablet volume estimates and top-down API demand projections were triangulated against customs trade data for citrate salt movements.
Across the projection horizon, analytical frameworks modeled dosage form segmentation, administration route differentiation, patient population cohorts, and regional regulatory clusters. CAGRs were derived from fitted growth curves calibrated to prescription volume trajectories in breast cancer screening program regions and specialty clinic channel expansion rates.
Material uncertainties — API supply concentration in Indian and Chinese manufacturing zones, EMA inspection backlog delays, aromatase inhibitor substitution velocity — sit outside the modeled envelope. Forecasts reflect assumptions about bioequivalence enforcement continuity and homecare protocol reimbursement stability. Recalibration cycles align with material shifts in FDA generic oncology guidance and WHO Essential Medicines List revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market