
 Primary Biliary Cholangitis (PBC) Therapeutics Market | 2026-2036
Primary Biliary Cholangitis (PBC) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Biliary Cholangitis (PBC) Therapeutics Market Analytics
Buyer concentration among hepatology treatment centers is hardening as academic medical centers and large health systems consolidate referrals for complex autoimmune liver conditions. Intercept Pharmaceuticals leverages its first-mover position in bile acid receptor modulation to sustain physician loyalty across major transplant centers. Gilead Sciences anchors its portfolio through integrated virology and hepatology commercial infrastructure that dominates hospital formularies.
Primary Biliary Cholangitis therapeutics encompass pharmaceutical agents targeting autoimmune-mediated destruction of intrahepatic bile ducts, with formulations requiring precise bile acid profiling and sustained-release manufacturing to achieve therapeutic levels without hepatotoxicity. Ursodeoxycholic acid occupies the established standard-of-care position with mature pricing and generic competition, while obeticholic acid and emerging fibrate combinations capture the innovation-driven premium segment where payers demand robust biochemical response data. Specialty pharmacies control the fastest-growing distribution channel as manufacturers navigate limited distribution networks for high-cost immunomodulatory therapies.
FDA orphan drug exclusivity and EMA conditional marketing authorization frameworks shape clinical trial design and commercial launch sequencing for novel PBC therapies. The European F-Gas Regulation and REACH chemical safety standards additionally constrain manufacturing inputs for certain synthetic bile acid derivatives, elevating compliance costs for formulation suppliers. Stakeholders must monitor payer evidence requirements for non-invasive fibrosis biomarkers as these will determine formulary positioning for next-generation therapeutics.
Market Dynamics
Specialty pharmacy networks are consolidating distribution control for high-cost PBC immunomodulators, concentrating patient access decisions among a handful of vertically integrated dispensers with direct hepatology center relationships. This channel compression is reshaping manufacturer go-to-market economics and formulary negotiation leverage across the therapeutic category.
Growth Catalysts
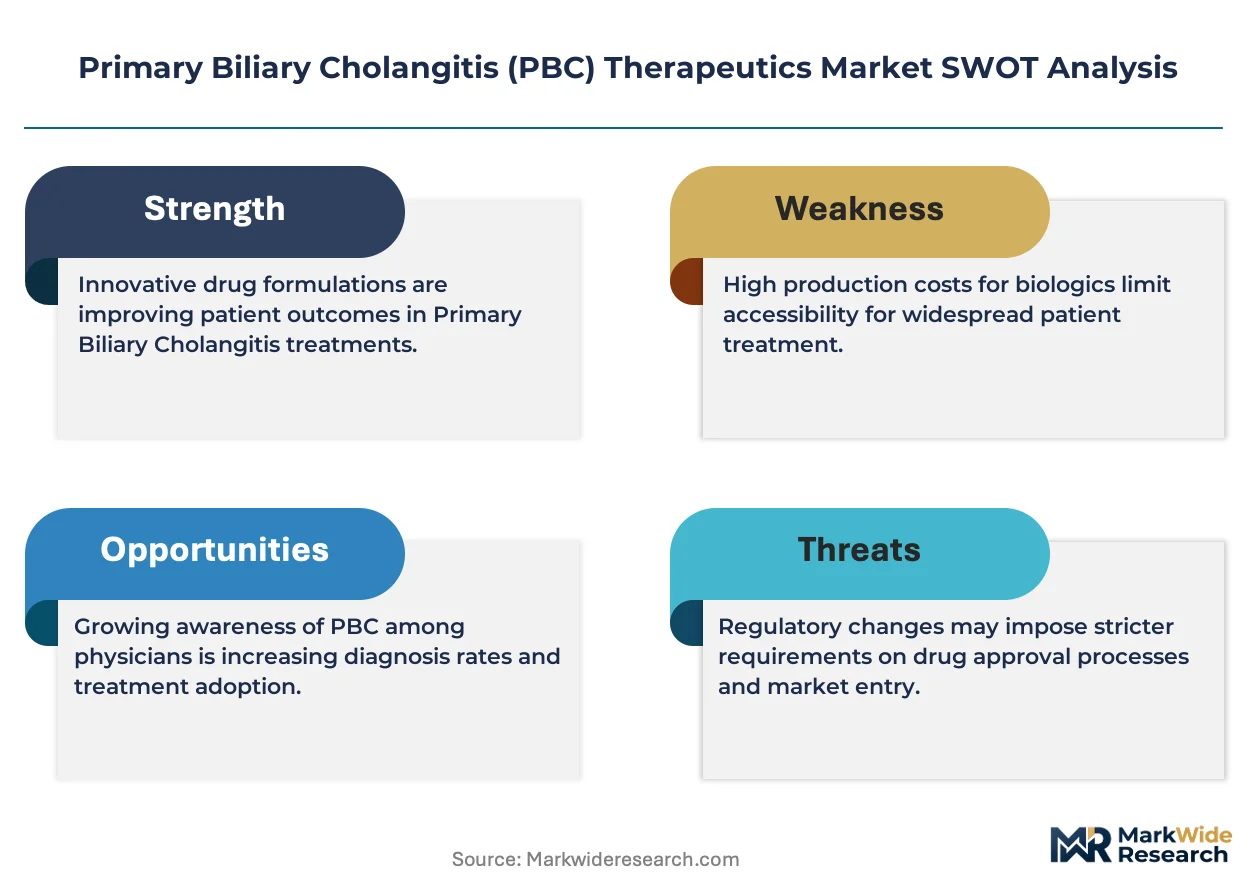
- EMA Conditional Marketing Authorization:The framework accelerates approval timelines for novel bile acid modulators targeting treatment-resistant PBC populations, compressing commercial launch sequencing for European market entry.
- Fibrate combination protocols:Emerging dual-therapy approaches pairing ursodeoxycholic acid with peroxisome proliferator-activated receptor agonists are expanding addressable patient pools beyond first-line responders.
- United States hepatology center concentration:Academic medical center networks in metropolitan clusters drive prescriber loyalty and concentrated reimbursement negotiation power for premium-priced therapies.
Market Restraints
- Generic ursodeoxycholic acid saturation:Mature pricing for the established standard-of-care agent compresses revenue pools and limits pricing headroom for novel mechanisms entering the market.
- European F-Gas Regulation compliance:Synthetic bile acid derivative manufacturing faces elevated input costs and supply security constraints under fluorinated greenhouse gas phase-down mandates.
- Biochemical response biomarker heterogeneity:Lack of standardized non-invasive fibrosis endpoints creates payer evidence requirements that prolong formulary access timelines for next-generation entrants.
Strategic Opportunities
- Japan's aging cirrhosis burden:Underpenetrated diagnosis rates and expanding hepatology infrastructure create whitespace for bile acid receptor modulators in East Asia's most mature pharmaceutical market.
- Specialty pharmacy limited distribution networks:Direct-to-patient hub services with integrated adherence monitoring capture margin and data assets unavailable through traditional wholesale channels.
- FDA Orphan Drug Exclusivity:Seven-year market protection windows incentivize development investment for rare autoimmune liver conditions with defined biochemical response endpoints.
Industry Challenges
- hepatology clinical trial recruitment:Rare disease prevalence and geographic dispersion of qualified treatment centers prolong enrollment timelines and inflate study costs for Phase III programs.
- REACH chemical safety documentation:Synthetic bile acid intermediate suppliers face extended registration timelines and toxicity testing burdens that disrupt active pharmaceutical ingredient supply security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Biliary Cholangitis (PBC) Therapeutics Market |
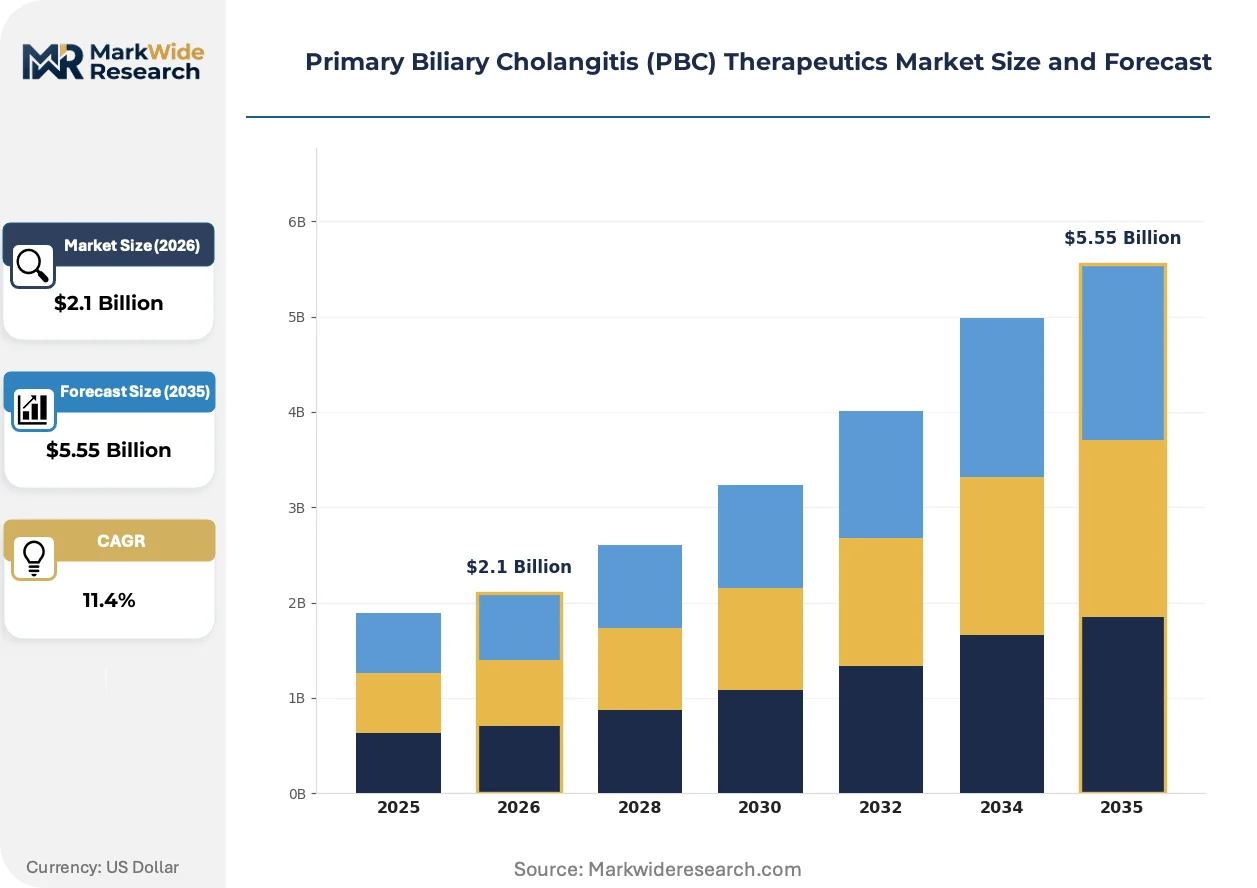
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ursodeoxycholic Acid, Obeticholic Acid, Fibrates, Others Application: Cholestatic Liver Disease, Autoimmune Condition, Hepatobiliary Disorders, Liver Failure End User: Hospitals, Outpatient Clinics, Specialty Pharmacies, Research Institutions Distribution Channel: Direct Sales, Retail Pharmacy, Online Pharmacy, Wholesalers |
| Companies Covered | Intercept Pharmaceuticals, Gilead Sciences, Ipsen, CymaBay Therapeutics, GENFIT, Viatris, AbbVie, Dr Falk Pharma, Mirum Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Biliary Cholangitis (PBC) Therapeutics Market Evolving Landscape
Next-generation bile acid receptor targeting is compressing development timelines while payer evidence requirements harden around non-invasive fibrosis monitoring. These forces are simultaneously expanding therapeutic options and raising commercialization barriers.
Non-invasive elastography and serum biomarker panels are rewriting how hepatology centers stage fibrosis progression and monitor treatment response. Major transplant centers in the United States and Germany are adopting these technologies for routine patient management, compressing reliance on invasive liver biopsy protocols and enabling more frequent therapeutic adjustment cycles.
REACH chemical safety standards and the European F-Gas Regulation are tightening manufacturing compliance requirements for synthetic bile acid derivatives. Formulation suppliers are reconfiguring European production footprints to secure alternative input sources, with contract manufacturers in Switzerland and the United Kingdom capturing displaced volume from continental facilities facing extended registration delays.
Patient assistance programs and hub services are displacing traditional wholesale distribution for high-cost PBC therapies. Specialty pharmacies with integrated adherence monitoring and prior authorization management are capturing the fastest-growing channel share, particularly in United States metropolitan markets where hepatology center concentration enables direct manufacturer-pharmacy contracting relationships.
Primary Biliary Cholangitis (PBC) Therapeutics Market Segmentation
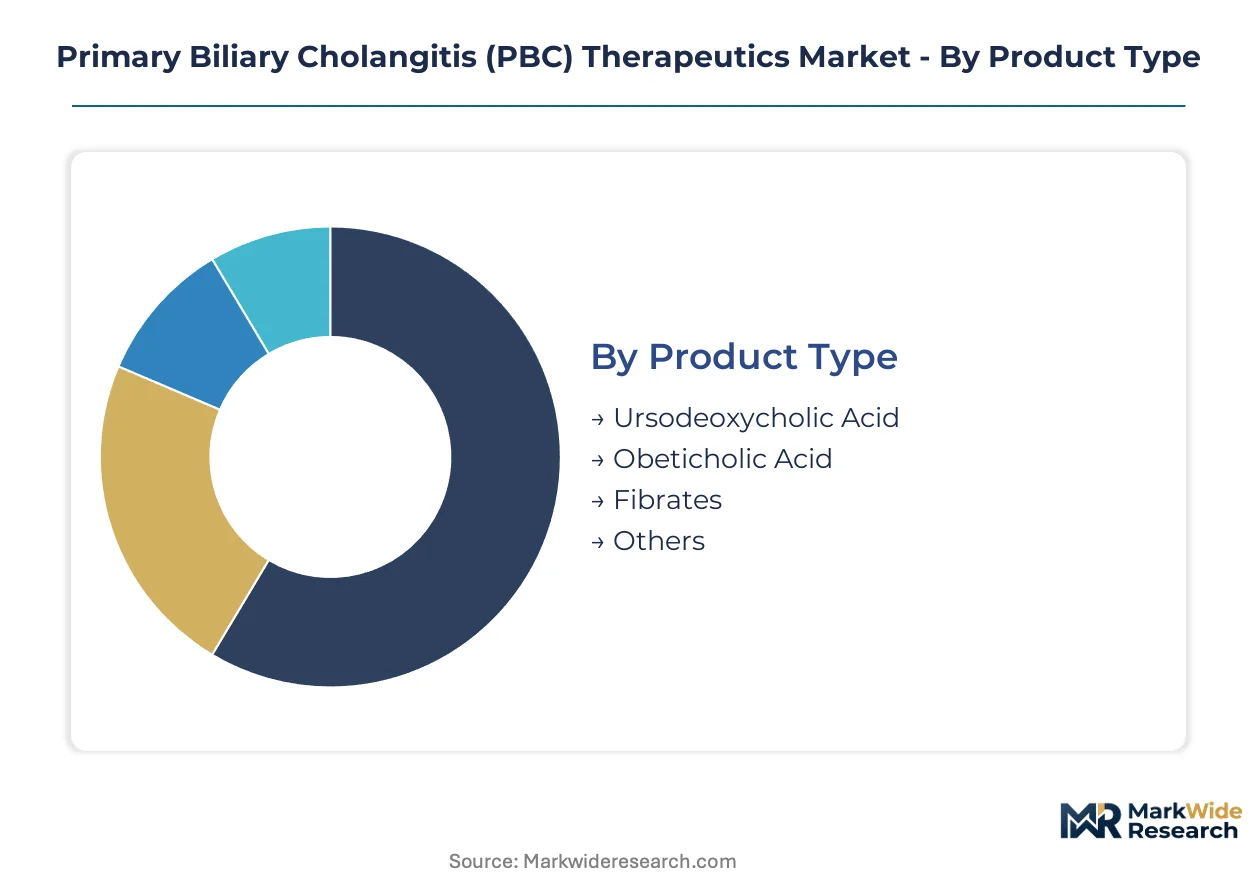
Segmentation in PBC therapeutics reveals how treatment complexity, prescriber concentration, and reimbursement pathways fragment commercial opportunity across distinct buyer and channel configurations. Understanding these divisions exposes where pricing power accumulates and where access barriers constrain market penetration.
Product Type:
Buyers differentiate primarily by biochemical response requirements and tolerance for hepatotoxicity risk, with first-line versus salvage therapy positioning driving distinct procurement behaviors.
- Ursodeoxycholic Acid:The synthetic bile acid derivative normalizes hepatocyte membrane composition and reduces bile acid cytotoxicity through choleretic action. Demand concentrates in United States hepatology centers managing early-stage PBC where generic pricing enables broad formulary inclusion, though biochemical non-response rates of 30-40% among treated patients create pressure for combination protocols.
- Obeticholic Acid:A farnesoid X receptor agonist modulating bile acid synthesis and inflammation pathways with sustained-release formulation requirements. Prescribing clusters at academic medical centers with transplant capabilities in Germany and the United Kingdom where EMA conditional authorization supports premium reimbursement for UDCA-inadequate responders.
- Fibrates:Peroxisome proliferator-activated receptor alpha agonists repurposed from metabolic indications for PBC combination therapy.
- Others:Emerging immunomodulatory agents and novel bile acid receptor modulators in clinical development.
Volume sits with Ursodeoxycholic Acid; growth tilts toward Fibrates as combination protocols expand addressable non-responder populations.
Application:
Clinical staging and fibrosis severity stratify treatment intensity, with prescriber specialization and monitoring infrastructure requirements varying sharply across disease progression states.
- Cholestatic Liver Disease:The core PBC indication involving autoimmune destruction of interlobular bile ducts with elevated alkaline phosphatase and gamma-glutamyl transferase markers. Demand concentrates in metropolitan hepatology networks across the United States and Germany where non-invasive elastography enables frequent therapeutic monitoring without biopsy requirements.
- Autoimmune Condition:Overlapping PBC-autoimmune hepatitis presentations requiring corticosteroid combination management. Treatment centers at Mayo Clinic, Mount Sinai, and Charité Berlin anchor prescriber concentration for these complex cases where misdiagnosis rates historically exceeded 15%.
- Hepatobiliary Disorders:Secondary cholestatic presentations including primary sclerosing cholangitis overlap syndromes.
- Liver Failure:End-stage decompensated cirrhosis requiring transplant evaluation and palliative symptom management.
Revenue concentrates in Cholestatic Liver Disease; Autoimmune Condition applications are climbing the fastest as diagnostic antibody panels improve detection of overlap syndromes.
End User:
Site-of-care economics and reimbursement complexity fragment buyer power, with integrated health systems leveraging formulary control against standalone specialty pharmacies competing on hub services.
- Hospitals:Academic medical centers and transplant hospitals with captive hepatology divisions managing complex PBC through multidisciplinary care protocols. United States centers including Cleveland Clinic and Johns Hopkins anchor prescriber concentration where 340B pricing programs distort competitive dynamics for outpatient dispensing.
- Specialty Pharmacies:Vertically integrated dispensers with direct hepatology center relationships providing prior authorization management, adherence monitoring, and patient assistance program administration. CVS Specialty and Accredo dominate limited distribution networks for high-cost immunomodulators where data capture creates secondary revenue streams.
- Outpatient Clinics:Community hepatology practices and gastroenterology groups managing stable patients on established therapy.
- Research Institutions:Clinical trial sites and academic centers conducting investigator-initiated studies on novel mechanisms.
Patient volume flows through Hospitals; Specialty Pharmacies capture the steepest expansion trajectory as limited distribution networks displace traditional wholesale channels.
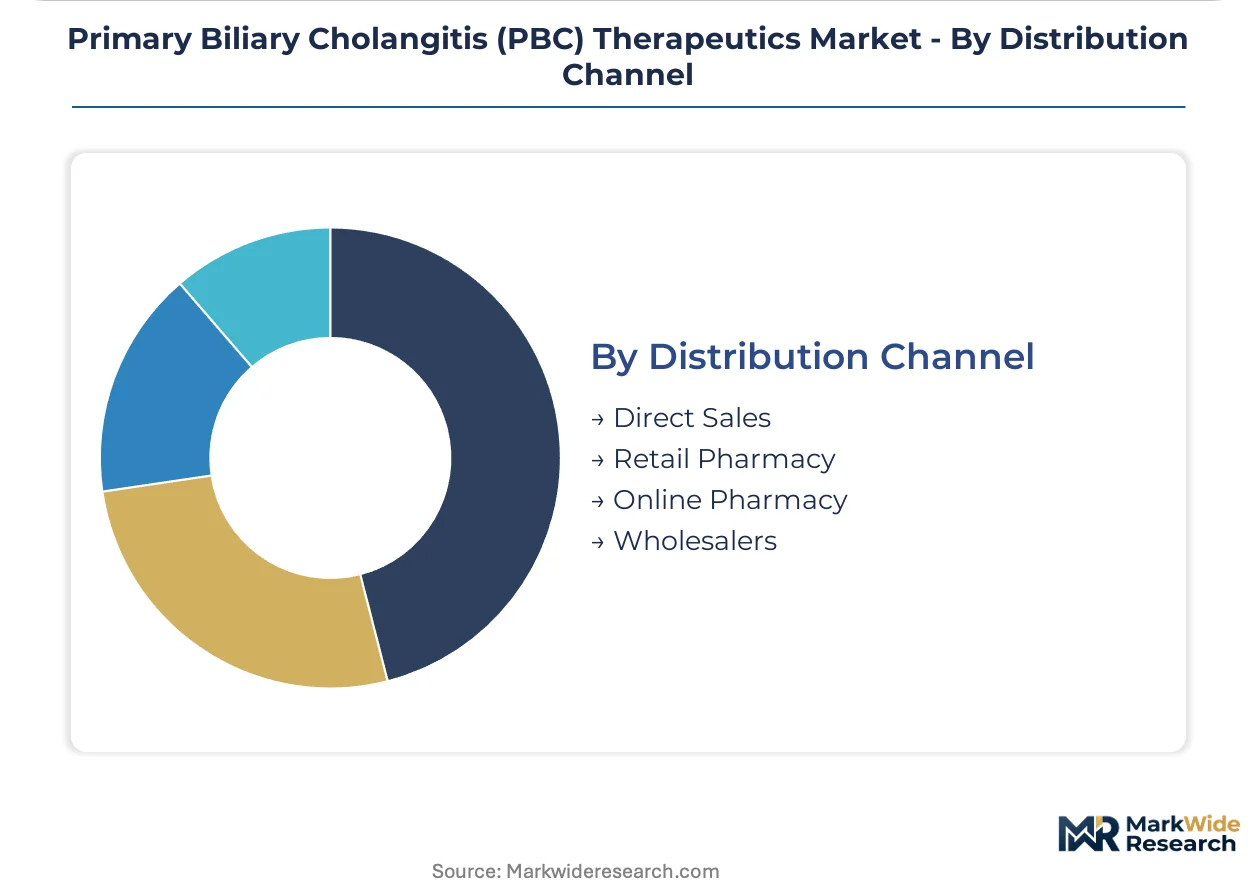
Distribution Channel:
Channel selection reflects therapy cost tier and patient support requirements, with manufacturer control over patient data and adherence outcomes driving network configuration decisions.
- Direct Sales:Manufacturer-to-institution contracting for hospital outpatient departments and integrated delivery networks. Gilead Sciences and Intercept Pharmaceuticals deploy dedicated hepatology account teams to major United States transplant centers where sole-source agreements secure formulary positioning.
- Retail Pharmacy:Traditional community dispensing for generic ursodeoxycholic acid with mature pricing and limited service differentiation.
- Online Pharmacy:Mail-order fulfillment for maintenance therapy with automated refill management.
- Wholesalers:McKesson and AmerisourceBergen handling inventory distribution to non-specialized sites with declining share in premium therapy segments.
Transaction volume remains with Wholesalers; margin capture is shifting fastest toward Direct Sales as manufacturers internalize patient support and data assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for PBC therapeutics concentrates in hepatology treatment centers across five countries where academic medical networks anchor prescriber concentration and reimbursement negotiation power.
United States
Cleveland Clinic, Mayo Clinic, and Johns Hopkins anchor hepatology center concentration where 340B pricing programs distort outpatient dispensing economics. FDA orphan drug exclusivity accelerates commercial timelines for novel bile acid modulators. Transplant centers in Boston and Houston drive prescriber loyalty for premium-priced therapies through integrated care protocols.
Germany
Charité Berlin and university hospital networks concentrate referrals for complex autoimmune liver conditions with elevated alkaline phosphatase markers. EMA conditional marketing authorization frameworks support premium reimbursement for UDCA-inadequate responders. The Rhine-Ruhr and Bavarian hospital clusters adopt non-invasive elastography for routine fibrosis monitoring.
Japan
Aging cirrhosis burden and expanding hepatology infrastructure create whitespace for bile acid receptor modulators in East Asia's most mature pharmaceutical market. PMDA regulatory pathways accommodate rare disease development with defined biochemical endpoints. Tokyo and Osaka academic centers lead diagnostic antibody panel adoption for overlap syndrome detection.
United Kingdom
NHS specialized commissioning frameworks concentrate PBC treatment decisions within designated liver units across England and Scotland. NICE technology appraisals demand robust biochemical response data for formulary inclusion of novel mechanisms. The Manchester and Birmingham hepatology networks pilot integrated adherence monitoring through specialty pharmacy partnerships.
Switzerland
Swissmedic regulatory efficiency attracts contract manufacturing for synthetic bile acid derivatives displaced from continental facilities under REACH registration delays. Basel and Zurich pharmaceutical clusters secure alternative input sources for formulation suppliers. Private reimbursement structures enable faster access to combination therapy protocols than neighboring EU markets.
Primary Biliary Cholangitis (PBC) Therapeutics Market Competitive Landscape
Established producers occupy the standard tier with mature ursodeoxycholic acid formulations; emerging entrants pursue novel bile acid receptor modulation and fibrate combination protocols. The vendor base stratifies across three tiers: generic manufacturers with commoditized pricing, specialty pharmaceutical companies with integrated hepatology commercial infrastructure, and clinical-stage developers targeting treatment-resistant populations. Competitive positioning hardens around formulary control at academic medical centers, limited distribution network exclusivity, and patient assistance program sophistication. Dominant competitive moves include specialty pharmacy vertical partnerships and orphan drug exclusivity acquisitions.
Within the specialty pharmaceutical tier, Intercept Pharmaceuticals and Gilead Sciences exemplify contrasting infrastructure strategies—Intercept anchors physician loyalty through first-mover bile acid receptor modulation positioning, while Gilead leverages integrated virology and hepatology commercial platforms. Among clinical-stage developers, CymaBay Therapeutics occupies a position targeting peroxisome proliferator-activated receptor agonist combinations for non-responder populations. These three entities represent the archetypal competitive vectors shaping prescriber access and payer negotiation dynamics across major transplant center networks.
| Leading Market Players |
|---|
| Intercept Pharmaceuticals |
| Gilead Sciences |
| Ipsen |
| CymaBay Therapeutics |
| GENFIT |
| Viatris |
| AbbVie |
| Dr Falk Pharma |
| Mirum Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Sustained-release formulation manufacturing for bile acid receptor modulators is compressing production economics while concentrating supply control among Swiss and United Kingdom contract manufacturers. This technological shift simultaneously elevates compliance costs under REACH standards and creates pricing power for qualified suppliers serving European and United States markets.
Pricing Analysis
Volume concentrates with generic ursodeoxycholic acid while margins accumulate with obeticholic acid and emerging fibrate combinations. Three-tier pricing structure across premium novel mechanisms, established branded agents, and commoditized generics reflects biochemical response differentiation and hepatology center formulary positioning. Pricing pressure stems from generic saturation in first-line therapy, though premium tiers maintain resilience through orphan drug exclusivity and limited distribution network control. Community hepatology practices exhibit highest price sensitivity; academic transplant centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
REACH chemical safety documentation and EMA good manufacturing practice certification gate active pharmaceutical ingredient supply for synthetic bile acid derivatives. Manufacturing concentrates in Switzerland, the United Kingdom, and selected Indian facilities with established regulatory track records. Formulation inputs draw from fluorinated solvent suppliers facing European F-Gas Regulation phase-down constraints, creating single-source vulnerability for specific intermediate chemistries. Distribution runs through vertically integrated specialty pharmacy networks with direct hepatology center relationships, displacing traditional wholesale channels for high-cost immunomodulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as biochemical response biomarker standardization and payer evidence requirements force subscale developers toward partnership or exit. Generic saturation in first-line therapy eliminates margin runway for undifferentiated entrants lacking novel mechanisms or specialty pharmacy integration.
For Market Incumbents: Lock in formulary positioning at Cleveland Clinic, Mayo Clinic, and Johns Hopkins through integrated adherence monitoring and prior authorization hub services. Secure captive supply of synthetic bile acid intermediates via manufacturing partnerships with Swiss and United Kingdom contract manufacturers ahead of REACH registration delays. Defensive investment in non-invasive fibrosis biomarker data packages will harden payer negotiation leverage against emerging fibrate combination protocols. For New Entrants and Emerging Players: Peroxisome proliferator-activated receptor agonist combinations for UDCA-inadequate responders offer the most penetrable white-space target, with Japan's aging cirrhosis burden providing geographic expansion runway. Diagnostic antibody panel integration for overlap syndrome detection creates differentiation in autoimmune condition applications. Go-to-market execution should anchor in specialty pharmacy limited distribution networks with direct-to-patient hub capabilities rather than hospital formulary competition. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical companies with Phase III-ready bile acid receptor modulators and established hepatology center relationships. Long-term viability across the analysis window hinges on biochemical response endpoint validation and EMA conditional marketing authorization track records. The signal to watch is payer adoption of non-invasive elastography staging protocols, which will accelerate formulary access timelines for therapies with robust fibrosis regression data.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III programs with defined alkaline phosphatase endpoints secure EMA conditional authorization and FDA orphan drug exclusivity. |
| Manufacturing Scale-Up | Swiss and United Kingdom facility expansion captures volume displaced by REACH registration delays in continental Europe. |
| Licensing Agreement | Fibrate combination protocols with peroxisome proliferator-activated receptor agonists expand addressable non-responder populations. |
| Regulatory Approval Pathway | PMDA submissions in Japan leverage aging cirrhosis burden and defined biochemical response endpoints for accelerated review. |
| Pipeline Diversification | Immunomodulatory mechanisms beyond bile acid receptor targeting address autoimmune hepatitis overlap syndromes with elevated misdiagnosis rates. |
Research Methodology
Multi-period observation of alkaline phosphatase response rates, fibrosis staging protocol adoption, and specialty pharmacy channel share anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at major United States hepatology centers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov enrollment data, EMA conditional marketing authorization submissions, FDA orphan drug designation filings, and hospital procurement databases. Bottom-up patient flow modeling across treatment lines and top-down revenue triangulation against disclosed pharmaceutical sales produced convergent estimates.
Input-output matrices mapped bile acid modulator demand to hepatology center concentration, REACH compliance costs to manufacturing location decisions, and specialty pharmacy network expansion to patient adherence outcomes. Segmentation dimensions included product type, disease staging, end-user site-of-care economics, and regional regulatory cluster. CAGRs were derived from biochemical response rate improvements, fibrate combination protocol penetration curves, and non-invasive monitoring technology diffusion across major transplant centers. Forecast inputs incorporated EMA conditional authorization timelines, F-Gas Regulation phase-down schedules, and PMDA rare disease pathway utilization.
Several conditions sit outside the modeled scope, including primary sclerosing cholangitis therapeutic crossover, diagnostic antibody panel reimbursement decisions, and 340B pricing program legislative modifications. Forecasts reflect assumptions regarding biochemical response biomarker standardization and specialty pharmacy vertical integration trajectories. A model refresh is warranted upon material change in payer evidence requirements for non-invasive fibrosis endpoints or REACH chemical safety documentation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Global Recombinant Proteins Market