
 Retail Genomics Market | 2026-2036
Retail Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Genomics Market Analytics
Consumer healthcare engagement is shifting toward proactive genetic risk management. 23andMe leverages vertical integration from sample collection to interpretive reporting. Ancestry sustains brand dominance through massive genealogical database network effects. Illumina anchors the technology layer with sequencing instrument and consumable leadership.
Retail genomics encompasses direct-to-consumer genetic testing services and associated analytical platforms that process DNA samples outside clinical settings, typically employing microarray genotyping or targeted next-generation sequencing with turnaround times of two to eight weeks. The primary commercial purpose is translating raw genetic data into actionable health, ancestry, or trait information for individual purchasers. Pharmacogenomics applications command premium pricing due to clinical utility and prescriber integration requirements, while ancestry testing represents a mature volume segment with compressing margins. Next-generation sequencing technology is displacing microarray analysis in high-value health applications, though microarrays retain cost advantages for broad population screening.
FDA oversight of direct-to-consumer genetic tests shapes product design and marketing claims for US-based providers, while the EU In Vitro Diagnostic Regulation imposes conformity assessment burdens on European market entrants. HIPAA privacy requirements constrain data monetization pathways for healthcare-adjacent offerings. Stakeholders must monitor evolving classification distinctions between wellness and medical device claims across jurisdictions.
Market Dynamics
Next-generation sequencing is electrifying the retail genomics value chain by compressing analysis costs and expanding interpretable health markers beyond ancestry panels, forcing microarray-dependent providers to reposition or integrate sequencing capabilities.
Growth Catalysts
- Pharmacogenomics Integration:FDA's 510(k) pathway for direct-to-consumer pharmacogenomic reports enables prescriber-facing partnerships. Health systems in the United States embed these tests into medication management protocols.
- HIPAA-Compliant Data Ecosystems:Cloud infrastructure providers build specialized genomics data lakes. Research institutions gain federated access to de-identified cohorts without compromising individual privacy protections.
- Polygenic Risk Scores:Algorithmic advances combine thousands of variants into disease probability metrics. Cardiovascular and type 2 diabetes applications attract preventive health expenditures from self-insured employers.
Market Restraints
- Illumina Instrument Lock-In:Sequencing consumable supply concentrates around a single vendor's proprietary flow cell chemistry. Alternative platform adoption faces switching costs and revalidation timelines.
- EU MDR Conformity Burden:The In Vitro Diagnostic Regulation reclassifies many health-related genetic tests as Class C devices. Notified body capacity constraints extend European market entry timelines.
- Saliva Sample Degradation:Ambient temperature shipping limits viable DNA yield from remote collection. Tropical climates and extended transit routes elevate failure rates and repeat collection costs.
Strategic Opportunities
- Brazil ANVISA Harmonization:Latin America's largest healthcare market streamlines genetic test registration. Local laboratory partnerships bypass import restrictions on processed samples.
- AI-Interpretive Convergence:Large language models trained on clinical literature generate consumer-facing variant explanations. Natural language interfaces reduce genetic counselor dependency for initial result delivery.
- Subscription Wellness Models:Continuous genomic updates replace one-time ancestry reports. Trait tracking and new marker notifications generate recurring revenue from existing sample banks.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant classification pipelines require dual expertise in computational biology and clinical genetics. Compensation inflation strains mid-stage provider operating models.
- CLIA Laboratory Certification Timelines:High-complexity testing accreditation demands documented quality systems and proficiency testing participation. New entrant sample processing capacity ramps average eighteen months.
- Cross-Border Data Sovereignty:China's Personal Information Protection Law and Russia's data localization requirements fragment global biobank architectures. Multi-jurisdictional providers must replicate infrastructure regionally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Genomics Market |
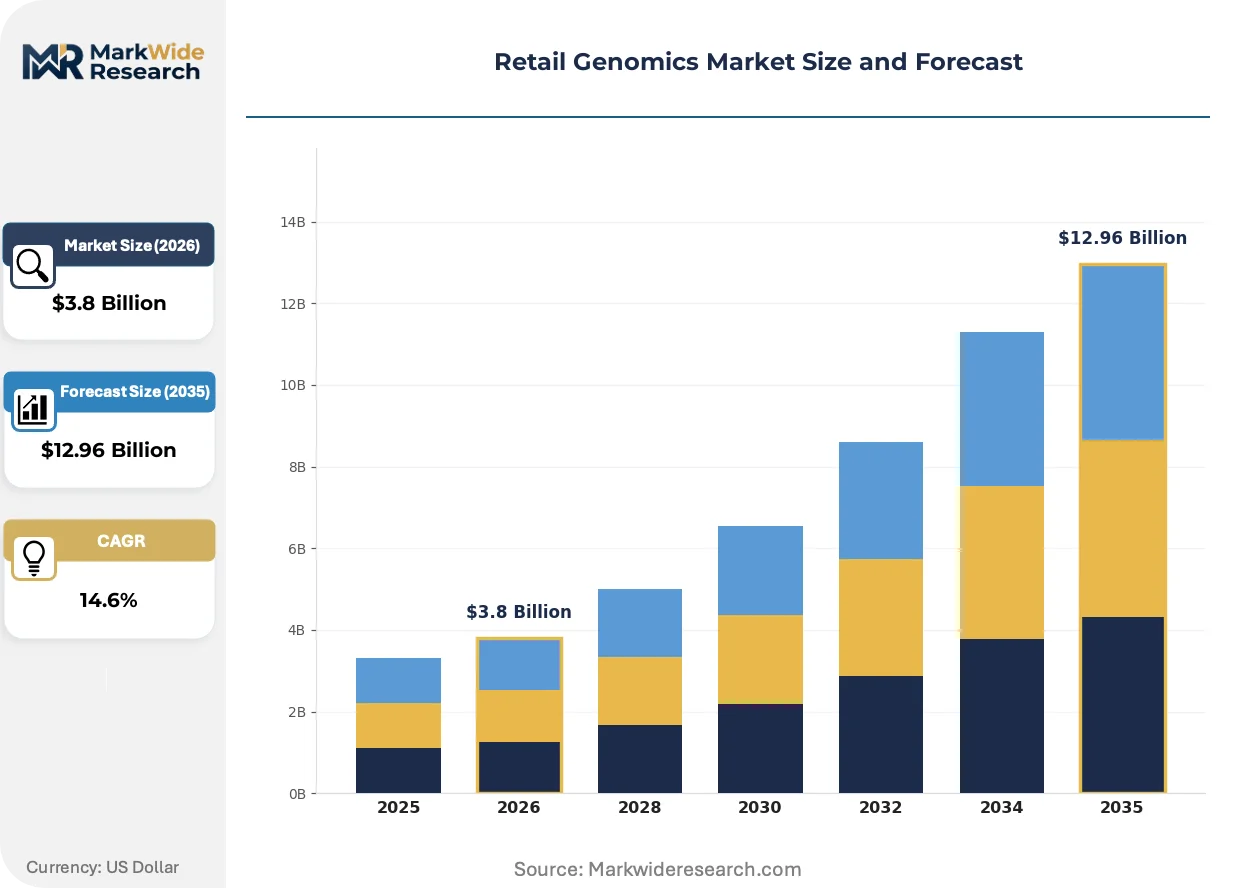
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, Genotyping, Gene Expression, Epigenomics Customer Type: Consumers, Healthcare Providers, Research Institutions, Biotechnology Firms Application: Personalized Nutrition, Pharmacogenomics, Disease Risk Assessment, Ancestry Testing Technology: Next-Generation Sequencing, Microarray Analysis, CRISPR, Bioinformatics |
| Companies Covered | 23andMe, Inc., Illumina Inc., Thermo Fisher Scientific Inc., Ancestry, Color Genomics, Inc., Myriad Genetics, Inc., QIAGEN N.V., Agilent Technologies, Inc., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Genomics Market Evolving Landscape
Retail genomics is bifurcating between commoditized ancestry volume and premium health utility, with technology investments concentrating on clinical-grade interpretation and prescriber workflow integration.
Long-read sequencing from Pacific Biosciences and Oxford Nanopore is electrifying structural variant detection in consumer-facing health panels. Pharmacogenomic providers adopt these platforms to capture copy number variations and phasing information that short-read methods miss. The technology is compressing the diagnostic yield gap between clinical laboratories and direct-to-consumer offerings.
The FDA's 2023 enforcement discretion update for genetic health risk tests narrows permissible claims while expanding required accuracy evidence. Manufacturers must demonstrate analytical validity across diverse populations or face marketing restriction. Pharmacogenomic and carrier screening segments absorb the heaviest compliance burden, while wellness-oriented trait reports operate under lighter oversight.
Employer-sponsored genetic benefits are displacing individual purchase as the primary demand channel for health-risk applications. Benefits administrators bundle testing with genetic counseling and care navigation. The United States leads this shift, with large self-insured plans covering pharmacogenomic testing for chronic condition management.
Retail Genomics Market Segmentation
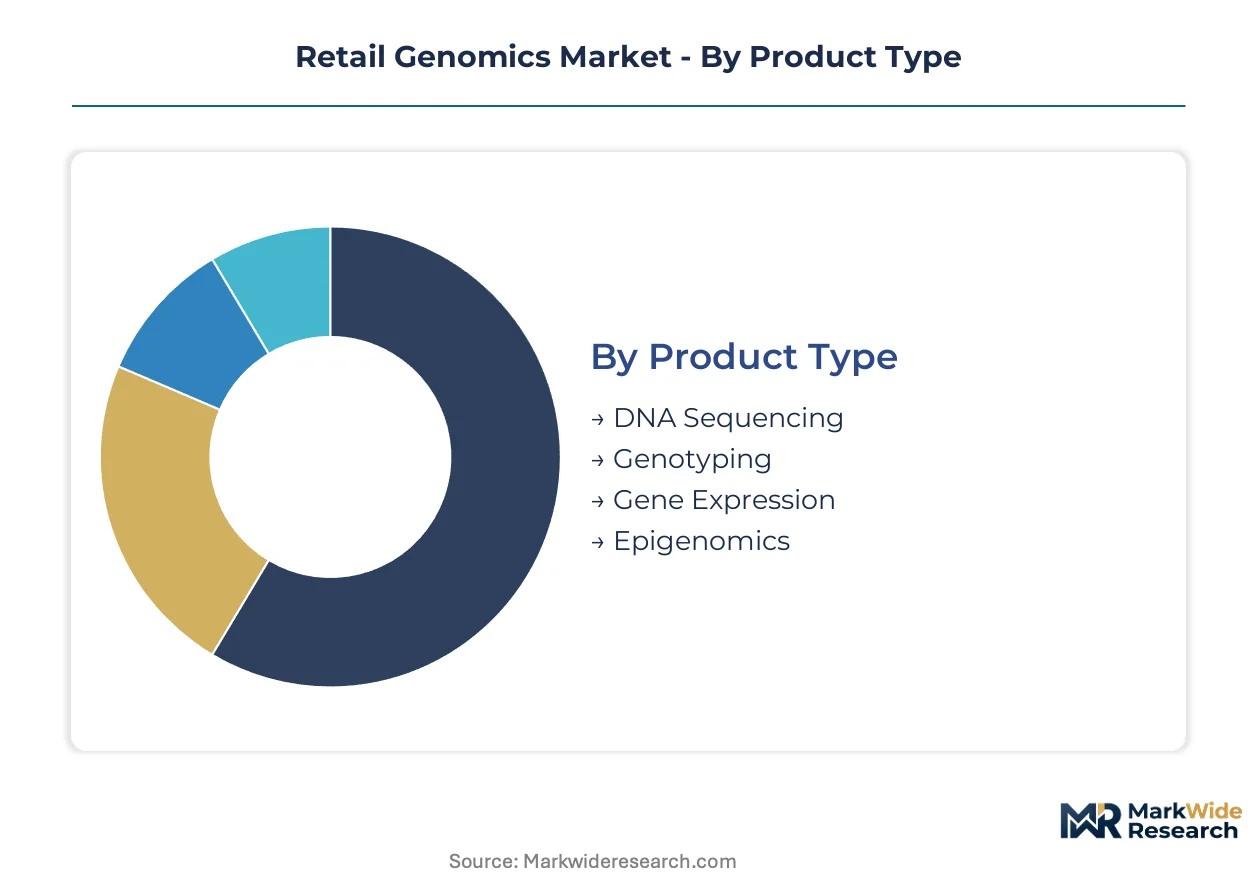
Retail genomics providers configure product portfolios around distinct technical capabilities and customer workflows. Segment boundaries blur as ancestry platforms add health markers and clinical laboratories launch direct-to-consumer channels. Understanding where margin concentrates versus where volume flows shapes capital allocation and partnership strategy.
Product Type:
Supply concentration in sequencing instrumentation and consumables creates divergent margin profiles across product categories, with platform economics favoring providers who control sample-to-data workflows.
- DNA Sequencing:Whole-genome and exome sequencing generate highest per-test revenue through clinical-grade interpretation. US health systems and self-insured employers drive demand for pharmacogenomic and carrier screening applications requiring base-pair resolution accuracy.
- Genotyping:Microarray-based SNP panels dominate ancestry and wellness volume with compressed margins but massive sample throughput. Illumina's beadchip chemistry supplies the underlying platform infrastructure for most consumer-facing providers.
- Gene Expression:Transcriptomic profiling remains nascent in direct-to-consumer channels, constrained by sample stability requirements and interpretive complexity.
- Epigenomics:Methylation analysis attracts longevity and wellness positioning, though standardization lags behind genotyping for consumer accessibility.
Today's leader: DNA Sequencing. Tomorrow's challenger: Epigenomics.
Customer Type:
Cost tier stratification separates individual purchasers from institutional procurement, with healthcare providers commanding volume discounts and technical support packages unavailable to direct consumers.
- Consumers:Individual purchasers drive ancestry testing volume through online channels, with price sensitivity highest among first-time buyers exploring genetic heritage. Subscription models and trait updates extend lifetime value beyond initial reports.
- Healthcare Providers:Hospitals and clinics integrate pharmacogenomic testing into medication management protocols, with FDA 510(k) clearance requirements filtering vendor selection. United States health systems anchor this segment's revenue concentration.
- Research Institutions:Academic biobanks and population genetics studies purchase de-identified cohort data and analytical services, with HIPAA-compliant data lakes enabling federated access.
- Biotechnology Firms:Drug developers license aggregated genetic datasets for target validation and biomarker discovery, with polygenic risk scores supporting patient stratification in clinical trials.
Healthcare Providers capture institutional procurement volume. Consumers represent the steepest expansion trajectory as wellness applications proliferate.
Application:
Maturity curves separate established ancestry services from emerging health utilities, with regulatory classification determining permissible marketing claims and prescriber integration depth.
- Personalized Nutrition:Dietary recommendations based on metabolic gene variants attract wellness-oriented consumers, though clinical evidence for efficacy remains limited compared to pharmacogenomic applications.
- Pharmacogenomics:Drug-gene interaction testing commands premium pricing through prescriber workflow integration and FDA-cleared reports. United States health systems embed these tests into formulary management for cardiovascular and psychiatric medications.
- Disease Risk Assessment:Polygenic risk scores for type 2 diabetes and cardiovascular conditions attract preventive health expenditures from employers, with algorithmic validation requirements tightening under FDA guidance.
- Ancestry Testing:Genealogical matching and ethnic composition analysis represents the most penetrated consumer segment, with network effects from database size creating winner-take-most dynamics.
Ancestry Testing holds installed base dominance. Pharmacogenomics is climbing the fastest as clinical utility evidence accumulates.
Technology:
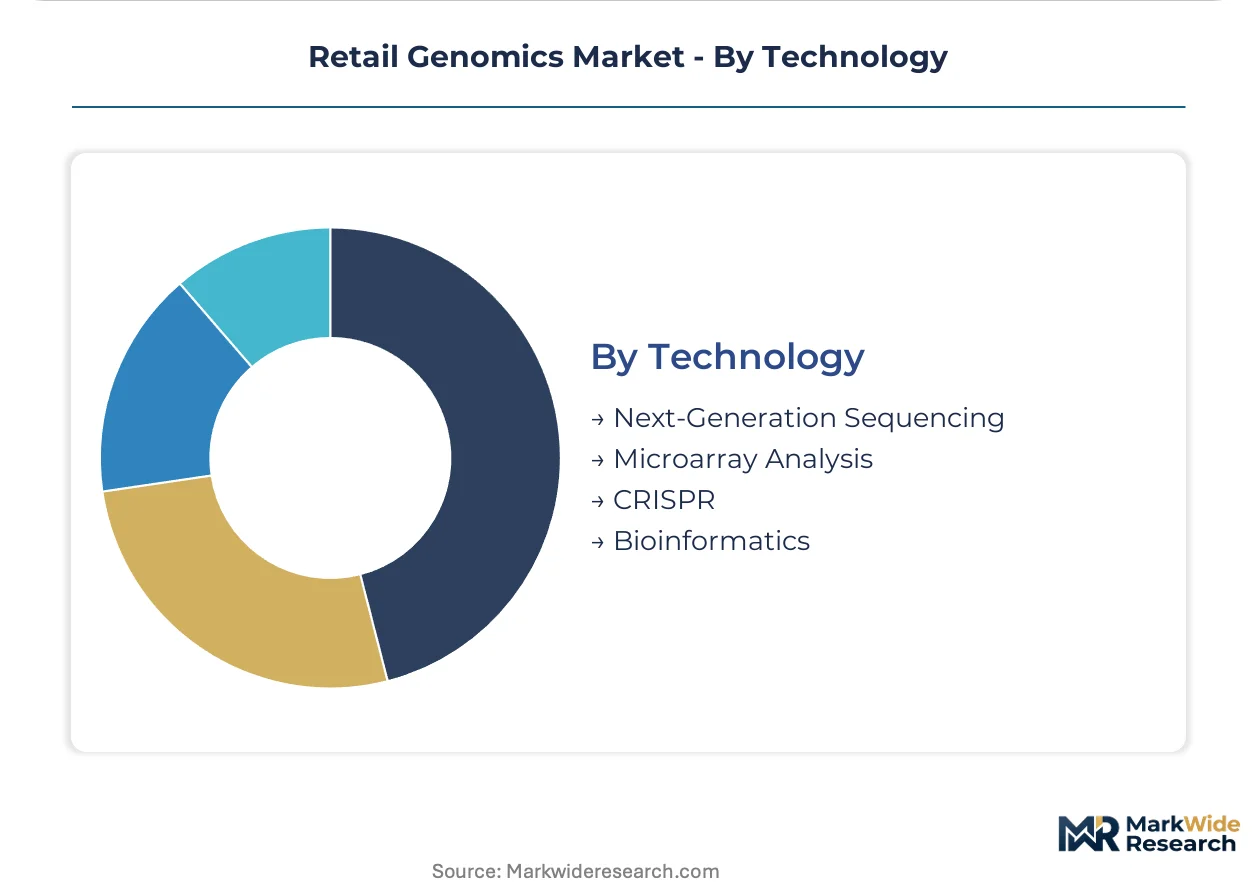
Application requirements dictate platform selection, with next-generation sequencing displacing microarrays in health-risk segments while bioinformatics capabilities differentiate interpretive quality.
- Next-Generation Sequencing:Short-read platforms from Illumina anchor clinical-grade testing, with long-read alternatives from Pacific Biosciences and Oxford Nanopore penetrating structural variant detection. Exome and genome applications drive fastest technology refresh cycles.
- Microarray Analysis:Beadchip and photolithographic arrays retain cost advantages for high-volume ancestry and wellness screening, though marker density limitations constrain health marker expansion.
- CRISPR:Gene editing technology remains confined to research applications and synthetic biology services, with consumer-facing diagnostic applications limited by regulatory and ethical constraints.
- Bioinformatics:Variant calling pipelines and clinical interpretation engines constitute the primary competitive differentiator, with AI-augmented reporting reducing genetic counselor dependency for result delivery.
Next-Generation Sequencing commands technology investment priority. Bioinformatics is gaining share fastest as interpretive accuracy becomes the purchase determinant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where retail genomics providers establish laboratory infrastructure, with the United States offering FDA-cleared pathways for pharmacogenomic claims while jurisdictions with lighter wellness-classification rules attract ancestry-focused operations.
United States
FDA 510(k) clearances for direct-to-consumer pharmacogenomic reports drive health-system partnerships. HIPAA privacy frameworks constrain data monetization but enable compliant research collaborations. The San Francisco Bay Area anchors 23andMe and Color Genomics headquarters, with CLIA-certified processing labs concentrated in California and North Carolina.
China
Personal Information Protection Law data-localization requirements fragment global biobank architectures. NMPA regulates clinical-grade genetic tests while wellness applications operate under lighter SAMR oversight. Shenzhen and Beijing host sequencing instrument manufacturing clusters serving domestic consumer testing platforms.
Germany
EU MDR conformity assessment burdens extend market entry timelines for health-risk genetic tests. BfArM and notified body capacity constraints create compliance backlogs. The Munich and Heidelberg biotech corridors concentrate bioinformatics talent and precision medicine research institutions.
United Kingdom
MHRA post-Brexit regulatory autonomy enables divergence from EU MDR classification approaches. Genomics England's population-scale sequencing programs create research data infrastructure. London and Cambridge host consumer-facing testing platforms and interpretive software development.
Brazil
ANVISA harmonization streamlines genetic test registration for Latin America's largest healthcare market. Local laboratory partnerships bypass import restrictions on processed samples. São Paulo and Rio de Janeiro concentrate private diagnostic laboratory capacity and health insurance network integration.
Retail Genomics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration from sample collection to interpretive reporting commanding premium positioning in pharmacogenomics while ancestry volume flows through platform-dependent service providers. The competitive structure concentrates around three strategic archetypes: integrated health-data platforms, sequencing technology licensors, and specialized clinical-test developers. Dominant competitive moves include backward integration into CLIA-certified laboratory capacity and prescriber workflow partnerships for reimbursement access.
Within the integrated platform tier, 23andMe, Inc. exemplifies the vertical-control archetype spanning consumer acquisition through clinical-grade reporting. Illumina Inc. anchors the technology-licensor position with sequencing instrument and consumable supply concentration. Ancestry occupies the database-network-effects position, with genealogical data scale creating consumer switching costs. These three entities represent the structural poles around which mid-stage providers and regional specialists position.
| Leading Market Players |
|---|
| 23andMe, Inc. |
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Ancestry |
| Color Genomics, Inc. |
| Myriad Genetics, Inc. |
| QIAGEN N.V. |
| Agilent Technologies, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Network & Pricing Analysis
Health system procurement departments and self-insured employer benefits administrators concentrate demand for pharmacogenomic testing, anchoring contract-based pricing with volume discounts that ancestry-facing direct-to-consumer channels cannot match.
Pricing Analysis
Direct-to-consumer retail markups on ancestry kits compress as genotyping commoditizes, while prescriber-facing pharmacogenomic reports command premium-mid-economy pricing differentiation through FDA 510(k) certification and clinical workflow integration. Price differentiation hinges on analytical validity tier and prescriber access pathway. Pricing pressure stems from Illumina consumable cost inflation and microarray margin erosion. Individual purchasers show highest price sensitivity, with health systems least sensitive due to formulary cost-offset calculations.
Supply Chain Analysis
Regional distribution centers in California, North Carolina, and Shenzhen anchor hub-and-spoke patterns for saliva collection kits and processed sample flows. Sequencing instrument manufacturing concentrates in the United States and China, while reagent production draws from Singapore and Germany. Raw material dependencies include proprietary flow cell chemistry, stabilized collection buffer formulations, and CRISPR-grade synthetic oligonucleotides. Single-source vulnerability around Illumina sequencing consumables elevates supply risk. Distribution runs through CLIA-certified laboratory networks with direct-to-consumer fulfillment partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail genomics offers margin expansion through next-generation sequencing cost compression and employer-sponsored benefit tier upgrades, with pharmacogenomic clinical utility evidence supporting premium positioning.
For Market Incumbents: Lock in prescriber workflow partnerships before FDA classification tightening restricts new entrant marketing claims. Secure captive supply of sequencing capacity through CLIA laboratory acquisitions or long-term instrument service contracts. Defend against long-read platform disruption by integrating Pacific Biosciences or Oxford Nanopore capabilities into health-risk panels. For New Entrants and Emerging Players: Enter via Brazil ANVISA harmonization pathways to bypass EU MDR conformity backlogs and US FDA 510(k) timelines. Target employer-sponsored genetic benefits as the fastest-penetrating demand channel, with benefits administrator partnerships offering reimbursement access that individual purchase channels lack. Lead with AI-interpretive reporting to reduce genetic counselor dependency and accelerate result delivery. For Investors and Strategic Acquirers: Health systems and pharmaceutical benefit managers are the most active acquirer in this space, seeking vertical data integration from testing through care navigation. Long-term viability favors providers with HIPAA-compliant biobank infrastructure and polygenic risk score algorithm portfolios. Watch FDA enforcement discretion updates for pharmacogenomic claims as the signal for regulatory arbitrage window closure.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Acquisition | Captures in-house processing capacity and accelerates pharmacogenomic report turnaround for health system contracts. |
| Prescriber Workflow Integration | Embeds pharmacogenomic decision support into EHR systems at United States health systems and formulary management platforms. |
| AI-Augmented Interpretation Engine | Reduces genetic counselor staffing ratios through large language model-trained variant explanation generation. |
| Employer Benefits Channel Partnership | Accesses self-insured plan procurement budgets through benefits administrator bundling with care navigation services. |
| Long-Read Sequencing Platform Adoption | Captures structural variants and phasing information for pharmacogenomic copy number variation detection. |
Research Methodology
Direct dialogue with CLIA laboratory directors, health system pharmacy and therapeutics committee members, genetic counseling practice managers, and FDA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from FDA 510(k) clearances, CMS Medicare coverage determinations, hospital GPO contract databases, and Illumina quarterly instrument shipment disclosures. Bottom-up sample processing capacity estimates triangulated against top-down employer benefits spending projections.
Bottom-up modeling segmented the market by product type, customer workflow, and application maturity, with technology platform transitions tracked across the projection horizon. Analytical frameworks incorporated pharmacogenomic test volume per covered life, ancestry kit price elasticity curves, and sequencing consumable cost trajectories. CAGRs were derived from installed base expansion rates and test frequency assumptions by segment.
Inputs from FDA enforcement discretion updates and EU notified body capacity reports were available through the study window; gaps in private employer benefits spending data introduce uncertainty bands around health-risk application forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Dna Polymerase Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Genotyping Market
Genomics
Mitochondrial DNA Market
Genomics
Molecular Breeding Market
Genomics
Global Nutrigenomics Market
Genomics
Global Long Read Sequencing Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Microarray Scanners Market
Genomics
US Genetic Testing Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Whole Genome Amplification Market
Genomics
Animal Genetics Market
Genomics
China Genetic Testing Market