
 Global Pipeline Safety Market | 2026-2036
Global Pipeline Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipeline Safety Market Outlook
The capability gap between integrated automation providers and point-solution vendors is rotating competitive capital allocation across the Global Pipeline Safety Market. ABB leverages its electrification and digital portfolio to anchor long-term service contracts with national transmission operators. Siemens AG sustains technology leadership through its industrial software and hardware convergence for pipeline monitoring. Honeywell competes on sensor density and control-system integration across North American infrastructure.
Pipeline safety encompasses the engineered systems, protocols, and technologies designed to prevent, detect, and mitigate failures in hydrocarbon and fluid conveyance networks, incorporating pressure-rated materials, cathodic protection systems, and real-time supervisory control with data acquisition at operational thresholds up to 1440 psi in interstate transmission lines. Leak detection technology dominates capital deployment due to regulatory mandates for rapid incident response, while monitoring systems are capturing accelerated investment as utilities digitize legacy distribution grids. Inspection tools occupy a mature but essential niche where robotic inline platforms and unmanned aerial surveys are displacing manual survey methods.
The U.S. Department of Transportation's Pipeline and Hazardous Materials Safety Administration sets integrity management standards that directly shape product certification requirements and operator procurement cycles. The European Union's F-Gas Regulation and the EU Green Deal methane strategy are forcing emission quantification capabilities into safety system specifications. China's Ministry of Emergency Management and its GB standards for pressure pipelines are tightening domestic manufacturing compliance. Stakeholders must weigh regulatory divergence against platform standardization when configuring product roadmaps for multi-jurisdiction deployment.
Market Dynamics
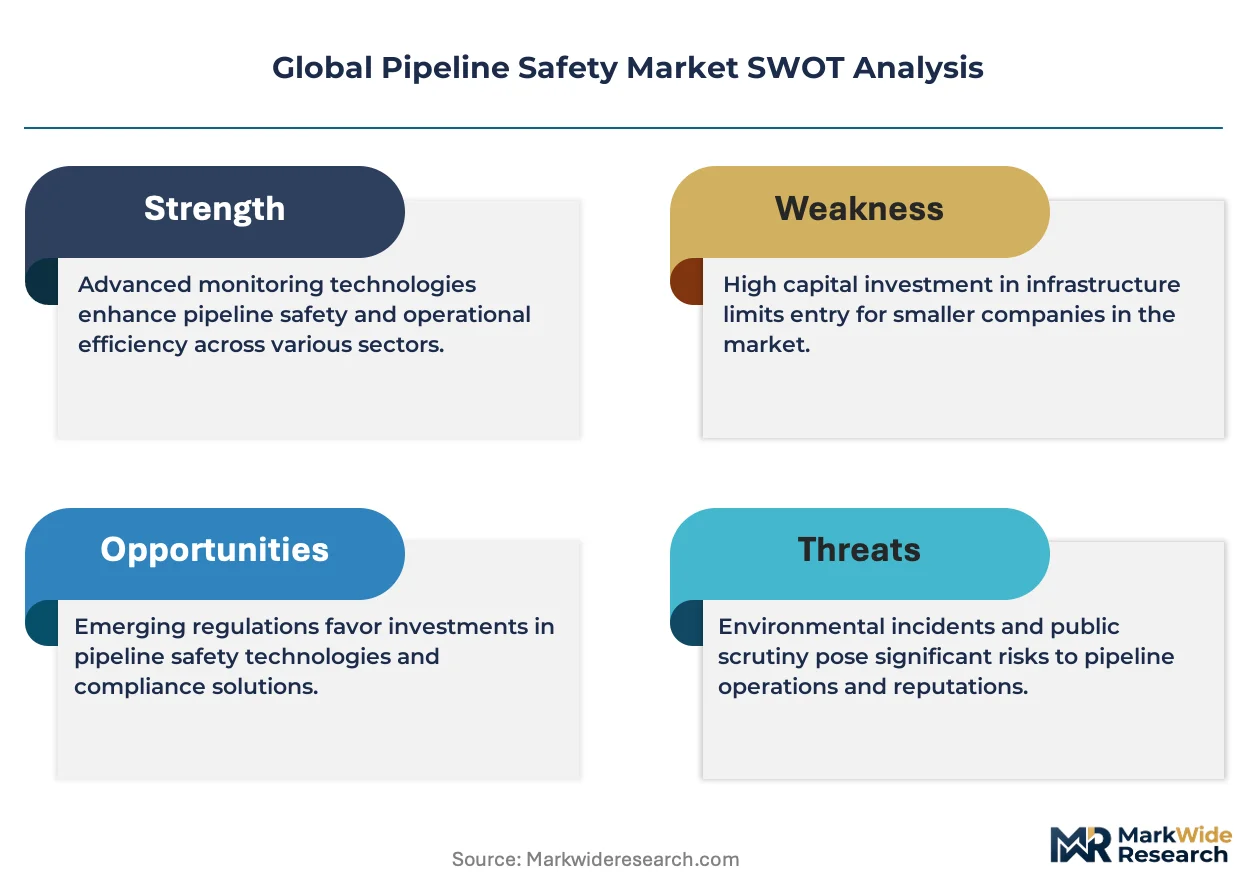
Regulatory divergence across the United States, European Union, and China is fragmenting product certification requirements and forcing vendors to maintain parallel compliance architectures for multi-jurisdiction deployment. This structural tension between standardization economies and localization mandates defines competitive positioning for integrated safety system providers.
Growth Catalysts
- EU F-Gas Regulation:Methane quantification mandates embedded in the EU Green Deal are accelerating procurement of emission-monitoring sensors for transmission infrastructure across Germany and the Netherlands.
- PHMSA integrity management:The U.S. Department of Transportation's stricter natural gas distribution rules are compressing replacement cycles for aging cathodic protection systems in metropolitan networks.
- Inline robotics:Unmanned robotic inspection platforms are displacing manual survey methods for subsea pipeline integrity assessment in the North Sea and Gulf of Mexico.
Market Restraints
- Specialized alloy supply:High-grade corrosion-resistant steels for pressure-rated pipeline construction face concentrated sourcing from limited metallurgical suppliers in Japan and Germany.
- Technical limitation:Acoustic leak detection systems suffer reduced sensitivity in high-noise multiphase flow environments common to shale gathering networks.
- Regulatory friction:China's GB standards for pressure pipelines impose domestic testing protocols that delay foreign equipment certification by 12-18 months.
Strategic Opportunities
- India distribution modernization:The Petroleum and Natural Gas Regulatory Board's city gas distribution expansion is creating first-mover advantage for leak detection vendors in Mumbai and Delhi clusters.
- Digital twin convergence:Integration of SCADA telemetry with predictive simulation platforms is opening subscription revenue models for pipeline operators seeking operational optimization.
- Hydrogen infrastructure:Germany's hydrogen core grid initiative is mandating material compatibility testing for existing natural gas pipelines, requiring upgraded safety system specifications.
Industry Challenges
- SCADA cybersecurity certification:Pipeline operators face extended validation timelines for IEC 62443-compliant industrial control systems due to scarce certified integration specialists.
- Legacy system interoperability:Retrofitting digital monitoring layers onto 1970s-era pipeline infrastructure requires custom protocol translation hardware that fragments vendor support models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipeline Safety Market |
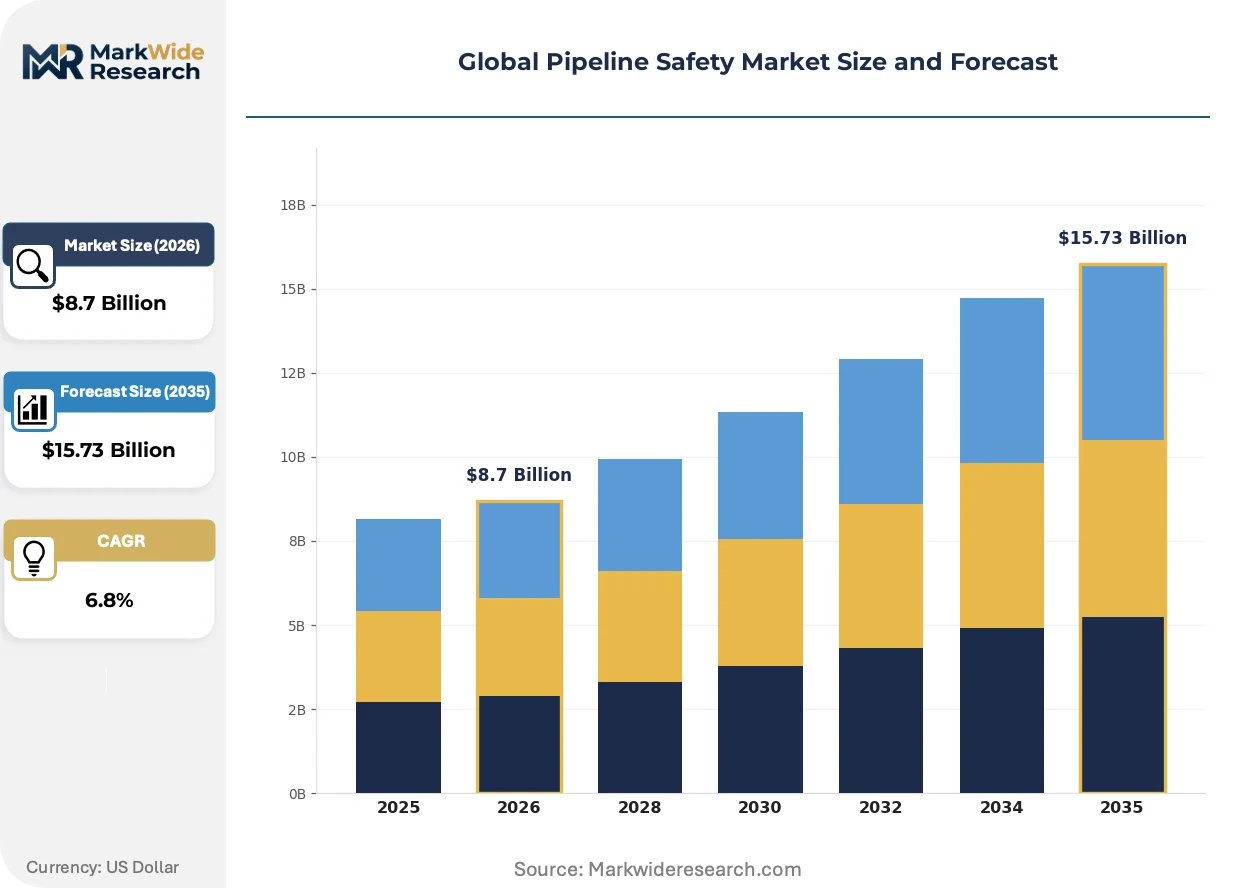
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Leak Detection, Monitoring Systems, Inspection Tools, Safety Valves End User: Oil & Gas Companies, Water Utilities, Chemical Plants, Transmission Operators Service Type: Consulting Services, Maintenance, Emergency Services, Training Application: Transportation, Distribution, Storage, Waste Management |
| Companies Covered | ABB, Siemens AG, Schneider Electric, Honeywell, Baker Hughes, Huawei Technologies, AVEVA, PSI AG, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipeline Safety Market Strategic Shifts
Sensor fusion architectures combining fiber-optic distributed sensing with satellite-based methane monitoring are compressing incident response windows from hours to minutes. This convergence of terrestrial and aerial detection modalities is redefining the technical specifications that govern procurement decisions.
Fiber-optic distributed acoustic sensing (DAS) converts standard telecommunications fiber into continuous vibration-monitoring arrays spanning hundreds of kilometers. North American transmission operators are deploying DAS overlays on existing fiber rights-of-way to achieve meter-scale leak localization without new trenching. This technology is supplanting discrete point-sensor networks that require costly excavation and maintenance access.
The EU's F-Gas Regulation and its methane reduction annex are forcing emission quantification capabilities into all new safety system specifications. Equipment vendors must now certify detection thresholds against standardized release rates rather than binary alarm triggers. Midstream operators in the Netherlands and Denmark are prioritizing vendors with validated quantification algorithms for regulatory reporting automation.
Integrated service contracts bundling hardware, software, and predictive maintenance are displacing transactional equipment sales in mature pipeline corridors. European transmission system operators in Germany and Italy are consolidating vendor relationships to reduce interface complexity. This consolidation is most visible in the North Sea offshore segment where platform operators seek single-accountability partners for subsea integrity management.
Global Pipeline Safety Market Segmentation
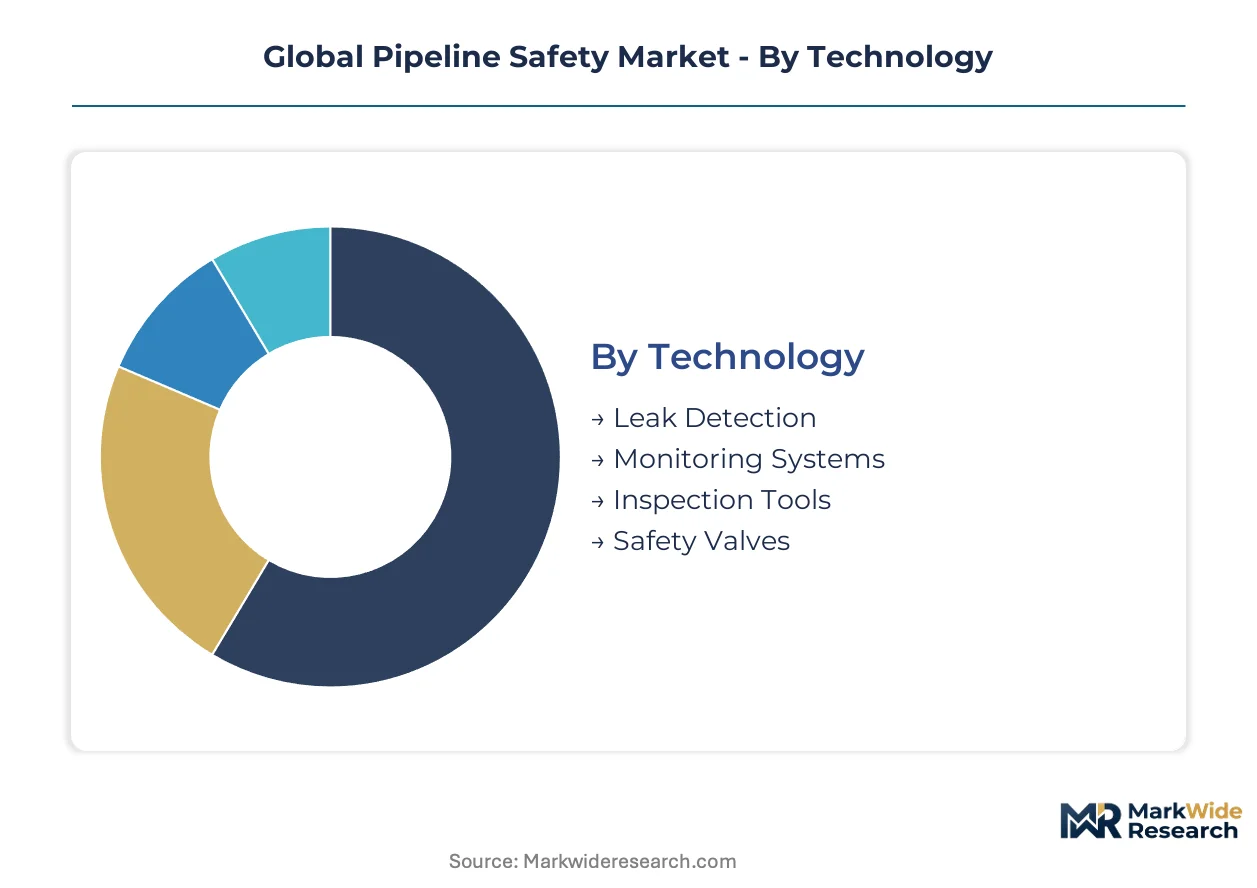
Technology choices in pipeline safety determine capital allocation cycles, regulatory compliance pathways, and vendor consolidation patterns across transmission and distribution networks. Segmentation reveals where substitution pressures from digital alternatives are compressing traditional equipment margins.
Technology:
Leak detection platforms face acute substitution pressure from fiber-optic distributed sensing systems that overlay existing telecommunications infrastructure without new trenching.
- Leak Detection:Acoustic, pressure-wave, and fiber-optic sensing systems localize ruptures and seepage events. Procurement concentrates in United States interstate transmission corridors where PHMSA mandates rapid incident response, though acoustic methods suffer degraded sensitivity in high-noise multiphase shale gathering networks.
- Monitoring Systems:SCADA architectures and telemetry networks deliver real-time pressure, flow, and integrity data to control centers. German and Dutch transmission operators are accelerating deployment to meet EU F-Gas Regulation methane quantification requirements for automated regulatory reporting.
- Inspection Tools:Robotic inline platforms and unmanned aerial systems displace manual survey methods.
- Safety Valves:Pressure-rated automatic shutoff devices isolate pipeline segments during overpressure events.
Leak detection retains volume leadership; monitoring systems hold the steepest expansion curve.
End User:
Cost tier stratification separates national transmission operators with integrated procurement budgets from municipal water utilities with fragmented purchasing authority.
- Oil & Gas Companies:Integrated majors and independents operate high-pressure transmission and gathering infrastructure. Investment clusters in Gulf of Mexico offshore corridors and Permian Basin shale networks where PHMSA integrity management rules compress replacement cycles for aging cathodic protection systems.
- Transmission Operators:Dedicated interstate and intrastate pipeline carriers manage regulated assets. Germany's hydrogen core grid initiative is mandating material compatibility testing for converted natural gas lines, requiring upgraded safety specifications.
- Water Utilities:Municipal and regional operators maintain lower-pressure distribution networks.
- Chemical Plants:Process industry facilities with captive pipeline networks for feedstock and product transfer.
Oil & gas companies dominate current procurement volume; transmission operators are gaining share fastest as hydrogen infrastructure mandates multiply.
Service Type:
Customer type divergence separates asset owners seeking outcome-based contracts from operators requiring discrete compliance documentation.
- Maintenance:Predictive and preventive service programs extend equipment lifecycle and ensure regulatory compliance. European North Sea platform operators are consolidating vendor relationships to secure single-accountability partners for subsea integrity management.
- Consulting Services:Engineering assessment and regulatory advisory support operator certification processes.
- Emergency Services:Rapid-response containment and repair capabilities for incident mitigation.
- Training:Operator certification and workforce development programs for control room and field personnel.
Maintenance commands the largest service revenue pool; consulting services are expanding most quickly as regulatory divergence multiplies compliance complexity.
Application:
Supply concentration in transportation infrastructure creates margin pressure on distribution and storage segments with more fragmented customer bases.
- Transportation:Long-haul transmission pipelines moving hydrocarbons and fluids between production, processing, and market centers. India's Petroleum and Natural Gas Regulatory Board city gas distribution expansion is creating first-mover opportunities for leak detection vendors in Mumbai and Delhi clusters.
- Distribution:Last-mile networks delivering product to industrial, commercial, and residential endpoints. United States metropolitan utilities face compressed replacement cycles under PHMSA's stricter natural gas distribution rules.
- Storage:Underground caverns and above-ground tankage with connected pipeline infrastructure.
- Waste Management:Conveyance systems for industrial effluent and hazardous material transport.
Transportation anchors capital deployment; distribution is climbing the fastest as digitization of legacy grids accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes rapid incident response systems for aging distribution networks. Germany and the Netherlands embed emission quantification into all new procurement. India concentrates investment in city gas distribution buildouts.
United States
Interstate transmission operators dominate capital deployment for leak detection and cathodic protection replacement. The Pipeline and Hazardous Materials Safety Administration compresses replacement cycles for metropolitan natural gas distribution infrastructure. Gulf of Mexico offshore corridors and Permian Basin shale networks anchor procurement volume.
Germany
Hydrogen core grid conversion mandates drive material compatibility testing for existing natural gas pipelines. The EU F-Gas Regulation and Green Deal methane strategy force emission quantification capabilities into safety system specifications. North Sea offshore platform operators consolidate vendor relationships for subsea integrity management.
China
Domestic pressure pipeline manufacturing faces tightened compliance under Ministry of Emergency Management GB standards. Foreign equipment certification delays of 12-18 months protect local suppliers. Sichuan-Chongqing shale basins and Yangtze River Delta industrial corridors concentrate demand for monitoring systems.
India
City gas distribution expansion under the Petroleum and Natural Gas Regulatory Board creates first-mover opportunities for leak detection vendors. Mumbai and Delhi clusters anchor procurement for distribution network digitization. Domestic manufacturing incentives accelerate local assembly of safety valve and sensor systems.
Netherlands
Transmission system operators prioritize vendors with validated methane quantification algorithms for automated regulatory reporting. The F-Gas Regulation mandates detection thresholds against standardized release rates. Rotterdam industrial corridors and North Sea pipeline terminals concentrate investment in fiber-optic distributed sensing overlays.
Global Pipeline Safety Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Global Pipeline Safety Market. The upper tier combines electrification, industrial software, and sensor hardware into long-term service contracts. Mid-tier specialists compete on discrete technology vectors such as acoustic sensing or robotic inspection. Dominant competitive moves include portfolio convergence around digital twin platforms and geographic expansion through integrated service contracts.
Among integrated automation providers, ABB leverages its electrification and digital portfolio to anchor national transmission operator relationships. Siemens AG exemplifies the industrial software-hardware convergence archetype for pipeline monitoring applications. Honeywell occupies a position emphasizing sensor density and control-system integration across North American infrastructure.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| Schneider Electric |
| Honeywell |
| Baker Hughes |
| Huawei Technologies |
| AVEVA |
| PSI AG |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month certification timelines for foreign equipment in China compress procurement cycles and concentrate pricing power with domestic suppliers who bypass regulatory friction. This lead-time differential between approved and pending vendors shapes contract negotiation leverage across transmission operator procurement desks.
Pricing Analysis
Long-term service contracts bundling hardware, software, and predictive maintenance dominate procurement decisions for national transmission operators, while spot purchases persist for discrete safety valve replacements in municipal distribution networks. Price differentiation hinges on IEC 62443 cybersecurity certification tier and fiber-optic sensing density per kilometer. Cost compression in acoustic sensing tiers is intensifying because fiber-optic distributed sensing overlays displace point-sensor excavation requirements. Municipal water utilities exhibit highest price sensitivity due to fragmented purchasing authority; North Sea offshore platform operators show lowest sensitivity given single-accountability vendor consolidation mandates.
Supply Chain Analysis
Japan and Germany anchor specialized alloy supply for corrosion-resistant pressure-rated steels, while China concentrates domestic manufacturing of monitoring system components under Ministry of Emergency Management GB standards. High-grade metallurgical inputs draw from limited blast furnace capacity in Osaka and Duisburg industrial corridors. Single-source vulnerability persists for subsea robotic inspection platforms where North Sea operators rely on two European specialists. Distribution runs through integrated automation providers who bundle electrification, sensors, and software into consolidated vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pipeline Safety Market sits in early-cycle expansion as hydrogen infrastructure mandates force material compatibility testing and safety system upgrades across converted natural gas corridors.
For Market Incumbents: Compound platform convergence advantages by deepening fiber-optic distributed sensing integration with predictive simulation software. Acquire specialist robotics vendors in the North Sea subsea segment before hydrogen core grid procurement accelerates. Prioritize IEC 62443 certification investment to capture extended validation timelines that disadvantage uncertified competitors.
For New Entrants and Emerging Players: Lead with validated methane quantification algorithms targeting Netherlands and Denmark transmission operators under EU F-Gas Regulation automated reporting mandates. Penetrate India's city gas distribution expansion through local assembly partnerships with Petroleum and Natural Gas Regulatory Board licensees. Deploy subscription-based digital twin offerings to bypass capital-intensive hardware competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core pipeline safety divisions amid portfolio rationalization. Five-to-ten year viability favors vendors with hydrogen compatibility testing capabilities and integrated service contract revenue pools. Watch PHMSA rulemaking velocity as the inflection signal compressing replacement cycle timing for aging cathodic protection systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Combines SCADA telemetry with predictive simulation to open subscription revenue models for German transmission operators. |
| Fiber-Optic Distributed Sensing Deployment | Overlays existing telecommunications rights-of-way to achieve meter-scale leak localization without new trenching in North America. |
| Hydrogen Compatibility Certification | Validates material safety for converted natural gas pipelines under Germany's hydrogen core grid initiative mandates. |
| Integrated Service Contract Consolidation | Bundles hardware, software, and predictive maintenance to reduce interface complexity for North Sea offshore platform operators. |
| IEC 62443 Cybersecurity Compliance | Accelerates control system validation timelines where certified integration specialist scarcity extends procurement cycles. |
Study Parameters
Operator-level perspectives from pipeline integrity managers, SCADA control room engineers, regulatory compliance officers, and procurement directors at transmission system operators anchored the qualitative base. These primary insights combined with secondary validation from PHMSA incident databases, EU ETS methane emissions registries, and industrial equipment customs records. Bottom-up equipment shipment tracking and top-down infrastructure investment forecasts underwent cross-triangulation to align volume estimates.
Sensitivity analysis tested forecast outputs against variable regulatory enforcement intensity and hydrogen infrastructure deployment pacing across the projection horizon. Segmentation dimensions modeled include leak detection technology type, end-user category from oil majors to municipal utilities, service delivery model, and application from transportation corridors to distribution networks. CAGRs derived from historical capital expenditure patterns projected forward through announced infrastructure buildouts and mandated replacement cycles.
The analysis sits within stated boundaries; outcomes outside sustained PHMSA rulemaking momentum or EU Green Deal methane enforcement would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and alloy supply continuity. Recalibration cycles align with material shifts in hydrogen infrastructure procurement velocity and cybersecurity mandate adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Asia-Pacific Industrial Valves Market
Valves
Global Plastic Valves Market
Valves
Mooring Inspection Market
Valves
Vacuum Insulated Pipe Market
Valves
Air Jet Ejectors Market
Valves
Air Vent Heads Market
Valves
Hot Blast Valves Market
Valves
Europe Valves Market
Valves
Global Valves Market
Valves
Global Plug Valve Market
Valves
Pup Joint Market
Valves
Hydraulic Valves Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Pneumatic Positioner Market
Valves
Compressor Valves Market
Valves
Axial and Radial Seals Market