
 China High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
China High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
China High-Voltage Direct Current (HVDC) Transmission Systems Market Outlook
The divergence between ultra-high voltage backbone projects and medium-voltage industrial interties is repositioning procurement standards across China's power sector. State Grid Corporation of China leverages its monopoly on 800 kV and above corridors to dictate converter station specifications nationwide. NR Electric differentiates through domestic control system integration, while Hitachi Energy competes on thyristor valve reliability for the most demanding submarine routes.
High-Voltage Direct Current (HVDC) Transmission Systems employ power electronic converters to transmit bulk electricity across distances exceeding 600 kilometers with losses below 3.5% per 1000 km, primarily serving asynchronous grid interconnection and renewable energy integration. Voltage Source Converter technology leads new project awards due to black-start capability and compact footprint, while Line Commutated Converter installations retain dominance in existing 800 kV ultra-high voltage lines where retrofit economics favor continuity. Component demand concentrates in converter transformers and DC switchgear, where manufacturing lead times now stretch eighteen months and margin pools deepen accordingly.
China's National Energy Administration enforces grid code compliance through GB standards administered by MIIT, while SAMR oversees converter equipment certification under mandatory product safety regimes. These frameworks compel foreign suppliers to localize testing facilities and joint-venture manufacturing to secure project participation. Stakeholders must monitor how provincial dispatch authorities reconcile central government renewable integration mandates with local grid stability constraints as offshore wind penetration accelerates.
Market Dynamics
State Grid Corporation of China's monopoly over 800 kV ultra-high voltage corridors is compressing procurement timelines and forcing converter station specifications toward domestic control system architectures, marginalizing foreign thyristor valve suppliers on all but the most demanding submarine cable routes.
Growth Catalysts
- Dual carbon goals mandate:China's binding carbon neutrality targets by 2060 require massive renewable integration, driving ultra-high voltage backbone expansion to transmit inland wind and solar to coastal load centers.
- Jiangsu and Guangdong offshore clusters:Submarine cable corridors connecting these provinces' offshore wind farms to onshore grids multiply converter station orders for voltage source converter technology.
- Voltage source converter black-start capability:This technical feature enables grid restoration without external power, making it indispensable for islanded offshore platforms and weak-grid connections.
Market Restraints
- Converter transformer manufacturing bottleneck:Eighteen-month lead times for these critical components constrain project execution velocity and inflate working capital requirements for EPC contractors.
- Silicon carbide substrate supply concentration:Domestic Chinese suppliers control limited high-purity substrate volumes, creating vulnerability for power semiconductor module production.
- GB standards compliance friction:Mandatory certification under SAMR-administered regimes forces foreign suppliers into joint-venture structures that dilute margin capture and technology control.
Strategic Opportunities
- Western China renewable export corridors:Xinjiang and Gansu provinces hold stranded wind and solar capacity awaiting ultra-high voltage transmission to eastern demand centers.
- Hybrid AC-DC substation integration:Converging voltage source converter technology with existing AC infrastructure enables phased retrofit of aging 500 kV corridors without full replacement.
- MIIT localization incentives:Domestic content requirements for control systems and protection equipment create captive demand for certified local suppliers.
Industry Challenges
- Power electronics specialist scarcity:Converter station commissioning requires rare expertise in harmonics management and DC fault protection, with training pipelines failing to match deployment timelines.
- Legacy line-commutated converter retrofit complexity:Existing 800 kV corridors demand continuity with thyristor-based systems, complicating technology transitions and spare parts logistics.
- Provincial dispatch authority coordination:Central renewable integration mandates clash with local grid stability constraints as offshore wind penetration accelerates in coastal provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China High-Voltage Direct Current (HVDC) Transmission Systems Market |
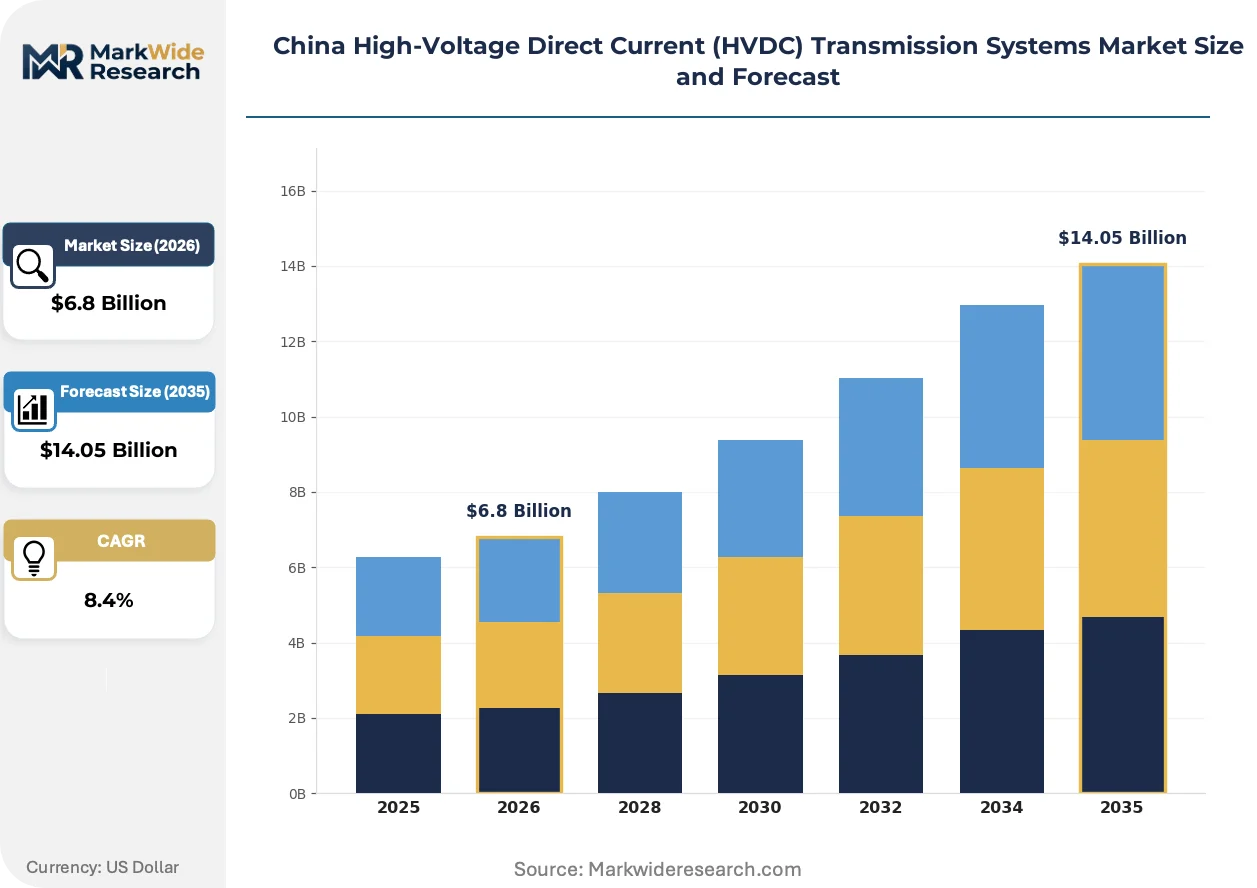
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Hybrid Converter, Others Component: Inverters, Transformers, Switchgear, Cables End User: Utilities, Industrial, Renewable Energy Projects, Railway Electrification Application: Offshore Wind Farms, Interconnection, Power Supply, Grid Stability |
| Companies Covered | State Grid Corporation of China, China Southern Power Grid, Hitachi Energy, NR Electric, TBEA, Siemens Energy, ABB, China XD Group, XJ Group Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China High-Voltage Direct Current (HVDC) Transmission Systems Market Strategic Shifts
Voltage source converter architectures are compressing the competitive landscape for converter station suppliers, while procurement patterns shift toward integrated system packages and away from component-level sourcing.
Modular multilevel converter technology is overtaking conventional two-level voltage source converter designs in new project awards. Offshore wind developers in Jiangsu and Guangdong provinces specify this topology for its superior harmonic performance and reduced filter requirements. The structural consequence is overtaking established suppliers who lack modular multilevel converter engineering depth, consolidating awards among firms with integrated semiconductor and control system capabilities.
GB standards administered by MIIT now mandate localized type testing for all converter equipment above 500 kV. This regulatory shift compels foreign suppliers to establish domestic testing facilities or cede high-voltage segments entirely. Converter transformer manufacturers face the steepest compliance burden, as thermal cycling and impulse test protocols differ materially from IEC baselines.
State Grid Corporation's procurement is consolidating around turn-key converter station contracts that bundle thyristor valves, control systems, and DC switchgear. This purchasing model is displacing component-level tendering that previously allowed specialized suppliers to compete on individual subsystems. The shift is most visible in 800 kV ultra-high voltage projects, where single-source accountability reduces interface risk during commissioning.
China High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
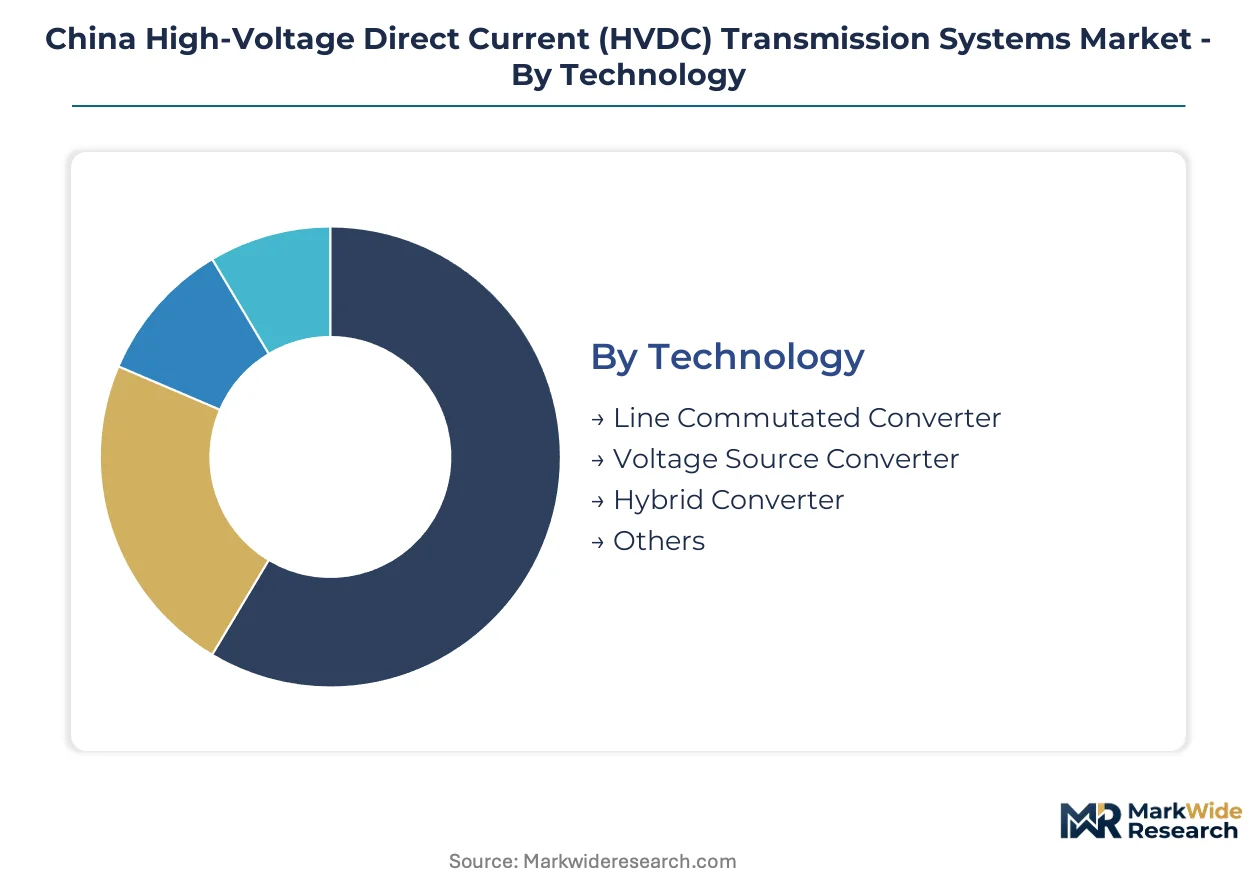
HVDC procurement patterns diverge sharply between standardized ultra-high voltage backbone corridors and customized offshore installations. Segment boundaries determine converter station architecture, component sourcing timelines, and margin capture potential across State Grid Corporation's procurement tiers.
Technology:
Standardized thyristor-based architectures dominate bulk power corridors, while customized voltage source converter designs address weak-grid and black-start requirements.
- Line Commutated Converter:Thyristor-based rectification systems operate at 800 kV and above with mature reliability records. State Grid Corporation specifies this technology for Xinjiang-to-eastern corridor projects where continuous high-capacity transmission outweighs flexibility needs. Retrofit economics favor continuity with existing spare parts inventories.
- Voltage Source Converter:Insulated-gate bipolar transistor modules enable independent reactive power control and compact footprint. Jiangsu and Guangdong offshore wind developers mandate this topology for submarine cable corridors where black-start capability and bidirectional power flow prove essential.
- Hybrid Converter:Combines line-commutated converter economics with voltage source converter flexibility for phased grid upgrades.
- Others:Emerging topologies including alternate arm converters and cascaded H-bridge designs for specialized research installations.
Leading the category by volume: Line Commutated Converter. Growing fastest: Voltage Source Converter.
Component:
Manufacturing lead times and margin concentration vary dramatically across the component stack, with transformer bottlenecks dictating project scheduling.
- Transformers:Converter transformers represent the single largest capital expenditure in station construction, with eighteen-month manufacturing lead times creating critical path constraints. Domestic suppliers capture premium pricing for 800 kV units where GB thermal cycling protocols exceed IEC baselines.
- Switchgear:DC circuit breakers and disconnectors manage fault isolation in multi-terminal configurations. Offshore platform specifications drive demand for gas-insulated designs with compact footprints and marine-grade corrosion resistance.
- Inverters:Power semiconductor modules convert between AC and DC with efficiency above 99% at rated load.
- Cables:Mass-impregnated and extruded insulation systems for submarine and underground corridors.
Margin concentration peaks with transformers. Supply bottleneck severity: transformers, then switchgear.
End User:
Procurement sophistication and technical specification authority concentrate with grid-scale operators, while industrial users pursue captive intertie solutions.
- Utilities:State Grid Corporation and China Southern Power Grid command 800 kV and above corridors with standardized specifications and consolidated tendering. Their procurement velocity determines national installation capacity, with ultra-high voltage project queues extending through renewable integration mandates.
- Renewable Energy Projects:Offshore wind developers in Jiangsu and Guangdong provinces specify voltage source converter stations for submarine export cables. Their technical requirements prioritize black-start capability and compact offshore platform footprint over capital cost minimization.
- Industrial:Aluminum smelters and petrochemical complexes negotiate bilateral interties for price arbitrage and supply security.
- Railway Electrification:Traction power supply authorities adopt medium-voltage DC for high-speed corridor integration.
Volume leadership: Utilities. Specification complexity leader: Renewable Energy Projects.
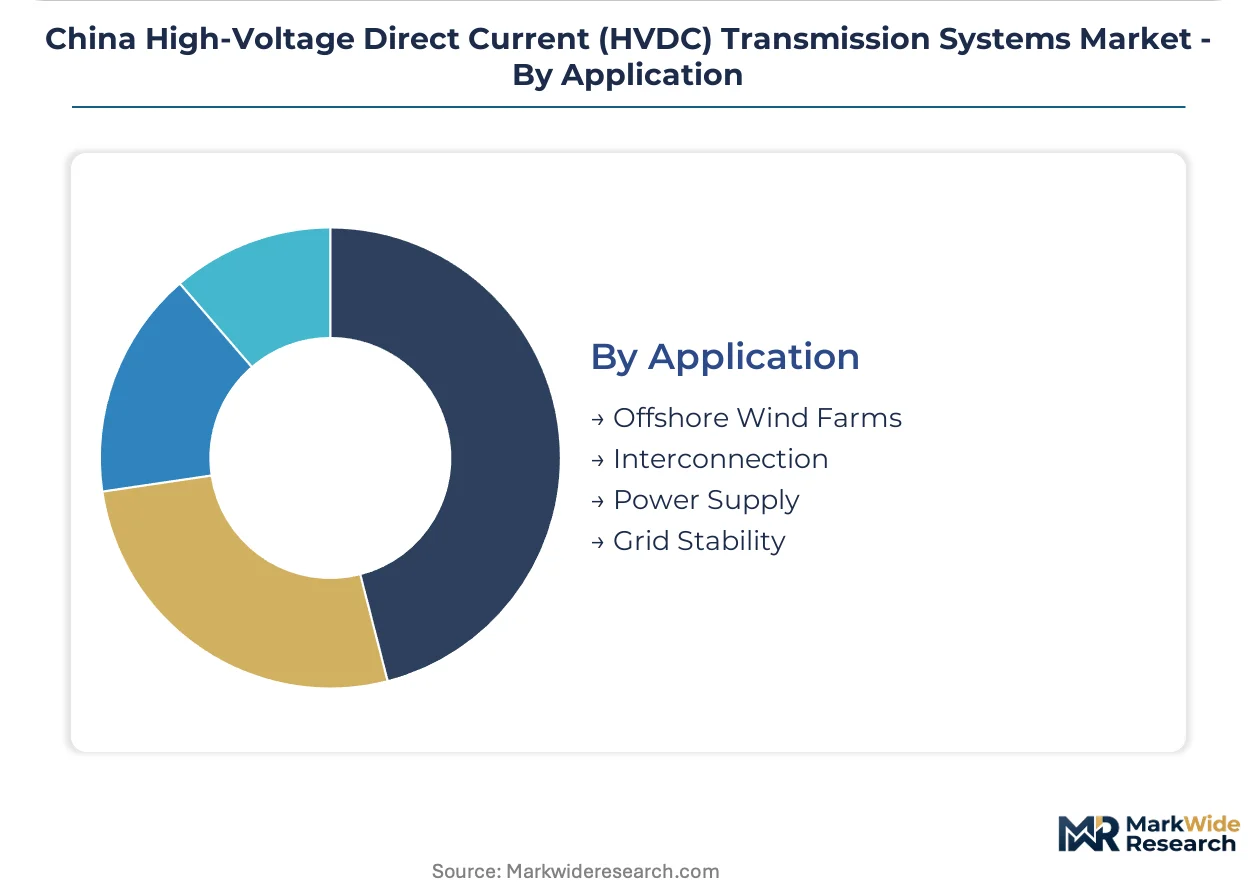
Application:
Geographic concentration and regulatory priority create tiered demand profiles across deployment scenarios.
- Interconnection:Asynchronous grid linking between State Grid and China Southern Power Grid territories, plus cross-border corridors. These projects command highest technical scrutiny for stability coordination across dispatch authority boundaries.
- Offshore Wind Farms:Submarine cable corridors from Jiangsu and Guangdong coastal arrays to onshore substations. MIIT certification requirements and marine environmental permits extend development timelines relative to terrestrial equivalents.
- Power Supply:Bulk transmission from western renewable generation to eastern load centers.
- Grid Stability:Frequency regulation and oscillation damping services through HVDC modulation.
Project scale leader: Interconnection. Deployment velocity leader: Offshore Wind Farms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors converter station manufacturing capacity through integrated semiconductor and transformer fabrication corridors serving the Yangtze River Delta offshore wind cluster.
Jiangsu Province
Offshore wind arrays in the Yellow Sea drive voltage source converter station procurement for submarine export cables. MIIT enforces GB standards compliance for all converter equipment above 500 kV. The Nantong-Rudong corridor hosts multiple converter platform fabrication yards where modular multilevel converter assemblies undergo pre-commissioning.
Guangdong Province
Pearl River Delta load centers absorb bulk western renewable imports through ultra-high voltage backbones terminating at Huizhou and Zhuhai substations. SAMR-administered certification regimes mandate localized type testing for converter transformers. The Yangjiang offshore wind cluster commands specialized black-start capable converter stations for islanded platform operation.
Xinjiang Uygur Autonomous Region
Stranded wind and solar capacity in Hami and Turpan awaits ultra-high voltage transmission to eastern demand centers. State Grid Corporation's monopoly over 800 kV corridor planning dictates converter station specifications. The Zhundong-Huainan line exemplifies bulk power export infrastructure connecting northwestern generation to Anhui province.
Sichuan Province
Hydropower surplus from the Jinsha River basin flows eastward through ultra-high voltage direct current corridors. The dual carbon goals mandate accelerate renewable integration timelines for western generation assets. The Xilingol League-Nanjing corridor originates partially from Sichuan-linked dispatch coordination.
Shandong Province
Bohai Sea offshore wind development drives converter station demand for submarine cable connections to Weihai and Yantai landing points. Provincial dispatch authorities reconcile central renewable mandates with local grid stability constraints. The Shandong peninsula hosts manufacturing facilities for gas-insulated DC switchgear serving marine environments.
China High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across converter station integration depth, with turn-key system suppliers capturing superior returns over component specialists. State Grid Corporation's procurement consolidation around bundled contracts compresses opportunities for subsystem-only vendors. Three archetypes dominate: state-owned grid operators with captive project pipelines, domestic equipment integrators leveraging MIIT localization incentives, and foreign technology licensors competing on thyristor valve reliability for submarine routes. Competitive moves center on backward integration into semiconductor module production and joint-venture manufacturing to satisfy SAMR certification requirements.
Within the state-operator tier, State Grid Corporation of China and China Southern Power Grid occupy positions as monopoly purchasers dictating national specifications. Among domestic equipment specialists, NR Electric exemplifies the control system integration archetype, while TBEA represents transformer-centric manufacturing scale. Hitachi Energy and Siemens Energy sit within the foreign technology licensing tier, anchoring premium positioning on thyristor valve performance for demanding submarine cable applications.
| Leading Market Players |
|---|
| State Grid Corporation of China |
| China Southern Power Grid |
| Hitachi Energy |
| NR Electric |
| TBEA |
| Siemens Energy |
| ABB |
| China XD Group |
| XJ Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers dominate converter transformer manufacturing, compressing procurement timelines for foreign suppliers while MIIT localization mandates harden pricing discipline through captive demand creation.
Pricing Analysis
Throughput-based pricing anchors converter station contracts, with State Grid Corporation bundling thyristor valves, control systems, and DC switchgear into turn-key agreements that reduce interface risk. Three-tier pricing structure across premium, standard, and economy levels separates foreign technology licensors with submarine cable reliability records from domestic integrators meeting GB baseline compliance. Cost compression in standard-tier equipment is intensifying because SAMR certification requirements force joint-venture structures that dilute margin capture. Industrial end-users in aluminum smelting show highest price sensitivity, while offshore wind developers in Jiangsu and Guangdong prioritize black-start capability over capital cost minimization.
Supply Chain Analysis
Silicon carbide substrate supply rests on Japanese and Chinese specialty material producers, with domestic Chinese suppliers controlling limited high-purity volumes for power semiconductor module fabrication. Converter transformers draw from domestic fabrication corridors in Shanghai and Shandong, while insulated-gate bipolar transistor modules feed from South Korean and German semiconductor packaging facilities. Single-source vulnerability concentrates in eighteen-month lead time components where thermal cycling test protocols exceed IEC baselines. Distribution runs through State Grid Corporation's consolidated tendering platforms, with provincial dispatch authorities managing downstream allocation to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT-administered GB standards create a cost-of-compliance moat that favors certified domestic suppliers and joint-venture structures, marginalizing unlocalized foreign competitors from 500 kV and above segments.
For Market Incumbents: Hedge against thyristor valve commoditization by backward integration into semiconductor module production and captive control system development. NR Electric's domestic integration archetype demonstrates margin defense against Hitachi Energy's premium submarine positioning. Capacity addition in Nantong-Rudong converter platform fabrication yards reinforces project execution velocity.
For New Entrants and Emerging Players: Aluminum smelter bilateral intertie developers represent an underserved buyer archetype with price-sensitive procurement and limited incumbent saturation. Hybrid AC-DC substation retrofits in aging 500 kV corridors offer the most penetrable application segment. Licensing modular multilevel converter engineering depth from research institutes provides a defensible go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor control system specialists with SAMR certification and joint-venture manufacturing footprints in Yangtze River Delta clusters. Long-term viability hinges on dual carbon goal execution through 2060 with renewable integration mandates sustaining demand. Watch provincial dispatch authority coordination failures as an inflection indicator for project delay risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Modules | Captive silicon carbide substrate supply reduces dependency on Japanese specialty material producers. |
| Joint Venture Manufacturing Establishment | SAMR certification compliance enables participation in 800 kV ultra-high voltage corridor tenders. |
| Modular Multilevel Converter Engineering Investment | Jiangsu and Guangdong offshore wind specifications favor suppliers with integrated topology capabilities. |
| Control System Localization Certification | MIIT incentives create captive demand for domestically certified protection equipment suppliers. |
| Converter Platform Fabrication Capacity Expansion | Nantong-Rudong pre-commissioning yards accelerate project timelines for submarine cable corridors. |
Study Parameters
Independent corroboration across State Grid Corporation procurement officers, EPC contractor project directors, and converter transformer plant managers underwrites the qualitative findings. Primary interviews with offshore wind developers in Jiangsu and Guangdong, MIIT standards administrators, and power semiconductor module procurement leads combined with secondary validation from NEA renewable integration mandates, SAMR certification registries, and provincial dispatch authority filings. Bottom-up project pipeline enumeration and top-down national capacity targets triangulate market sizing.
Comparable-period anchoring to historical ultra-high voltage corridor commissioning rates and offshore wind capacity additions established the forecast window baseline. Segmentation modeling across technology topology, component category, end-user archetype, and application scenario with regional grid type differentiation generated volume and value outputs. CAGRs derived from project queue analysis and manufacturing capacity expansion schedules incorporated converter transformer lead time constraints and silicon carbide substrate supply availability.
Revisions become necessary when provincial dispatch authority coordination failures disrupt offshore wind integration timelines or SAMR certification protocols shift materially. Forecasts reflect documented assumptions regarding State Grid Corporation procurement consolidation and dual carbon goal execution continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market