
 United States (US) MEP Services Market | 2026-2036
United States (US) MEP Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States (US) MEP Services Market Analytics
Cross-linked polyethylene (PEX) piping is hardening its position against copper in commercial plumbing specifications across the US, cutting material costs and installation labor for large-scale projects. Jacobs Engineering Group Inc. leverages its federal contracting footprint to dominate military and institutional MEP work. Burns & McDonnell anchors its growth in utility-scale power and industrial mechanical systems. AECOM Technology Corporation extends its reach through integrated design-build delivery on infrastructure megaprojects.
United States MEP Services encompass the engineering, design, installation, and commissioning of building systems including HVAC with specified airflow rates of 500–2,000 cubic feet per minute per ton of cooling capacity, electrical distribution up to 480V three-phase for commercial facilities, and plumbing networks designed to 80 psi operating pressure. The primary purpose is ensuring safe, efficient, and code-compliant building operations across occupied structures. Electrical service type leads revenue contribution due to datacenter power density requirements exceeding 50 kW per rack. New construction installation type captures the largest project value pool, though renovation and retrofitting segments expand fastest as building electrification mandates tighten across jurisdictions.
OSHA safety standards, the National Electrical Code (NEC) administered by the National Fire Protection Association, and ASHRAE 90.1 energy standards collectively shape contractor licensing, system design thresholds, and equipment specification minimums across US states. The Inflation Reduction Act's Section 179D deductions directly stimulate retrofit demand by improving project returns for energy-efficient MEP upgrades. Stakeholders must monitor evolving state-level stretch codes and utility incentive programs that increasingly require modeled energy performance guarantees rather than prescriptive equipment compliance.
Market Dynamics
Data center power density requirements exceeding 50 kW per rack are compressing project timelines and forcing electrical contractors to pre-integrate modular substations before site delivery. This structural pressure is reshaping competitive positioning toward firms with in-house fabrication capabilities.
Growth Catalysts
- Inflation Reduction Act Section 179D:Commercial building owners in Texas and Virginia now capture accelerated depreciation for deep energy retrofits, redirecting capital toward full MEP system replacements.
- Cross-linked polyethylene piping:PEX systems cut installation labor hours by eliminating soldering requirements, accelerating adoption in Austin and Dallas-Fort Worth megaprojects.
- Northern Virginia data center cluster:Ashburn and Loudoun County zoning approvals for hyperscale facilities are generating contiguous demand for integrated design-build MEP contracts at unprecedented scale.
Market Restraints
- Copper price volatility:Electrical contractors face margin compression when commodity spikes occur between bid submission and material procurement.
- Skilled electrician concentration:Licensed journeyman availability concentrates in Texas and California, leaving Mountain States projects exposed to wage inflation and schedule risk.
- ASHRAE 90.1 stringency:Model code adoption lags across southeastern states, fragmenting equipment specification requirements for national MEP firms.
Strategic Opportunities
- Electrification retrofits in legacy commercial stock:Chicago and New York City building performance standards are mandating fossil fuel phase-outs, creating white space for thermal system replacement specialists.
- Utility incentive program stacking:Pacific Gas & Electric and Dominion Energy now permit combined rebates for integrated HVAC-electrical upgrades, improving project returns.
- Building information modeling convergence:MEP contractors pairing BIM with prefabrication are capturing design-build contracts that traditional bid-spec firms cannot execute.
Industry Challenges
- Master electrician certification timelines:Apprenticeship completion requirements extending to 8,000 hours in California and New York are constraining workforce expansion.
- Legacy control system integration:BACnet and Modbus protocol incompatibilities between existing building automation and new smart equipment are extending commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States (US) MEP Services Market |
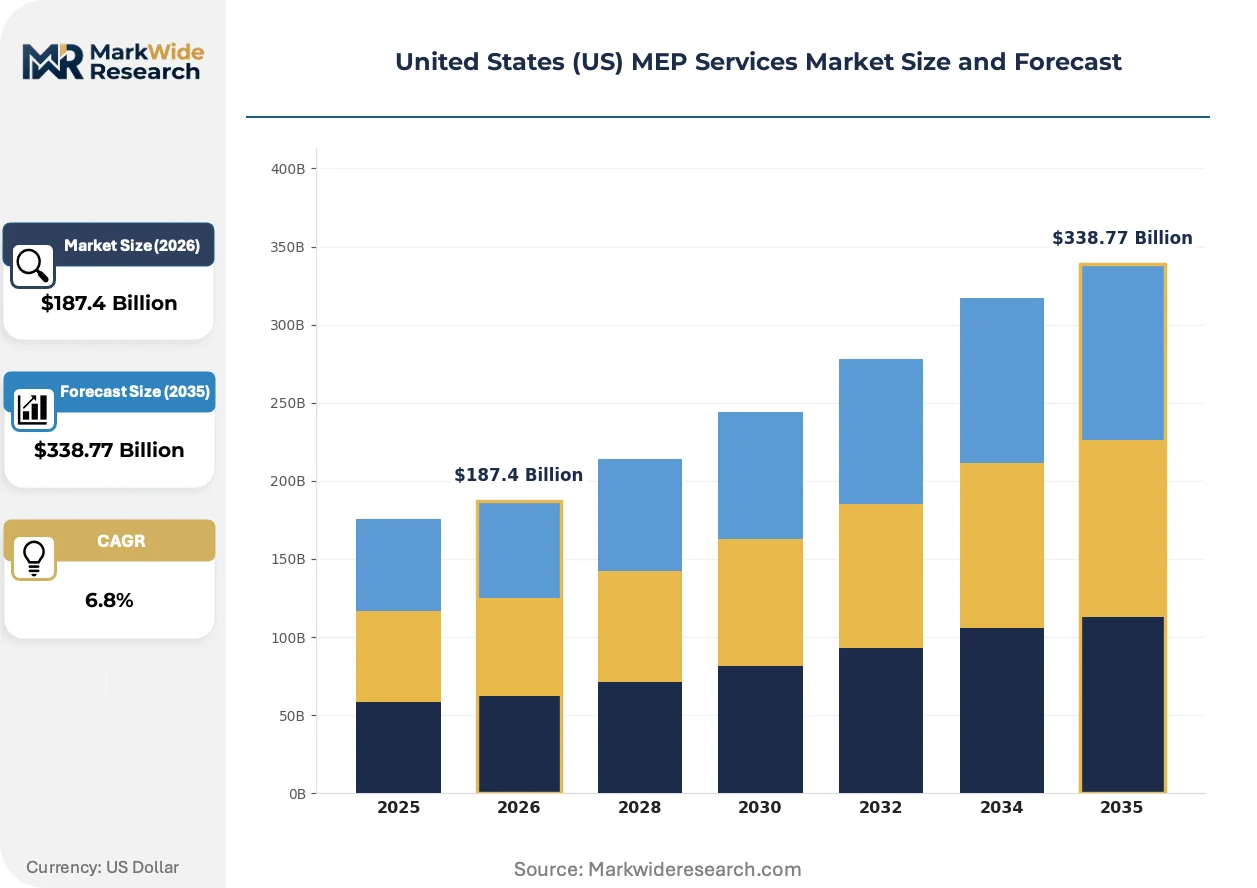
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical, Electrical, Plumbing, Fire Protection End User: Commercial, Residential, Industrial, Institutional Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Installation Type: New Construction, Renovation, Retrofitting, Maintenance |
| Companies Covered | AECOM Technology Corporation, Burns & McDonnell, Jacobs Engineering Group Inc., Jensen Hughes, Tetra Tech, WSP USA, Arup Group, IMEG, HDR Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States (US) MEP Services Market Evolving Landscape
Prefabrication and modular assembly are compressing field installation hours while raising the technical bar for contractor capabilities. Three distinct shifts are restructuring how MEP services are procured and delivered.
Modular electrical rooms are overtaking traditional stick-built substations in data center construction. These factory-assembled units integrate switchgear, transformers, and bus duct in controlled environments. Hyperscale operators in Northern Virginia now specify skid-mounted solutions for 80% of new capacity additions. This shift is overtaking conventional electrical contractors lacking fabrication partnerships or in-house panel shops.
OSHA's updated National Emphasis Program on heat-related hazards is tightening safety protocol enforcement across southern states. Inspection frequency has risen for outdoor mechanical installation crews in Texas and Arizona. Contractors are responding with mandatory hydration monitoring and adjusted shift scheduling, adding 3-5% to labor cost structures in affected jurisdictions.
Integrated project delivery contracts now dominate Texas megaproject procurement, displacing design-bid-build sequences. Owner-operators in Austin and Dallas-Fort Worth are bundling MEP design, installation, and commissioning under single-accountability agreements. This concentration is most visible in life science and advanced manufacturing verticals where schedule certainty outweighs first-cost minimization.
United States (US) MEP Services Market Segmentation
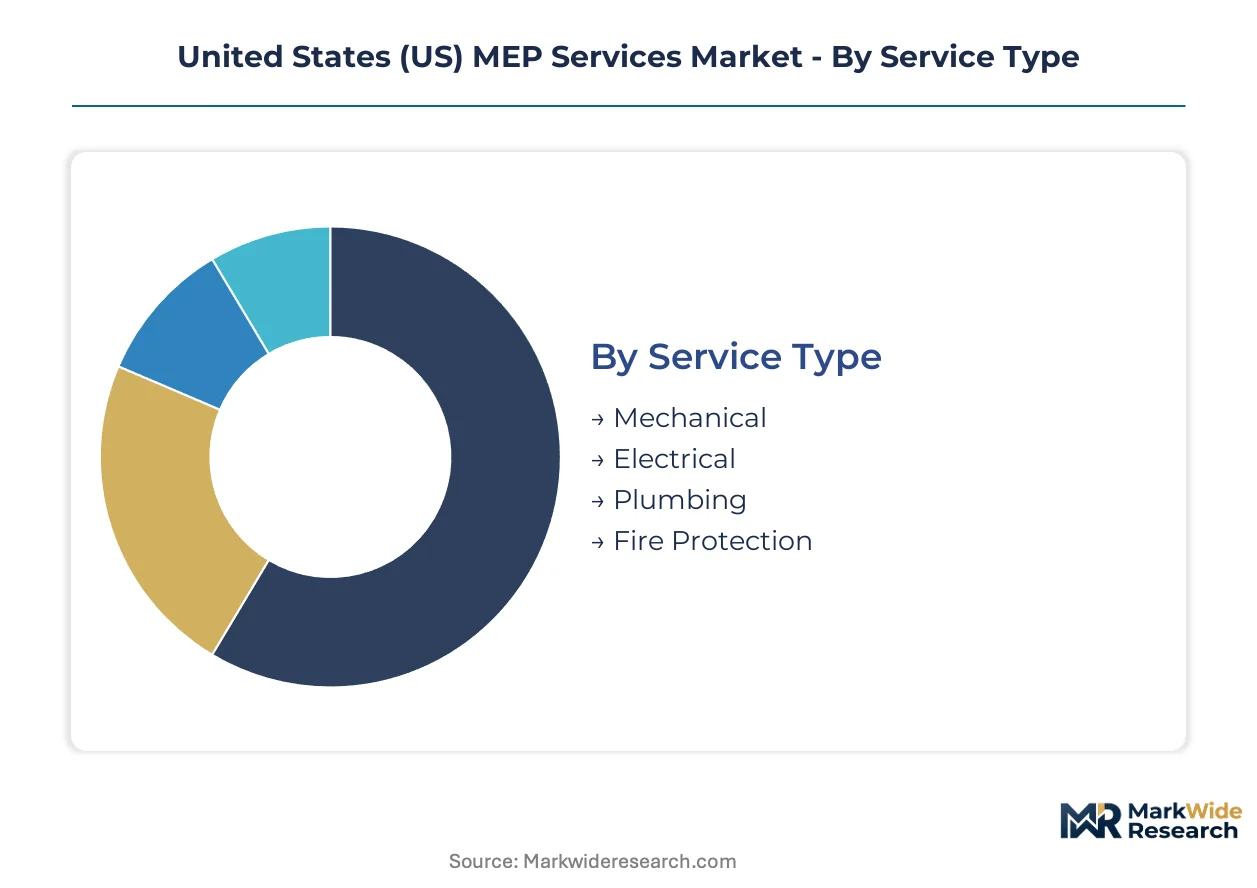
MEP service procurement in the US fragments across technical specializations, building typologies, and project scales. Each segmentation axis carries distinct regulatory burdens, margin profiles, and competitive dynamics that reshape contractor positioning.
Service Type:
OSHA, NFPA, and ASHRAE certification requirements vary sharply across mechanical, electrical, and plumbing disciplines, with electrical contractors facing the steepest licensing barriers and mechanical specialists navigating the most complex energy code compliance.
- Mechanical:HVAC and ventilation systems designed to ASHRAE 90.1 airflow specifications of 500–2,000 CFM per ton. Demand concentrates in Northern Virginia data centers where cooling density requirements exceed 50 kW per rack, forcing specialized thermal engineering capabilities.
- Electrical:Power distribution and control systems up to 480V three-phase commercial service. NEC compliance and master electrician certification requirements create the highest barrier to entry, with Texas and California journeyman concentration leaving Mountain States exposed to wage inflation.
- Plumbing:PEX piping networks operating at 80 psi design pressure with cross-linked polyethylene displacing copper specifications. Austin and Dallas-Fort Worth megaprojects drive adoption for labor-hour reduction through solderless installation.
- Fire Protection:Sprinkler and suppression systems governed by NFPA 13 and local amendments. Institutional and high-rise commercial codes mandate integrated MEP coordination for life safety system commissioning.
Leading the category by volume: Electrical. Growing fastest: Mechanical.
End User:
Building typology determines procurement sophistication, with institutional clients demanding bonded performance guarantees and commercial owners prioritizing speed-to-market over first-cost minimization.
- Commercial:Office, retail, and hospitality buildings where Section 179D deductions redirect capital toward deep energy retrofits. Chicago and New York City building performance standards mandate fossil fuel phase-outs, creating thermal system replacement demand.
- Residential:Single-family and multifamily housing where PEX adoption cuts both material and labor costs. Production homebuilders in Texas and Florida drive standardized MEP package procurement.
- Industrial:Manufacturing and processing facilities requiring utility-scale power and specialized mechanical systems. Burns & McDonnell anchors growth in this vertical through captive relationships with heavy industrial operators.
- Institutional:Government, healthcare, and education buildings where federal contracting footprints dominate. Jacobs Engineering leverages its military and institutional presence for design-build MEP capture.
Commercial commands the largest project value pool. Industrial expands most quickly on reshoring-driven manufacturing construction.
Project Size:
Scale tier determines delivery methodology, with mega projects forcing integrated design-build contracts and small-scale work remaining vulnerable to commodity price volatility between bid and procurement.
- Small Scale:Tenant improvements and facility repairs under $500,000 where local electrical contractors compete on speed and relationship depth.
- Medium Scale:Standalone buildings and campus additions where regional MEP firms balance in-house engineering with subcontracted specialty trades.
- Large Scale:Multi-building developments and infrastructure packages where BIM-enabled prefabrication separates competitive tiers.
- Mega Projects:Life science and advanced manufacturing campuses in Austin and Dallas-Fort Worth where single-accountability IPD contracts displace design-bid-build sequences.
Mega projects concentrate the highest-margin work. Medium-scale activity provides the steadiest backlog for regional contractors.
Installation Type:
Project origin—ground-up versus existing building—shapes technical risk profiles, with retrofit work demanding legacy system integration expertise that stick-built contractors often lack.
- New Construction:Greenfield development where modular electrical rooms and prefabricated MEP assemblies compress field schedules. Northern Virginia data centers specify skid-mounted substations for 80% of capacity additions.
- Renovation:Building modernization where ASHRAE 90.1 stringency upgrades force equipment replacement without full system redesign.
- Retrofitting:Deep energy retrofits capturing stacked utility incentives from Pacific Gas & Electric and Dominion Energy for integrated HVAC-electrical upgrades.
- Maintenance:Ongoing service contracts where BACnet and Modbus protocol incompatibilities between legacy automation and smart equipment extend commissioning periods.
New construction captures the largest absolute value. Retrofitting climbs fastest as electrification mandates tighten across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's Section 179D tax deduction zones concentrate MEP retrofit investment across high-energy-cost states, redirecting capital from coasts toward Sun Belt construction corridors.
Texas
Austin and Dallas-Fort Worth megaprojects drive integrated design-build demand for life science and advanced manufacturing campuses. State licensing requirements for master electricians remain less stringent than coastal counterparts, expanding available workforce pools. The Interstate 35 corridor hosts contiguous development requiring full MEP coordination at unprecedented scale.
Virginia
Ashburn and Loudoun County hyperscale data center approvals generate concentrated demand for modular electrical room fabrication. Dominion Energy utility incentive programs permit stacked rebates for integrated HVAC-electrical upgrades. Northern Virginia now specifies skid-mounted substations for the majority of new capacity additions.
California
Los Angeles and San Francisco building performance standards mandate fossil fuel phase-outs, creating thermal system replacement demand. Pacific Gas & Electric incentive stacking improves project returns for deep energy retrofits. Silicon Valley data center expansion compresses electrical contractor timelines through pre-integrated modular delivery.
New York
New York City Local Law 97 carbon caps accelerate commercial building electrification retrofits. State master electrician certification requirements extending to 8,000 hours constrain workforce expansion against demand. The Hudson Valley corridor sees concentrated life science facility construction requiring IPD contract structures.
Illinois
Chicago building performance standards drive thermal system replacement in legacy commercial stock. Commonwealth Edison utility programs support integrated MEP upgrades with performance-guarantee requirements. The I-55 industrial corridor attracts reshoring manufacturing construction demanding utility-scale power distribution.
United States (US) MEP Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with design-build integrators capturing premium-tier contracts while regional electrical contractors compete on speed for small-scale tenant improvements. The vendor base organizes around three strategic archetypes: federal contracting specialists leveraging military relationships, utility-scale power firms anchoring industrial mechanical systems, and infrastructure integrators bundling design-build delivery. Dominant competitive moves include in-house fabrication capability acquisition and integrated project delivery partnership formation.
Among federal-contracting specialists, Jacobs Engineering Group Inc. occupies a position exemplifying military and institutional MEP capture. Burns & McDonnell represents the utility-scale power archetype through captive industrial operator relationships. AECOM Technology Corporation anchors the infrastructure integrator tier, with its design-build bundling capability separating competitive positioning on megaprojects.
| Leading Market Players |
|---|
| AECOM Technology Corporation |
| Burns & McDonnell |
| Jacobs Engineering Group Inc. |
| Jensen Hughes |
| Tetra Tech |
| WSP USA |
| Arup Group |
| IMEG |
| HDR Inc. |
| Others |
Value Network & Pricing Analysis
ASHRAE 90.1 energy standards gate qualified supply and premium-tier pricing access for MEP contractors, separating firms with certified thermal engineering capabilities from commodity competitors locked into prescriptive equipment bidding wars. Compliance investment creates tiered market access where certified contractors command design-build premiums while uncertified players compete on labor rates alone.
Pricing Analysis
Lead-time-driven pricing stratification rewards contractors with in-house fabrication capabilities, with Northern Virginia data center operators paying premiums for pre-integrated modular electrical rooms against spot-market stick-built alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentiation. Cost compression in standard-tier electrical contracting is intensifying because copper price volatility between bid submission and procurement erodes fixed-price margins. Commercial building owners show highest price sensitivity on first-cost minimization, while life science developers prioritize schedule certainty over unit economics.
Supply Chain Analysis
Licensed journeyman electrician availability concentrates in Texas and California manufacturing geographies, leaving Mountain States projects exposed to wage inflation and procurement delays. MEP service delivery draws from copper and cross-linked polyethylene piping inputs, alongside modular substation assemblies and smart building automation components. Single-source vulnerability runs through concentrated master electrician certification pipelines where California and New York's 8,000-hour apprenticeship requirements constrain workforce expansion. Distribution runs through regional electrical contractors for small-scale tenant improvements, with national design-build integrators capturing mega-project direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
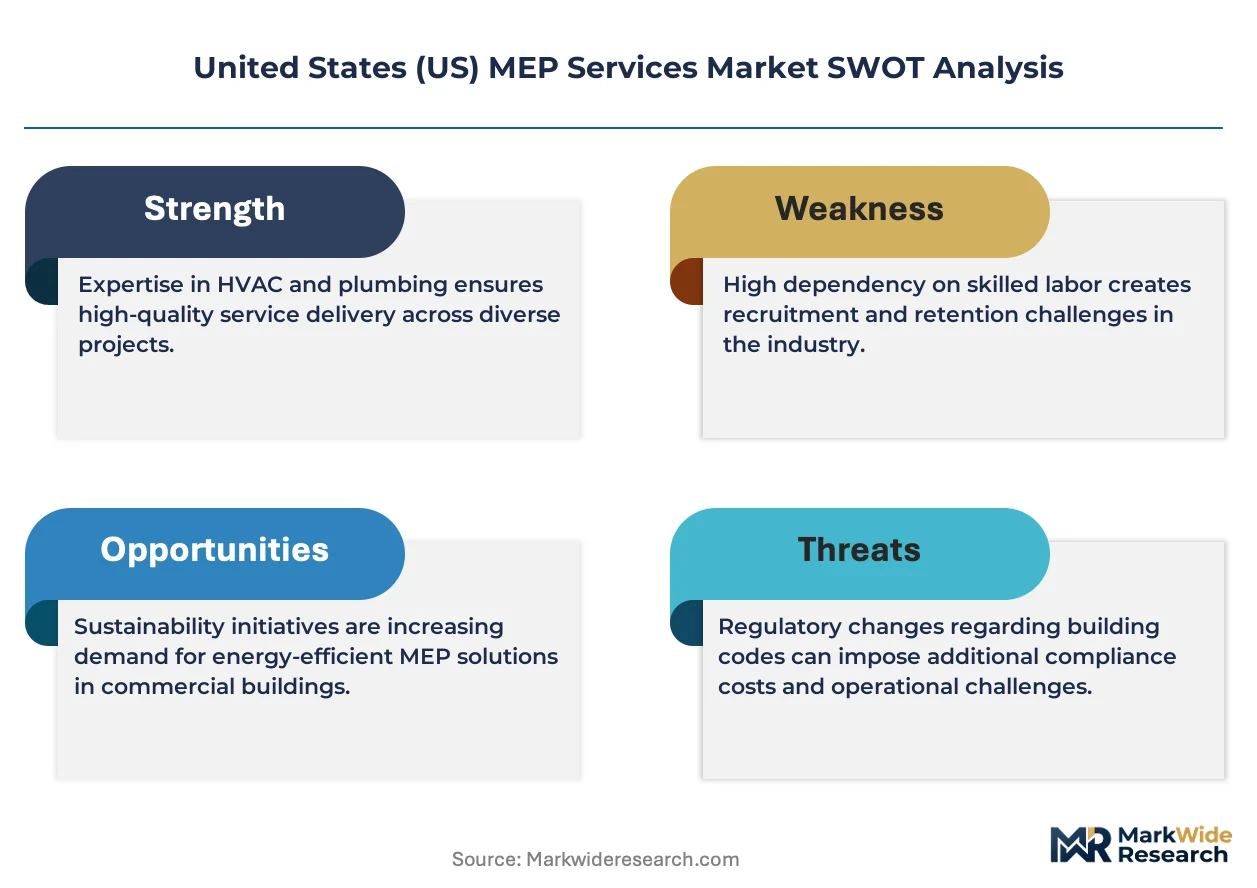
This market reads as a cost-of-compliance story where OSHA safety standards and NEC certification requirements create barrier-to-entry moats for compliant players, insulating established contractors from price-based competition.
For Market Incumbents: Lock in prefabrication partnerships or in-house panel shop acquisitions before modular electrical room specifications harden across Northern Virginia and Texas megaprojects. Threat substitution from BIM-enabled prefabrication specialists demands captive fabrication capability, while vertical integration into skid-mounted substation production secures margin capture against commodity electrical contractors. For New Entrants and Emerging Players: Capture white space in Chicago and New York City thermal system replacement demand created by building performance standard mandates, where legacy fossil fuel phase-outs outpace incumbent contractor capacity. Electrification retrofit specialization in legacy commercial stock offers the most penetrable segment, with go-to-market positioning around stacked utility incentive program navigation differentiating from full-service generalists. For Investors and Strategic Acquirers: Dominion Energy and Pacific Gas & Electric incentive program expansion is the leading indicator that integrated HVAC-electrical upgrade bundling will concentrate market share among design-build capable platforms. Long-term viability favors acquisition targets with federal contracting footprints and military-institutional relationships, where Jacobs Engineering's positioning exemplifies defensible revenue anchoring. Signal to watch: state-level stretch code adoption accelerating modeled performance guarantee requirements over prescriptive compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capability Acquisition | In-house panel shops secure modular electrical room contracts from Dominion Energy-served hyperscale operators. |
| Federal Contracting Footprint Expansion | Military and institutional relationships mirror Jacobs Engineering's captive design-build capture mechanism. |
| Utility Incentive Program Stacking | Combined Pacific Gas & Electric rebates improve project returns for integrated HVAC-electrical upgrade specialists. |
| BIM-Enabled Design-Build Partnership | Integrated project delivery contracts in Austin and Dallas-Fort Worth displace traditional bid-spec competitors. |
| Master Electrician Apprenticeship Pipeline | California and New York certification requirements demand captive workforce development against journeyman scarcity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with MEP contractors, electrical engineering directors, utility program administrators, and commercial real estate developers with bottom-up and top-down triangulation. OSHA enforcement databases, NEC adoption tracking by the National Fire Protection Association, ASHRAE standards documentation, and state licensing board records provided secondary validation layers.
Granularity-level modeling addressed service type, end user building typology, project scale tier, and installation origin across the projection horizon, with CAGRs derived from segment-level demand buildup and macroeconomic sensitivity testing. Forecast inputs incorporated Inflation Reduction Act Section 179D utilization rates, data center power density specifications, and regional journeyman electrician supply constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper commodity volatility, state-level stretch code adoption velocity, and master electrician certification requirement changes. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Geosteering Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Geophysical Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Architectural Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Pipeline Installation Services Market