
 India Engineering, Procurement, and Construction Management (EPCM) Market | 2026-2036
India Engineering, Procurement, and Construction Management (EPCM) Market Size, Share, and Industry Trends Forecast 2026-2036
India Engineering, Procurement, and Construction Management (EPCM) Market Insights
Project finance through infrastructure investment trusts is reconfiguring capital deployment across India's EPCM landscape. Larsen & Toubro leverages its balance-sheet depth to anchor large-scale hydrocarbon and metro contracts. Tata Projects competes through integrated design-build capability in industrial and urban infrastructure. Afcons Infrastructure specializes in complex marine and tunnelling works, sustaining premium positioning in technically demanding segments.
Engineering, Procurement, and Construction Management denotes a unified contracting framework where a single entity assumes responsibility for front-end design, vendor selection, material procurement, and on-site construction execution, typically governed by milestone-based payment schedules and liquidated damages clauses. Its primary purpose is to transfer schedule, cost, and performance risk from asset owners to a consolidated contractor, thereby reducing coordination failure in capital-intensive installations. Project Management services command the deepest margin pools due to scarce qualified manpower and long-term client retention, while Mega Projects represent the fastest-expanding size category as India's National Infrastructure Pipeline channels sovereign capital into refineries, airports, and semiconductor fabs. Design-Build delivery models are displacing traditional Design-Bid-Build structures in power generation and industrial applications where speed-to-commissioning determines project returns.
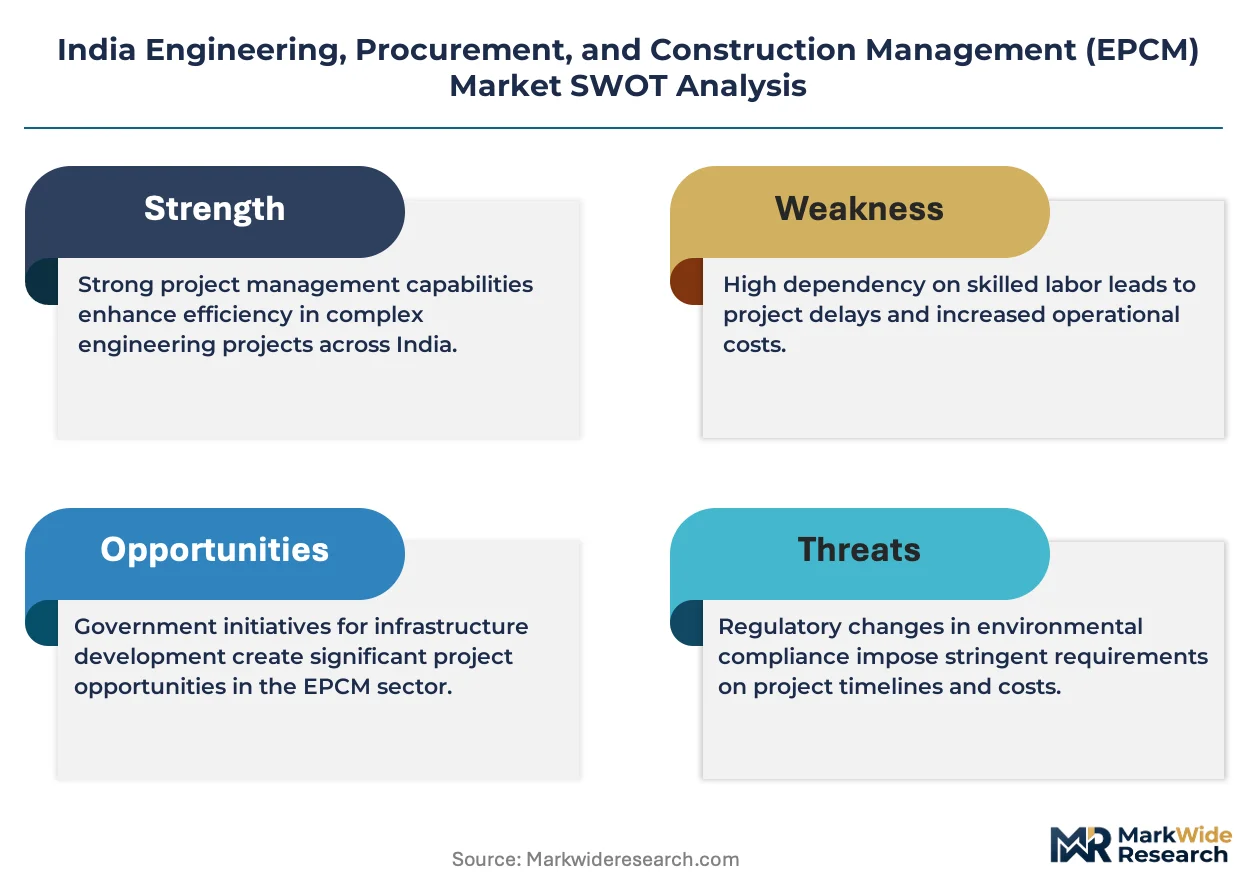
BIS certification requirements for structural steel and concrete quality, combined with CEA technical standards for power plant commissioning, are elevating compliance costs and filtering out undercapitalized regional contractors. The PLI scheme administered by DPIIT is reshaping domestic procurement obligations, pressuring EPCM firms to deepen local supplier networks. Stakeholders must monitor how impending amendments to the Arbitration and Conciliation Act affect dispute-resolution timelines and working-capital intensity across long-duration contracts.
Market Dynamics
India's National Infrastructure Pipeline channels sovereign capital into refineries, airports, and semiconductor fabs, compressing contractor selection timelines and elevating single-point accountability requirements for EPCM providers bidding on mega-scale installations.
Growth Catalysts
- PLI Scheme for Specialty Steel:The DPIIT-administered production-linked incentive compresses input costs for domestic contractors, improving bid competitiveness against foreign rivals on hydrocarbon and power infrastructure tenders.
- Maharashtra State Infrastructure Buildout:State-led highway and metro rail expansions concentrate EPCM demand in India's most industrialized corridor, creating predictable contract pipelines for qualified bidders.
- Semiconductor Fabrication Entry:India's push into chip manufacturing generates demand for ultra-cleanroom construction and specialized utility systems, requiring EPCM firms with advanced clean-build credentials.
Market Restraints
- Cement Price Volatility:Input cost swings for Portland cement and ready-mix concrete compress fixed-price contract margins, forcing contractors to load escalation clauses or absorb working-capital strain.
- Specialized Equipment Import Dependence:Heavy-lift cranes and tunnel-boring machines concentrate supply with German, Japanese, and Chinese OEMs, exposing project schedules to forex fluctuation and shipping bottlenecks.
- Arbitration Timeline Uncertainty:Pending amendments to India's Arbitration and Conciliation Act extend dispute-resolution horizons, elevating working-capital intensity for contractors locked in milestone-payment structures.
Strategic Opportunities
- Gujarat Petrochemical Corridor Expansion:Dahej and Hazira clusters attract downstream chemical investments, creating demand for integrated EPCM services across process units, storage, and marine terminals.
- InvIT Capital Deployment:Infrastructure investment trusts unlock institutional capital for operational assets, enabling EPCM firms to transition into long-term asset-management contracts post-construction.
- Green Hydrogen Electrolyzer Manufacturing:India's renewable hydrogen targets generate demand for gigawatt-scale electrolyzer fabrication facilities, requiring EPCM capabilities in high-purity gas handling and renewable integration.
Industry Challenges
- Commissioning Engineer Scarcity:CEA-mandated certification for power plant commissioning creates bottlenecks, extending project handover timelines and elevating manpower costs for thermal and renewable generation contracts.
- BIS Compliance Burden:Structural steel and concrete quality certification requirements filter undercapitalized regional contractors, consolidating bid pools but stretching accredited firms across multiple concurrent certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Engineering, Procurement, and Construction Management (EPCM) Market |
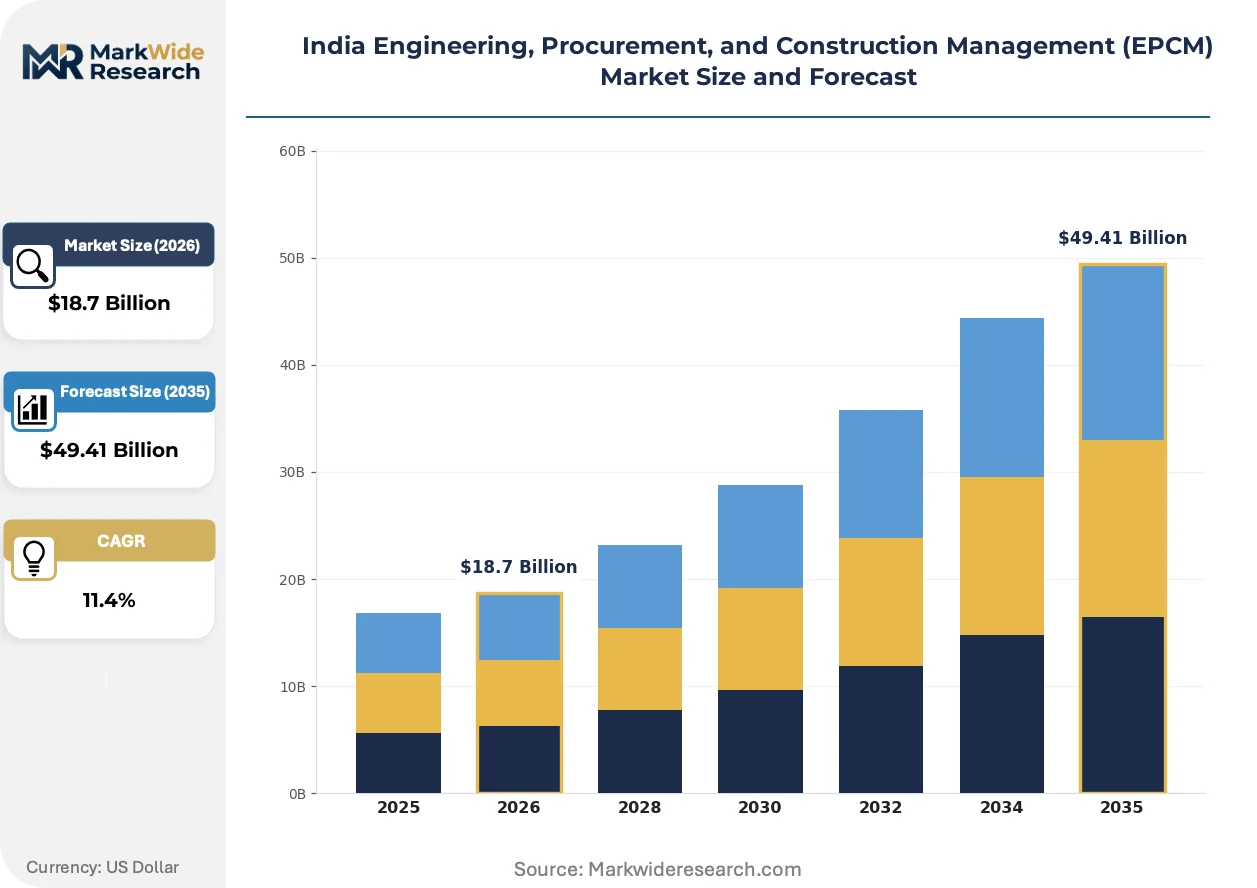
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Procurement, Project Management End User: Oil & Gas, Power Generation, Infrastructure, Industrial Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Delivery Model: Design-Bid-Build, Design-Build, Construction Management, Integrated Project Delivery |
| Companies Covered | Larsen & Toubro, Tata Projects, Reliance Infrastructure, GMR Group, Megha Engineering and Infrastructures Ltd, Hindustan Construction Company, Afcons Infrastructure, Engineers India Limited, Punj Lloyd Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Engineering, Procurement, and Construction Management (EPCM) Market Trends and Innovations
Digital construction technologies and modular fabrication methods are compressing project delivery timelines across India's power and industrial infrastructure sectors. Regulatory pressure on quality assurance and environmental compliance is simultaneously elevating technical entry barriers.
Building information modeling platforms are digitizing design coordination and clash detection across multi-discipline engineering teams. State-owned power utilities and private refinery operators are mandating BIM deliverables for contracts above threshold values, compressing pre-construction revision cycles and reducing field change orders. This digitizing of project workflows is compressing traditional document-control margins for EPCM firms lacking in-house modeling capabilities.
BIS certification requirements for structural steel grades and concrete mix designs are elevating quality-assurance costs across highway and metro rail contracts. The Bureau of Indian Standards mandates third-party testing for critical structural elements, extending procurement lead times but reducing post-construction defect liability. Industrial and transportation infrastructure segments bear the heaviest compliance burden, with contractors absorbing testing costs or embedding premiums in lump-sum bids.
Asset owners are unbundling long-term operations and maintenance contracts from initial construction awards, compressing EPCM scopes to design-build handover. Power generation and petrochemical clients now prefer separate O&M procurement, forcing construction contractors to compete on capital-cost efficiency alone rather than lifecycle value propositions. This pattern concentrates most visibly in Gujarat and Maharashtra, where institutional investors acquiring operational assets demand clean contractual separation between construction and operational phases.
India Engineering, Procurement, and Construction Management (EPCM) Market Segmentation
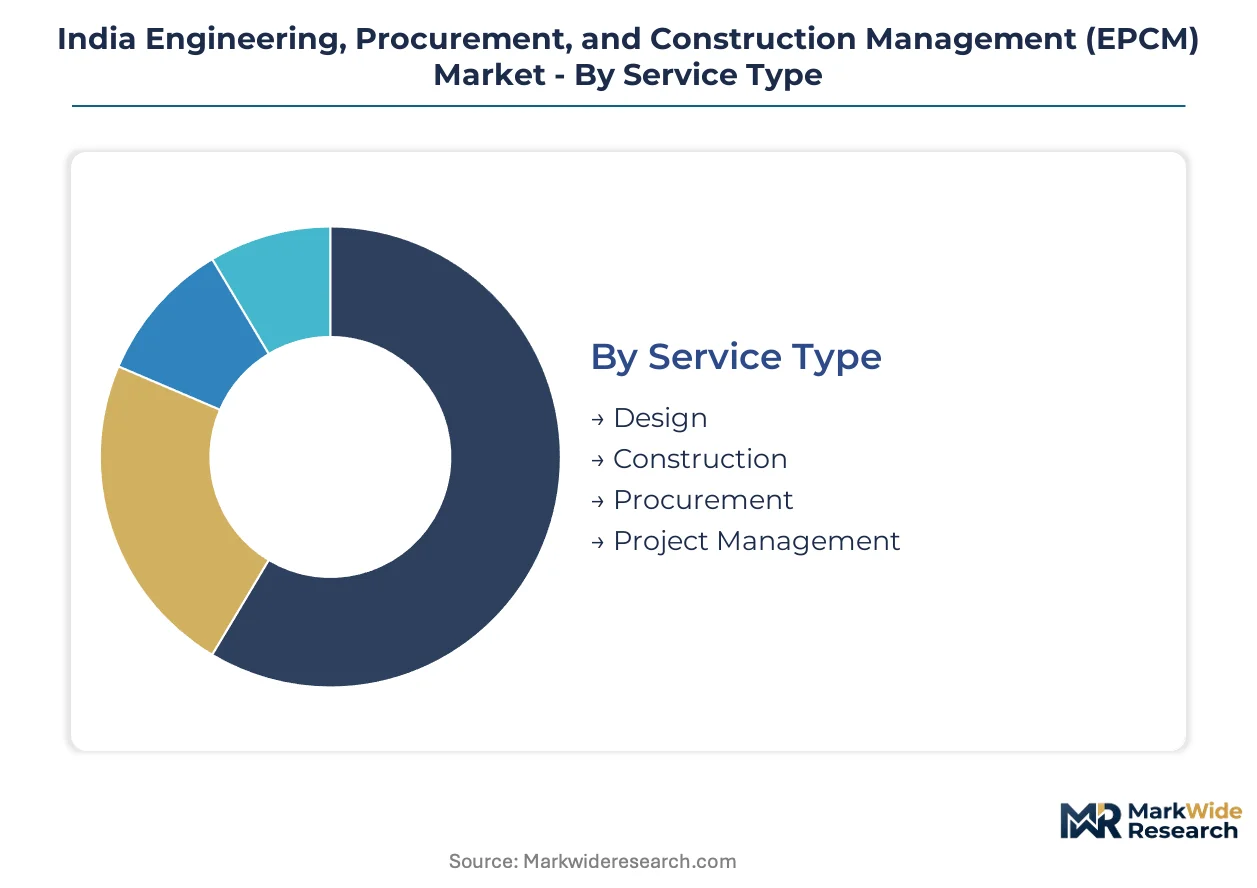
EPCM service segmentation in India reveals how contract structures and project characteristics dictate capability requirements, risk allocation, and margin profiles across distinct buyer clusters. Understanding these divisions exposes where specialized engineering expertise commands premium positioning versus where scale economies dominate competitive outcomes.
Service Type:
After-sales service intensity varies dramatically across EPCM service lines, with ongoing operational support obligations creating divergent working-capital demands and client retention economics.
- Project Management:Comprehensive oversight of schedule, cost, and quality parameters across multi-contractor environments. Maharashtra metro rail and Gujarat refinery expansions concentrate demand here, as public-sector clients prioritize single-point accountability for complex, multi-year installations. Scarce qualified manpower and CEA-mandated commissioning certifications sustain the deepest margin pools in this segment.
- Construction:Physical execution of civil, structural, and mechanical works with milestone-based payment structures. Cement price volatility and BIS certification requirements for structural steel compress margins, forcing contractors to absorb testing costs or embed escalation premiums in fixed-price bids.
- Design:Front-end engineering and detailed design development governing downstream procurement and build specifications. Building information modeling platforms are digitizing coordination workflows, with state-owned utilities mandating BIM deliverables for contracts above threshold values.
- Procurement:Vendor selection, material sourcing, and supply chain coordination for project inputs. PLI scheme benefits for specialty steel reshape domestic sourcing obligations, pressuring EPCM firms to deepen local supplier networks.
By volume, Construction leads. By growth pace, Project Management is ahead.
End User:
Cost tier differentiation across end-use sectors separates capital-intensive process industries from publicly funded infrastructure, with payment security and contract duration varying accordingly.
- Oil & Gas:Hydrocarbon processing, pipeline transmission, and storage terminal construction requiring specialized pressure vessel and safety system expertise. Dahej and Hazira petrochemical corridors generate concentrated demand for integrated EPCM services across process units and marine terminals.
- Power Generation:Thermal, renewable, and grid infrastructure projects governed by CEA technical standards and commissioning protocols. Renewable hydrogen targets are generating demand for gigawatt-scale electrolyzer fabrication facilities, expanding EPCM scopes beyond conventional generation assets.
- Infrastructure:Highway, metro rail, airport, and urban development projects channeled through India's National Infrastructure Pipeline. State-led buildouts in Maharashtra concentrate predictable contract pipelines for qualified bidders.
- Industrial:Manufacturing facilities, semiconductor fabs, and heavy industrial complexes requiring clean-build and high-purity utility credentials. India's semiconductor fabrication entry demands ultra-cleanroom construction capabilities that filter out undercapitalized regional contractors.
By contract value concentration, Oil & Gas dominates. By project velocity, Infrastructure is expanding most quickly.
Project Size:
Margin structures compress as project scale increases, with mega-scale installations transferring disproportionate schedule and performance risk to consolidated contractors while smaller projects retain fragmented, multi-party delivery.
- Mega Projects:Refineries, airports, and semiconductor fabs exceeding multi-billion-rupee capital commitments where single-point accountability reduces interface risk. India's National Infrastructure Pipeline channels sovereign capital here, compressing contractor selection timelines and elevating qualification barriers.
- Large Scale:Major industrial and power installations requiring integrated design-build capability but permitting more flexible procurement structures. Tata Projects and Larsen & Toubro compete aggressively in this bracket through balance-sheet depth and technical credentials.
- Medium Scale:Mid-sized manufacturing and commercial infrastructure where regional contractors maintain competitive positioning. BIS compliance burdens filter undercapitalized players, consolidating bid pools but stretching accredited firms across concurrent certifications.
- Small Scale:Localized commercial and residential construction with minimal engineering complexity and commodity procurement profiles. Working-capital intensity and thin margins limit specialist EPCM participation here.
By absolute contract count, Medium Scale leads. By revenue expansion trajectory, Mega Projects are climbing the fastest.
Delivery Model:
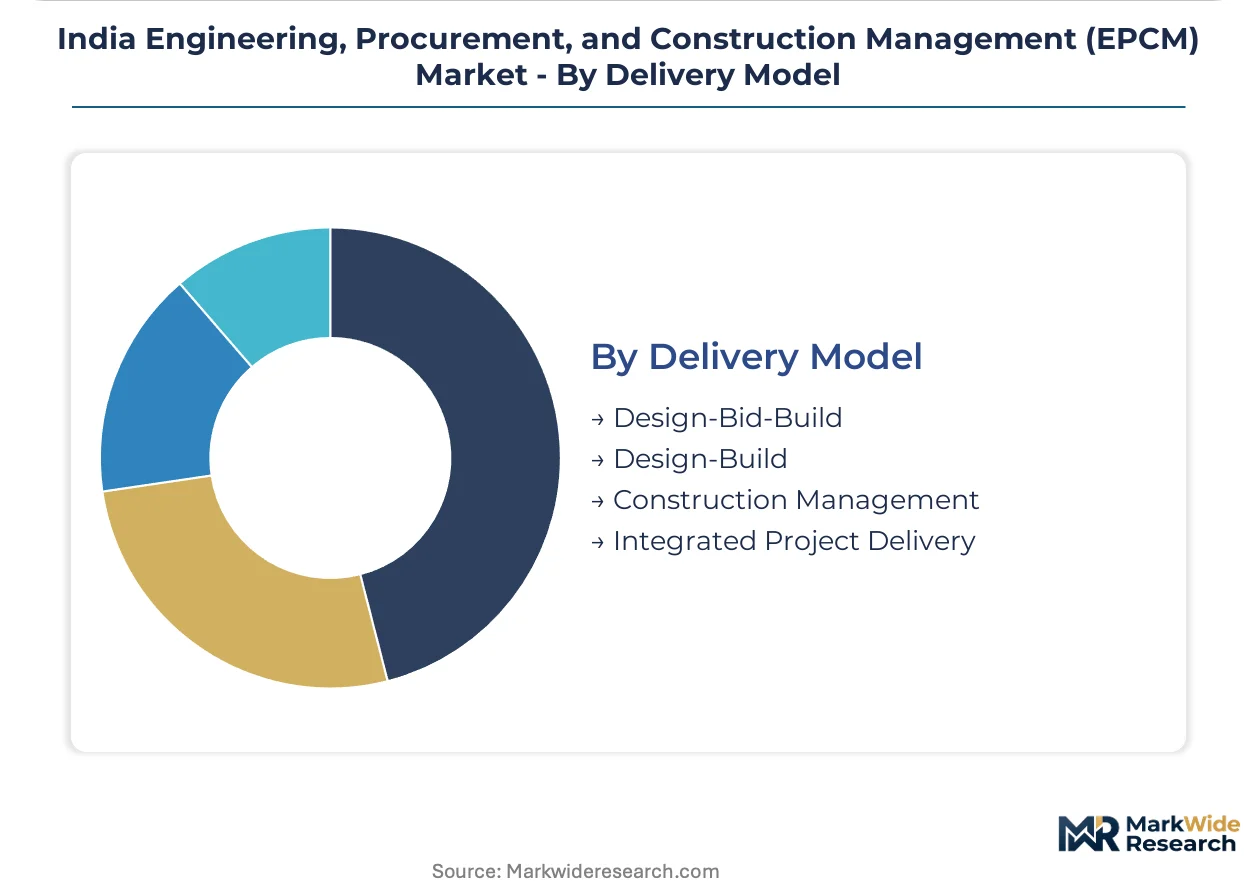
Application context determines delivery model selection, with speed-to-commissioning requirements in power and industrial sectors accelerating displacement of traditional procurement structures.
- Design-Build:Unified responsibility for engineering and construction compressing handover timelines and reducing owner coordination burden. This model is displacing traditional structures in power generation and industrial applications where commissioning speed determines project returns.
- Design-Bid-Build:Sequential designer selection followed by competitive construction tendering, preserving owner control but extending procurement cycles. Public-sector clients with rigid tendering mandates retain this structure despite schedule inefficiencies.
- Construction Management:Owner-retained design with professional construction oversight, transferring build risk while preserving design autonomy. Institutional investors acquiring operational assets in Gujarat and Maharashtra increasingly demand this separation between construction and operational phases.
- Integrated Project Delivery:Multi-party risk-sharing agreements with shared financial incentives aligning designer, builder, and owner interests. Limited adoption in India due to contractual complexity and dispute-resolution uncertainty under pending Arbitration Act amendments.
By current contract volume, Design-Bid-Build retains the largest share. By adoption momentum, Design-Build is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PLI scheme for specialty steel and cement is compressing input costs for domestic contractors across India's most industrialized corridors. State-led infrastructure buildouts in Maharashtra and Gujarat are expanding EPCM adoption across highways, metro rail, and petrochemical complexes. Mega-scale power and refinery projects concentrate demand where single-point accountability reduces interface risk for public-sector clients.
Maharashtra
Mumbai-Pune Expressway expansion and Mumbai Metro Phase III are driving highway and urban rail EPCM demand. The state's public works department mandates BIS-certified structural steel for all bridge contracts. The Mumbai Metropolitan Region concentrates integrated design-build awards for water treatment and metro depots.
Gujarat
Dahej and Hazira petrochemical corridors attract downstream chemical investments requiring process unit construction. CEA technical standards govern power plant commissioning timelines across the state's renewable and thermal installations. The Gujarat State Petronet network anchors marine terminal and storage EPCM contracts.
Karnataka
Bengaluru's suburban rail and airport expansion projects channel design-build procurement for transportation infrastructure. The state's renewable energy policy mandates CEA-compliant grid interconnection standards. The Bengaluru-Tumkur industrial corridor concentrates semiconductor fab and electronics manufacturing facility construction.
Tamil Nadu
Ennore and Kattupalli port expansions generate marine and heavy civil EPCM demand. The state's solar park program requires integrated EPC contractors for utility-scale photovoltaic installations. The Chennai Metropolitan Area anchors metro rail phase extensions and elevated corridor construction.
Telangana
Hyderabad Pharma City and Genome Valley expansions demand ultra-cleanroom and high-purity utility construction expertise. The state's life sciences policy incentivizes BIS-compliant specialized infrastructure. The Hyderabad-Warangal industrial corridor concentrates bulk drug and active pharmaceutical ingredient facility buildouts.
India Engineering, Procurement, and Construction Management (EPCM) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's EPCM landscape. The market structures around three tiers: diversified conglomerates with balance-sheet depth anchoring mega-projects, mid-scale integrated contractors capturing industrial and urban infrastructure, and specialized operators dominating technically demanding marine and tunnelling segments. Consolidation pressure intensifies as BIS certification requirements and CEA-mandated commissioning credentials filter undercapitalized regional players. Dominant competitive moves include strategic partnerships for technology licensing and backward integration into captive steel and cement supply.
Among diversified conglomerates, Larsen & Toubro and Tata Projects anchor the premium tier through integrated design-build capability and balance-sheet capacity for hydrocarbon and metro contracts. Afcons Infrastructure occupies a specialist position in complex marine and tunnelling works where technical credentials sustain premium positioning. These three exemplify how scale, specialization, and certification depth determine competitive outcomes across India's infrastructure buildout.
| Leading Market Players |
|---|
| Larsen & Toubro |
| Tata Projects |
| Reliance Infrastructure |
| GMR Group |
| Megha Engineering and Infrastructures Ltd |
| Hindustan Construction Company |
| Afcons Infrastructure |
| Engineers India Limited |
| Punj Lloyd Group |
| Others |
Pricing and Supply Chain Analysis
Cement price volatility and BIS certification requirements for structural steel compress fixed-price contract margins while simultaneously filtering undercapitalized regional contractors from bid pools. This input cost instability forces EPCM firms to load escalation clauses or absorb working-capital strain, creating pricing tier spreads between accredited conglomerates and commodity-dependent regional players.
Pricing Analysis
Certification level creates the primary spread across India's EPCM market, with CEA-mandated commissioning credentials and BIS structural steel accreditation commanding 15-25% bid premiums over uncertified competitors. Project-based milestone pricing dominates mega-scale hydrocarbon and metro rail contracts, while smaller industrial installations permit more flexible cost-plus structures. Pricing pressure stems from cement price volatility and forex exposure on imported tunnel-boring equipment, compressing margins on fixed-price commitments. Public-sector clients in Maharashtra and Gujarat exhibit lowest price sensitivity due to sovereign-backed payment security, whereas private industrial developers in medium-scale manufacturing segments drive aggressive competitive tendering.
Supply Chain Analysis
Upstream feedstock for structural steel and Portland cement draws from integrated domestic producers under India's PLI scheme, reducing import dependency for standard-grade construction inputs. Heavy-lift cranes and tunnel-boring machines concentrate supply with German, Japanese, and Chinese OEMs, exposing project schedules to shipping bottlenecks and currency fluctuation. Single-source vulnerability runs through specialized process equipment for petrochemical and semiconductor fab construction, where German and Japanese engineering firms maintain technological lock-in. Distribution runs through project-site direct delivery for mega-installations, with consolidated logistics networks serving the Dahej-Hazira and Mumbai-Pune industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's EPCM market sits in early-cycle recovery as sovereign capital deployment through the National Infrastructure Pipeline reaccelerates project awards. State-led buildouts in Maharashtra and Gujarat provide visible contract pipelines that justify capacity positioning ahead of demand inflection.
For Market Incumbents: Entrench certification moats by accelerating CEA commissioning engineer training pipelines and captive steel fabrication investments before regulatory tightening elevates compliance costs further. Deepen balance-sheet deployment into InvIT-aligned asset management contracts to capture recurring revenue streams post-construction handover. Defensive positioning against emerging design-build specialists requires locking multi-year framework agreements with state public works departments.
For New Entrants and Emerging Players: Establish a beachhead in Telangana's life sciences infrastructure cluster, where ultra-cleanroom construction expertise remains scarce relative to announced Pharma City and Genome Valley expansions. Target medium-scale semiconductor fab ancillaries in Karnataka's Bengaluru-Tumkur corridor, where BIS compliance burdens filter national competitors but project scale permits specialist positioning. A go-to-market alliance with German or Japanese clean-build technology licensors accelerates credential acquisition.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors accredited mid-cap contractors with demonstrated CEA and BIS compliance track records. Long-term viability over the next decade hinges on exposure to sovereign-backed infrastructure rather than private industrial cyclicality. Acquisition screening should prioritize firms with commissioning engineer bench depth and established supplier networks under PLI scheme coverage. The signal to watch is amendment progression on India's Arbitration and Conciliation Act, which would reduce working-capital intensity and improve contract economics across long-duration projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Steel Supply | PLI scheme benefits compress input costs and accelerate BIS certification timelines for structural grades. |
| CEA Commissioning Engineer Training Pipeline | Scarce qualified manpower commands premium positioning in power generation and grid interconnection contracts. |
| InvIT-Aligned Asset Management Transition | Long-term O&M contracts post-construction unlock institutional capital and recurring revenue streams. |
| Clean-Build Technology Licensing Alliance | Semiconductor fab and pharma facility demand requires ultra-cleanroom credentials that filter regional competitors. |
| Gujarat Petrochemical Corridor Expansion | Dahej and Hazira downstream investments create integrated EPCM demand across process units and marine terminals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across India's EPCM value chain, combining primary interviews with project directors at Larsen & Toubro and Tata Projects, procurement leads at state public works departments, commissioning engineers holding CEA certifications, and marine construction specialists at Afcons Infrastructure. Secondary validation drew from CEA technical standards filings, BIS certification registries, National Infrastructure Pipeline project databases, and state government budget expenditure statements. Bottom-up project pipeline aggregation and top-down infrastructure investment flow analysis were triangulated to establish market sizing.
Calibration against historical contract award patterns and announced state capital expenditure commitments anchored the projection framework across service type, end user sector, project size tier, and delivery model dimensions. CAGRs were derived from segment-level growth differentials reflecting PLI scheme impact, regulatory compliance cost trajectories, and sovereign capital deployment velocity. Industry-specific forecast inputs included cement and steel price elasticity assumptions, commissioning engineer supply constraints, and arbitration timeline sensitivity.
Sensitivities concentrate around cement price volatility, forex fluctuation on imported equipment, and Arbitration Act amendment progression that could compress working-capital cycles. Forecasts reflect documented assumptions on state fiscal capacity and infrastructure investment trust capital formation rates. Cross-checking against state government budget outlay announcements and InvIT fundraising disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Seismic Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Architectural Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
United States Engineering Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Vertical Seismic Profile Service Market