
 Vacuum Excavation Service Market | 2026-2036
Vacuum Excavation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Excavation Service Market Insights
Remote monitoring as a software-defined service layer is decoupling equipment uptime guarantees from traditional hourly rental models. Badger Daylighting leverages telematics integration to anchor its fleet utilization rates across Canadian oil sands and US shale corridors. Veolia Group competes through environmental compliance bundling, while Clean Harbors dominates hazardous spoil disposal linkages that lock in recurring revenue per project.
Vacuum excavation services deploy high-pressure water or compressed air to loosen soil, then vacuum debris into sealed tanks for controlled disposal, operating at pressures typically ranging from 2,000 to 4,000 PSI to expose buried utilities without mechanical damage. Hydro excavation leads service type demand where frozen ground or clay-heavy substrates resist air-based methods, while directional drilling application segments capture margin pools in fiber-optic and renewable energy corridor builds. Suction excavator technology segments grow fastest in European urban cores where space constraints and heritage utility density restrict truck-mounted system deployment.
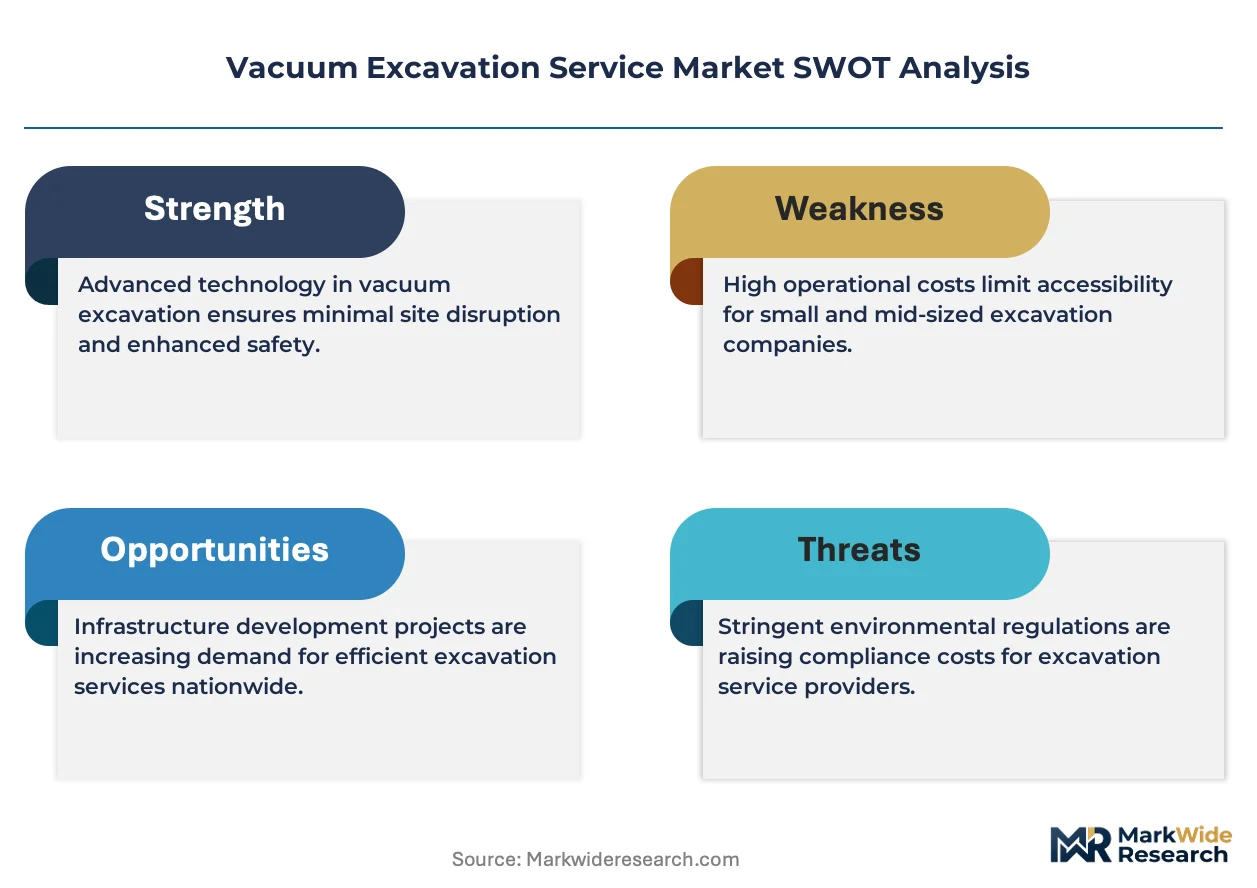
OSHA excavation standards mandate protective system requirements for trenches exceeding five feet, directly expanding vacuum method substitution for mechanical digging in US metropolitan projects. EPA spill containment rules and state DOT utility coordination mandates shape equipment specification and operator certification thresholds. Stakeholders must track how municipal procurement shifts toward outcome-based damage prevention warranties rather than per-hour service contracting.
Market Dynamics
Telematics-enabled fleet management is restructuring contract economics by decoupling uptime guarantees from hourly billing, forcing operators to invest in predictive maintenance infrastructure or lose municipal procurement contests.
Growth Catalysts
- OSHA excavation standards:Federal trench protection mandates for excavations exceeding five feet accelerate vacuum method substitution across US metropolitan infrastructure projects.
- Renewable energy corridor builds:Fiber-optic and offshore wind interconnection projects in Texas and California generate sustained demand for precision exposure services.
- Hydro excavation:Frozen ground and clay-heavy substrates in Canadian oil sands and northern US shale corridors favor high-pressure water systems over pneumatic alternatives.
Market Restraints
- Specialized truck chassis supply:European chassis manufacturers concentrate production, creating lead time volatility for North American fleet operators expanding capacity.
- Compressed air system performance limits:Rocky or frozen substrates in high-altitude Colorado and Utah projects restrict air-based method deployment, forcing equipment redundancy.
- EPA spill containment rules:Stringent hazardous spoil transport documentation increases project overhead and operator certification burdens.
Strategic Opportunities
- Florida utility infrastructure aging:Saltwater intrusion and hurricane damage to buried coastal systems create recurring damage prevention contracting.
- Outcome-based damage prevention warranties:Municipal procurement in California and Texas shifts from hourly rates to strike-free performance guarantees.
- Telematics and predictive maintenance convergence:Real-time pressure monitoring and automated scheduling reduce unplanned downtime for fleet operators.
Industry Challenges
- Certified hydrovac operator shortage:OSHA-compliant training programs and state-level one-call certification requirements extend hiring timelines.
- Disposal site access:Contaminated spoil routing to licensed facilities creates logistical bottlenecks in dense urban cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Excavation Service Market |
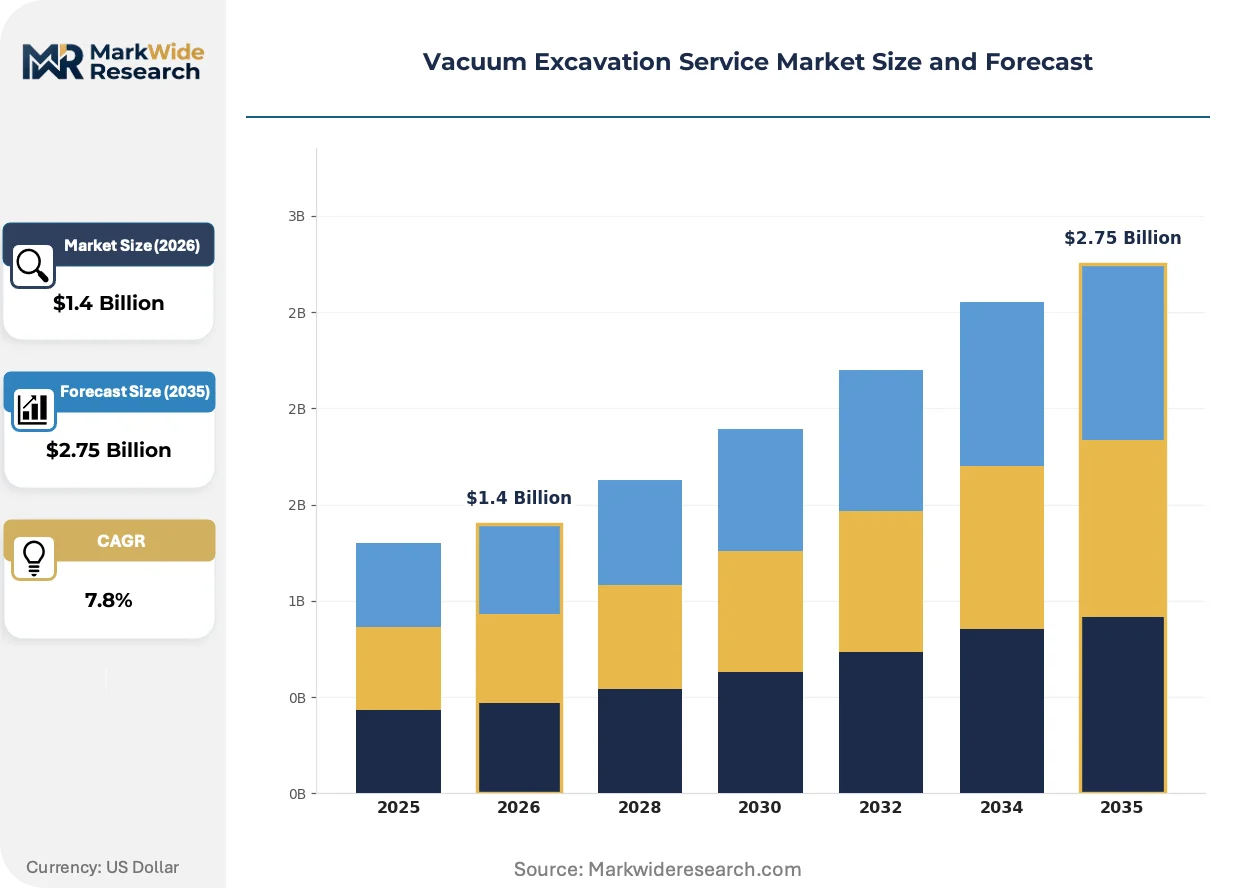
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hydro Excavation, Air Excavation, Soft Digging, Directional Drilling End User: Construction Firms, Utility Companies, Municipalities, Environmental Services Application: Potholing, Trenching, Site Preparation, Pipeline Installation Technology: Vacuum Truck, Suction Excavators, Water Jetting, Remote Monitoring |
| Companies Covered | Remondis, McVac Environmental, Badger Daylighting, Cloud 9 Services, ACVenviro, PowerTeam Services, Clean Harbors, Performance Contracting Group, Veolia Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Excavation Service Market Trends and Innovations
Digital layer integration is compressing traditional service boundaries, with software-defined uptime guarantees and automated compliance documentation emerging as primary competitive differentiators.
Remote monitoring systems are consolidating fleet management economics by embedding pressure sensors, GPS tracking, and automated maintenance alerts into vacuum excavation units. Utility contractors in Texas and California demand real-time visibility into equipment location and operational status. This telemetry infrastructure is consolidating contract structures around guaranteed availability rather than hourly utilization.
OSHA excavation safety standards and state DOT utility coordination mandates are tightening protective system requirements for trenching operations. Contractors must document shoring, benching, or vacuum method substitution for excavations near buried infrastructure. US metropolitan projects face the steepest compliance ramps, with California and Florida municipalities requiring certified damage prevention plans before permit issuance.
Outcome-based service contracts are displacing traditional hourly rental models in municipal procurement. Texas cities now specify strike-free performance warranties rather than day-rate billing for utility exposure work. This behavioral shift concentrates contracting power with operators carrying telematics infrastructure and documented safety records.
Vacuum Excavation Service Market Segmentation
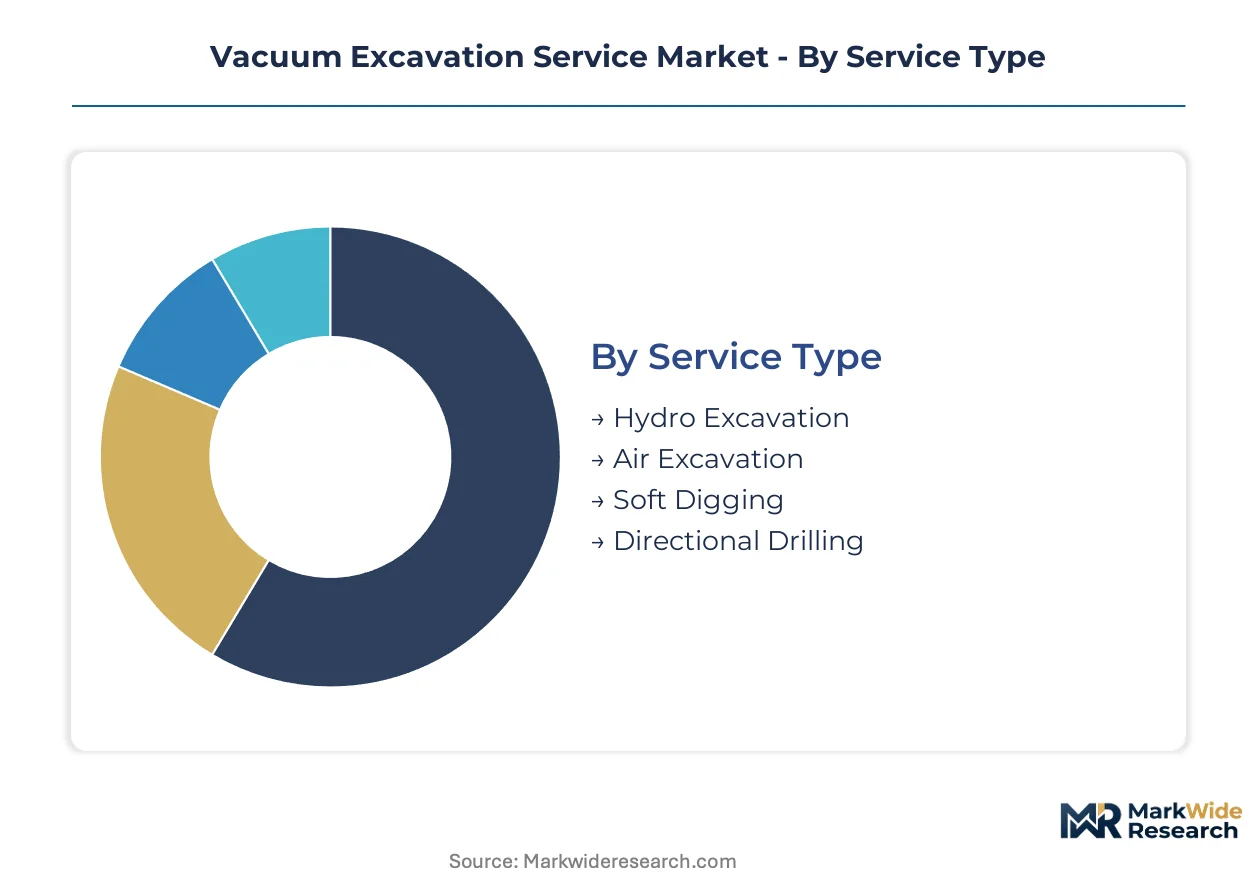
Service differentiation in vacuum excavation tracks substrate conditions, regulatory exposure, and project scale. Equipment upgrade cycles and operator certification tiers further stratify contracting economics across customer types.
Service Type:
Equipment replacement cycles in hydro excavation run shorter than air-based alternatives due to pump wear and pressure vessel certification demands.
- Hydro Excavation:High-pressure water systems operating at 2,000 to 4,000 PSI liquefy soil for vacuum extraction. Demand concentrates in Canadian oil sands and northern US shale corridors where frozen ground resists pneumatic methods.
- Air Excavation:Compressed air loosens debris without introducing moisture, preserving soil chemistry for laboratory analysis. Rocky or frozen substrates in high-altitude Colorado and Utah projects restrict deployment, forcing equipment redundancy.
- Soft Digging:Manual tool assistance for precision exposure near fiber-optic and electrical infrastructure. Utility contractors specify this method for heritage districts with dense buried networks.
- Directional Drilling:Horizontal boring combined with vacuum spoil removal for renewable energy corridor builds. Texas and California interconnection projects generate sustained contracting volume.
Hydro Excavation sits at the top of the volume ranking, with Directional Drilling climbing the fastest.
End User:
Customer procurement sophistication separates damage prevention warranty demand from basic hourly rental contracting.
- Utility Companies:North American electric and gas distributors specify telematics-enabled fleets for strike-free performance guarantees. OSHA trench protection mandates accelerate vacuum method substitution across metropolitan infrastructure projects.
- Construction Firms:General contractors bundle excavation into turnkey site packages, prioritizing equipment availability over method specification. Compressed air system performance limits in rocky substrates create change-order exposure.
- Municipalities:California and Florida cities mandate certified damage prevention plans before permit issuance. Outcome-based contracts displace day-rate billing for utility exposure work.
- Environmental Services:Contaminated site remediation requires EPA-compliant spoil documentation and licensed disposal routing. Dense urban cores present logistical bottlenecks for tanker access.
Utility Companies anchor the revenue base, with Municipalities expanding most quickly.
Application:
Project duration and soil volume determine whether truck-mounted or trailer-based systems deploy.
- Potholing:Precision daylighting of buried utilities for verification and mapping. Fiber-optic builds in Texas generate recurring demand for small-diameter exposure.
- Trenching:Linear excavation for pipeline and cable installation. OSHA five-foot depth triggers mandate protective system substitution across US metropolitan projects.
- Site Preparation:Bulk soil removal for foundation and pad construction. Margin pressure from mechanical excavation competitors limits vacuum method penetration.
- Pipeline Installation:Cross-country corridor construction with continuous spoil management. Offshore wind interconnection projects in California sustain long-duration contracting.
Trenching captures the largest project volume, with Potholing gaining share fastest.
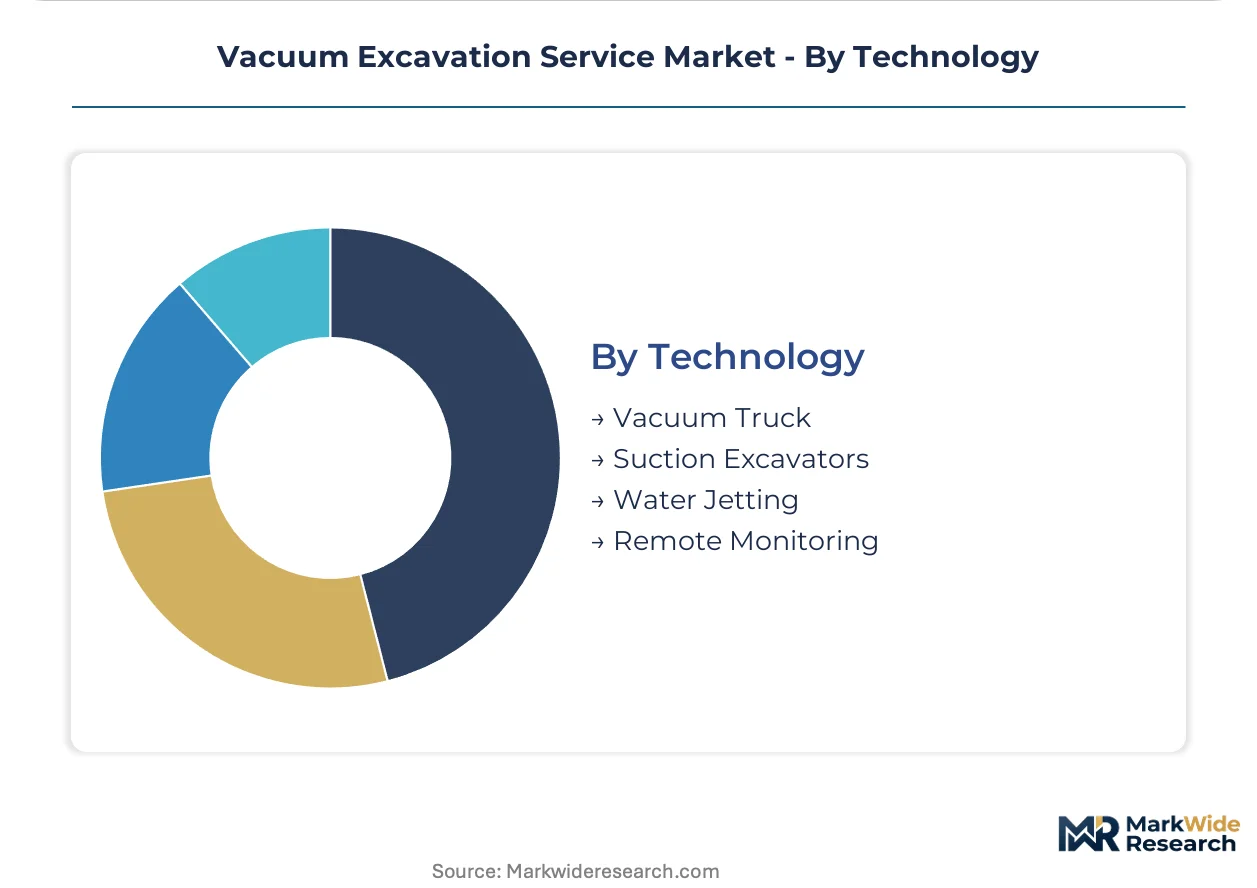
Technology:
Telematics infrastructure investment separates fleet operators capable of uptime guarantees from hourly rental competitors.
- Vacuum Truck:Chassis-mounted debris tanks with integrated pressure systems dominate North American fleet composition. European chassis supply concentration creates lead time volatility for capacity expansion.
- Suction Excavators:Compact units deploy in European urban cores where space constraints and heritage utility density restrict truck access. Suction excavator technology segments expand most quickly in constrained environments.
- Water Jetting:High-pressure nozzle systems for hydro excavation service delivery. Pump maintenance cycles drive shorter replacement intervals than air compressor systems.
- Remote Monitoring:GPS tracking, pressure sensors, and automated maintenance alerts embedded in fleet units. Real-time visibility into equipment location and status enables guaranteed availability contracting.
Vacuum Truck technology holds the installed base advantage, with Remote Monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's oil sands operators deploy hydro excavation fleets at scale, while Germany's heritage urban cores constrain truck-mounted systems and accelerate suction excavator adoption. Market development tracks substrate conditions, infrastructure age, and regulatory stringency across national boundaries.
United States
Utility infrastructure aging and renewable energy corridor expansion drive contracting volume in Texas and California. OSHA excavation standards mandate protective systems for trenches exceeding five feet, accelerating vacuum method substitution. Municipal procurement in Florida cities shifts toward outcome-based damage prevention warranties rather than hourly billing.
Canada
Frozen ground conditions in northern shale corridors and oil sands operations favor high-pressure hydro excavation over pneumatic alternatives. Federal and provincial environmental regulations govern hazardous spoil transport and disposal documentation. Fleet operators concentrate in Alberta and Saskatchewan where energy infrastructure maintenance generates recurring service demand.
Germany
Heritage utility density and space constraints in urban cores restrict vacuum truck deployment and expand suction excavator segments. REACH and national environmental regulations shape equipment specification and waste handling protocols. Industrial clusters in North Rhine-Westphalia and Bavaria anchor precision exposure contracting for fiber-optic and utility networks.
United Kingdom
London's dense subterranean infrastructure and Crossrail-style megaprojects sustain precision potholing demand. HSE excavation safety regulations and utility strike avoidance mandates tighten compliance requirements for metropolitan contractors. Southeast England and Midlands urban corridors concentrate service providers with telematics-enabled fleet capabilities.
Australia
Mining sector automation and remote infrastructure maintenance expand vacuum excavation adoption in Western Australia and Queensland. State-level environmental protection authorities regulate contaminated spoil handling and disposal site access. Perth and Brisbane metropolitan areas concentrate contractors serving both resource extraction and urban utility sectors.
Vacuum Excavation Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated environmental service groups commanding municipal procurement and regional operators capturing project-specific contracting. Market structure tilts toward consolidation at the national fleet level while remaining fragmented in metropolitan service zones. Three archetypes dominate: telematics-enabled fleet operators, environmental compliance bundlers, and hazardous waste disposal integrators. Competitive moves concentrate on predictive maintenance infrastructure investment and outcome-based warranty structuring.
Among North American fleet operators, Badger Daylighting and Clean Harbors exemplify contrasting strategic positions. Badger Daylighting anchors the telematics-integrated tier with real-time fleet visibility capabilities. Clean Harbors occupies the environmental compliance bundling position, linking excavation services to licensed spoil disposal infrastructure. Veolia Group represents the European multinational archetype, competing through integrated waste and environmental service platforms.
| Leading Market Players |
|---|
| Remondis |
| McVac Environmental |
| Badger Daylighting |
| Cloud 9 Services |
| ACVenviro |
| PowerTeam Services |
| Clean Harbors |
| Performance Contracting Group |
| Veolia Group |
| Others |
Pricing and Supply Chain Analysis
Telematics-enabled fleet certification separates premium-tier operators from hourly rental competitors, with that divergence manifesting in both rate structures and chassis procurement strategies. Municipal buyers in Texas and California now demand guaranteed-availability contracts that lock in telematics infrastructure, while commodity operators compete on day-rate bidding with shorter equipment replacement cycles.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for hydro excavation services as fleet operators expand truck-mounted deployments. Three-tier pricing structure across premium telematics-bundled, standard certified-operator, and economy day-rate levels captures divergent buyer risk appetites. Cost compression in the economy tier is intensifying because municipal procurement shifts toward outcome-based damage prevention warranties. Utility companies show least price sensitivity due to strike-liability exposure, while general contractors exhibit highest sensitivity as they bundle excavation into turnkey site packages.
Supply Chain Analysis
Certified hydrovac operator shortages in Germany and chassis manufacturing bottlenecks in European production centers constrain fleet expansion timelines. Equipment sourcing draws from Germany, Italy, and Poland for specialized vacuum truck chassis, with high-pressure pump assemblies and debris tank fabrications as critical component categories. Single-source vulnerability in European chassis supply creates lead time volatility for North American operators scaling capacity. Distribution runs through regional fleet depots with project-based logistics coordination for hazardous spoil routing to licensed disposal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vacuum excavation services rests on telematics infrastructure amortization across guaranteed-availability contracts and premium pricing for certified damage prevention performance.
For Market Incumbents: Extend telematics-enabled service bundling to lock in municipal procurement contracts before outcome-based warranty standards harden. Defensive consolidation of licensed hazardous spoil disposal assets protects recurring revenue streams against environmental compliance bundlers. Capacity addition in Alberta and Saskatchewan secures positioning in Canadian oil sands maintenance cycles. For New Entrants and Emerging Players: Enter via suction excavator technology deployment in European urban cores where space constraints and heritage utility density restrict truck-mounted system access. Florida's aging coastal infrastructure presents the most penetrable geography given saltwater intrusion damage and hurricane recovery demand. Go-to-market angle centers on certified damage prevention plans that satisfy California and Florida municipal permit requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics infrastructure gaps fragment regional operators below municipal procurement scale thresholds. Long-term viability favors fleet operators with backward integration into licensed spoil disposal and predictive maintenance capabilities. Signal to watch is municipal adoption velocity of strike-free performance guarantees versus hourly rate retention.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Deployment | Enables guaranteed-availability contracting with Texas and California municipalities shifting from day-rate billing. |
| Licensed Spoil Disposal Integration | Locks recurring revenue per project through EPA-compliant routing infrastructure that competitors cannot replicate quickly. |
| Predictive Maintenance Capability | Reduces unplanned downtime for fleet operators competing on uptime guarantees rather than hourly utilization. |
| Certified Operator Training Investment | Addresses OSHA-compliant hiring bottlenecks that extend project mobilization timelines for uncertified competitors. |
| Suction Excavator Technology Adoption | Captures constrained-environment segments in European urban cores where truck-mounted systems face access restrictions. |
Research Methodology
Direct dialogue with fleet operations managers, municipal procurement officers, utility damage prevention coordinators, and licensed waste disposal facility operators grounded qualitative findings. Secondary validation drew from OSHA excavation safety filings, EPA spill containment documentation, state DOT utility coordination mandates, and municipal contract award databases. Bottom-up service demand modeling triangulated against top-down infrastructure investment forecasts across the analysis window.
Segment-level projections for hydro excavation, air excavation, and directional drilling applications were generated through equipment utilization rate analysis and operator capacity constraints throughout the forecast period. Modeled dimensions included service type, end-user procurement sophistication, application project duration, and technology telematics integration tier. CAGRs were derived from substrate-condition-driven demand elasticity and regulatory mandate implementation timelines, with renewable energy corridor build schedules and utility infrastructure replacement cycles as primary forecast inputs.
Inputs from municipal contract databases and fleet telematics providers were available through the study window; gaps in real-time equipment utilization benchmarking introduce uncertainty bands around capacity expansion assumptions. Forecasts reflect documented substrate condition prevalence, regulatory enforcement intensity, and chassis supply lead time assumptions. Material deviation in OSHA excavation standard enforcement, European chassis export restrictions, or municipal procurement standardization velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
United States Engineering Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Engineering Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geotechnical Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Seismic Services Market