
 Global Pipeline Maintenance Services Market | 2026-2036
Global Pipeline Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipeline Maintenance Services Market Outlook
The gap between premium integrity management and commodity patch-repair services is restructuring contractor economics across the sector. Baker Hughes Company leverages its digital inspection platforms to command premium pricing on smart pigging campaigns across deepwater export lines. Halliburton Company anchors its position through integrated pipeline intervention packages that bundle pressure isolation with composite sleeve installation. Schlumberger Limited differentiates via robotics-based inline inspection tools that reduce downtime on subsea gathering systems.
Pipeline maintenance services encompass the technical assessment, mechanical repair, and preventive rehabilitation of pressurized tubular conveyance systems used for hydrocarbon, water, and chemical transport, typically involving non-destructive testing, cathodic protection verification, and pressure-boundary restoration to ensure continuous operational safety. Inspection services lead the service type category, driven by regulatory-driven inline assessment mandates on high-consequence areas, while smart pigging technology within the technology dimension captures the fastest growth trajectory as magnetic flux leakage and ultrasonic tools displace manual dig-and-verify protocols. The oil and gas end user segment remains the dominant margin pool, though water utilities are emerging as a structurally growing buyer category amid municipal infrastructure replacement cycles.
PHMSA integrity management rules in the United States, the EU Pipeline Safety Directive, and ISO 13623 design standards collectively shape compliance-driven maintenance spending and equipment certification requirements across operating territories. The EPA's methane emissions regulations further tighten leak detection and repair frequencies on natural gas transmission infrastructure. Stakeholders must monitor the divergence between prescriptive regulatory timelines and the operational readiness of next-generation autonomous inspection platforms.
Market Dynamics
PHMSA integrity management mandates are compressing inspection cycles across aging North American infrastructure while autonomous robotics reduce field crew requirements on subsea gathering systems. This regulatory-technology tension is redrawing contractor economics between premium digital platforms and commodity repair services.
Growth Catalysts
- PHMSA High-Consequence Area Mandates:United States operators must complete inline assessments on transmission lines near population centers every seven years, creating recurring demand for smart pigging campaigns.
- Shale Basin Takeaway Expansion:Permian and Bakken producers are commissioning new gathering lines that require continuous cathodic protection monitoring and pressure-boundary verification.
- Ultrasonic Testing Advancement:Phased-array ultrasonic tools now detect crack-like flaws in seam welds that magnetic flux leakage methods miss, accelerating technology refresh cycles.
Market Restraints
- Specialized Labor Scarcity:Certified inline inspection analysts and composite repair technicians command premium wages that inflate project costs across North America and the North Sea.
- Equipment Import Dependencies:Advanced robotics platforms and sensor arrays concentrate manufacturing in Germany, Japan, and the United States, exposing contractors to currency volatility and shipping delays.
- Extended Certification Timelines:ISO 13623 pressure-boundary restoration protocols require third-party witness testing that stretches project schedules by four to eight weeks.
Strategic Opportunities
- Brazil Pre-Salt Infrastructure:Petrobras-operated subsea tiebacks lack indigenous maintenance capacity, creating entry points for robotics-equipped contractors.
- Water Utility Rehabilitation:Municipal transmission mains in the United Kingdom and Germany face replacement cycles that mirror oil and gas integrity management workflows.
- EU Methane Emission Regulations:The F-Gas Regulation and complementary national leak detection mandates are forcing natural gas distributors to quadruple survey frequencies on distribution networks.
Industry Challenges
- Data Integration Complexity:Historical paper-based inspection records from 1980s-era pipelines resist digitization, complicating predictive corrosion modeling.
- Subsea Robotics Standardization:Proprietary communication protocols between autonomous inspection vehicles and topside control systems fragment vendor interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipeline Maintenance Services Market |
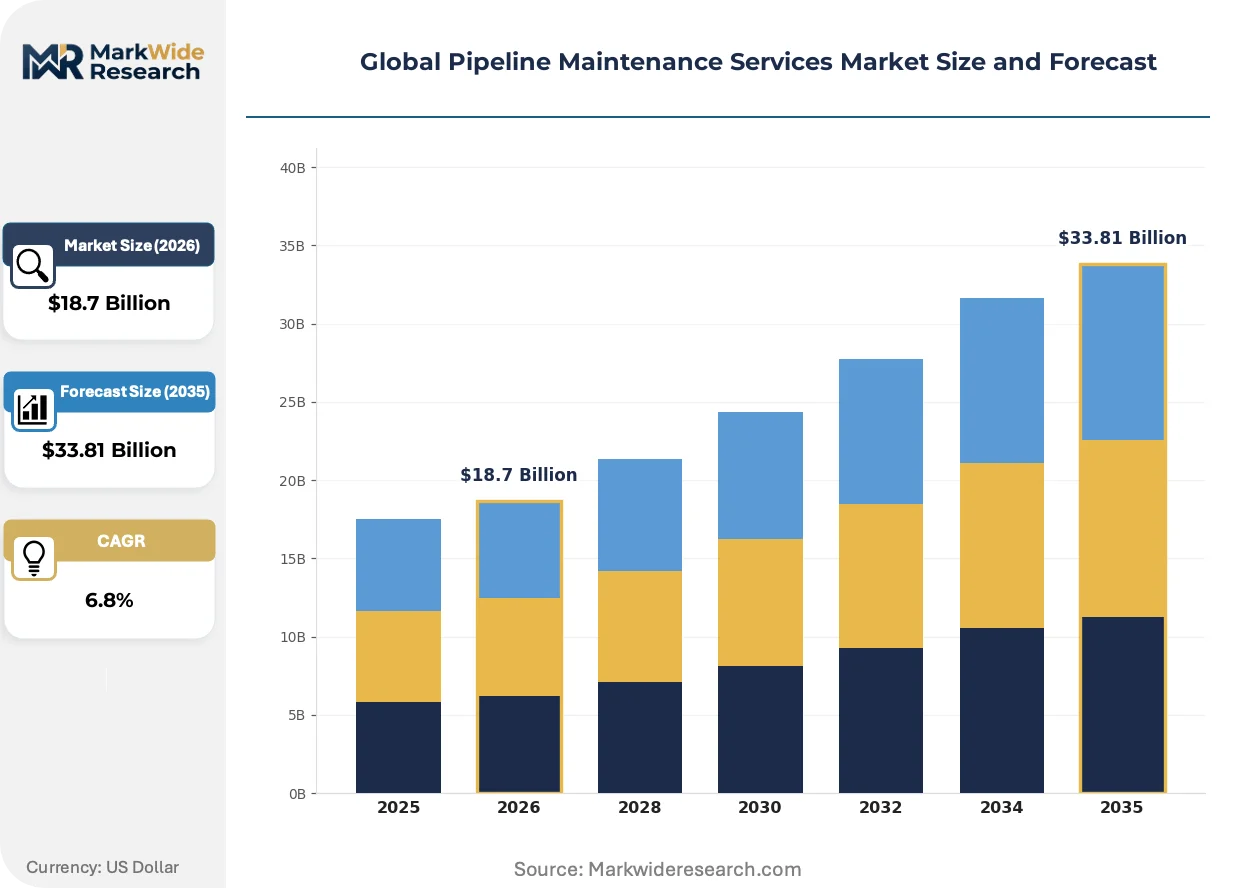
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Repair, Maintenance, Rehabilitation Technology: Smart Pigs, Hydrotesting, CCTV Inspection, Coating Inspection End User: Oil & Gas, Water Utilities, Chemical Manufacturing, Municipalities Installation: Onshore, Offshore, Urban, Rural |
| Companies Covered | Baker Hughes Company, Halliburton Company, Schlumberger Limited, T.D. Williamson, Inc., EnerMech Ltd., STATS Group, Rosen Group, Mistras Group, Inc., NDT Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipeline Maintenance Services Market Strategic Shifts
Digital twin platforms are converging with inline inspection data streams to enable predictive rather than calendar-based maintenance scheduling. This shift compresses contractor revenue recognition cycles while elevating analytics capabilities above mechanical execution.
Autonomous underwater vehicles equipped with laser profilometry and electromagnetic acoustic transducers are overtaking tethered remotely operated vehicles for deepwater export line surveys. Offshore operators in the Gulf of Mexico and West Africa are deploying these systems on twelve-month continuous monitoring contracts. The technology is overtaking conventional methods by eliminating vessel standby costs and reducing inspection windows from weeks to days.
The EPA's methane emissions regulations are mandating quarterly leak detection surveys on natural gas transmission infrastructure exceeding specified throughput thresholds. Pipeline operators must deploy optical gas imaging or aerial LiDAR systems that detect fugitive releases below 500 parts per million. Gathering system operators in the Permian Basin are most affected, retrofitting compressor stations with continuous monitoring sensors to avoid penalty structures.
Asset owners are unbundling integrity management contracts from integrated service providers, creating direct procurement relationships with specialized analytics firms. North American midstream companies now separately contract inline inspection runs, data interpretation, and repair execution. This pattern is most visible among master limited partnerships seeking to optimize operating expense disclosure for investor presentations.
Global Pipeline Maintenance Services Market Segmentation
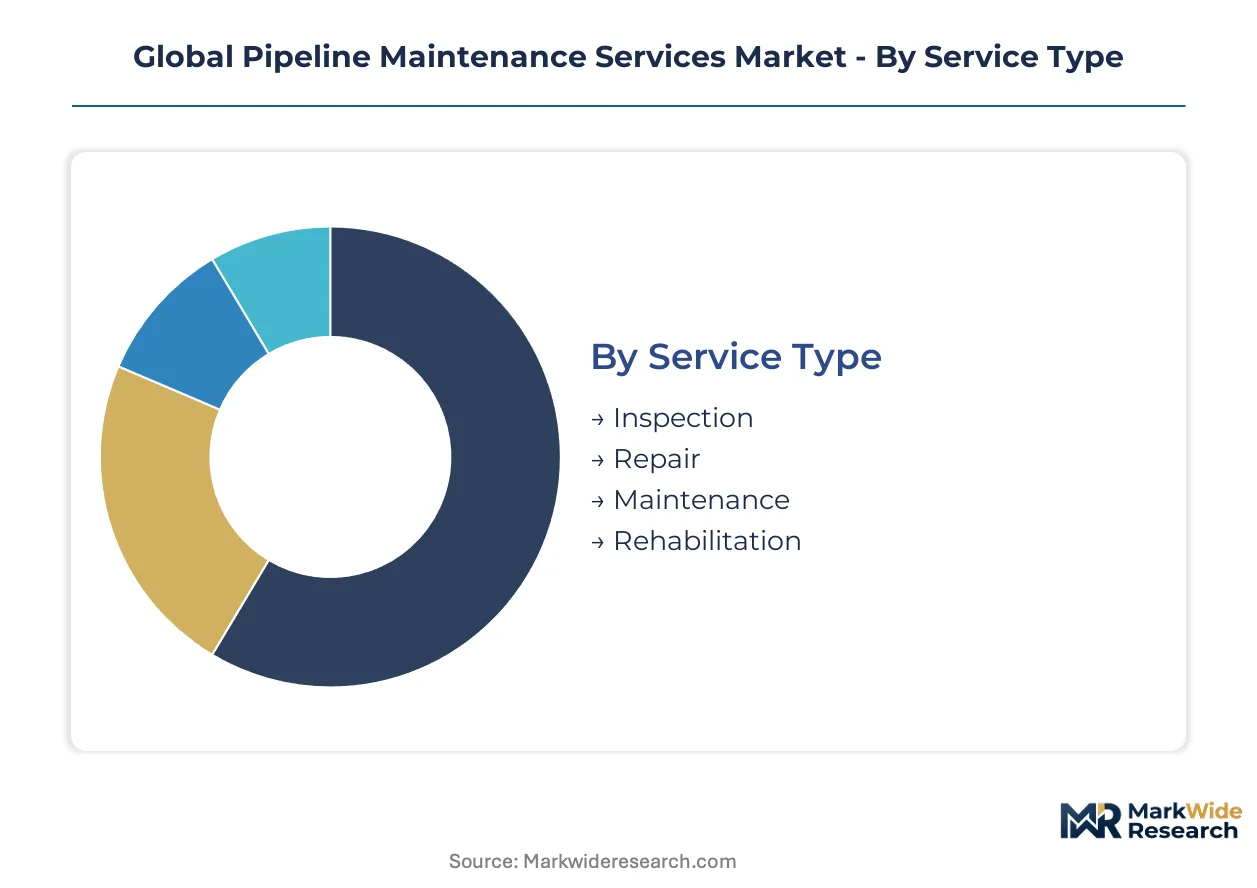
Pipeline maintenance contractors configure service portfolios around four distinct axes: the technical work performed, the diagnostic equipment deployed, the asset owner served, and the physical environment where intervention occurs. Each axis carries divergent margin profiles and capital requirements that reshape contractor specialization strategies.
Service Type:
Buyers in this category separate on regulatory pressure intensity and consequence-of-failure tolerance.
- Inspection:Non-destructive evaluation using inline tools, external direct assessment, and pressure testing to verify structural integrity. PHMSA mandates in the United States drive seven-year assessment cycles on transmission lines near population centers, concentrating procurement among midstream operators in Texas and Pennsylvania shale corridors.
- Repair:Mechanical restoration of pressure boundaries through welding, composite sleeve installation, or hot tapping. Gulf of Mexico offshore operators dominate demand for subsea repair campaigns where vessel day rates amplify project economics.
- Maintenance:Scheduled preventive work including cathodic protection system verification, valve servicing, and corrosion inhibitor injection. Water utilities in Germany and the United Kingdom are expanding maintenance contracts amid municipal infrastructure replacement programs.
- Rehabilitation:Comprehensive renewal of aged pipeline sections through lining, replacement, or rerouting. Urban gas distribution networks in Japan and South Korea are accelerating rehabilitation spending as polyethylene pipe reaches end-of-design-life.
Inspection leads volumes today; rehabilitation is gaining share fastest.
Technology:
Technology selection tracks pipeline accessibility constraints and defect detection resolution requirements.
- Smart Pigs:Self-propelled inline inspection vehicles equipped with magnetic flux leakage or ultrasonic sensors for wall-thickness mapping. Deepwater export lines in Brazil and West Africa are converting to smart pigging as autonomous platforms eliminate vessel standby costs.
- Hydrotesting:Pressure-boundary verification through water filling, pressurization, and leak detection. Onshore gathering systems in the Permian Basin require hydrotesting for new construction tie-ins under Texas Railroad Commission rules.
- CCTV Inspection:Closed-circuit video survey for internal condition assessment, primarily in non-pressurized water and sewer infrastructure. Municipalities in Australia are deploying crawler-mounted CCTV for condition rating of aging cast-iron water mains.
- Coating Inspection:External corrosion protection verification through holiday detection, adhesion testing, and cathodic protection potential survey. Offshore operators in the North Sea specify coating inspection for platform-to-shore pipelines exposed to splash-zone degradation.
Smart pigs dominate offshore procurement; CCTV inspection is expanding most quickly in municipal water segments.
End User:
End-user differentiation centers on regulatory scrutiny intensity and asset replacement urgency.
- Oil & Gas:Hydrocarbon transport infrastructure spanning production gathering, processing, transmission, and distribution. FERC interstate regulations and EPA methane emissions rules in the United States compress inspection frequencies and tighten leak detection thresholds.
- Water Utilities:Potable water and wastewater conveyance systems operated by municipal or regional authorities. Infrastructure replacement cycles in the United Kingdom and Germany are mirroring oil and gas integrity management workflows.
- Chemical Manufacturing:Process pipeline networks handling corrosive, toxic, or high-purity fluids. Facilities in Japan's Keiyo Industrial Zone require specialized inspection protocols for chlorine and acid service lines.
- Municipalities:Public-sector ownership of water, gas, or district heating distribution grids. French municipalities are procuring integrated inspection-rehabilitation contracts under EU public procurement directives.
Oil and gas commands the largest contract values; water utilities are climbing the fastest as municipal spending accelerates.
Installation:
Installation environment dictates crew mobilization logistics and regulatory jurisdiction.
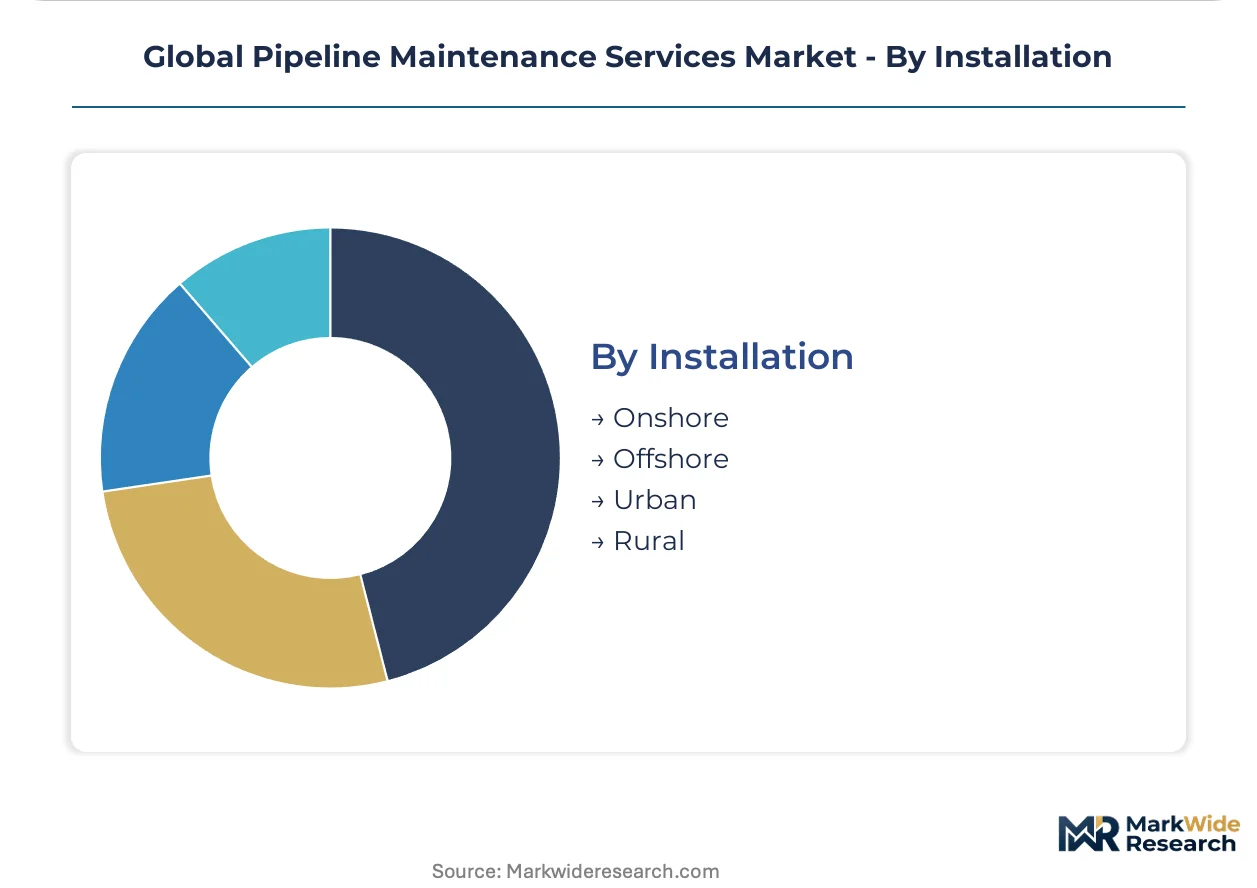
- Onshore:Terrestrial pipeline corridors traversing private, state, and federal lands. PHMSA class location regulations in the United States impose stricter design and inspection requirements near populated areas.
- Offshore:Subsea pipelines, risers, and platform piping in marine environments. Brazil's pre-salt fields lack indigenous maintenance capacity, creating entry points for robotics-equipped international contractors.
- Urban:Distribution networks within city boundaries with high population density and infrastructure congestion. Tokyo's dense utility corridors require night-shift inspection windows and specialized traffic management.
- Rural:Long-distance transmission across agricultural or undeveloped terrain with limited access roads. Gathering lines in North Dakota's Bakken shale traverse remote ranchland where mobilization costs dominate project economics.
Onshore generates the highest absolute contract count; offshore is expanding most quickly as deepwater production rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified inline inspection analysts and composite repair technicians cluster around Houston, Aberdeen, and Singapore, anchoring service delivery for deepwater and shale basin operations worldwide.
United States
Shale basin takeaway capacity expansion and coastal export terminal connections drive contract volumes across Texas and Louisiana. PHMSA integrity management mandates compress assessment cycles to seven years for high-consequence area transmission lines. The Permian Basin gathering system operators in Midland-Odessa commission continuous cathodic protection monitoring for new construction tie-ins.
Brazil
Pre-salt subsea tieback infrastructure lacks indigenous maintenance capacity, creating procurement openings for robotics-equipped international contractors. Petrobras-operated deepwater export lines convert to autonomous inspection platforms that eliminate vessel standby costs. The Santos Basin cluster near Rio de Janeiro anchors demand for twelve-month continuous monitoring contracts.
Germany
Municipal water transmission mains face replacement cycles mirroring oil and gas integrity management workflows. The EU Pipeline Safety Directive and F-Gas Regulation force natural gas distributors to quadruple leak detection survey frequencies. Industrial zones along the Rhine-Ruhr corridor contract specialized inspection protocols for chlorine and acid service lines.
United Kingdom
North Sea offshore operators specify coating inspection for platform-to-shore pipelines exposed to splash-zone degradation. Pipeline Safety Regulations accelerate scheduled maintenance cycles across aging North Sea infrastructure. Aberdeen anchors the subsea robotics technician concentration serving West African export line contracts.
Australia
Municipalities deploy crawler-mounted CCTV for condition rating of aging cast-iron water mains in Sydney and Melbourne. Water utility rehabilitation spending climbs amid infrastructure replacement programs matching oil and gas sector intensity. The country's national pipeline regulator enforces design standards that elevate equipment certification requirements for imported inspection platforms.
Global Pipeline Maintenance Services Market Competitive Environment
Top-tier vendors anchor premium digital platform provision, while commodity repair specialists compete on mobilization speed and labor arbitrage. The vendor base stratifies across three tiers: integrated energy service conglomerates with proprietary robotics, regional inspection contractors with certified analyst pools, and specialized composite repair shops. Two strategic archetypes dominate competitive positioning: technology licensors monetizing sensor IP through platform sales, and execution specialists capturing recurring maintenance contracts through geographic density. M&A activity concentrates on robotics startups with autonomous underwater vehicle capabilities, while incumbents expand through strategic partnerships with municipal water utilities.
Among Houston-based energy service conglomerates, Baker Hughes Company, Halliburton Company, and Schlumberger Limited exemplify the integrated archetype that bundles inspection hardware, data analytics, and repair execution. These entities occupy positions where proprietary technology platforms command premium pricing on deepwater campaigns. Their scale enables sustained R&D investment in magnetic flux leakage and ultrasonic sensor arrays that smaller regional competitors cannot replicate.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton Company |
| Schlumberger Limited |
| T.D. Williamson, Inc. |
| EnerMech Ltd. |
| STATS Group |
| Rosen Group |
| Mistras Group, Inc. |
| NDT Global |
| Others |
Value Chain & Pricing Dynamics
PHMSA's seven-year inline assessment mandates for high-consequence area transmission lines are compressing procurement cycles and forcing contractors to pre-position inspection hardware closer to shale basins, elevating capital carrying costs that transmit into project pricing premiums. This regulatory-driven demand intensity concentrates negotiating leverage with midstream operators who unbundle integrity management contracts to optimize operating expense disclosure.
Pricing Analysis
The bundled-versus-unbundled service split separates premium digital platform providers from commodity repair specialists. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and analytics capability differentiation. Cost compression in the standard tier is intensifying because master limited partnerships now separately contract inline inspection runs, data interpretation, and repair execution. Water utilities emerging as buyers exhibit highest price sensitivity due to municipal budget constraints, while deepwater offshore operators demonstrate lowest sensitivity given vessel day rate economics.
Supply Chain Analysis
Workforce availability constraints in Germany, Japan, and the United States concentrate advanced robotics platform and sensor array manufacturing, exposing contractors to currency volatility and shipping delays. Supply draws from specialized component producers of magnetic flux leakage sensors, ultrasonic transducer arrays, and autonomous navigation modules. Single-source vulnerability runs through German precision sensor manufacturers. Distribution runs through Houston, Aberdeen, and Singapore service hubs that anchor technician deployment for deepwater and shale basin operations worldwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where contractors can capture margin premiums by deploying robotics-equipped crews from low-cost technician pools into Brazil's pre-salt fields where indigenous maintenance capacity remains absent.
For Market Incumbents: Cement dominance in smart pigging campaigns by deepening proprietary sensor IP portfolios and securing twelve-month continuous monitoring contracts in the Gulf of Mexico and West Africa. Vertical integration into autonomous underwater vehicle manufacturing insulates against equipment import dependencies while expanding addressable margin pools beyond execution-only services. For New Entrants and Emerging Players: Laser profilometry-equipped autonomous inspection platforms offer a technology-first wedge into municipal water utility rehabilitation contracts in Germany and the United Kingdom where infrastructure replacement cycles mirror oil and gas integrity management workflows. Target procurement officers at regional water authorities with outcome-based pricing models that transfer corrosion risk from asset owners to contractors. For Investors and Strategic Acquirers: Asymmetric upside sits with robotics startups possessing autonomous underwater vehicle capabilities and established calibration relationships with classification societies. Long-term viability hinges on regulatory enforcement durability rather than commodity cycle recovery. Monitor PHMSA penalty structures on methane emissions compliance as the inflection indicator for leak detection technology valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Inspection Platform Development | Eliminates vessel standby costs for Petrobras-operated deepwater export lines in Brazil. |
| Municipal Water Utility Partnership | Captures replacement cycle spending matching oil and gas integrity management intensity. |
| Sensor Array Manufacturing Integration | Reduces exposure to German and Japanese component import delays and currency volatility. |
| Continuous Monitoring Contract Structuring | Converts project-based revenue to recurring streams with twelve-month offshore terms. |
| Analytics Firm Acquisition | Secures data interpretation capabilities as asset owners unbundle integrity management contracts. |
Study Parameters
Coverage spans North America, Latin America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pipeline integrity managers, cathodic protection specialists, subsea robotics engineers, and municipal water utility procurement officers with secondary validation against PHMSA incident databases, EPA methane emissions filings, EU Pipeline Safety Directive implementation reports, and ISO certification registries. Bottom-up project pipeline tracking triangulates against top-down regulatory mandate analysis.
Granularity-level modeling extends to service type, technology deployment, end-user sector, and installation environment dimensions across the projection horizon. CAGRs derive from segment-level demand build-ups incorporating shale basin takeaway capacity expansion timelines, pre-salt field development schedules, and municipal infrastructure replacement program pacing. Industry-specific forecast inputs include smart pigging technology refresh cycles and autonomous robotics adoption curves in offshore environments.
The model holds under sustained PHMSA enforcement intensity and EU methane regulation expansion; deviation in regulatory penalty structures or autonomous platform certification timelines would shift contractor revenue recognition patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Industrial Maintenance Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Die Casting Services Market
Construction Services
Work Order Management Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
MENA Architectural Services Market
Construction Services
Global Industrial Services Market
Construction Services
Condenser Cleaners Market
Construction Services
Construction TIC Market
Construction Services
Construction Project Management Services Market
Construction Services
Remote Construction Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Forklift Repair and Maintenance Service Market