
 North America Seismic Survey Market | 2026-2036
North America Seismic Survey Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seismic Survey Market Insights
Buyer concentration among supermajors and large independents is realigning contract structures toward integrated multi-year acquisition and processing agreements. Halliburton Company leverages its bundled seismic-to-drilling offerings to lock in recurring revenue streams. Schlumberger Limited anchors its position through proprietary ocean-bottom node technology that reduces survey redundancy. ION Geophysical Corporation specializes in redeployable land acquisition systems that lower mobilization costs for Permian operators.
Seismic survey denotes the geophysical method of mapping subsurface structures through controlled energy source propagation and reflected wavefield recording, typically employing vibroseis trucks, airgun arrays, or distributed acoustic sensing cables with sampling rates exceeding 2 milliseconds to resolve stratigraphic boundaries. Its primary commercial purpose centers on reducing exploration risk by delineating hydrocarbon traps, mineral deposits, or geohazards prior to capital-intensive extraction. Reflection technology dominates revenue contribution due to its maturity in both marine and terrestrial environments, while ground penetrating radar represents the fastest-expanding category as infrastructure operators adopt shallow subsurface imaging for pipeline integrity and utility mapping. Data processing commands the thickest margin pool because algorithmic velocity model building and pre-stack depth migration require specialized computational infrastructure that few contractors replicate.
The US Bureau of Ocean Energy Management, Transport Canada, and Mexico's National Hydrocarbons Commission each enforce distinct seismic permitting protocols that dictate survey timing, marine mammal observation standards, and data submission requirements. BOEM's incidental harassment authorization process for marine seismic surveys extends project lead times by months, compressing the operational window in Arctic and Atlantic planning areas. Stakeholders must monitor evolving cetacean protection thresholds and cross-border data sharing agreements as regulatory divergence between federal and provincial jurisdictions creates compliance complexity.
Market Dynamics
The US Bureau of Ocean Energy Management's compressed permitting timelines for marine seismic surveys are forcing contractors to front-load technical preparation and pre-position equipment, compressing project cycles and elevating capital efficiency requirements across the Gulf of Mexico planning areas.
Growth Catalysts
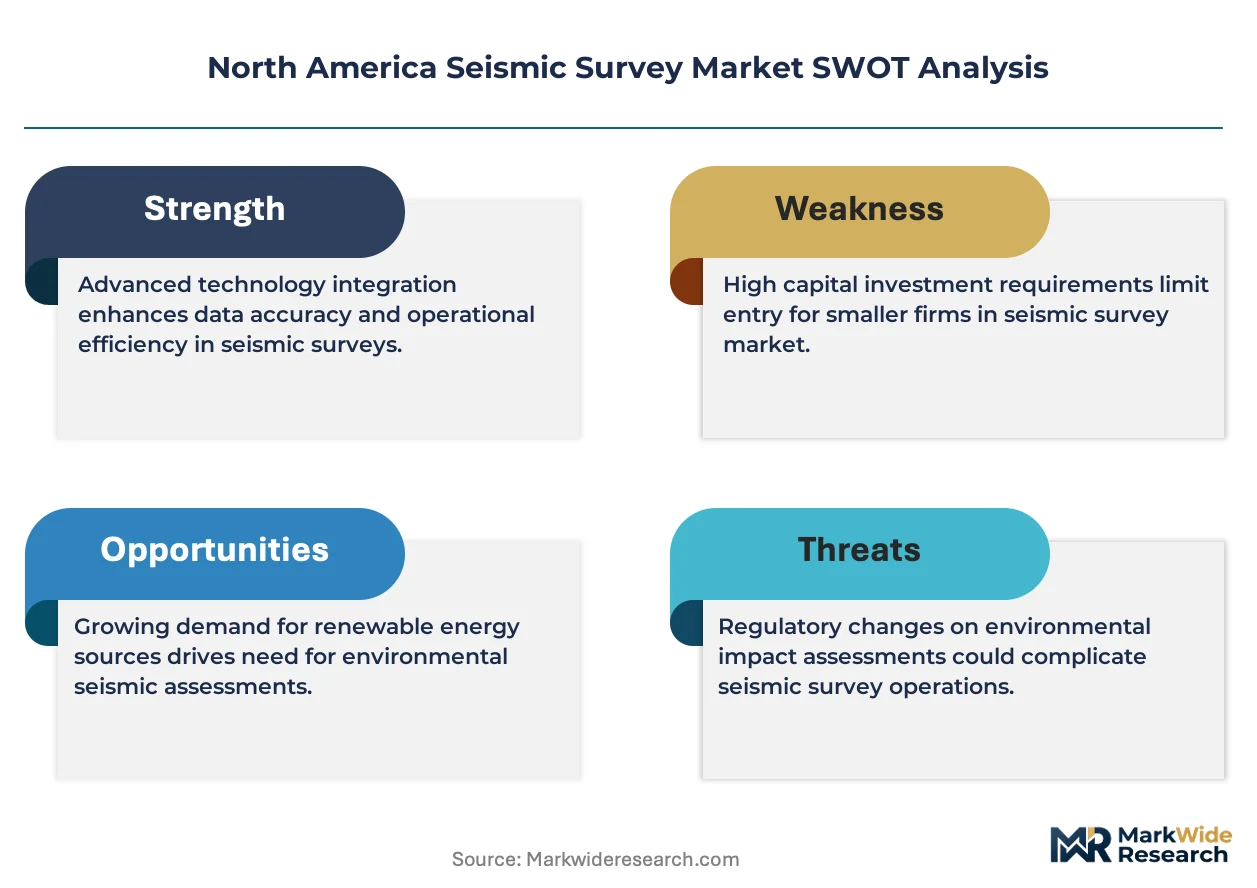
- Permian-Delaware Stack Expansion:Texas onshore operators are deploying dense 3D seismic grids to delineate stacked pay zones, driving crew utilization to capacity limits.
- BOEM Streamlined Authorization:The Bureau's revised incidental harassment authorization protocols, while stringent, provide predictable timelines that reduce planning uncertainty for Atlantic and Arctic survey programs.
- Distributed Acoustic Sensing:Fiber-optic cable deployments are enabling continuous reservoir monitoring, converting single-shot surveys into persistent data streams.
Market Restraints
- Marine Mammal Observer Mandates:BOEM's protected species observer requirements extend vessel standby periods, inflating day-rate costs for Atlantic offshore programs.
- Specialized Crew Scarcity:Geophysicist and vibration control technician availability concentrates in Houston, creating wage pressure that propagates through contract pricing.
- Airgun Array Supply Concentration:Manufacturing of marine source equipment clusters with a limited supplier base in the Gulf Coast, exposing operators to delivery bottlenecks.
Strategic Opportunities
- Carbon Storage Site Characterization:Class VI injection well permitting under EPA frameworks is generating demand for shallow seismic to verify caprock integrity.
- Canada Arctic Frontier:Transport Canada's evolving marine spatial planning is opening discretionary survey windows in the Beaufort Sea for operators with ice-capable assets.
- 4D Time-Lapse Convergence:Integration of ocean-bottom node data with permanent reservoir monitoring systems is creating recurring revenue streams beyond single acquisition contracts.
Industry Challenges
- Velocity Model Building Talent Gap:Specialized geophysicists capable of pre-stack depth migration for complex salt geometries command premium compensation, constraining processing throughput.
- Legacy Data Integration Friction:Operators sitting on decades of 2D seismic tape archives face format obsolescence when merging vintage surveys with modern high-density acquisitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seismic Survey Market |
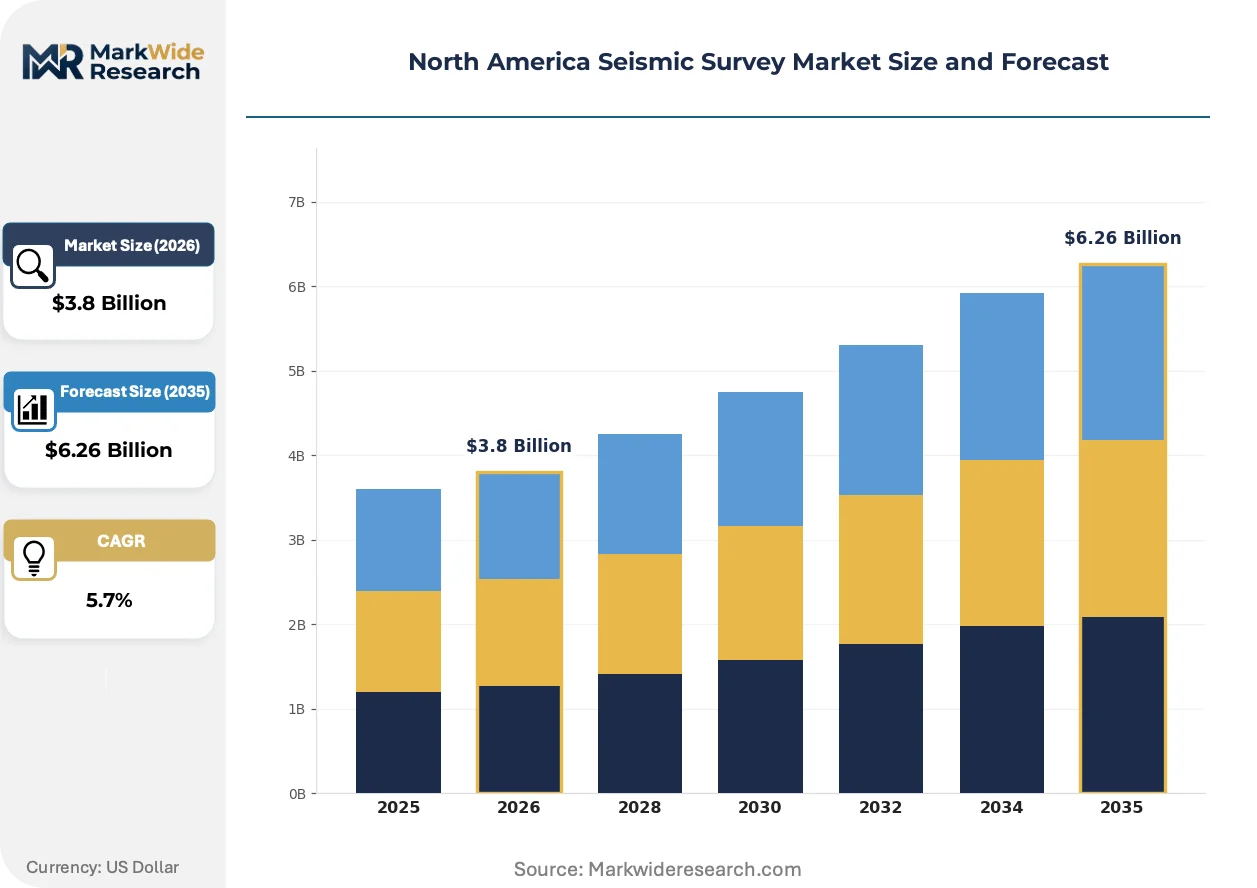
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reflection, Refraction, Tomography, Ground Penetrating Radar Application: Oil & Gas Exploration, Mineral Prospecting, Environmental Studies, Civil Engineering End User: Energy Companies, Mining Corporations, Government Agencies, Construction Firms Service Type: Data Acquisition, Data Processing, Data Interpretation, Consulting |
| Companies Covered | Halliburton Company, Schlumberger Limited, ION Geophysical Corporation, Fugro N.V., CGG SA, SAExploration Holdings Inc., Shearwater GeoServices Holding AS, PGS ASA, TGS-NOPEC Geophysical Company ASA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seismic Survey Market Trends and Innovations
Seismic acquisition technology is fragmenting into specialized, redeployable components that compress mobilization timelines and enable rapid reconfiguration between onshore and offshore environments.
Autonomous nodal systems are modularizing field operations by replacing cabled receiver arrays with self-contained, wirelessly synchronized seabed units. Supermajors operating in the Gulf of Mexico are adopting these systems for repeatability-critical 4D programs, reducing survey redundancy and enabling denser receiver spacing without vessel congestion.
Transport Canada's updated marine mammal protection protocols are tightening acoustic exposure thresholds in the Atlantic offshore planning areas. These standards are extending project lead times by mandating adaptive ramp-up procedures and real-time shutdown protocols, compelling contractors to invest in predictive detection systems and alternative low-impact source technologies.
Integrated acquisition-to-processing contracts are displacing discrete service procurement among Permian Basin independents. Buyers are bundling vibroseis deployment, real-time QC, and fast-track imaging into single-provider agreements that compress decision cycles, with this pattern most visible among Delaware sub-basin operators targeting Wolfcamp and Bone Spring intervals.
North America Seismic Survey Market Segmentation
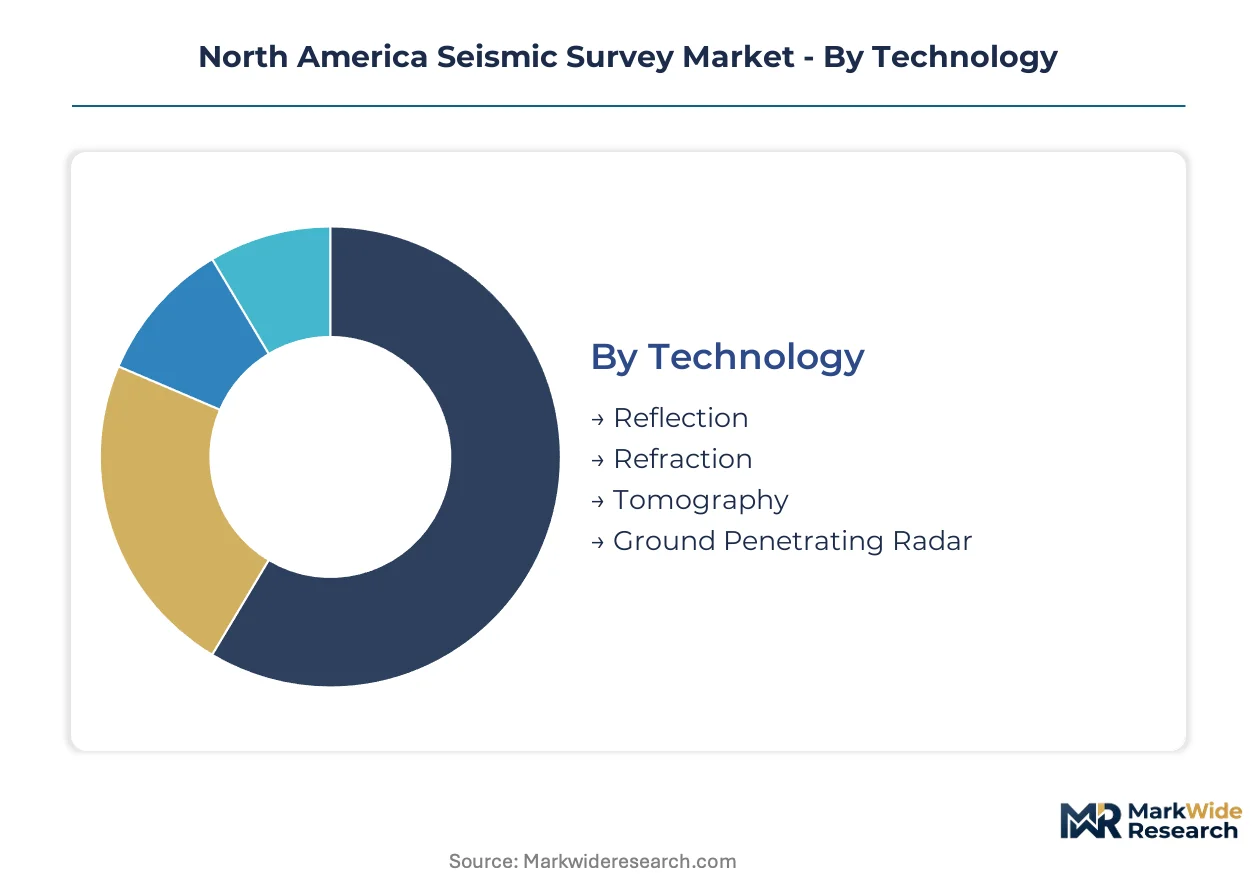
Seismic survey segmentation reveals distinct procurement patterns across technology maturity and integration depth. Buyers select standalone acquisition systems for discrete exploration campaigns, while embedded processing and interpretation services lock into multi-year frameworks.
Technology:
Reflection technology operates as the embedded backbone of hydrocarbon exploration, while emerging modalities function as standalone point solutions for specialized use cases.
- Reflection:Controlled source energy propagation captures subsurface acoustic impedance contrasts through vibroseis trucks, airgun arrays, or ocean-bottom nodes. Permian Basin operators deploy dense 3D reflection grids to de-risk Wolfcamp and Bone Spring drilling decisions, with crew utilization pressing capacity limits across Texas.
- Ground Penetrating Radar:Electromagnetic pulse transmission enables shallow subsurface imaging at centimeter-scale resolution. Infrastructure operators in the US Gulf Coast corridor adopt GPR for pipeline integrity verification and utility mapping, driven by Class VI carbon storage site characterization requirements under EPA frameworks.
- Refraction:First-arrival wave analysis maps bedrock depth and velocity structure for engineering foundation design.
- Tomography:Cross-borehole or surface-to-borehole wavefield inversion resolves complex salt geometries and fractured reservoirs.
Reflection leads volumes today; Ground Penetrating Radar is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive hydrocarbon exploration from lower-budget environmental and engineering deployments.
- Oil & Gas Exploration:3D and 4D seismic programs delineate structural and stratigraphic traps prior to drilling commitment. Supermajors operating in the US Gulf of Mexico anchor demand through integrated acquisition-to-processing contracts that compress decision cycles.
- Civil Engineering:Shallow seismic refraction and MASW surveys characterize soil stiffness and bedrock depth for transportation infrastructure. State departments of transportation in Texas and California drive procurement through bridge foundation and tunnel alignment studies.
- Mineral Prospecting:Deep reflection and electromagnetic methods target base metal and rare earth deposits in the Canadian Shield.
- Environmental Studies:Surface wave methods and electrical resistivity tomography map contaminant plumes and groundwater resources.
Oil & Gas Exploration commands the premium tier; Civil Engineering shows the steepest expansion trajectory as infrastructure stimulus accelerates.
End User:
Customer type determines contract structure, with integrated energy companies favoring multi-year frameworks and government agencies requiring discrete competitive procurement.
- Energy Companies:Supermajors and large independents concentrate buying power through bundled seismic-to-drilling agreements. Delaware sub-basin operators in Texas specifically target stacked pay zone delineation through dense 3D programs.
- Government Agencies:The US Bureau of Ocean Energy Management, Transport Canada, and state geological surveys commission regional data libraries and hazard assessments. BOEM's compressed permitting timelines for marine surveys reshape contractor pre-qualification criteria.
- Mining Corporations:Junior explorers and major producers deploy seismic ahead of drill programs in the Canadian Arctic and US Southwest.
- Construction Firms:Heavy civil contractors procure shallow geophysics for site characterization on transportation and energy infrastructure projects.
Energy Companies dominate contract value; Government Agencies are expanding procurement most quickly through carbon storage and marine spatial planning mandates.
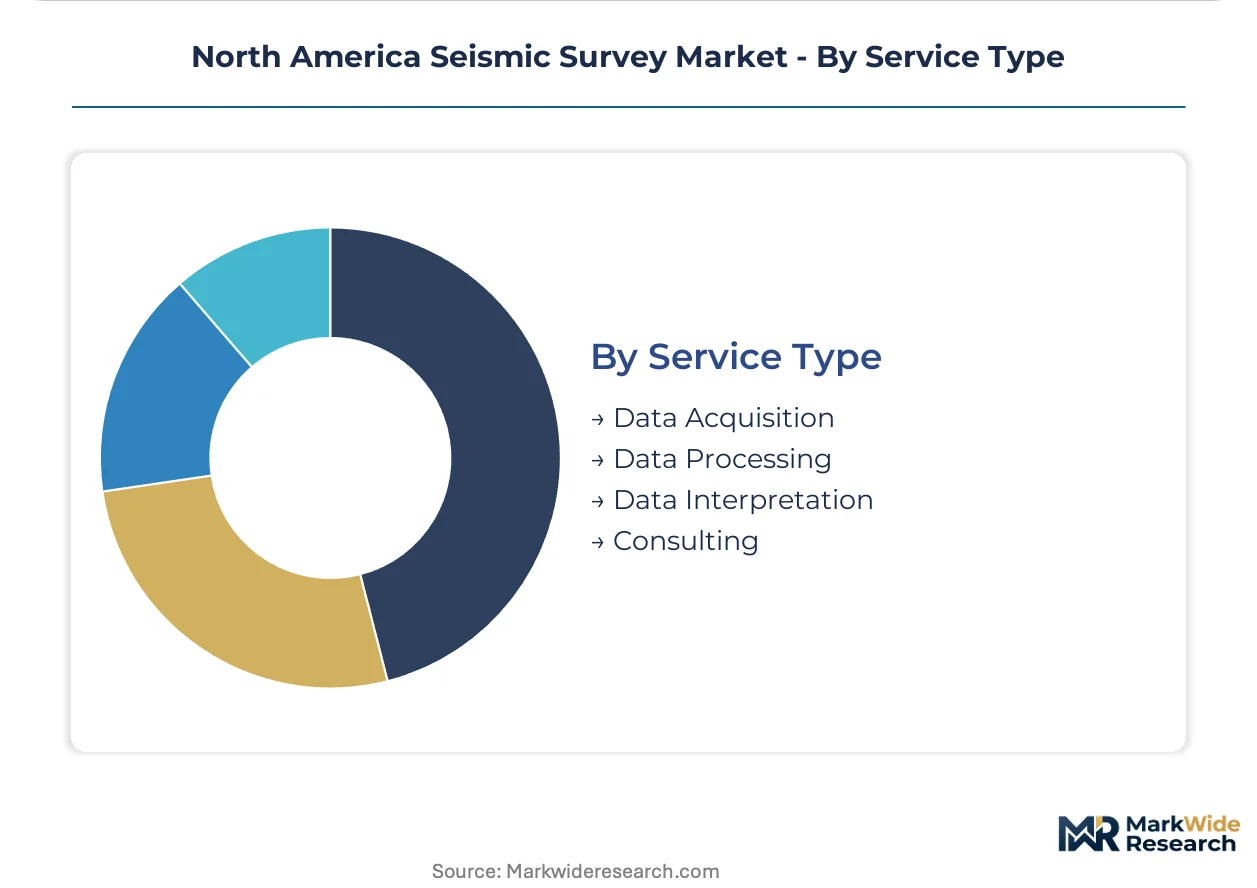
Service Type:
Margin concentration pools in algorithmic processing stages that require specialized computational infrastructure unavailable to most contractors.
- Data Processing:Velocity model building, pre-stack depth migration, and full-waveform inversion demand high-performance computing clusters and specialized geophysicist talent. The velocity model building talent gap constrains throughput, with salt geometry specialists commanding premium compensation in Houston.
- Data Acquisition:Field deployment of vibroseis fleets, ocean-bottom nodes, and marine streamer systems generates revenue through day-rate structures. Crew scarcity in Texas and equipment supply concentration on the Gulf Coast create pricing pressure.
- Data Interpretation:Geoscientists integrate seismic with well logs and production data to generate drillable prospect maps.
- Consulting:Advisory services cover survey design optimization, regulatory permitting strategy, and data licensing.
Data Acquisition leads volumes today; Data Processing captures margin expansion fastest through algorithmic differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates offshore survey demand in the Gulf of Mexico while Canada dominates Arctic frontier exploration. Mexico's energy reform agenda is reshaping contractor presence across its southern basins. Sub-regional specialization is deepening as regulatory divergence creates distinct operational requirements.
United States
Permian Basin operators in Texas deploy dense 3D seismic grids to delineate Wolfcamp and Bone Spring stacked pay zones. The US Bureau of Ocean Energy Management's compressed incidental harassment authorization timelines reshape contractor pre-qualification for Atlantic and Arctic programs. Houston anchors the highest crew utilization rates nationally as vibration control technician scarcity propagates wage pressure through contract pricing.
Canada
Beaufort Sea exploration is resuming as Transport Canada's evolving marine spatial planning opens discretionary survey windows for ice-capable asset holders. The National Energy Board and provincial regulators enforce distinct seismic protocols that extend project lead times through adaptive ramp-up mandates. Calgary-based processing centers concentrate velocity model building talent for complex salt geometry interpretation.
Mexico
The National Hydrocarbons Commission's bid rounds are attracting integrated survey contractors to deepwater blocks in the Gulf of Mexico. Cross-border data sharing agreements with US regulators create compliance complexity for operators spanning both jurisdictions. Ciudad del Carmen serves as the primary logistics hub for marine acquisition campaigns targeting Mexican southern basins.
North America Seismic Survey Market Competitive Landscape
United States-based energy service conglomerates anchor one tier; European and Canadian specialists hold differentiated positions in marine and frontier environments. Market structure concentrates around bundled seismic-to-drilling offerings and proprietary acquisition technologies. Three archetypes dominate: integrated full-service providers, marine technology specialists, and redeployable land system innovators. Competitive moves center on multi-year integrated contract structures and ocean-bottom node technology licensing.
Within the integrated service tier, Halliburton Company and Schlumberger Limited exemplify bundled offering strategies that compress decision cycles for Permian Basin independents. ION Geophysical Corporation occupies a distinct position through redeployable land acquisition systems that address mobilization cost pressures. These three entities represent the competitive spectrum from full-service integration through specialized equipment differentiation.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| ION Geophysical Corporation |
| Fugro N.V. |
| CGG SA |
| SAExploration Holdings Inc. |
| Shearwater GeoServices Holding AS |
| PGS ASA |
| TGS-NOPEC Geophysical Company ASA |
| Others |
Pricing and Supply Chain Analysis
Ocean-bottom node technology maturation simultaneously compresses survey redundancy costs and concentrates manufacturing capacity among Gulf Coast suppliers. This dual effect reshapes contractor bidding strategies and equipment procurement timelines across North American planning areas.
Pricing Analysis
Capacity additions in Texas onshore crews are reshaping price floors for vibroseis deployment contracts. Project-based pricing dominates the market, with differentiation driven by crew specialization tier and mobilization distance from Houston. Pricing pressure stems from vibration control technician scarcity propagating wage inflation through contract structures. Permian Basin independents exhibit highest price sensitivity due to capital discipline mandates, while supermajors anchor premium tier demand through multi-year integrated agreements.
Supply Chain Analysis
Airgun array manufacturing rests on specialty metal fabrication concentrated in the United States Gulf Coast, Norway, and Singapore. Key inputs include high-strength steel forgings, piezoelectric hydrophones, and fiber-optic sensing cables. Single-source vulnerability pervades marine source equipment given limited qualified suppliers. Distribution runs through Houston-based equipment yards serving Gulf of Mexico campaigns and Calgary logistics hubs for Arctic programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Seismic Survey Market functions as a geographic-arbitrage play where BOEM's compressed Atlantic permitting timelines contrast with Transport Canada's extended adaptive ramp-up mandates, creating differential cost structures for contractors with cross-border capabilities.
For Market Incumbents: Deploy proprietary ocean-bottom node licensing to lock in 4D program recurrence. Halliburton Company and Schlumberger Limited should deepen backward integration into permanent reservoir monitoring systems to defend against autonomous nodal disruptors. Anchor position through captive supply of redeployable land acquisition components addressing Permian mobilization cost pressures.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in data processing services creates entry opportunity for algorithmic velocity model building specialists. Target carbon storage site characterization under EPA Class VI frameworks as the most penetrable application segment. Pursue fast-track imaging partnerships with Delaware sub-basin operators seeking compressed decision cycles.
For Investors and Strategic Acquirers: Roll-up economics work for regional processing boutiques because velocity model building talent concentrates in Houston and Calgary with limited replication. Five-to-ten year viability hinges on exposure to recurring 4D revenue streams versus single-shot exploration exposure. Monitor BOEM marine mammal observer mandate evolution as the inflection signal for Atlantic offshore cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Ocean-bottom node IP agreements enable recurring 4D revenue beyond single acquisition contracts. |
| Backward Integration | In-house production of vibration control systems reduces Gulf Coast supplier bottlenecks. |
| Geographic Expansion | Ice-capable asset positioning captures Transport Canada Beaufort Sea discretionary windows. |
| Strategic Partnership | Fast-track imaging alliances with Permian independents compress decision cycles for stacked pay delineation. |
| Green Certification Program | Low-impact source technology investment addresses evolving marine mammal protection thresholds. |
Research Methodology
Bottom-up energy company procurement modeling reconciled against top-down contractor fleet tracking forms the analytical core. Primary interviews with geophysical operations managers, seismic crew supervisors, BOEM permitting officers, and Permian Basin drilling engineers combined with secondary validation from BOEM incidental harassment authorization databases, Transport Canada marine spatial planning filings, and SEC 10-K equipment disclosure segments. Triangulation across supply-side capacity utilization and demand-side contract award patterns ensures cross-verification.
Historical trendline analysis of crew utilization rates and day-rate structures informs projection mechanics across the analysis window. Segmentation dimensions include technology modality, service type tier, application vertical, and regulatory framework cluster. CAGRs derive from equipment deployment trajectories and permitting velocity assumptions. Industry-specific forecast inputs incorporate BOEM authorization timeline revisions and EPA Class VI carbon storage permitting momentum.
Caveats apply where BOEM marine mammal observer mandate intensification or Transport Canada acoustic threshold tightening could materially shift the outlook. Forecasts reflect assumptions around supermajor capital commitment durability and Permian stacked pay delineation economics. A small set of regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Directional Drilling Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Geotechnical Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market