
 Bridge Inspection System Market | 2026-2036
Bridge Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Inspection System Market Analytics
The Federal Highway Administration's National Bridge Inspection Standards revision is recalibrating procurement priorities across state transportation agencies. AECOM leverages its integrated engineering platform to dominate large-scale inspection contracts. Jacobs Engineering anchors its position through specialized structural health monitoring capabilities. Stantec differentiates by combining drone-based data collection with proprietary analytics software.
Bridge inspection systems encompass hardware and software solutions designed to assess structural integrity, material degradation, and load-bearing capacity of bridges through non-destructive testing methods including ultrasonic pulse velocity measurement, ground-penetrating radar, and LiDAR scanning. These systems serve the primary commercial purpose of enabling asset owners to schedule maintenance, prevent catastrophic failures, and extend infrastructure service life while minimizing traffic disruption. Drone technology leads the technology segment due to its ability to access confined spaces and reduce inspector safety risks, while automated inspection types represent the fastest-growing category as agencies seek to reduce subjective variability in condition ratings. Mobile inspection platforms occupy the mature core of the type segment, though margin pools increasingly concentrate in remote monitoring subscriptions that deliver continuous structural data.
The Federal Highway Administration enforces biennial inspection mandates that shape minimum capability requirements for equipment and personnel qualifications, while state-level departments of transportation layer additional protocols that vary by seismic zone and climate exposure. OSHA standards governing confined space entry and work-at-height directly influence the design specifications for robotic and remotely operated inspection platforms. Stakeholders must monitor how evolving federal infrastructure funding mechanisms affect the timing and scale of inspection technology procurement cycles across competing state priorities.
Market Dynamics
The Federal Highway Administration's National Bridge Inspection Standards revision is compressing replacement cycles for state transportation agencies, forcing simultaneous upgrades to equipment fleets and inspector training protocols.
Growth Catalysts
- Biennial inspection mandates:Federal Highway Administration requirements create recurring procurement demand for ultrasonic pulse velocity measurement equipment and LiDAR scanning platforms across state departments of transportation.
- California bridge inventory scale:The state's twenty-thousand-plus structure count drives concentrated demand for automated inspection platforms that reduce inspector exposure to seismic zone hazards.
- Drone technology maturation:FAA Part 107 commercial remote pilot certification expansion enables broader deployment of unmanned aerial systems for confined space access and underside deck inspection.
Market Restraints
- LiDAR sensor supply concentration:Component sourcing depends on a limited manufacturing base concentrated in specific Asian production clusters, creating vulnerability to export control disruptions.
- Ground-penetrating radar technical limitations:Signal attenuation in high-moisture concrete environments restricts reliable subsurface defect detection in coastal and northern climate zones.
- OSHA work-at-height compliance costs:Confined space entry standards impose equipment certification and personnel training burdens that inflate total cost of ownership for robotic platforms.
Strategic Opportunities
- Texas bridge inventory modernization:The state's twenty-thousand-plus structure count and hurricane exposure create demand for continuous remote monitoring subscriptions that deliver real-time structural data.
- AI-driven defect classification:Machine vision algorithms trained on historical inspection imagery are converging with edge computing hardware to enable autonomous condition rating generation.
- Infrastructure Investment and Jobs Act funding windows:Federal appropriation timing creates predictable procurement surges that vendors can anticipate through state transportation agency budget cycle alignment.
Industry Challenges
- Structural engineer certification bottlenecks:Professional engineer licensure requirements for final condition rating approval create talent scarcity that limits inspection team scaling during peak demand periods.
- Legacy data format incompatibility:Proprietary file structures from incumbent mobile inspection platforms obstruct seamless migration to cloud-based analytics environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Inspection System Market |
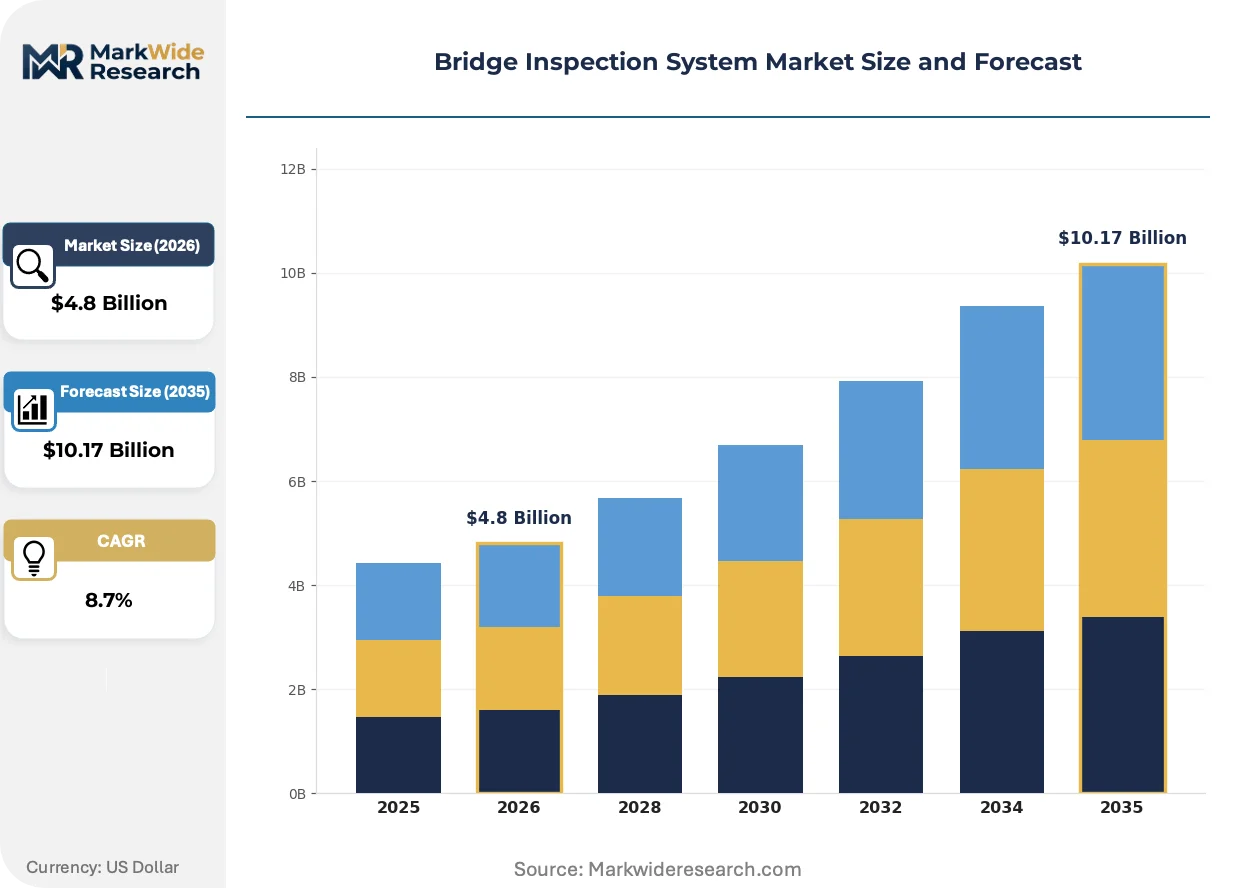
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drone, Ultrasonic Testing, Visual Inspection, RFID Type: Mobile Inspection, Automated Inspection, Manual Inspection, Remote Monitoring End User: Government, Construction Firms, Maintenance Providers, Engineering Consultants Service Type: Analysis, Repair, Maintenance, Consulting |
| Companies Covered | AECOM, Jacobs Engineering, Stantec, WSP Global, Collins Engineers, CEC Corporation, KCI Technologies, Mistras Group, Ayres Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Inspection System Market Evolving Landscape
Inspection technology is shifting from episodic manual assessment toward continuous automated monitoring, with data architecture decisions now preceding hardware procurement in state transportation agency planning cycles.
Computer vision algorithms trained on crack propagation patterns are converging with thermal imaging sensors to detect subsurface delamination before surface manifestation. State departments of transportation in seismic zones are piloting these integrated platforms for priority structure monitoring. The structural consequence is compression of inspection intervals from twenty-four months to continuous assessment for critical span elements.
The Federal Highway Administration's pending revision to fracture-critical member inspection protocols is mandating hands-on access requirements that drone platforms cannot satisfy. This regulatory friction is driving investment in robotic crawlers and magnetic adhesion systems for steel superstructure examination. Bridge owners in Texas and California are responding by dual-sourcing aerial and ground-based platforms to maintain compliance flexibility.
Asset owners are unbundling inspection data analytics from hardware procurement, contracting specialized software vendors to process imagery collected by in-house drone fleets. This procurement model shift displaces traditional turnkey system vendors in favor of modular component suppliers. The pattern is most visible in New York, where the metropolitan transportation authority operates one of the largest internal UAV programs among state agencies.
Bridge Inspection System Market Segmentation
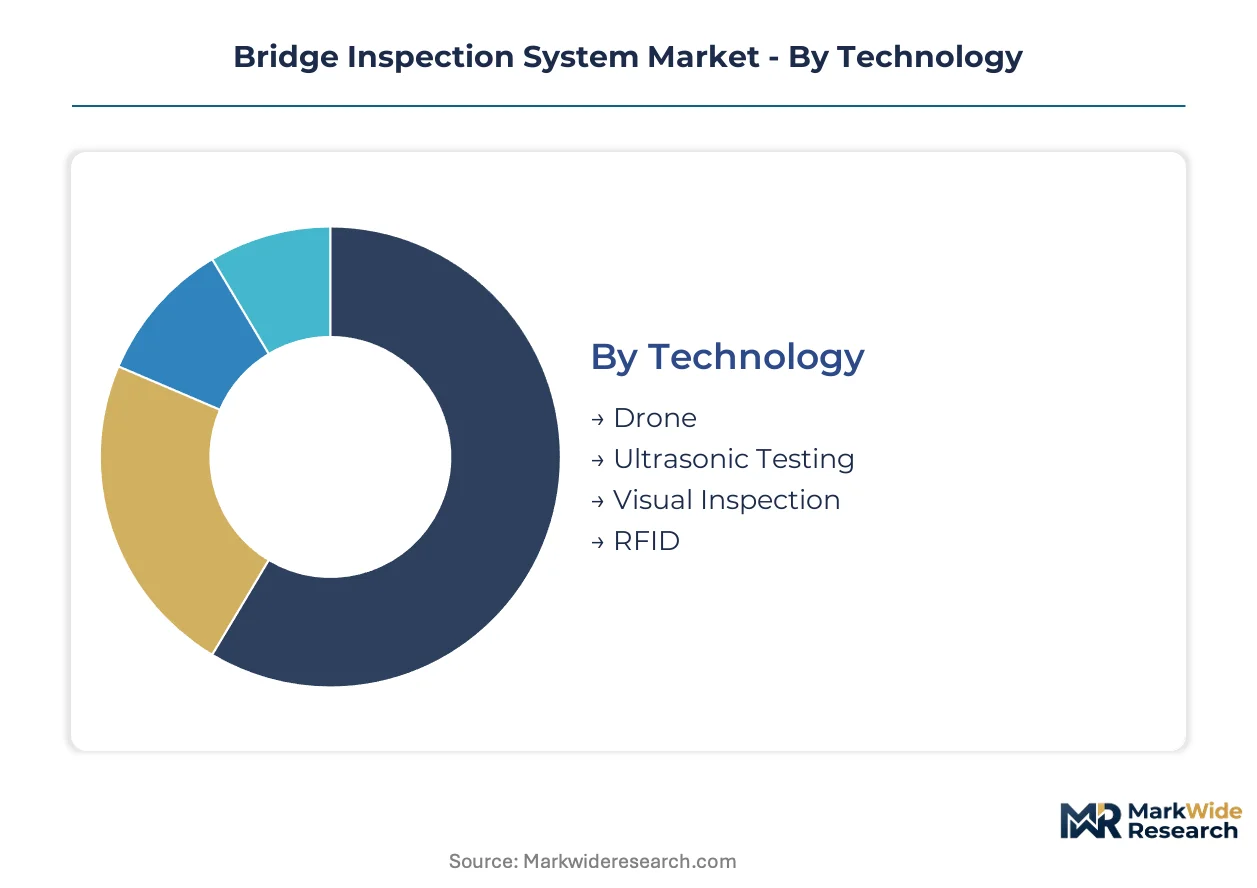
Bridge inspection procurement cycles now hinge on technology selection that determines inspector safety protocols and data continuity capabilities. Federal mandate compression forces agencies to evaluate segments through replacement-cost and interoperability lenses rather than standalone equipment specifications.
Technology:
Equipment upgrade waves concentrate where legacy platforms face FAA certification expiration or sensor obsolescence.
- Drone:Unmanned aerial systems carry high-resolution cameras and LiDAR payloads for underside deck access without traffic closure. California and Texas transportation departments deploy these for seismic zone structures where human access risks exceed tolerance thresholds.
- Ultrasonic Testing:Pulse velocity measurement detects internal voids and delamination in concrete members through stress wave propagation analysis. Northeastern state agencies favor this for freeze-thaw damage assessment in coastal bridge inventories.
- Visual Inspection:Traditional optical assessment remains mandatory for fracture-critical member hands-on verification under pending Federal Highway Administration protocol revisions.
- RFID:Embedded radio-frequency identification tags enable automated asset tracking and inspection history retrieval for large inventory management.
Drone platforms sit at the top of the volume ranking, with ultrasonic testing climbing the fastest as concrete deterioration analytics mature.
Type:
Agency procurement budgets now split between capital equipment and recurring subscription services, reshaping vendor revenue models.
- Automated Inspection:Machine vision and edge computing hardware generate condition ratings without human interpretation variability. New York's metropolitan transportation authority pilots these for high-traffic span priority assessment.
- Remote Monitoring:Continuous sensor networks transmit structural response data through cellular or satellite uplinks for real-time anomaly detection. Hurricane-exposed Gulf Coast bridges drive subscription demand here.
- Mobile Inspection:Truck-mounted platforms with articulated booms and ground-penetrating radar arrays serve as the mature workhorse for routine biennial surveys.
- Manual Inspection:Rope-access and under-bridge inspection vehicles retain regulatory necessity for hands-on steel member examination.
Mobile inspection maintains the widest installed base, though remote monitoring subscriptions are gaining share fastest as agencies shift toward predictive maintenance models.
End User:
Contractor specialization deepens as state agencies unbundle data analytics from field collection.
- Government:State departments of transportation and federal highway administrations set procurement standards and mandate minimum capability tiers through inspection quality assurance programs.
- Engineering Consultants:Professional engineer licensure requirements position these firms as mandatory final condition rating approvers, creating talent-scaled service bottlenecks.
- Maintenance Providers:Specialized contractors execute routine cleaning, debris removal, and minor repair work that precedes formal structural assessment.
- Construction Firms:Quality control divisions deploy inspection systems for new bridge acceptance testing and warranty period monitoring.
Government entities dominate absolute spending, with engineering consultants expanding most quickly as agencies outsource rating generation.
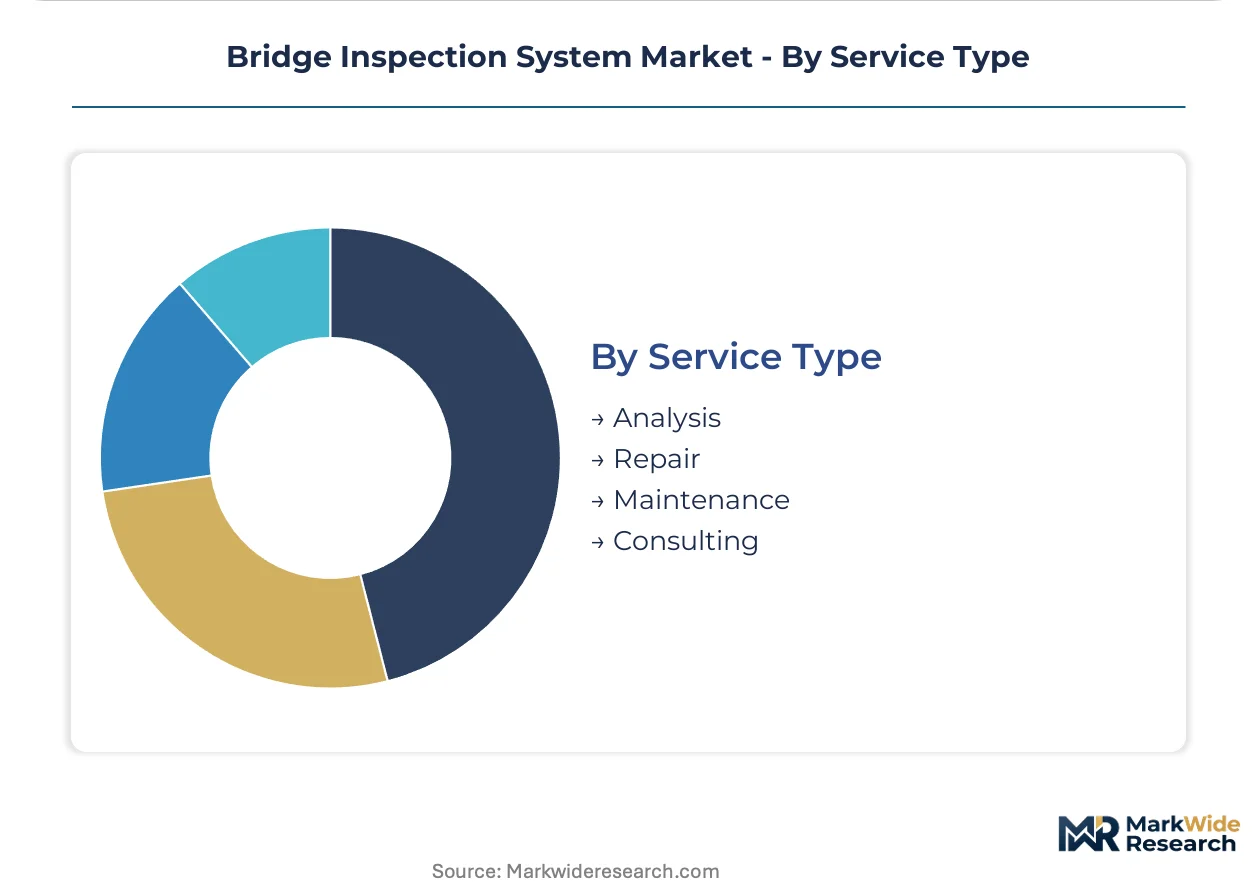
Service Type:
Vendor margins concentrate in advisory layers above commodity hardware deployment.
- Analysis:Software platforms process inspection imagery and sensor data to classify defect severity and predict remaining service life using historical degradation models.
- Consulting:Structural engineers interpret inspection findings and recommend repair prioritization schedules aligned with funding cycle constraints.
- Maintenance:Routine protective system upkeep including joint sealing, drainage clearing, and corrosion inhibitor reapplication.
- Repair:Structural intervention execution including concrete patching, steel member replacement, and bearing rehabilitation.
Analysis services command the highest margin expansion, with repair work scaling most directly with infrastructure funding authorization timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge inspection technology originated in the United States following the 1967 Silver Bridge collapse, which catalyzed federal mandates that spread inspection protocols worldwide. The industry now concentrates where aging infrastructure inventories intersect with regulatory enforcement capacity.
United States
The Federal Highway Administration's National Bridge Inventory tracks over six hundred thousand structures, creating sustained equipment demand across state transportation departments. California's twenty-thousand-plus bridge count drives automated platform adoption to reduce inspector seismic exposure. Texas transportation officials deploy remote monitoring subscriptions for hurricane-vulnerable Gulf Coast spans.
Germany
The country's extensive autobahn bridge network and stringent structural maintenance regulations sustain precision inspection equipment demand. Federal Ministry of Transport guidelines mandate detailed condition documentation that favors ultrasonic testing and ground-penetrating radar deployment. Engineering consultancies in Bavaria and North Rhine-Westphalia anchor specialized inspection service provision.
Japan
Seismic resilience requirements and aging highway infrastructure sustain advanced structural health monitoring demand. Ministry of Land, Infrastructure, Transport and Tourism protocols require rigorous earthquake damage assessment capabilities. Tokyo and Osaka metropolitan authorities pilot AI-driven defect classification for high-traffic elevated expressways.
China
Rapid highway network expansion and mountainous terrain bridge construction create inspection technology procurement scale. Ministry of Transport standards increasingly incorporate automated assessment methods for concrete superstructure evaluation. Yangtze River Delta provincial authorities deploy drone fleets for inaccessible valley span examination.
India
National highway bridge inventory expansion and climate-induced deterioration accelerate non-destructive testing equipment adoption. Ministry of Road Transport and Highways quality assurance programs standardize inspection protocol implementation. Maharashtra and Karnataka state public works departments contract specialized consultants for major river crossing assessment.
Bridge Inspection System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data analytics specialization and integrated engineering platform depth. The vendor base separates into three tiers: multinational engineering conglomerates with bundled inspection services, specialized structural health monitoring technology providers, and regional equipment fabricators serving single-state procurement cycles. Two strategic archetypes dominate: integrated platform vendors capturing turnkey contracts and modular component suppliers unbundling hardware from software analytics. Competitive moves concentrate on strategic partnerships for AI algorithm development and geographic expansion through state transportation agency relationship cultivation.
Within the integrated engineering tier, AECOM and Jacobs Engineering exemplify platform-scale positioning that spans inspection execution through structural rating approval. Stantec occupies a specialized position combining aerial data collection with proprietary analytics development. WSP Global anchors multinational infrastructure consultancy presence across North American and European bridge markets. These named entities represent archetype diversity rather than exhaustive market coverage.
| Leading Market Players |
|---|
| AECOM |
| Jacobs Engineering |
| Stantec |
| WSP Global |
| Collins Engineers |
| CEC Corporation |
| KCI Technologies |
| Mistras Group |
| Ayres Associates |
| Others |
Value Network & Pricing Analysis
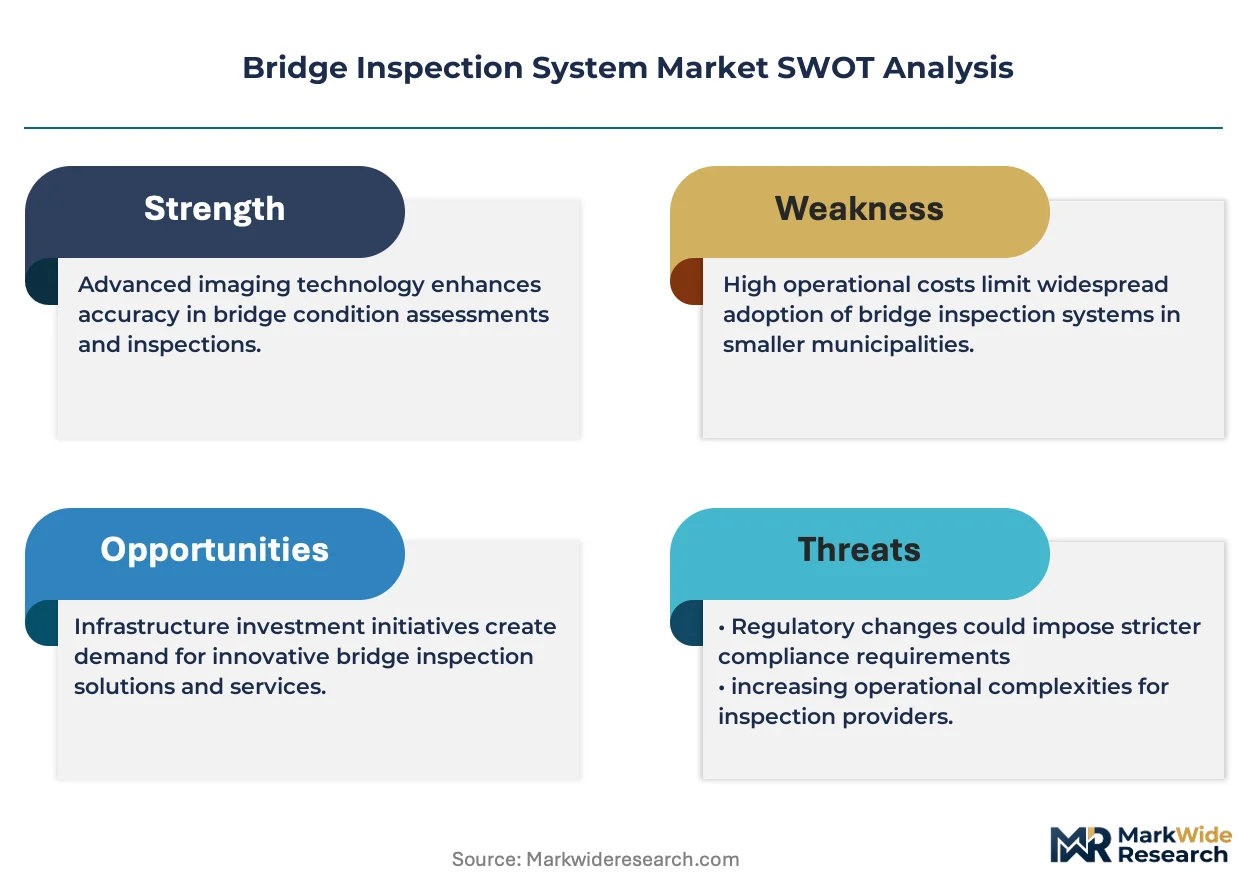
Private-equity-rolled-up engineering specialists now control dominant inspection platform vendors, concentrating pricing power with firms that bundle hardware procurement, software subscriptions, and engineer-staffed rating services into multi-year state transportation agency contracts. This ownership pattern tightens margin discipline across equipment tiers while amplifying procurement leverage against fragmented LiDAR sensor suppliers.
Pricing Analysis
Project-based contracting with embedded subscription renewals anchors revenue capture, where automated inspection platforms command premium positioning against mobile inspection workhorses. Price differentiation rests on FAA Part 107 certification tier and proprietary analytics depth rather than hardware specifications alone. Cost compression in economy-tier drone fleets is intensifying because Asian component suppliers face export licensing friction. State departments of transportation exhibit acute price sensitivity on initial capital outlays, while engineering consultants absorb premium pricing for continuous remote monitoring subscriptions that reduce liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese LiDAR sensor foundries and South Korean ultrasonic transducer manufacturers, where production concentration creates chokepoint exposure for North American inspection platform assemblers. Component sourcing draws from Japanese precision optics specialists and German ground-penetrating radar module producers, with final integration anchored in U.S. Gulf Coast and Midwest fabrication facilities. Tariff exposure on Chinese carbon-fiber airframes and battery cells elevates landed cost volatility for drone platform vendors. Distribution runs through authorized dealer networks serving state procurement offices, with direct OEM relationships penetrating large metropolitan transportation authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Federal Highway Administration mandate compression is forcing procurement toward premium-tier automated platforms with certified AI defect classification and continuous monitoring capabilities.
For Market Incumbents: Anticipate margin compression from modular software vendors unbundling analytics from hardware, and respond by deepening vertical integration into LiDAR sensor calibration facilities and in-house FAA certification training academies. Lock in multi-year remote monitoring subscriptions with Texas and California transportation departments before federal infrastructure funding windows close. Certification investment in emerging fracture-critical member robotic access systems will defend positioning against specialized crawler entrants. For New Entrants and Emerging Players: The premium-to-economy price-point gap in drone-based deck inspection systems offers entry room for mid-tier vendors with FAA Part 107 waiver expertise and cloud-native analytics architectures. Target hurricane-exposed Gulf Coast counties where continuous monitoring penetration remains underdeveloped and subscription pricing discipline is loose. A go-to-market angle through county-level emergency management offices bypasses entrenched state transportation agency vendor lists. For Investors and Strategic Acquirers: Engineering conglomerates with integrated infrastructure platforms are the most active acquirer in this space, seeking bolt-on structural health monitoring capabilities to deepen state agency relationships. Long-term viability favors vendors with recurring revenue exceeding sixty percent of total mix and proprietary AI training datasets spanning multiple climate degradation patterns. Watch for Federal Highway Administration fracture-critical member protocol finalization as the signal for robotic crawler demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development Partnership | Machine vision training with California DOT historical crack imagery accelerates autonomous rating accuracy. |
| Remote Monitoring Subscription Expansion | Cellular-enabled sensor networks capture Texas hurricane-vulnerable span contracts from episodic inspection vendors. |
| Robotic Crawler Platform Launch | Magnetic adhesion systems satisfy pending FHWA hands-on steel member access mandates. |
| LiDAR Sensor Backward Integration | Captive supply of Taiwanese-sourced modules insulates against export control disruption. |
| State Agency Relationship Cultivation | Direct New York MTA engagement displaces turnkey vendors through unbundled analytics procurement. |
Research Methodology
Multiple input streams — primary interviews with state bridge inspection program managers, FAA certification specialists, and structural health monitoring engineering directors, alongside secondary validation through FHWA National Bridge Inventory databases, state transportation agency budget appropriations records, and SEC filings from publicly traded infrastructure conglomerates — were reconciled through bottom-up equipment shipment tracking and top-down procurement budget analysis.
Data-stream reconciliation across the projection horizon employed segmentation modeling across technology type, inspection platform category, end-user organization scale, and regional regulatory enforcement intensity. CAGRs were derived from equipment replacement cycle compression rates and subscription service penetration curves, with specific inputs including biennial inspection mandate compliance deadlines and Infrastructure Investment and Jobs Act obligation timelines.
Caveats apply where FHWA protocol revision timing, LiDAR export control expansion, or state budget sequestration could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Engineering Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Asia-Pacific Seismic Services Market